
 Global Carbon Fiber Reinforced Plastic Market | 2026-2036
Global Carbon Fiber Reinforced Plastic Market Size, Share, and Industry Trends Forecast 2026-2036
Global Carbon Fiber Reinforced Plastic Market Foresight
AS9100 aerospace certification is rotating the competitive landscape toward suppliers with proven quality management systems. Toray Industries leverages its PAN precursor supply chain to sustain leadership in aerospace-grade carbon fiber. Hexcel Corporation anchors North American defense and commercial aviation programs through long-term OEM contracts. Mitsubishi Chemical Group differentiates via integrated operations spanning precursor through prepreg manufacturing.
Carbon fiber reinforced plastic combines continuous carbon fiber reinforcement with thermoset or thermoplastic matrices, typically achieving tensile strengths exceeding 1,500 MPa and modulus values above 150 GPa, to deliver stiffness-to-weight ratios superior to aluminum alloys. Carbon fiber prepreg dominates commercial aerospace fabrication due to controlled resin content and handling characteristics that suit autoclave processing. Resin transfer molding is gaining traction in wind turbine blade production where part scale exceeds autoclave capacity. Aerospace components command premium positioning, while sporting goods represents a mature volume segment with compressed margins.
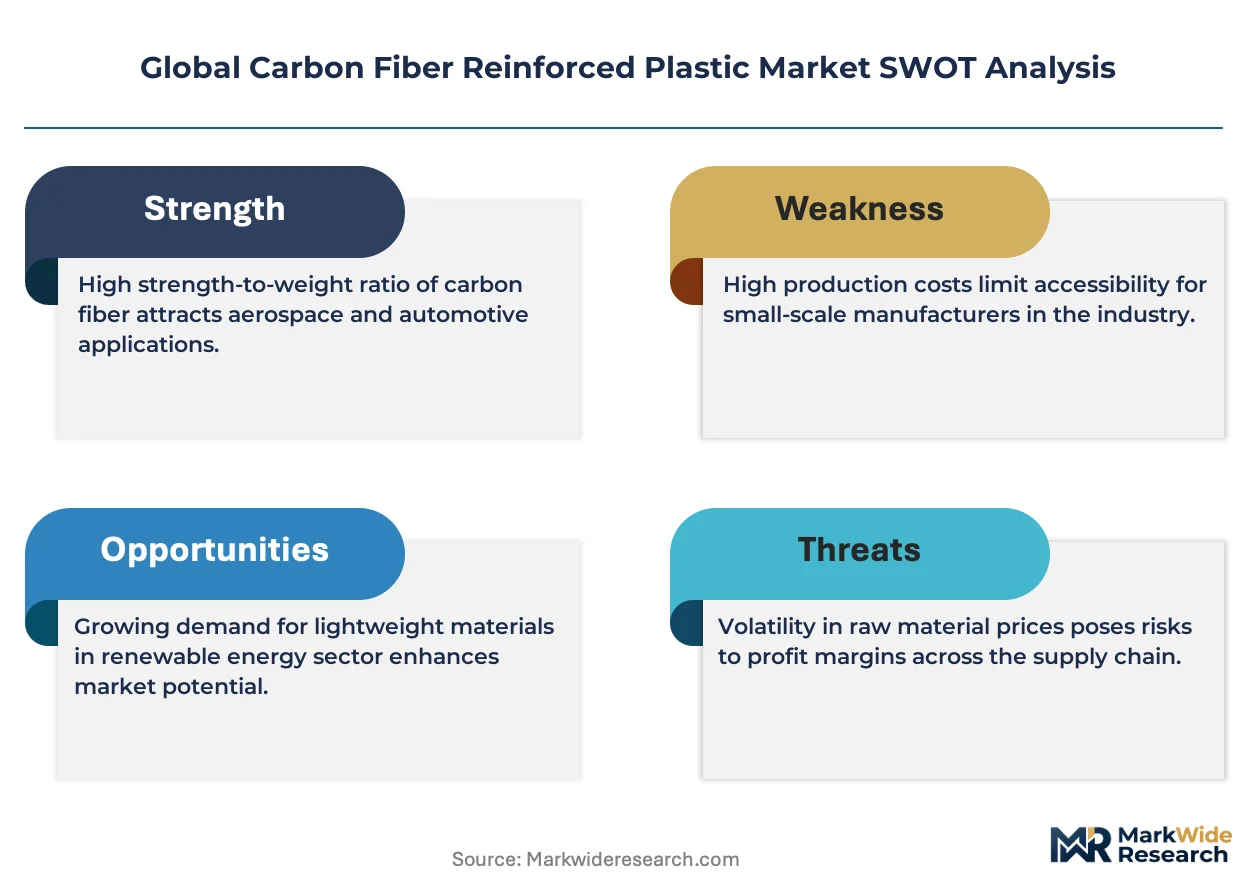
FAA airworthiness standards, EASA certification requirements, and REACH chemical regulations collectively shape material qualification timelines and supplier eligibility across major aviation markets. OEMs now demand full supply chain traceability from precursor to finished component, elevating compliance costs for tier-two material converters. Stakeholders must monitor evolving sustainability disclosure rules under the EU CSRD, as embodied carbon reporting becomes a procurement criterion for European aircraft manufacturers and energy equipment makers.
Market Dynamics
Aerospace OEMs are consolidating supplier bases around AS9100-certified producers capable of full supply chain traceability, compressing qualification timelines and elevating barriers for tier-two converters.
Growth Catalysts
- EU Green Deal decarbonization mandates:Aircraft and wind turbine manufacturers face binding embodied carbon targets that favor lightweight CFRP over aluminum in fuselage and blade applications.
- Thermoplastic prepreg maturation:Out-of-autoclave processing cuts cycle times by half for commercial aviation programs, accelerating adoption in narrowbody production lines.
- Japan's integrated precursor-to-prepreg infrastructure:Domestic supply chain density enables rapid qualification of aerospace-grade materials for defense and space programs.
Market Restraints
- Acrylonitrile price volatility:PAN precursor production consumes petroleum-derived feedstocks exposed to energy market fluctuations, compressing margins for non-integrated suppliers.
- Autoclave capacity scarcity:Large-diameter wind turbine blades exceed standard autoclave dimensions, forcing reliance on slower resin transfer molding with higher scrap rates.
- REACH chemical registration burdens:ECHA compliance timelines for novel epoxy formulations extend material qualification by 18-24 months, freezing innovation pipelines.
Strategic Opportunities
- India's defense localization push:Indigenization requirements under the PLI scheme create captive demand for domestic CFRP fabrication in unmanned aerial systems and helicopter airframes.
- Hydrogen pressure vessel adoption:Type IV composite tanks for fuel cell vehicles represent an emerging volume segment outside traditional aerospace and wind energy.
- EU CSRD sustainability disclosure:Mandatory embodied carbon reporting positions suppliers with verified lifecycle data to capture premium procurement contracts from Airbus and Vestas.
Industry Challenges
- Certified composite technician scarcity:FAA repair station and EASA Part 145 approvals require specialized laminator training that outpaces vocational program output in Germany and the United States.
- Multi-tier traceability integration:OEM mandates for precursor-to-component documentation force tier-two converters to upgrade ERP systems and audit sub-supplier networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Carbon Fiber Reinforced Plastic Market |
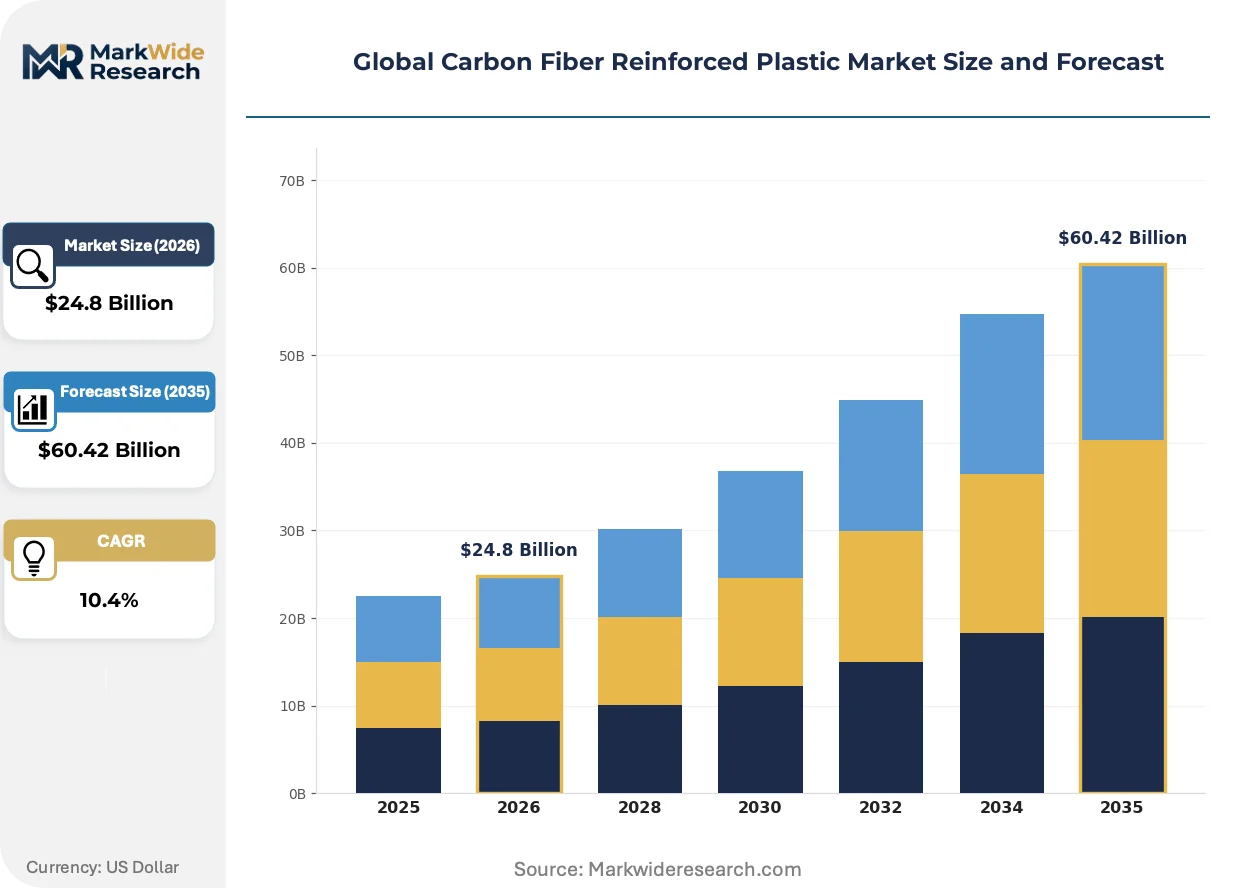
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $60.42 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Fiber Prepreg, Carbon Fiber Tow, Carbon Fiber Fabric, Carbon Fiber Tape, Carbon Fiber Mat Technology: Resin Transfer Molding, Autoclave Molding, Compression Molding, Pultrusion, Filament Winding Application: Aerospace Components, Sporting Goods, Wind Turbine Blades, Marine Equipment, Consumer Electronics End User: Aircraft Manufacturers, Sports Equipment Producers, Energy Equipment Makers, Shipbuilders, Electronics Manufacturers |
| Companies Covered | Mitsubishi Chemical Group, Solvay, Toray Industries, Formosa Plastics Corporation, DowAksa Advanced Composites, Hexcel Corporation, Teijin Limited, Gurit Services AG, SGL Carbon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Carbon Fiber Reinforced Plastic Market Shifts & Advancements
Material science and processing economics are diverging along thermoset-thermoplastic lines, while regulatory disclosure requirements and buyer consolidation reshape competitive access.
Thermoplastic carbon fiber reinforced plastic is bifurcating the aerospace fabrication landscape. PEEK and PPS matrices enable welding and thermoforming, eliminating autoclave bottlenecks. Boeing and Airbus suppliers are piloting these materials for secondary structures and interior components. The technology is compressing capital requirements for new entrants while forcing incumbent thermoset specialists to defend position through qualification depth.
EASA certification harmonization with FAA airworthiness standards is streamlining dual-approval pathways for European suppliers. The convergence reduces redundant testing for composite primary structures. German and French material producers gain most from shortened time-to-market for international aviation programs. The alignment pressures national regulators in Japan and China to accelerate bilateral recognition agreements.
Long-term offtake contracting is displacing spot procurement in wind energy blade manufacturing. Vestas and Siemens Gamesa now lock resin and fiber supply three to five years forward, mirroring aerospace purchasing patterns. Tier-one blade producers in Denmark and Spain consolidate converter relationships to secure volume commitments. The shift squeezes independent prepreg distributors unable to guarantee supply continuity.
Global Carbon Fiber Reinforced Plastic Market Segmentation
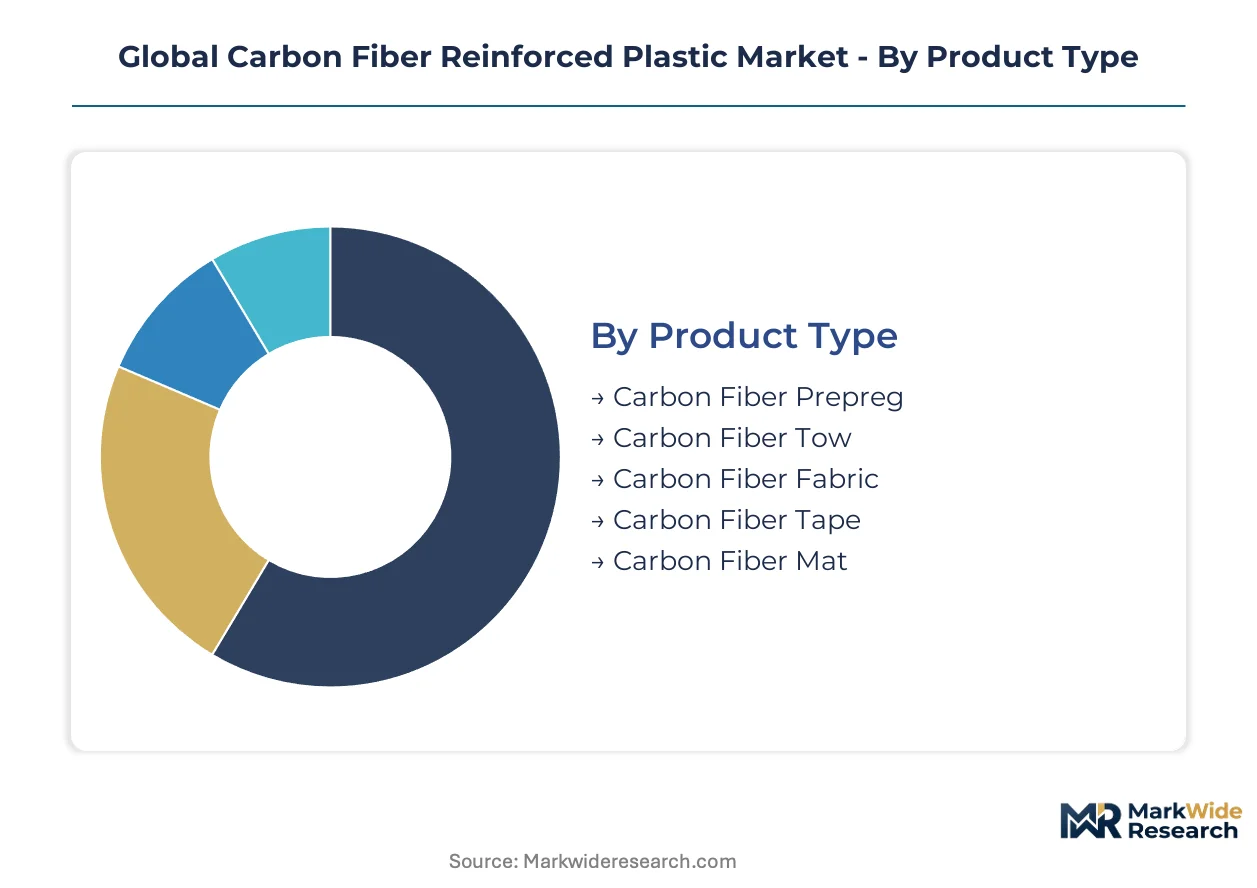
CFRP segmentation reveals how material form and processing technology dictate channel economics. Aerospace programs source through qualified prepreg distributors, while wind energy procures directly from integrated converters. Sporting goods flows through wholesale distributors with compressed lead times.
Product Type:
Prepreg and tow products move through distinct channel structures. Aerospace-grade prepreg routes through AS9100-certified distributors with frozen qualification protocols. Industrial-grade tow and fabric sell direct to tier-one converters with volume-based contracting.
- Carbon Fiber Prepreg:Continuous fiber sheets pre-impregnated with thermoset resin at controlled fiber volume fractions between 58% and 65%. Airbus and Boeing suppliers in Germany and Japan lock supply through three-year offtake agreements with resin-content specifications. REACH chemical registration for novel epoxy formulations extends European qualification timelines.
- Carbon Fiber Tow:Untwisted bundles of 3,000 to 50,000 filaments serving as feedstock for filament winding and pultrusion operations. Wind turbine blade producers in Denmark source 50K tow directly from precursor-integrated manufacturers to bypass margin-stacking.
- Carbon Fiber Fabric:Woven textile forms for hand lay-up and resin infusion processes in marine and industrial applications.
- Carbon Fiber Tape:Unidirectional narrow-width rolls optimized for automated fiber placement in aerospace structural components.
- Carbon Fiber Mat:Chopped or continuous strand mats for compression molding in automotive and consumer goods.
By volume, carbon fiber tow leads. By growth pace, carbon fiber prepreg is expanding most quickly.
Technology:
Processing method selection hinges on part scale, production rate, and capital intensity. Aerospace structural components demand autoclave consolidation for void-free laminates. Wind energy blades exceed autoclave dimensions, forcing resin transfer molding adoption with higher scrap tolerance.
- Autoclave Molding:Pressure-thermal consolidation at 6-10 bar and 180°C curing cycles delivering aerospace-grade void content below 1%. Boeing 787 fuselage sections in the United States require 8-meter diameter autoclaves with nitrogen inerting systems. Capacity scarcity in Germany and Japan elevates scheduling premiums for qualified facilities.
- Resin Transfer Molding:Closed-mold infusion of catalyzed resin into preplaced fiber preforms enabling wind turbine blade production beyond 100 meters length. Vestas suppliers in Denmark accept 3-5% void content trade-offs against autoclave scale limitations. Cycle times run 24-48 hours versus 4-6 hours for aerospace autoclave cycles.
- Resin Transfer Molding:Closed-mold infusion for large-scale parts where autoclave capacity is unavailable.
- Compression Molding:Matched-die forming of thermoplastic or thermoset charges for automotive and industrial components.
- Pultrusion:Continuous pulling of resin-impregnated fiber through heated dies for structural profiles and rebar.
- Filament Winding:Automated fiber deposition on rotating mandrels for pressure vessels and cylindrical structures.
Autoclave molding commands premium pricing. Resin transfer molding is gaining share fastest in energy applications.
Application:
Application segmentation tracks end-use value capture and certification burden. Aerospace components carry 10-15 year qualification horizons with full traceability mandates. Sporting goods operates on seasonal procurement cycles with minimal regulatory overlay.
- Aerospace Components:Primary and secondary airframe structures, control surfaces, and interior components subject to FAA and EASA airworthiness certification. Airbus A350 XWB wings in France incorporate 53% composite content by weight. Each material batch requires precursor-to-component documentation spanning carbonization temperature records and resin gel times.
- Wind Turbine Blades:Glass-carbon hybrid spar caps and full-carbon root sections for multi-megawatt turbines. Siemens Gamesa blade facilities in Spain source 80-meter-plus spar caps through long-term resin and fiber contracts. EU Green Deal embodied carbon reporting now influences material selection against aluminum alternatives.
- Sporting Goods:Bicycles, golf clubs, and hockey sticks representing mature volume demand with compressed margin structures.
- Marine Equipment:Hull structures and mast components for racing and luxury vessels with moderate certification requirements.
- Consumer Electronics:Laptop chassis and wearable device housings prioritizing aesthetic surface finish over structural loading.
Aerospace components generate highest revenue per kilogram. Wind turbine blades are climbing the fastest on absolute volume expansion.
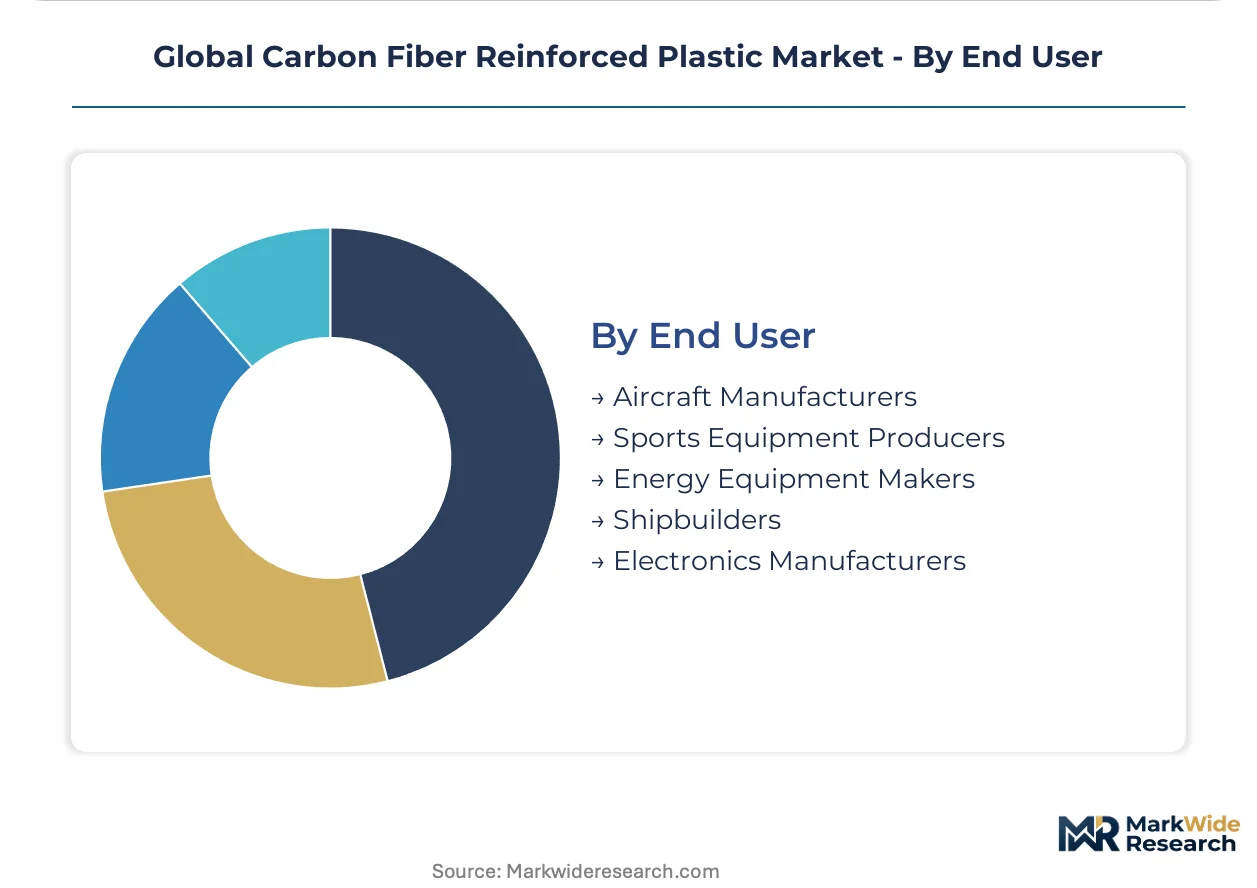
End User:
End user categories reflect procurement sophistication and supply chain power. Aircraft manufacturers enforce vendor reduction programs with single-source qualification for critical structures. Sports equipment producers maintain multi-source flexibility for commodity grades.
- Aircraft Manufacturers:Boeing, Airbus, and defense primes with dedicated composite engineering teams and proprietary material specifications. Lockheed Martin F-35 program in the United States mandates AS9100 and NADCAP accreditation for all composite suppliers. OEM technical audits occur annually with corrective action timelines.
- Energy Equipment Makers:Vestas, Siemens Gamesa, and GE Renewable Energy with blade manufacturing joint ventures in Denmark, Spain, and India. PLI scheme localization requirements in India are forcing technology transfer agreements for domestic CFRP fabrication capacity.
- Sports Equipment Producers:Decathlon, Callaway, and Specialized with seasonal forecasting and rapid product refresh cycles.
- Shipbuilders:Lürssen and Feadship for superyacht composite superstructures with Lloyd's Register classification.
- Electronics Manufacturers:Dell, Apple, and Samsung suppliers with surface-quality and electromagnetic shielding specifications.
Aircraft manufacturers concentrate purchasing power most intensely. Energy equipment makers are scaling procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal decarbonization mandates and defense localization programs are redirecting composite demand toward integrated supply chains in Germany, Japan, and the United States. Aircraft OEMs and wind turbine manufacturers now prioritize suppliers with verified embodied carbon data and full precursor-to-component traceability.
United States
Boeing 787 and Lockheed Martin F-35 programs sustain aerospace-grade CFRP consumption through AS9100-certified supplier networks. FAA airworthiness standards enforce multi-tier documentation from carbonization to finished component. Wichita, Kansas and Charleston, South Carolina host concentrated autoclave capacity for commercial and defense airframe fabrication.
Germany
Airbus A350 XWB wing production in Hamburg and Bremen drives premium prepreg demand with three-year offtake contracting. EASA certification alignment with FAA standards shortens dual-approval pathways for German material producers. Munich and Stuttgart industrial clusters specialize in thermoplastic matrix development for out-of-autoclave processing.
Japan
Integrated precursor-to-prepreg infrastructure supports rapid qualification for defense and space programs under METI industrial policy. Toray Industries and Teijin Limited anchor domestic supply chain density in Tokyo and Osaka metropolitan areas. JIS standards harmonization with ISO aerospace specifications accelerates material export approvals.
China
Dual carbon goals under MEE oversight propel wind turbine blade manufacturing beyond 100-meter lengths, forcing resin transfer molding adoption. COMAC C919 narrowbody program develops indigenous CFRP supply chains in Shanghai and Xi'an aerospace clusters. GB standards for composite pressure vessels create parallel certification tracks for hydrogen storage applications.
India
PLI scheme localization requirements generate captive demand for domestic CFRP fabrication in unmanned aerial systems and helicopter airframes. Indigenization mandates force technology transfer agreements at Bengaluru and Hyderabad defense manufacturing hubs. BIS standards development for aerospace composites lags OEM qualification timelines by 24-36 months.
Global Carbon Fiber Reinforced Plastic Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates with captive precursor supply, compressing margins for non-integrated converters. Three archetypes dominate: PAN precursor-integrated fiber producers, AS9100-certified prepreg specialists, and resin-formulation compounders with wind energy offtake contracts. Competitive moves concentrate on backward integration into acrylonitrile supply and long-term OEM contracting to lock volume commitments.
Among Japanese chemical conglomerates, Toray Industries and Mitsubishi Chemical Group exemplify the precursor-integrated archetype with operations spanning carbonization through prepreg manufacturing. Hexcel Corporation anchors North American positioning through aerospace OEM relationships. Solvay and SGL Carbon occupy distinct formulation-specialist positions, with Solvay representing resin chemistry depth and SGL Carbon exemplifying carbon-based material science focus across industrial grades.
| Leading Market Players |
|---|
| Mitsubishi Chemical Group |
| Solvay |
| Toray Industries |
| Formosa Plastics Corporation |
| DowAksa Advanced Composites |
| Hexcel Corporation |
| Teijin Limited |
| Gurit Services AG |
| SGL Carbon |
| Others |
Supply & Pricing Matrix
Long-term offtake contracting locks in both supply access and price visibility for aerospace-grade carbon fiber prepreg, compressing spot-market liquidity while embedding AS9100 certification costs into multi-year unit pricing. Three-year agreements between Airbus suppliers and German material producers freeze resin-content specifications and carbonization temperature records, transferring feedstock volatility risk onto non-integrated converters.
Pricing Analysis
Certification level creates the primary spread between aerospace-grade and industrial-grade carbon fiber products. Contract-based long-term offtake dominates commercial aviation procurement, while spot purchasing persists in sporting goods. Quality grade and volume scale drive price differentiation, with premium prepreg commanding substantial uplifts over tow products. Cost compression in industrial-grade tow is intensifying because wind turbine blade producers source directly from precursor-integrated manufacturers. Sporting goods manufacturers exhibit highest price sensitivity; aircraft OEMs show least sensitivity due to qualification lock-in effects.
Supply Chain Analysis
Japan and Germany anchor aerospace-grade carbon fiber production through integrated precursor-to-prepreg operations. Acrylonitrile feedstock for PAN precursor draws from petroleum-derived supply chains exposed to energy market fluctuations. Carbon fiber tow, epoxy resin formulations, and autoclave nitrogen inerting systems represent critical input dependencies. Single-source vulnerability concentrates in large-diameter autoclave capacity for fuselage sections. Distribution runs through AS9100-certified distributors for aerospace, direct procurement for wind energy, and wholesale channels for sporting goods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite lifecycle services including repair station certification and predictive maintenance analytics are expanding faster than raw material hardware sales, creating recurring revenue pools for qualified suppliers.
For Market Incumbents: Consolidate supplier relationships around full precursor-to-component traceability to defend against emerging thermoplastic specialists. Deepen backward integration into acrylonitrile supply to offset petroleum feedstock volatility. Lock multi-year offtake agreements with Vestas and Siemens Gamesa before capacity expansion saturates wind energy procurement. For New Entrants and Emerging Players: Lead with hydrogen pressure vessel fabrication as the most penetrable segment outside aerospace qualification barriers. Target India's PLI scheme localization requirements for unmanned aerial systems and helicopter airframes. Pursue technology transfer partnerships at Bengaluru defense manufacturing hubs to bypass BIS standards lag. For Investors and Strategic Acquirers: Capital is best deployed toward precursor-integrated mid-cap specialists with captive PAN supply and existing AS9100 accreditation. Long-term viability hinges on qualification depth rather than capacity scale across the projection horizon. Watch EASA-FAA harmonization progress as signal for accelerated dual-approval pathway monetization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylonitrile | Captive feedstock supply insulates margin compression from petroleum price volatility for PAN precursor producers. |
| Thermoplastic Prepreg Capacity Expansion | Out-of-autoclave processing cuts Boeing and Airbus supplier cycle times for secondary structure components. |
| AS9100 Certification Investment | FAA and EASA traceability mandates elevate tier-two converter compliance costs and consolidate qualified supplier bases. |
| Long-term Supply Agreement with Energy OEMs | Vestas and Siemens Gamesa lock resin and fiber commitments three to five years forward, mirroring aerospace purchasing. |
| Hydrogen Pressure Vessel Joint Venture | Type IV composite tank demand from fuel cell vehicle programs creates volume outside traditional aviation and wind segments. |
Research Methodology
Initial hypotheses were tested against primary input from composite engineering directors, procurement leads at aircraft OEMs, wind turbine blade manufacturing heads, AS9100 certification auditors, and resin formulation R&D directors, then refined against customs trade data, SEC 10-K filings from listed material producers, ECHA REACH registration databases, and FAA airworthiness directive records. Bottom-up volume builds across product types and applications were cross-checked against top-down market sizing from precursor production capacity estimates.
Variance decomposition across the modeling period isolates volume growth from price-mix effects within each segmentation dimension. Segmentation modeling covers product form, processing technology, end-use application, and geographic production hub. CAGRs were derived from fitted trend lines applied to qualified demand estimates. Forecast inputs include acrylonitrile price trajectory assumptions and OEM composite content targets for next-generation airframes.
Forecasts assume regulatory continuity in FAA airworthiness standards, EASA certification requirements, and REACH chemical registration regimes; material policy shifts would require re-modeling. Specific risks include bilateral recognition delays between Japan and China, and PLI scheme modification in India. Recalibration cycles align with material shifts in OEM composite adoption timelines and energy transition policy stringency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Low Temperature Sealing Glass Composite Powder Market
Composite Materials
Graphite Felt Market
Composite Materials
Wind Turbine Composites Market
Composite Materials
Automotive Carbon Fiber Materials Market
Composite Materials
Reinforced Nonwoven Plastics Market
Composite Materials
Carbon Fiber Composites Market
Composite Materials
Lightweight Materials Market
Composite Materials
Global Closed Molding Composites Market
Composite Materials
Synthetic Rope Market
Composite Materials
Polyphenylene Sulfide (PPS) Composites Market
Composite Materials
Carbon Thermoplastic Composites Market
Composite Materials
High-Temperature Composite Materials Market
Composite Materials
High Performance Carbon Fiber Precursor Market
Composite Materials
Global Geocomposites Market
Composite Materials
Composite Drums Market
Composite Materials
Europe Wood-Plastic Composite (WPC) Market