
 Medical Grade Silicone Market | 2026-2036
Medical Grade Silicone Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Grade Silicone Market Analysis
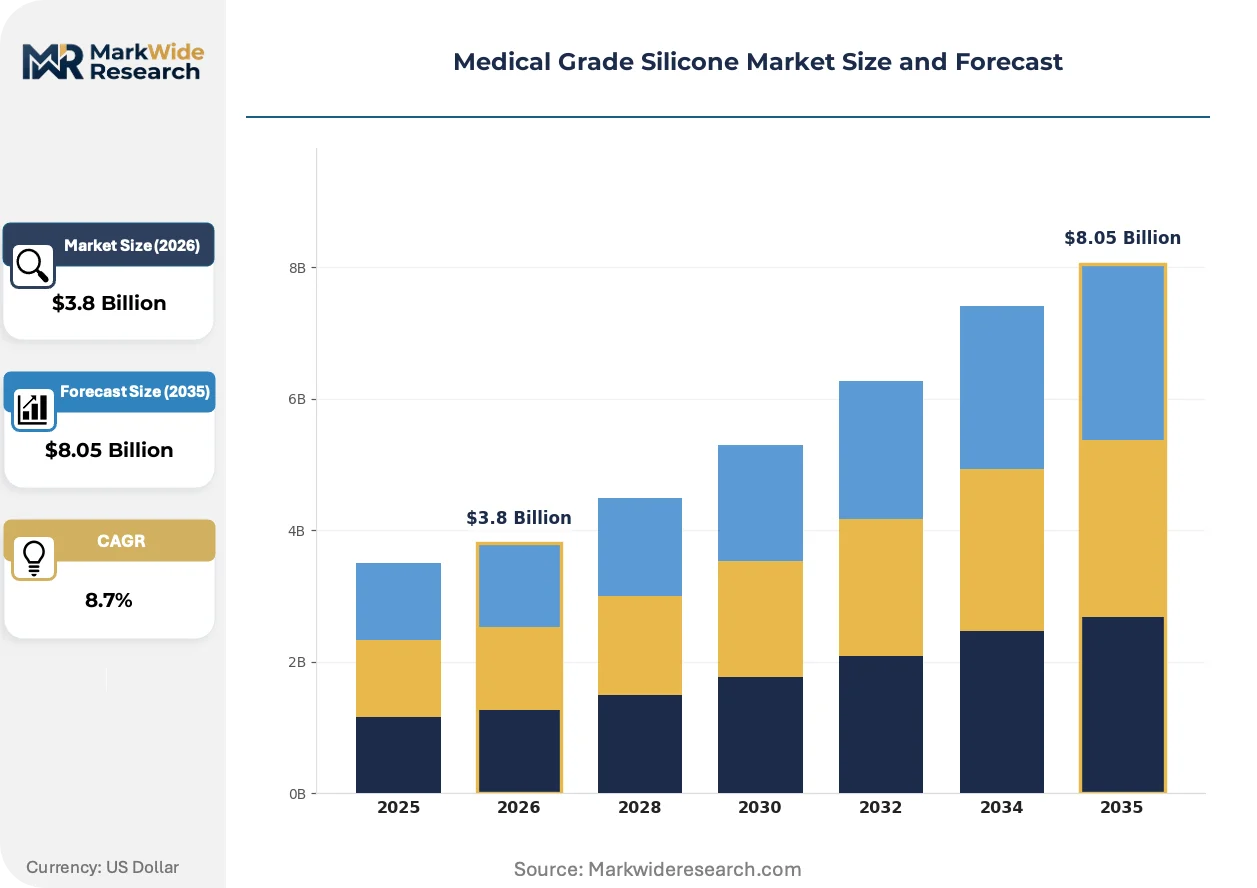
EU MDR is realigning the cost-of-entry calculus for medical silicone suppliers by mandating extended clinical evidence and supply chain traceability. Dow leverages backward integration into siloxane feedstocks to sustain margin control across implant-grade product lines. Wacker Chemie AG anchors its position through ISO 13485-certified production campuses that serve European device OEMs. Shin-Etsu Chemical Co., Ltd. dominates ultra-high-purity polymerization for long-term implant applications where ionic contamination thresholds are most stringent.
Medical grade silicone denotes platinum-cured or peroxide-cured polydimethylsiloxane formulations meeting USP Class VI or ISO 10993 biocompatibility standards, with Shore A hardness typically ranging from 5 to 80 and extractable limits below specified thresholds for implantable durations exceeding 30 days. Liquid silicone rubber commands the largest volume share due to its suitability for high-precision injection molding of complex geometries such as seals and valves in drug delivery systems. Solid silicone rubber retains mature demand in surgical tubing and sheet applications where compression set resistance determines procurement decisions. Foam silicone represents the fastest-growing structural category as wound care and soft-tissue prosthetic applications require controlled porosity combined with skin-contact biocompatibility.
FDA enforces 21 CFR 177.2600 compliance for repeated-use rubber articles in medical settings, while EMA through the MDR framework requires notified body involvement for all implantable silicone devices. ISO 10993-5 cytotoxicity testing and ISO 10993-10 sensitization assays form the baseline biological evaluation protocol that regulators in both jurisdictions cross-reference. Stakeholders must monitor evolving extractables and leachables guidance from pharmacopeial authorities, as analytical detection thresholds for siloxane oligomers continue tightening and will determine which formulation platforms retain commercial viability.
Market Dynamics
EU MDR documentation mandates are compressing supplier margins while concentrating procurement among ISO 13485-certified manufacturers capable of extended biocompatibility traceability. Platinum-cured formulations now dominate implantable device tenders as extractable thresholds tighten.
Growth Catalysts
- Cardiology implant procurement:Pacemaker and defibrillator manufacturers are expanding silicone seal specifications to meet 30-day implantable duration standards under FDA 21 CFR 177.2600.
- REACH-compliant feedstock localization:German precision molding clusters are securing regional siloxane supply chains to serve European hospital device OEMs.
- Foam silicone wound care:Controlled porosity formulations are displacing traditional gauze in post-surgical applications requiring skin-contact biocompatibility.
Market Restraints
- Platinum catalyst cost volatility:Precious metal price swings compress formulation margins for long-term implant grades.
- Ultra-high-purity polymerization concentration:Ion-contamination threshold capabilities cluster among Asian specialty chemical producers.
- Thermoplastic polyurethane substitution:TPU elastomers encroach on short-duration catheter and tubing applications.
Strategic Opportunities
- Soft-tissue prosthetic expansion:Brazil's ANVISA is streamlining silicone implant registration pathways for reconstructive surgery demand.
- Dual-cure process convergence:Platinum-peroxide hybrid curing is enabling thicker cross-section molding without thermal degradation.
- Direct hospital procurement platforms:German university hospital networks are bypassing traditional distributors for custom-molded silicone components.
Industry Challenges
- ISO 10993-18 extractables study capacity:Analytical chemistry bottlenecks delay MDR technical documentation completion.
- Cleanroom molding capex intensity:Class 7 and Class 8 certified production lines require seven-figure capital deployment per facility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Grade Silicone Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Silicone Rubber, Solid Silicone Rubber, RTV Silicone, Foam Silicone Application: Medical Devices, Drug Delivery Systems, Surgical Supplies, Prosthetics End User: Hospitals, Clinics, Laboratories, Home Care Form: Sheets, Tubing, Molds, Coatings |
| Companies Covered | Dow, Wacker Chemie AG, Elkem ASA, Shin-Etsu Chemical Co., Ltd., Momentive Performance Materials, Avantor, Inc., China National Bluestar (Group) Co. Ltd., KCC Corporation, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Grade Silicone Market Emerging Trajectories
Automation of quality verification and real-time process monitoring is compressing batch release timelines while tightening extractable consistency. Regulatory harmonization pressures are forcing convergence between FDA and EMA biocompatibility protocols.
Multi-cavity liquid silicone rubber injection systems is automating precision seal production for drug delivery devices. Diabetes care OEMs in Massachusetts and Minnesota are deploying these platforms at scale. Cycle time compression from automated cavity pressure monitoring is enabling just-in-time supply contracts previously uneconomical at silicone volumes.
EMA's MDR Article 10 technical documentation requirements are mandating supply chain traceability to raw material batch levels. Notified body involvement for all implantable silicone devices extends certification timelines by 12-18 months. German and Swiss device manufacturers are consolidating supplier panels to reduce audit burden.
Hospital procurement teams are consolidating silicone component vendors to capture volume-based pricing and reduce incoming inspection overhead. Group purchasing organizations in the United States are displacing individual hospital negotiations with multi-year framework agreements. Academic medical centers in California and Texas are piloting consignment inventory models for surgical silicone kits.
Medical Grade Silicone Market Segmentation
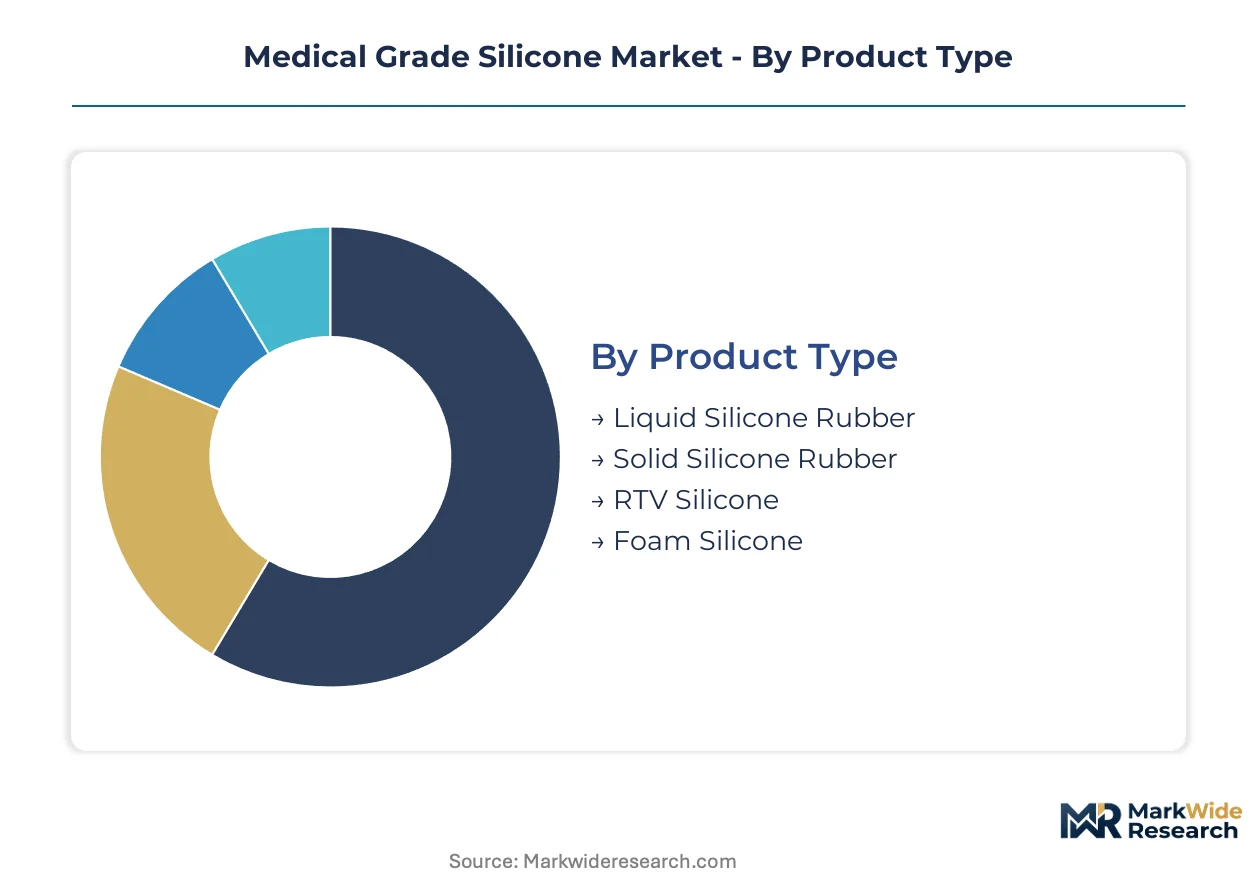
Medical grade silicone procurement hinges on matching curing chemistry and physical form to regulatory exposure duration and sterilization protocols. Device OEMs segment specifications by implantable versus non-implantable service life, with formulation choices directly determining USP Class VI or ISO 10993 testing burden.
Product Type:
Platinum-cured and peroxide-cured chemistries define performance ceilings across implant duration thresholds.
- Liquid Silicone Rubber:Two-part platinum-cured systems enable high-precision injection molding of complex geometries with Shore A hardness from 5 to 80. Demand concentrates in Massachusetts and Minnesota diabetes care OEMs automating multi-cavity production for drug delivery seals and valves.
- Solid Silicone Rubber:Peroxide-cured sheets and extrusions deliver compression set resistance for surgical tubing applications. German precision molding clusters specify solid grades for European hospital supply chain procurement where dimensional stability under repeated sterilization cycles determines vendor selection.
- RTV Silicone:Room-temperature vulcanizing formulations serve prototyping and custom mold applications requiring rapid cure without thermal processing equipment.
- Foam Silicone:Controlled porosity structures combine skin-contact biocompatibility with cushioning properties for wound care dressings and soft-tissue prosthetics.
Mature deployment sits with Liquid Silicone Rubber. Newer deployment is concentrated in Foam Silicone.
Application:
Regulatory jurisdiction and patient contact duration reshape formulation requirements across therapeutic areas.
- Medical Devices:Pacemaker and defibrillator manufacturers specify platinum-cured seals meeting FDA 21 CFR 177.2600 for 30-day implantable duration standards. EMA MDR Article 10 technical documentation mandates extend certification timelines for device-integrated silicone components.
- Drug Delivery Systems:Auto-injector and infusion pump OEMs prioritize extractable consistency and lot-to-lot biocompatibility traceability.
- Surgical Supplies:Tubing, drains, and retractors utilize solid silicone rubber grades where gamma and steam sterilization resistance outweighs precision molding requirements.
- Prosthetics:Soft-tissue reconstruction applications in Brazil are expanding through ANVISA registration pathway streamlining for silicone implant commercialization.
Procurement scale clusters with Medical Devices. Volume expansion is accelerating fastest in Prosthetics.
End User:
Capital intensity and quality verification protocols segment addressable markets by procurement sophistication.
- Hospitals:German university hospital networks are consolidating vendor panels and piloting direct procurement platforms for custom-molded silicone surgical kits, bypassing traditional distributor markups.
- Clinics:Outpatient surgical centers source standardized tubing and seal components through group purchasing organization frameworks.
- Laboratories:Research and diagnostic equipment manufacturers specify ultra-high-purity grades with ionic contamination thresholds most stringent for analytical applications.
- Home Care:Wearable drug delivery and respiratory device markets drive demand for skin-contact biocompatible formulations in patient-operated settings.
Contract concentration sits with Hospitals. Patient-direct volume is building fastest in Home Care.
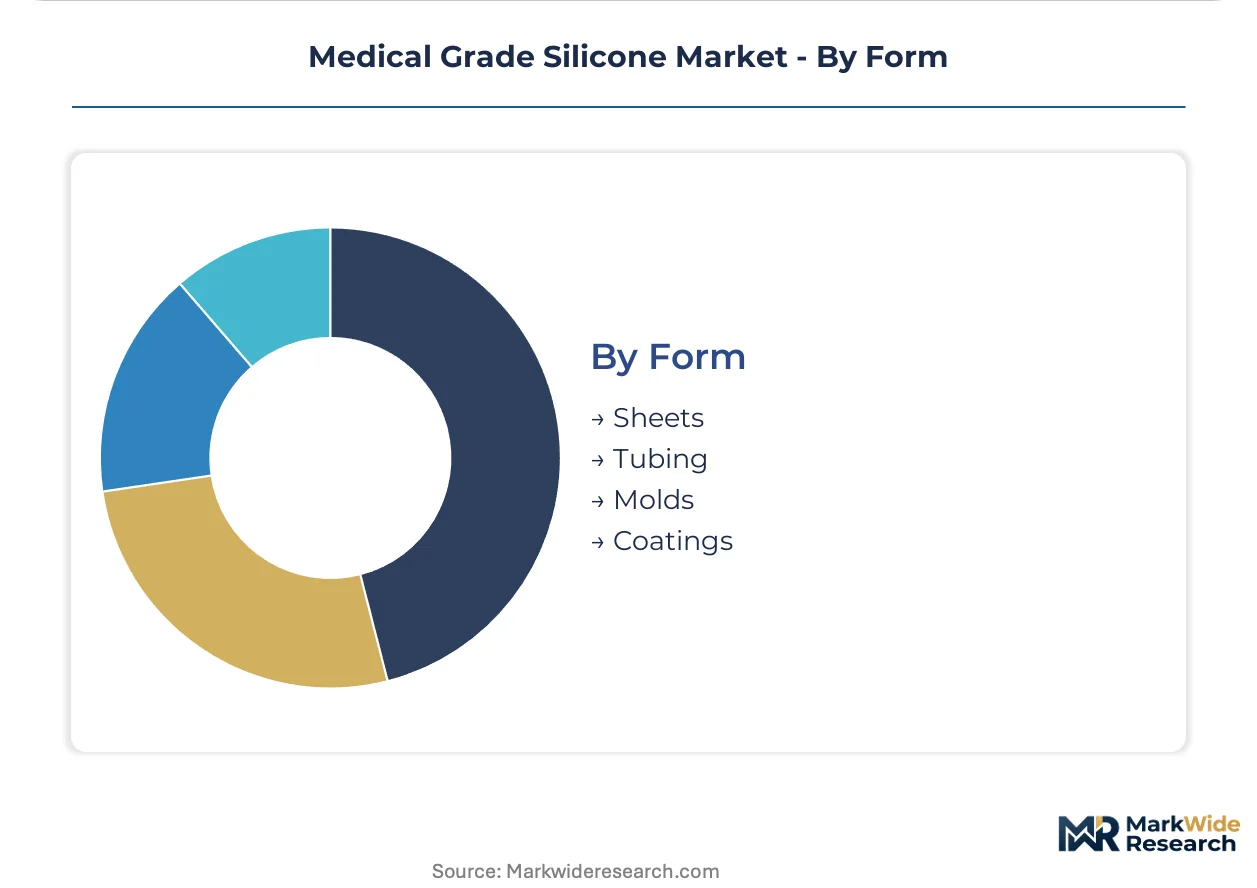
Form:
Manufacturing process compatibility and downstream fabrication steps determine form factor selection.
- Sheets:Calendered solid silicone serves die-cutting operations for gaskets, seals, and wound contact layers where thickness uniformity controls performance.
- Tubing:Extruded profiles dominate fluid transfer applications requiring kink resistance and peristaltic pump compatibility in dialysis and infusion systems.
- Molds:Custom injection-molded components integrate complex geometries including undercuts and thin-wall sections for device assembly.
- Coatings:Thin-film applications provide lubricity and barrier properties on substrates ranging from metal stents to polymer catheters.
Specification maturity sits with Tubing. Technical complexity is climbing fastest in Molds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Germany's precision manufacturing corridor concentrate medical silicone molding capacity to serve European hospital supply chains. Tax incentives for ISO 13485-certified production facilities draw compounders to Bavaria and Baden-Württemberg. This clustering pattern repeats across four additional national markets where regulatory alignment shapes investment decisions.
Germany
Pacemaker seal manufacturers and orthopedic device OEMs drive platinum-cured silicone procurement volumes. EMA's MDR Article 10 technical documentation mandates extend certification timelines for implantable components. The Freiburg precision molding cluster supplies catheter and valve geometries to university hospital networks across the Rhine corridor.
United States
Diabetes care device manufacturers in Massachusetts and Minnesota automate multi-cavity liquid silicone rubber production for drug delivery seals. FDA enforces 21 CFR 177.2600 compliance for repeated-use rubber articles in implantable applications. Greater Boston medical device OEMs consolidate supplier panels to reduce incoming inspection overhead.
China
Domestic cardiology implant production scales drive demand for ultra-high-purity polymerization capabilities. NMPA biocompatibility documentation requirements tighten for long-term implantable silicone devices. The Yangtze River Delta specialty chemical corridor concentrates ion-contamination threshold production for analytical and implant applications.
Brazil
Soft-tissue reconstructive surgery expansion accelerates silicone implant commercialization through streamlined registration pathways. ANVISA regulatory reforms reduce approval timelines for prosthetic-grade formulations. São Paulo-based distributors bypass traditional import channels to secure direct hospital procurement contracts.
Japan
Long-term implant applications requiring stringent extractable limits sustain demand for platinum-cured high-purity grades. PMDA consultation procedures for novel silicone device materials extend pre-market review cycles. The Osaka-Kobe chemical manufacturing belt maintains captive siloxane feedstock integration for medical-grade polymerization.
Medical Grade Silicone Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers and curing chemistry segments. The vendor base stratifies between backward-integrated siloxane producers and downstream compounders serving regional device OEMs. Three archetypes dominate: captive feedstock operators, ISO 13485-certified precision molders, and regional distributors with formulation blending capabilities. Capacity expansion and M&A consolidation represent the dominant competitive moves as MDR documentation requirements raise fixed-cost barriers.
Among diversified chemical conglomerates, Dow and Wacker Chemie AG exemplify the captive-feedstock archetype through upstream siloxane integration. Shin-Etsu Chemical Co., Ltd. occupies a specialist position in ultra-high-purity polymerization for extended-duration implant applications. These three companies represent distinct strategic postures: Dow anchors North American diabetes care supply chains, Wacker serves European device OEMs through certified production campuses, and Shin-Etsu concentrates on ionic contamination thresholds for analytical and long-term implant markets.
| Leading Market Players |
|---|
| Dow |
| Wacker Chemie AG |
| Elkem ASA |
| Shin-Etsu Chemical Co., Ltd. |
| Momentive Performance Materials |
| Avantor, Inc. |
| China National Bluestar (Group) Co. Ltd. |
| KCC Corporation |
| 3M Company |
| Others |
Supply Flow & Price Mechanics
Platinum-catalyst chemists concentrated in Germany's Freiburg precision molding corridor command wage premiums that compress formulation margins for mid-tier compounders while widening spreads between implant-grade and industrial-grade silicone pricing tiers. Labor-cost differentials between certified cleanroom technicians in Bavaria and standard molding operators in Eastern European satellite facilities now determine whether device OEMs qualify for EU hospital procurement panels or compete on spot-market tubing contracts.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to platinum-cured implant grades requiring ISO 10993-18 extractables documentation, while spot inventory of peroxide-cured industrial tubing trades at discounts to contract volumes. Three-tier pricing structure across premium, standard, and economy levels separates FDA 21 CFR 177.2600-compliant implant grades from ISO 13485-certified device components and uncertified industrial formulations. Cost compression in mid-tier solid silicone rubber is intensifying because TPU elastomers encroach on short-duration catheter applications. Price-sensitive buyers cluster in outpatient surgical centers sourcing through group purchasing organizations, while least-sensitive procurement sits with German university hospital networks requiring custom-molded geometries.
Supply Chain Analysis
Domestic-content mandates under EU MDR Article 10 technical documentation requirements are reshaping sourcing toward REACH-compliant siloxane feedstocks produced within European Economic Area borders. Geographic supply concentration centers on Germany, China, and Japan, with ion-contamination threshold capabilities clustering in the Yangtze River Delta and Osaka-Kobe chemical manufacturing belt. Raw material dependencies rest on platinum catalyst supplies from South African refiners, high-purity siloxane monomers from integrated petrochemical complexes, and peroxide curing agents from specialty chemical distributors. Single-source vulnerability concentrates in ultra-high-purity polymerization equipment where Asian producers hold ionic contamination threshold expertise. Distribution runs through ISO 13485-certified compounders serving regional device OEMs, with hospital procurement platforms increasingly bypassing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
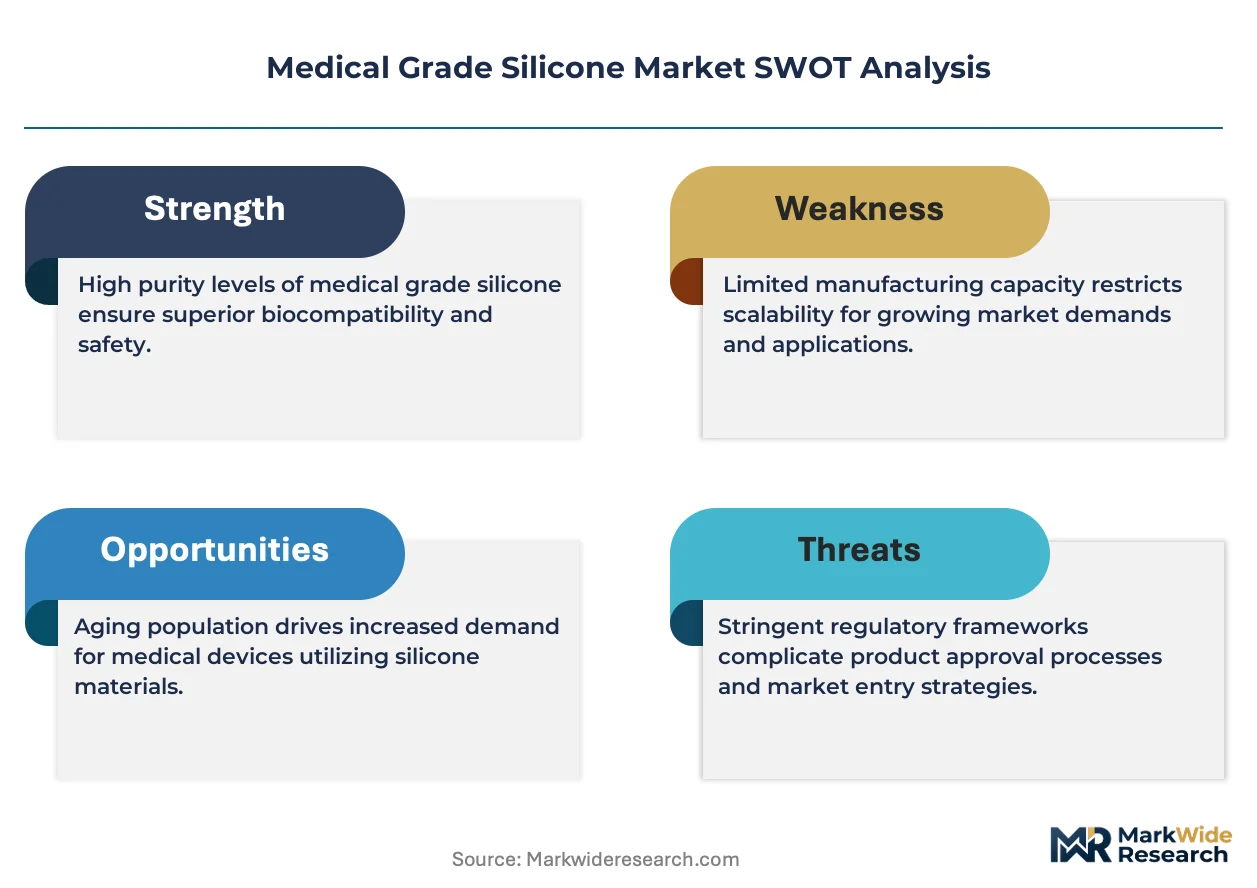
The medical grade silicone market is becoming a vertical-integration race as MDR documentation requirements and platinum catalyst cost volatility compel compounders to secure captive siloxane feedstock supplies and in-house analytical chemistry capabilities for extractables studies.
For Market Incumbents: Deepen backward integration into siloxane monomer production to defend margin compression from precious metal price swings and consolidate supplier panels among German device OEMs facing extended EMA certification timelines. Priority investments should target ISO 10993-18 analytical chemistry capacity to eliminate documentation bottlenecks that delay batch releases. For New Entrants and Emerging Players: Begin with foam silicone wound care formulations for Brazilian reconstructive surgery markets where ANVISA registration pathway streamlining reduces approval timelines versus implantable device tiers. Direct hospital procurement platforms in São Paulo offer a go-to-market angle bypassing established distributor relationships. For Investors and Strategic Acquirers: Re-rating potential sits with ISO 13485-certified precision molders given EU MDR Article 10 mandates extending certification timelines and concentrating procurement among documented suppliers. Long-term viability over a five-to-ten year window favors compounders with cleanroom molding capex already deployed. The signal to watch is notified body audit queue lengths as a real-time indicator of supply-constraint pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Feedstocks | Dow and Wacker Chemie AG sustain margin control across implant-grade product lines through captive monomer supply. |
| ISO 13485 Certification Expansion | EMA MDR technical documentation mandates concentrate procurement among certified manufacturers capable of extended biocompatibility traceability. |
| Multi-Cavity LSR Automation Deployment | Massachusetts and Minnesota diabetes care OEMs compress cycle times for drug delivery seal production through real-time cavity pressure monitoring. |
| Dual-Cure Process Development | Platinum-peroxide hybrid curing enables thicker cross-section molding without thermal degradation for complex orthopedic geometries. |
| Direct Hospital Procurement Platform Launch | German university hospital networks bypass traditional distributor markups for custom-molded silicone surgical kits. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving silicone formulation chemists, biomedical engineers at device OEMs, hospital procurement committee members, group purchasing organization contract managers, and notified body auditors. FDA 21 CFR 177.2600 compliance databases, EMA MDR Article 10 technical documentation submissions, ISO 13485 certification registries, and German precision molding cluster production statistics provided downstream validation. Bottom-up volume estimates from individual compounder capacities reconciled with top-down demand projections from cardiology and orthopedic implant shipment data.
Segment-level modeling tracked curing chemistry, physical form, application exposure duration, and end-user procurement sophistication across the projection horizon. Liquid silicone rubber injection molding volumes, solid silicone rubber extrusion throughputs, and foam silicone porosity specifications were disaggregated by implantable versus non-implantable service life thresholds. CAGR derivation incorporated platinum catalyst price elasticity, cleanroom molding capacity utilization rates, and regulatory certification timeline assumptions. Forecast inputs included notified body audit queue projections, REACH-compliant feedstock localization trends, and TPU substitution elasticities in short-duration catheter applications.
Platinum price volatility, EMA MDR documentation mandate enforcement intensity, and NMPA biocompatibility requirement tightening are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented analytical protocols and stated boundary conditions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Global Cellulose Acetate Market
Specialty Materials
ePTFE Electronic Film Market
Specialty Materials
Talc Alternatives Market
Specialty Materials
Activated Carbon Bags Market
Specialty Materials
Africa Collagen Market
Specialty Materials
Global PMMA Microspheres Market
Specialty Materials
Conductive Plastics Market
Specialty Materials
Dysprosium Oxide Sputtering Target Market
Specialty Materials
Water Soluble Film Market
Specialty Materials
Cellulose Derivative Excipient Market
Specialty Materials
Battery Separator Films Market
Specialty Materials
Metallic Hot Stamping Foils Market
Specialty Materials
Specialty Silicone Market
Specialty Materials
Electroactive Polymers (EAP) Market
Specialty Materials
Engineered Foam Market
Specialty Materials
United States Neoprene Market