
 Respiratory Virus Infection Drug Market | 2026-2036
Respiratory Virus Infection Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Respiratory Virus Infection Drug Market Intelligence
The World Health Organization's focus on pandemic preparedness and response is broadening the strategic scope for respiratory virus infection drug development. GlaxoSmithKline leverages its extensive portfolio in vaccines and antivirals to address seasonal and novel threats. Pfizer competes through significant R&D in mRNA technology and oral antiviral candidates. AstraZeneca specializes in monoclonal antibody therapies for vulnerable patient groups.
Respiratory virus infection drugs encompass therapeutic and prophylactic agents designed to inhibit pathogens like influenza and RSV. These compounds function through specific mechanisms, such as neuraminidase inhibition or blocking viral host cell entry. Among product types, monoclonal antibodies and next-generation vaccines represent the fastest-growing categories due to their targeted efficacy and improved safety profiles. While influenza treatments constitute a mature segment, drug development for respiratory syncytial virus is experiencing significant R&D investment.
Regulatory pathways established by the FDA in the United States and the EMA in Europe set rigorous standards for clinical trial data and drug approval. In parallel, China's NMPA influences market access and post-market surveillance, aligning with its specific public health priorities. Stakeholder success will depend on effectively navigating these diverse and evolving regulatory landscapes while managing the high costs of clinical development.
Market Dynamics
The central structural force is the pivot from broad-spectrum antivirals to targeted therapies. This shift, driven by pandemic preparedness and advances in mRNA and monoclonal antibody platforms, prioritizes mechanism-specific drug development for respiratory pathogens.
Growth Catalysts
- Pandemic Preparedness Mandates:WHO initiatives and national strategies accelerate funding and fast-track approvals for novel antiviral platforms.
- Aging Demographics:A growing elderly population in nations like Japan creates a larger high-risk patient base for severe RSV and influenza.
- Advanced Diagnostics:Rapid point-of-care molecular tests improve early detection, enabling timely antiviral prescriptions and increasing drug utilization.
Market Restraints
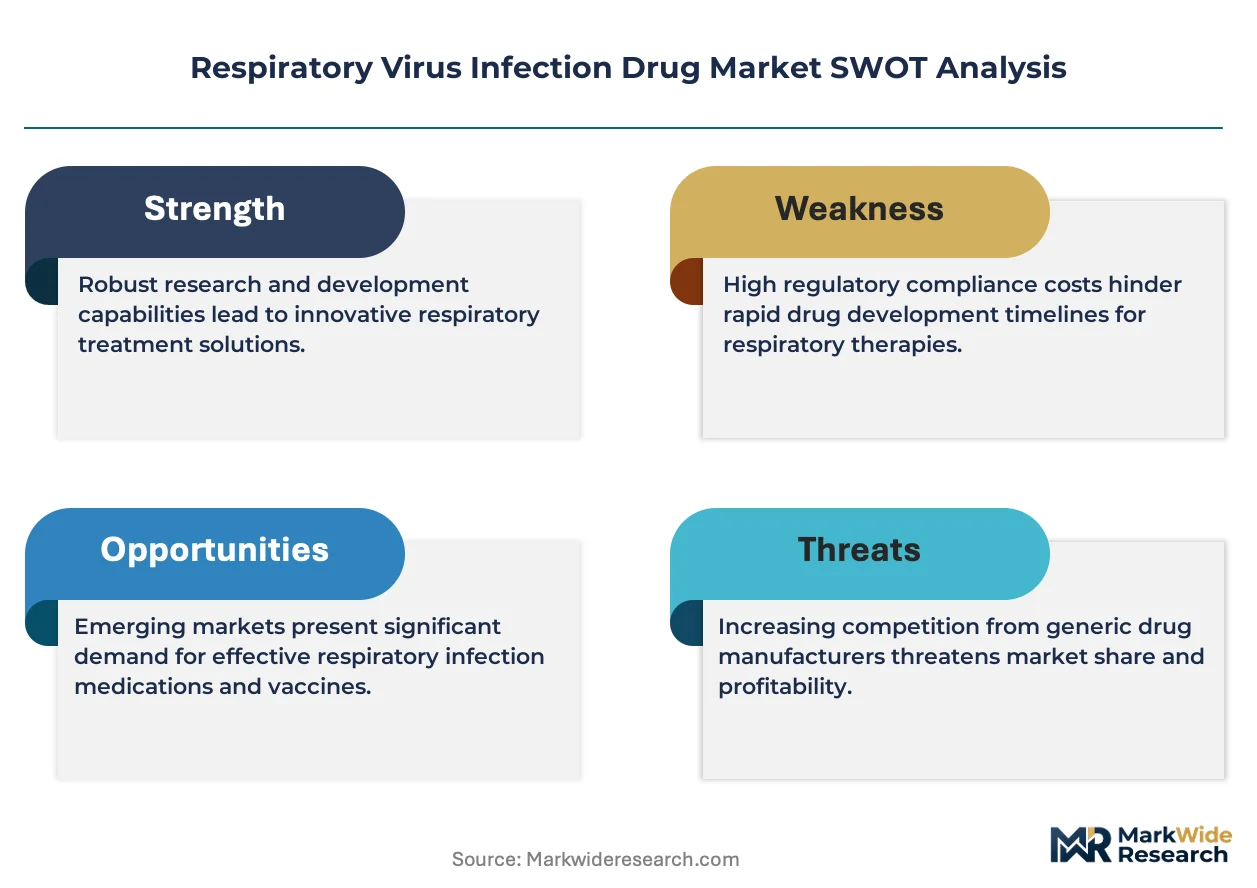
- Viral Mutation and Resistance:High mutation rates in RNA viruses like influenza demand continuous redevelopment, rendering some existing treatments obsolete.
- High Development Costs:The immense cost and long timelines of clinical trials for new antiviral agents create significant barriers to entry.
- Stringent Regulatory Hurdles:Navigating distinct approval requirements from the FDA, EMA, and NMPA for a single product delays market entry.
Strategic Opportunities
- Combination Therapies:Developing drug cocktails targeting multiple viral proteins offers a strategy to combat resistance and improve efficacy in severe cases.
- Pediatric Formulations:An unmet need exists for safe antivirals specifically formulated for infants, a key population vulnerable to RSV.
- Orphan Drug Incentives:The FDA's orphan drug designation provides market exclusivity for drugs targeting rare respiratory pathogens, creating a viable commercial path.
Industry Challenges
- Clinical Trial Enrollment:Recruiting sufficient patients for specific viral infections is difficult outside of peak seasons, extending trial timelines.
- Cold Chain Logistics:Maintaining the integrity of biologics like monoclonal antibodies through the global supply chain is a capital-intensive challenge.
- Intellectual Property Conflicts:Overlapping patents on foundational technologies like mRNA delivery systems lead to complex licensing negotiations and potential litigation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Respiratory Virus Infection Drug Market |
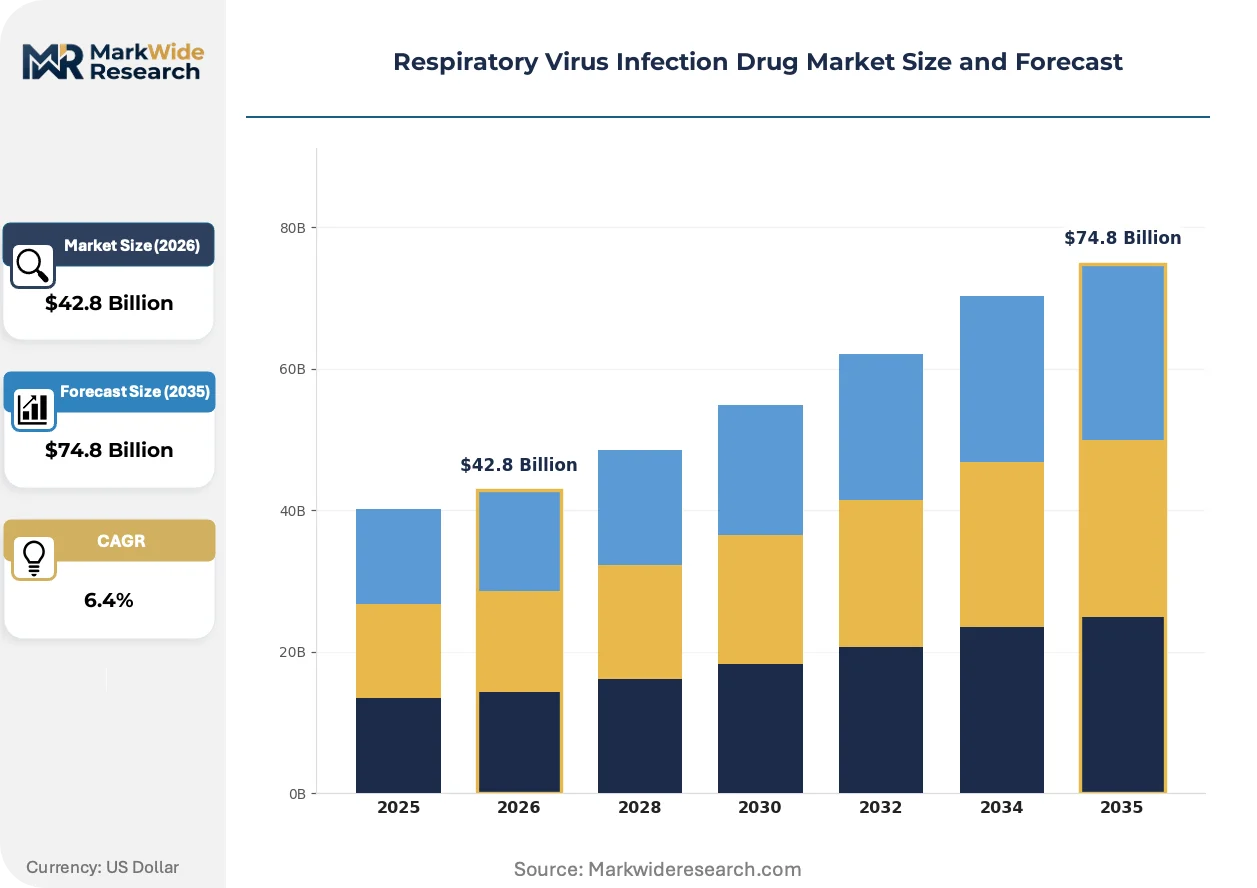
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $74.8 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiviral Agents, Vaccines, Immunomodulators, Monoclonal Antibodies, Symptomatic Relief Agents Therapy Area: Influenza, Respiratory Syncytial Virus, Human Parainfluenza Virus, Human Rhinovirus, Adenovirus End User: Hospitals, Outpatient Clinics, Diagnostic Laboratories, Research Institutes Delivery Mode: Oral, Intravenous, Intramuscular, Inhalation, Nasal Spray |
| Companies Covered | GlaxoSmithKline, AstraZeneca, Sanofi, Pfizer, Merck & Co., Inc., Boehringer Ingelheim International GmbH, F. Hoffmann-La Roche Ltd., Janssen, Moderna, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Respiratory Virus Infection Drug Market Strategic Shifts & Innovations
The market's evolution is defined by a strategic move toward personalized and prophylactic interventions. This transition is driven by technological convergence in drug discovery and a re-evaluation of public health priorities following recent global health events.
AI-driven drug discovery platforms rapidly screen compound libraries to identify novel antiviral candidates. Pharmaceutical R&D departments integrate these tools early in development to shorten discovery timelines. This computational approach is unifying data from genomics, proteomics, and clinical trials into predictive models, accelerating the path from lab to clinic.
Regulatory frameworks like the European Medicines Agency's PRIority MEdicines (PRIME) scheme offer enhanced support for therapies targeting unmet needs. This program accelerates assessment of promising antiviral drugs by enabling earlier interaction with regulators. Developers of next-generation monoclonal antibodies are most affected, allowing alignment of clinical trial designs with EMA expectations.
A shift from treatment-focused purchasing to prophylaxis-driven stockpiling alters procurement for national governments. This change disrupts traditional seasonal buying for influenza antivirals, replacing it with long-term supply agreements. The trend is most visible in the United States and European Union, where preparedness strategies mandate strategic reserves.
Respiratory Virus Infection Drug Market Segmentation
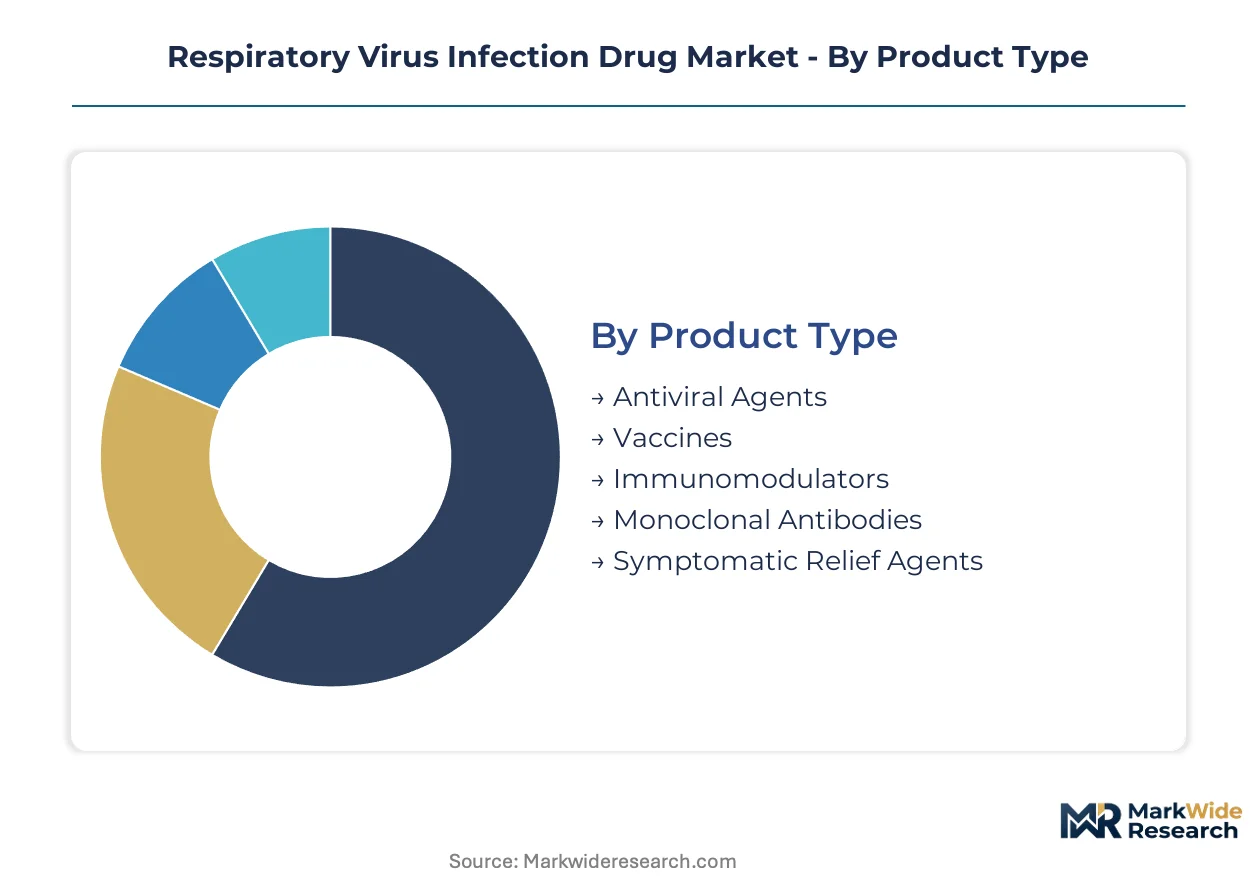
The segmentation analysis of the respiratory virus infection drug market provides a granular understanding of product types, therapy areas, end-user dynamics, and delivery modes. This detailed breakdown illuminates where innovation and demand are concentrating across the therapeutic landscape. Understanding these segments is crucial for strategic market positioning.
Product Type:
The market for respiratory virus infection drugs exhibits a clear division between high-volume, established agents and premium, targeted therapies.
- Monoclonal Antibodies:These biologics offer highly specific targeting of viral proteins, providing passive immunity or direct antiviral action. Demand is accelerating in the United States for high-risk patient populations, driven by improved safety profiles and targeted efficacy against specific pathogens like RSV.
- Antiviral Agents:These small molecules inhibit viral replication through various mechanisms, such as neuraminidase inhibition for influenza. Outpatient clinics in Germany prioritize rapid-acting antiviral agents for timely patient management, improving patient outcomes.
- Vaccines:Prophylactic agents stimulate an immune response against specific respiratory viruses, reducing infection severity and transmission.
- Immunomodulators:These drugs modulate the host immune response to either enhance antiviral activity or mitigate excessive inflammation.
- Symptomatic Relief Agents:These non-specific therapies manage symptoms like fever, cough, and congestion associated with respiratory viral infections.
Mature deployment sits with Antiviral Agents. Newer deployment is concentrated in Monoclonal Antibodies.
Therapy Area:
The market's therapy areas reflect varying levels of clinical maturity and R&D investment, from long-established treatments to emerging therapeutic targets.
- Influenza:This segment addresses a pervasive seasonal respiratory virus, utilizing neuraminidase inhibitors and other antiviral compounds. Demand remains consistently high across Japan, driven by annual vaccination campaigns and the need for rapid treatment options.
- Respiratory Syncytial Virus:This area focuses on preventing and treating a common cause of lower respiratory tract infections, particularly in infants and the elderly. Significant R&D investment in France targets novel monoclonal antibodies and vaccines for vulnerable patient groups.
- Human Parainfluenza Virus:Therapies target these viruses, which cause respiratory illnesses ranging from common colds to pneumonia, especially in young children.
- Human Rhinovirus:This segment addresses the primary cause of the common cold, with research focusing on symptomatic relief and potential antiviral targets.
- Adenovirus:Treatments manage infections caused by adenoviruses, which can affect the respiratory tract, eyes, and gastrointestinal system.
Therapies for Influenza continue to dominate in volume. Treatments for Respiratory Syncytial Virus are expanding most quickly.
End User:
End-user segments delineate distinct purchasing behaviors and clinical priorities, from acute care settings to research-focused institutions.
- Hospitals:These facilities manage severe respiratory viral infections, requiring a broad spectrum of antiviral agents, oxygen support, and critical care medications. Large hospitals in the United Kingdom maintain substantial stockpiles of essential drugs for pandemic preparedness.
- Outpatient Clinics:These clinics focus on early diagnosis and management of less severe infections, emphasizing rapid diagnostics and timely antiviral prescriptions. Primary care networks in Canada increasingly utilize point-of-care testing to guide treatment decisions.
- Diagnostic Laboratories:These laboratories perform viral testing to identify specific pathogens, supporting clinical decision-making and epidemiological surveillance.
- Research Institutes:These organizations conduct fundamental and translational research, developing new antiviral compounds and therapeutic strategies.
Hospitals represent the largest procurement segment. Outpatient Clinics are gaining share fastest due to decentralized care trends.
Delivery Mode:
The choice of delivery mode significantly influences drug efficacy, patient compliance, and administrative convenience across different clinical scenarios.
- Oral:Oral formulations offer convenience for outpatient treatment and prophylaxis, allowing for easy administration outside of clinical settings. Patients in Australia prefer oral antiviral options due to their ease of use and reduced need for medical supervision.
- Intravenous:Intravenous administration ensures rapid drug delivery and high bioavailability, crucial for severe infections requiring immediate therapeutic intervention. Critical care units in Germany rely on intravenous antivirals for hospitalized patients with advanced respiratory disease.
- Intramuscular:Intramuscular injections provide sustained drug release or vaccine delivery, often used for prophylactic measures or specific therapeutic agents.
- Inhalation:Inhaled therapies deliver drugs directly to the respiratory tract, maximizing local concentration and minimizing systemic side effects.
- Nasal Spray:Nasal spray formulations offer a non-invasive delivery route for localized antiviral action or vaccine administration, targeting the upper respiratory tract.
Oral delivery modes command the largest market share due to patient convenience. Inhalation methods are seeing steeper expansion trajectory for targeted lung delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global respiratory virus infection drug market features a complex interplay between drug production capabilities and regional consumption patterns. Highly developed healthcare systems in certain nations drive significant demand for advanced therapies and rapid diagnostics. However, manufacturing hubs for novel biologics and small molecule antivirals are often concentrated in specific geographic clusters.
United States
United States demand for respiratory virus infection drugs is strong, driven by advanced healthcare infrastructure and robust reimbursement policies. The FDA establishes rigorous standards for clinical trial data and drug approval. Boston's biotech corridor actively develops novel monoclonal antibodies and mRNA vaccines.
Germany
Germany prioritizes rapid-acting antiviral agents within outpatient clinics for timely patient management. The European Medicines Agency (EMA) sets rigorous standards for drug approval, influencing market access for new therapies. Pharmaceutical companies in Frankfurt leverage advanced manufacturing capabilities for intravenous antivirals.
Japan
Japan exhibits consistently high demand for influenza treatments, driven by its aging demographic and annual vaccination campaigns. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures strict regulatory oversight for new antiviral compounds. Medical research institutions in Tokyo conduct extensive studies on influenza treatments and next-generation vaccines.
France
France shows significant R&D investment in Respiratory Syncytial Virus therapies, targeting vulnerable patient groups. The Agence Nationale de Sécurité du Médicament et des produits de santé (ANSM) guides drug development, particularly for pediatric formulations. Lyon's biopharmaceutical sector develops novel monoclonal antibodies for RSV prevention.
China
China's National Medical Products Administration (NMPA) influences market access and post-market surveillance for respiratory drugs. The NMPA aligns regulatory pathways with specific public health priorities. Shanghai's pharmaceutical industry expands its local production of antiviral agents.
Respiratory Virus Infection Drug Market Key Industry Players
The competitive structure tilts toward a tiered landscape, with established pharmaceutical giants coexisting with specialized biotech firms. This market features a mix of consolidated players dominating mature segments and fragmented innovators in emerging therapy areas. Strategic archetypes include large-scale integrators with broad portfolios and nimble R&D specialists focused on specific viral targets. Dominant competitive moves involve significant R&D investment in novel platforms and strategic partnerships for drug development.
Among the established pharmaceutical giants, GlaxoSmithKline exemplifies a broad portfolio approach, leveraging extensive vaccine and antiviral capabilities across seasonal and novel threats. Pfizer, a global pharmaceutical corporation, represents significant R&D investment in mRNA technology and oral antiviral candidates, pushing boundaries in therapeutic innovation. AstraZeneca, a biopharmaceutical company, occupies a position in specialized monoclonal antibody therapies for vulnerable patient groups. These entities collectively drive innovation across various product types, from mature antiviral agents to next-generation biologics, shaping the market's trajectory.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| AstraZeneca |
| Sanofi |
| Pfizer |
| Merck & Co., Inc. |
| Boehringer Ingelheim International GmbH |
| F. Hoffmann-La Roche Ltd. |
| Janssen |
| Moderna |
Cost & Logistics Intelligence
Specialized biotech scientists in regions like Boston's corridor and Frankfurt's manufacturing hubs drive labor-cost differentials, influencing pricing-tier spreads between novel biologics and established antivirals. This dynamic interaction ensures that highly skilled human capital directly translates into premium pricing for advanced therapeutic solutions in the respiratory virus drug market.
Pricing Analysis
Cost compression in mature antiviral segments traces to generic competition and high-volume procurement by national health systems. The dominant pricing structure is a hybrid, combining value-based pricing for innovative monoclonal antibodies with contract-based long-term agreements for established vaccines. Price differentiation stems from targeted efficacy against specific pathogens and regulatory approval status from agencies like the FDA. Hospitals exhibit lower price sensitivity for critical care biologics, while outpatient clinics prioritize cost-effective options for routine antiviral prescriptions.
Supply Chain Analysis
Logistics and freight costs for temperature-sensitive biologics, particularly monoclonal antibodies, significantly impact the overall supply chain efficiency. Geographic supply concentrates in China for active pharmaceutical ingredients, Germany for advanced biologics manufacturing, and the United States for mRNA vaccine production. Raw material dependencies include specialized cell culture media and sterile packaging components. A key structural risk is the complex cold chain logistics required to maintain product integrity globally. Distribution runs primarily through direct-to-hospital channels and national strategic stockpiling programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The respiratory virus infection drug market is in a technology-transition phase, with mRNA technology displacing traditional vaccine development approaches. This shift creates both opportunities and challenges across the value chain.
For Market Incumbents:Cement leadership by continuously diversifying R&D into novel platforms like mRNA and gene therapies. Proactively acquire specialized biotech firms possessing promising pipeline assets to counter emerging biotech entrants and viral mutation threats. Invest in strategic partnerships for accelerated clinical development and global market access. Expand manufacturing capacity in key regions to ensure supply resilience against future pandemics.
For New Entrants and Emerging Players:Academic research institutions represent a key channel partner for early-stage validation and technology transfer. Target unmet needs such as pediatric formulations for Respiratory Syncytial Virus or orphan drug development for rare respiratory pathogens. The most penetrable segment lies in specific viral targets with limited existing therapeutic options. Leverage academic collaborations and grant funding for preclinical validation as a focused go-to-market angle.
For Investors and Strategic Acquirers:Re-rating potential sits with specialized monoclonal antibody developers given the high efficacy and targeted nature of these therapies. Long-term viability remains strong, driven by persistent pandemic preparedness mandates and an aging global demographic. Acquisition targets should focus on companies with robust intellectual property in mRNA platforms or novel antiviral mechanisms. Successful Phase 3 trial readouts for innovative antiviral agents serve as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market entry for novel antiviral candidates, meeting urgent public health needs. |
| Regulatory Approval Pathway | Streamlines access to key markets like the United States and Europe for new therapies. |
| Licensing Agreement | Expands product portfolios with innovative therapeutic modalities and broader market reach. |
| Manufacturing Scale-Up | Ensures global supply for high-demand biologics, supporting national preparedness strategies. |
| Pipeline Diversification | Mitigates risks associated with single-product reliance in a rapidly evolving viral landscape. |
Research Approach
Document review covered FDA filings, EMA submissions, ClinicalTrials.gov, and industry white papers, complemented by interviews with drug development executives and regulatory affairs leads. This approach integrated insights from hospital procurement managers and infectious disease specialists. Bottom-up and top-down triangulation validated market size estimations and growth projections.
The quantitative model produced detailed volume and value outputs across the analysis window, segmented by product type, therapy area, end-user, and delivery mode. This analytical framework also incorporated regional regulatory clusters as a key dimension. Compound annual growth rates were derived from historical growth trends and projected future market drivers. Key forecast inputs included disease prevalence rates and R&D pipeline progress for novel antiviral agents.
Several conditions sit outside the modeled scope, including unforeseen global pandemics or rapid shifts in government healthcare spending. The forecasts reflect assumptions regarding R&D success rates and regulatory timelines. Stakeholders should weigh these assumptions against their own operating context, considering the risk factors of highly resistant viral strains or major regulatory policy changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
North America Adenomyosis Drugs Market
Pharmaceuticals
Europe Sodium-Dependent Glucose Cotransporter 2 Market
Pharmaceuticals
Anti-Obesity Drugs Market
Pharmaceuticals
AI Drug Development Market
Pharmaceuticals
Atorvastatin API Market
Pharmaceuticals
Nuclear Medicines Radioisotopes Market
Pharmaceuticals
North America Meglitinide Market
Pharmaceuticals
Cough Syrup Market
Pharmaceuticals
Submucosal Lifting Agent Market
Pharmaceuticals
Complement-Targeted Therapeutics Market
Pharmaceuticals
Oncology Small Molecule Drugs Market
Pharmaceuticals
Middle-East and Africa Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Global Pharmaceutical Warehousing Market
Pharmaceuticals
Global Specialty Pharmaceuticals Market
Pharmaceuticals
Global Alteplase Market
Pharmaceuticals
Global Nizatidine Market