
 Thrombosis Drugs Market | 2026-2036
Thrombosis Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Thrombosis Drugs Market Intelligence
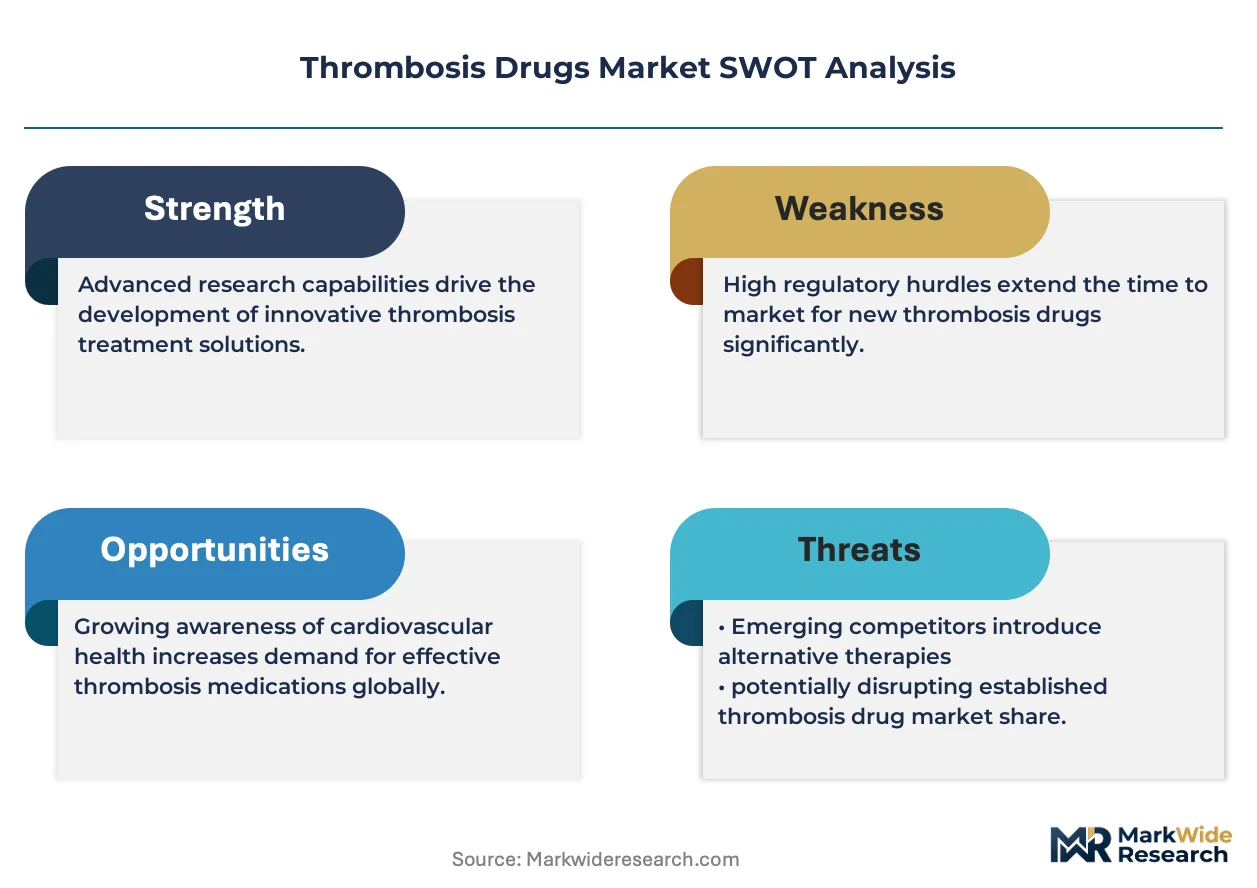
The divergence in R&D investment capacity for large-scale clinical trials is unwinding the traditional competitive landscape. Major pharmaceutical firms like Pfizer leverage extensive global distribution networks to maximize reach for their blockbuster drugs. In contrast, companies such as Daiichi Sankyo differentiate through focused research on novel anticoagulant mechanisms. Bristol-Myers Squibb sustains its market position through strategic alliances and a strong pipeline in cardiovascular therapies.
Thrombosis drugs are pharmacological agents designed to prevent or dissolve pathological blood clots within the circulatory system. These therapies function by either inhibiting specific clotting factors, such as Factor Xa, or by preventing platelet aggregation. Anticoagulants represent the largest drug type segment, driven by the effectiveness of newer oral medications. Within therapy areas, treatments for atrial fibrillation and stroke prevention command the largest share due to high patient volumes and chronic treatment regimens.
Regulatory oversight from bodies like the U.S. FDA, the European Medicines Agency (EMA), and Japan's PMDA is stringent. These agencies mandate extensive clinical trials to prove both efficacy and safety, particularly regarding bleeding risks, which shapes market entry. The approval pathways for biosimilars and next-generation anticoagulants are a critical area of focus. Navigating the choice between established therapies with extensive safety data and innovative drugs offering superior efficacy will define future clinical practice.
Market Dynamics
The clinical and regulatory imperative to balance antithrombotic efficacy against bleeding risk defines the market's structure. This dynamic intensifies with widespread NOAC adoption and a growing elderly population susceptible to both thrombosis and hemorrhage.
Growth Catalysts
- Novel Anticoagulant Mechanisms:Research into Factor XI and XII inhibitors promises therapies with reduced bleeding risk compared to current Factor Xa inhibitors, attracting significant R&D investment.
- Aging Demographics:High-prevalence countries for atrial fibrillation, such as Japan and Germany, exhibit sustained demand for long-term stroke prevention therapies due to their rapidly aging populations.
- Clinical Guideline Endorsements:Updated recommendations from bodies like the European Society of Cardiology that prioritize NOACs over traditional vitamin K antagonists for stroke prevention accelerate adoption in clinical practice.
Market Restraints
- Patent Expirations:The loss of market exclusivity for blockbuster drugs like apixaban and rivaroxaban invites generic and biosimilar competition, putting downward pressure on pricing for branded therapies.
- Stringent Safety Mandates:Regulatory bodies including the FDA and Japan's PMDA require extensive post-market surveillance and risk evaluation mitigation strategies to monitor for adverse bleeding events.
- High R&D Investment:The immense cost and long timelines of large-scale cardiovascular outcome trials create a significant barrier to entry for smaller biopharmaceutical firms.
Strategic Opportunities
- Companion Diagnostics:Integrating genetic testing to identify patient-specific responses to anticoagulants offers a path to personalized medicine, improving safety and justifying premium pricing.
- Underserved Patient Populations:Developing specific therapies for cancer-associated thrombosis represents a significant opportunity, as this patient group has distinct clinical needs not fully met by current drugs.
- Digital Health Integration:Mobile applications and wearable devices that monitor adherence and potential side effects for patients on oral anticoagulants provide a new channel for improving outcomes.
Industry Challenges
- Reversal Agent Availability:Limited access to and high cost of specific reversal agents, such as andexanet alfa for Factor Xa inhibitors, pose a clinical challenge during emergency bleeding events.
- Complex Reimbursement Negotiations:Securing favorable reimbursement status from national payers like Germany's G-BA or the UK's NICE requires demonstrating significant cost-effectiveness over established, cheaper alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thrombosis Drugs Market |
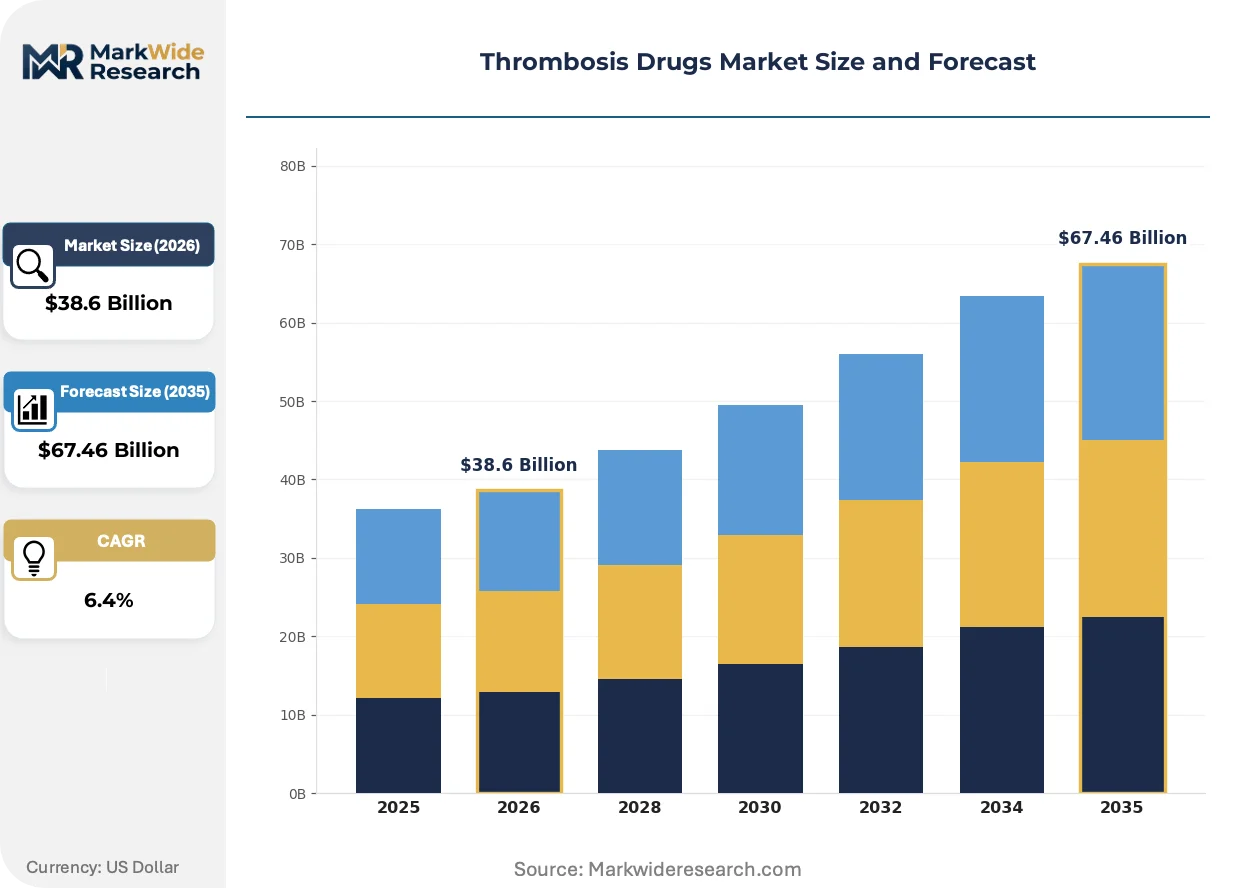
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $67.46 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Anticoagulants, Antiplatelets, Thrombolytics, Hemorrheologic Agents Therapy Area: Deep Vein Thrombosis, Pulmonary Embolism, Atrial Fibrillation, Stroke Prevention End User: Hospitals, Specialty Clinics, Diagnostic Laboratories, Ambulatory Surgical Centers Formulation Type: Oral Tablets, Injectable Solutions, Topical Gels, Sublingual Tablets |
| Companies Covered | Boehringer Ingelheim, Pfizer, Bristol-Myers Squibb, AstraZeneca, Daiichi Sankyo, Johnson & Johnson, Bayer, Novartis, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thrombosis Drugs Market Strategic Shifts & Innovations
Precision medicine concepts are altering therapeutic strategies in thrombosis. The market is moving beyond a one-size-fits-all approach toward tailored treatments aligned with individual patient risk profiles and genetic predispositions, driven by diagnostic advancements.
Next-generation anticoagulants like Factor XI and XII inhibitors are a focal point of pharmaceutical research. These agents selectively target components of the intrinsic coagulation pathway, involved in thrombosis rather than hemostasis. This drug class is miniaturizing the therapeutic intervention, aiming to uncouple antithrombotic efficacy from the systemic bleeding risk of broader-acting agents.
Regulatory frameworks are adapting to novel anticoagulant complexity. The European Union's Clinical Trial Regulation (CTR) streamlines approvals via a single system for trial applications and reporting through the Clinical Trials Information System (CTIS). This change impacts how sponsors conduct multinational cardiovascular outcome studies, requiring a unified strategy across EU member states.
Patient-centric care models are displacing traditional management of chronic anticoagulation. The shift is away from routine INR clinic visits toward long-acting NOACs and digital tools for remote monitoring and adherence support. This trend is most advanced in the United States and Northern Europe, where systems focus on home-based care delivery.
Thrombosis Drugs Market Segmentation
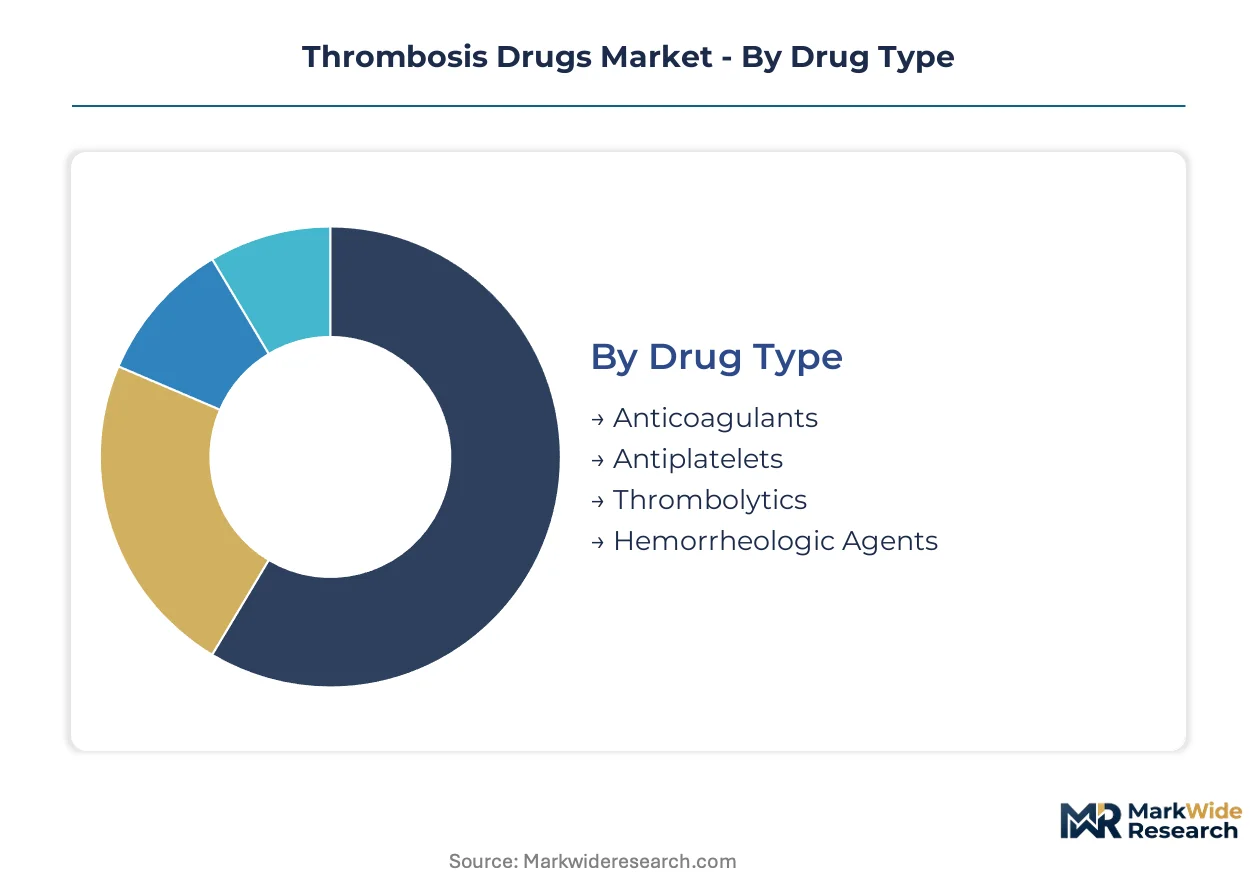
The thrombosis drugs market categorizes diverse pharmacological agents based on their mechanisms of action, therapeutic applications, and delivery methods. Understanding these segments is critical for pharmaceutical companies to align R&D with unmet patient needs and for healthcare systems to optimize treatment pathways.
Drug Type:
Regulatory frameworks heavily influence the classification and market entry for different drug types, particularly concerning their safety profiles and approved indications.
- Anticoagulants:These agents prevent blood clot formation or extension by interfering with the coagulation cascade, often targeting specific clotting factors like Factor Xa or thrombin. Demand concentrates in the United States, driven by its aging demographic and the high prevalence of cardiovascular diseases requiring long-term prevention.
- Antiplatelets:These medications inhibit platelet aggregation, thereby preventing the formation of arterial clots, commonly used in patients with acute coronary syndromes or peripheral artery disease. Clinical guidelines from bodies like the European Society of Cardiology support their widespread use for secondary prevention in high-risk individuals.
- Thrombolytics:Designed to dissolve existing blood clots rapidly, these drugs are typically administered in acute, life-threatening situations such as ischemic stroke or massive pulmonary embolism. Their use requires careful patient selection due to significant bleeding risks.
- Hemorrheologic Agents:These drugs improve blood flow by reducing blood viscosity and enhancing red blood cell flexibility, primarily used for conditions like peripheral arterial disease.
Established volume favors Anticoagulants; emerging adoption favors Hemorrheologic Agents.
Therapy Area:
Application of thrombosis drugs varies significantly across therapeutic indications, reflecting diverse patient needs and disease progression.
- Atrial Fibrillation:This therapy area addresses the prevention of stroke in patients with irregular heartbeats, where blood clots can form in the heart and travel to the brain. Patient volumes are high in countries with aging populations, such as Japan and Germany, sustaining demand for long-term therapies.
- Stroke Prevention:This segment includes primary and secondary prevention strategies for ischemic stroke, often involving long-term anticoagulant or antiplatelet therapy. The U.S. FDA and European Medicines Agency rigorously evaluate new drugs for efficacy and safety in reducing stroke incidence.
- Deep Vein Thrombosis:Treatment and prevention of blood clots forming in deep veins, typically in the legs, constitutes a significant therapy area. Management involves acute treatment and extended prophylaxis.
- Pulmonary Embolism:This life-threatening condition involves a blood clot blocking an artery in the lungs, requiring immediate and effective antithrombotic intervention.
Stroke prevention therapies continue to drive significant patient volumes, while management of deep vein thrombosis experiences consistent demand.
End User:
Patient care settings dictate the distribution and administration of thrombosis drugs, influencing procurement patterns and treatment protocols.
- Hospitals:These institutions serve as primary sites for acute thrombotic events, requiring immediate drug administration and intensive patient monitoring. Hospitals manage a broad spectrum of patients, from emergency admissions to those undergoing surgical procedures with thrombotic risk.
- Specialty Clinics:Focused on specific conditions like cardiology or hematology, these clinics manage chronic anticoagulation therapy and provide follow-up care for patients. Their role in long-term patient management is expanding, especially with the rise of NOACs.
- Diagnostic Laboratories:These facilities provide essential testing for thrombosis, including coagulation factor assays and genetic predisposition screening, guiding drug selection and dosage.
- Ambulatory Surgical Centers:These centers perform outpatient surgical procedures, requiring protocols for perioperative thrombosis prophylaxis.
Hospitals remain the primary point of care for acute thrombotic events, with specialty clinics expanding their role in chronic disease management.
Formulation Type:
The choice of formulation type depends on patient adherence, acute clinical need, and specific drug delivery mechanisms.
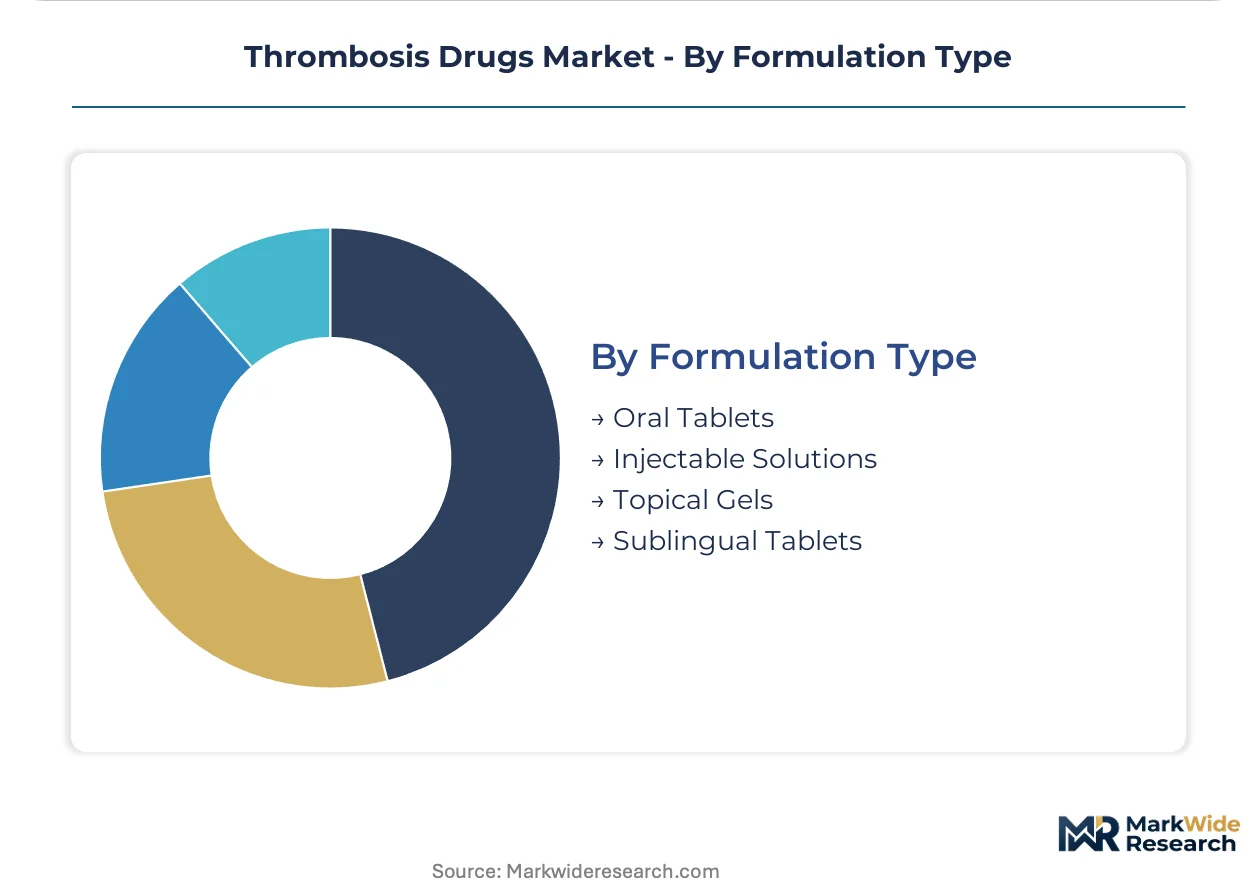
- Oral Tablets:This formulation type includes widely adopted novel oral anticoagulants (NOACs) and vitamin K antagonists, offering convenience for long-term patient adherence. Digital health integration, such as mobile applications, supports adherence for patients on these medications.
- Injectable Solutions:Used for rapid onset of action in acute settings or for patients unable to take oral medication, this category includes heparins and some thrombolytics. Access to reversal agents for these solutions remains a clinical challenge during emergency bleeding events.
- Topical Gels:These formulations deliver antithrombotic agents directly to localized areas, typically for superficial thrombophlebitis or venous insufficiency.
- Sublingual Tablets:Designed for rapid absorption through oral mucosa, this formulation type offers an alternative for patients with swallowing difficulties or for quick systemic action.
Oral tablets dominate long-term patient adherence, while injectable solutions are critical for immediate clinical intervention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global thrombosis drugs market exhibits a complex interplay between domestic production and international supply, driven by specialized manufacturing capabilities and regional demand. Advanced economies often lead in pharmaceutical innovation and export high-value novel oral anticoagulants. Conversely, certain regions rely on imports to meet the growing need for both established and next-generation antithrombotic therapies.
United States
Demand for thrombosis drugs in the United States is significantly influenced by its aging demographic and the high prevalence of cardiovascular diseases. The U.S. FDA mandates extensive clinical trials for new antithrombotic agents, ensuring rigorous safety and efficacy standards. Pharmaceutical clusters in states like New Jersey and Massachusetts drive research and development, focusing on novel anticoagulant mechanisms and personalized medicine approaches.
Japan
Japan's rapidly aging population sustains high demand for long-term stroke prevention therapies, particularly for atrial fibrillation. The PMDA oversees stringent approval processes for new drugs, emphasizing both efficacy and reduced bleeding risks. Major pharmaceutical companies headquartered in Tokyo and Osaka actively invest in R&D for next-generation anticoagulants to address this demographic shift.
Germany
High patient volumes for atrial fibrillation and an aging demographic underpin the sustained demand for thrombosis drugs across Germany. The European Medicines Agency (EMA) guides regulatory approvals for novel antithrombotic therapies throughout the European Union. Biomedical hubs in cities like Munich and Berlin contribute to clinical research and the development of advanced treatment protocols.
China
A large patient population and increasing awareness of cardiovascular health are fueling demand for thrombosis drugs in China. The National Medical Products Administration (NMPA) is streamlining approval pathways for innovative medicines, including novel anticoagulants. Major pharmaceutical manufacturing bases in Shanghai and Guangzhou are expanding local production and R&D capabilities for antithrombotic agents.
Thrombosis Drugs Market Key Industry Players
Concentration sits with established pharmaceutical giants leveraging extensive R&D capabilities and global distribution networks. The market structure is characterized by a tiered competitive landscape, featuring multinational corporations alongside specialized biopharmaceutical firms. Three strategic archetypes define this space: blockbuster drug producers, novel mechanism innovators, and strategic alliance builders. Dominant competitive moves include extensive R&D investment for new molecular entities and strategic partnerships to expand market access.
Among the multinational pharmaceutical companies, Pfizer and Bristol-Myers Squibb exemplify firms that sustain market position through strategic alliances and strong pipelines in cardiovascular therapies. Pfizer leverages extensive global distribution networks to maximize reach for its blockbuster drugs. Daiichi Sankyo represents a company differentiating through focused research on novel anticoagulant mechanisms, particularly in next-generation anticoagulants. These firms collectively anchor the development and commercialization of antithrombotic drugs, driving innovation in therapeutic approaches and shaping future clinical practice.
| Leading Market Players |
|---|
| Boehringer Ingelheim |
| Pfizer |
| Bristol-Myers Squibb |
| AstraZeneca |
| Daiichi Sankyo |
| Johnson & Johnson |
| Bayer |
| Novartis |
| Sanofi |
| Others |
Cost & Logistics Intelligence
The U.S. FDA's stringent approval pathways gate both supply qualification and price differentiation for novel thrombosis drugs. These regulatory hurdles ensure product safety while allowing premium pricing for validated therapies.
Pricing Analysis
National payers anchor contract-based pricing for thrombosis drugs, emphasizing cost-effectiveness over established alternatives. Price differentiation stems from superior efficacy data, reduced bleeding risk profiles, and the availability of specific reversal agents. Pricing pressure intensifies for branded therapies due to impending patent expirations and generic competition. Hospital procurement departments and national health systems exhibit high price sensitivity, while specialty clinics may accept premium pricing for innovative, clinically differentiated treatments.
Supply Chain Analysis
Strategic stockpiling of critical thrombosis drugs is common, balancing demand volatility with manufacturing lead times for complex agents. Supply concentrates in specialized pharmaceutical manufacturing hubs within the United States, Europe, and India. The supply chain relies on the availability of active pharmaceutical ingredients and sterile packaging components. Single-source vulnerability for highly specialized APIs represents a structural risk, while global distribution networks deliver products to hospitals and specialty clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The thrombosis drugs market faces capability scarcity in developing novel agents that uncouple antithrombotic efficacy from bleeding risk. This specific R&D challenge requires significant investment in advanced mechanistic understanding and clinical trial expertise.
For Market Incumbents: Consolidate market share by aggressively investing in next-generation anticoagulant research, particularly Factor XI and XII inhibitors. Leverage extensive global distribution networks to counter generic erosion for blockbuster drugs nearing patent expiry. Strategic alliances with diagnostic firms can integrate companion diagnostics, justifying premium pricing. This proactive approach mitigates threats from novel mechanism innovators and maintains a competitive edge.
For New Entrants and Emerging Players: Differentiate on novel anticoagulant mechanisms offering superior safety profiles for specific patient groups. Target underserved patient populations like those with cancer-associated thrombosis, where existing therapies have limitations. Develop therapies with reduced bleeding risk by focusing on Factor XI/XII inhibitors. Integrate digital health solutions for remote monitoring and adherence support, providing a distinct value proposition.
For Investors and Strategic Acquirers: Carve-out targets emerge from large pharmaceutical firms divesting non-core cardiovascular assets or smaller biotechs with promising early-stage anticoagulant pipelines. The market offers long-term viability due to sustained demand from aging demographics and chronic disease prevalence. Investors should seek specialized firms with strong intellectual property in Factor XI/XII inhibitors. Successful Phase 3 clinical trial readouts for next-generation anticoagulants serve as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates the introduction of Factor XI and XII inhibitors with improved safety profiles. |
| Regulatory Approval Pathway | Streamlines market entry for novel oral anticoagulants across major economic blocs. |
| Licensing Agreement | Integrates genetic testing into treatment protocols, enhancing personalized medicine strategies. |
| Manufacturing Scale-Up | Ensures sufficient supply of new molecular entities to meet global patient demand. |
| Pipeline Diversification | Addresses unmet needs in patient groups such as those with cancer-associated thrombosis. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through extensive primary interviews. Regulatory affairs leads, hospital procurement managers, R&D executives, and formulary directors provided critical insights. This primary research was validated against secondary sources including FDA filings, EMA submissions, ClinicalTrials.gov, and national health authority reports. A robust triangulation approach combined bottom-up market sizing with top-down validation.
The analytical framework projects market dynamics across the analysis window, integrating volume and value outputs. Segmentation dimensions include drug type, therapy area, end user, formulation type, and regional regulatory cluster. Compound annual growth rates were derived from historical trends and projected market shifts. Key industry-specific inputs included patent expiration schedules and novel anticoagulant clinical trial success rates.
Forecasts assume regulatory continuity in the US FDA and European Medicines Agency regimes; material policy shifts would require re-modeling. These projections reflect current clinical practice guidelines and R&D pipelines. Revision becomes warranted when significant unforeseen bleeding events or novel reversal agent developments cross clinical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
B7-H3 Antibody Market
Pharmaceuticals
North America Analgesics Market
Pharmaceuticals
Global Osteoporosis Drugs Market
Pharmaceuticals
Acne Therapeutics Market
Pharmaceuticals
Selective Serotonin Reuptake Inhibitors Market
Pharmaceuticals
Nuclear Medicines Radioisotopes Market
Pharmaceuticals
Saudi Arabia Insulin Drugs and Delivery Devices Market
Pharmaceuticals
High Potency API Contract Manufacturing Market
Pharmaceuticals
Global Psychotropic Drugs Market
Pharmaceuticals
Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Global Liver Diseases Therapeutics Market
Pharmaceuticals
Clozapine Market
Pharmaceuticals
Netherlands Pharmaceutical Market
Pharmaceuticals
Aripiprazole Market
Pharmaceuticals
Global Online Pharmacy Market
Pharmaceuticals
North America Glucagon-Like Peptide-1 Agonists Market