
 US Quick Lube Equipment Market | 2026-2036
US Quick Lube Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
US Quick Lube Equipment Market Analysis
ASE Blue Seal certification is collapsing the competitive field to shops with credentialed technicians and compliant equipment workflows. Graco Inc. leverages its fluid handling engineering heritage to dominate high-volume dispensing installations. Lincoln Industrial anchors its position through integrated pump and meter systems designed for continuous-duty bay operations. Balcrank Corporation competes on specialized reel and hose configurations tailored to quick-lube throughput demands.
Quick lube equipment encompasses fluid transfer, containment, and monitoring systems built to handle petroleum and synthetic lubricants within SAE viscosity grades, typically operating at pressures from 750 to 1500 PSI in commercial service environments. Oil change equipment and fluid dispensing machines represent the mature revenue core, while IoT-enabled equipment captures the fastest structural expansion as shops integrate tank-level monitoring and automated service logging. Fleet operators and automotive shops split end-user demand, with fleet procurement concentrating on mobile solutions for multi-site maintenance and automotive shops prioritizing fixed automated systems for lane efficiency.
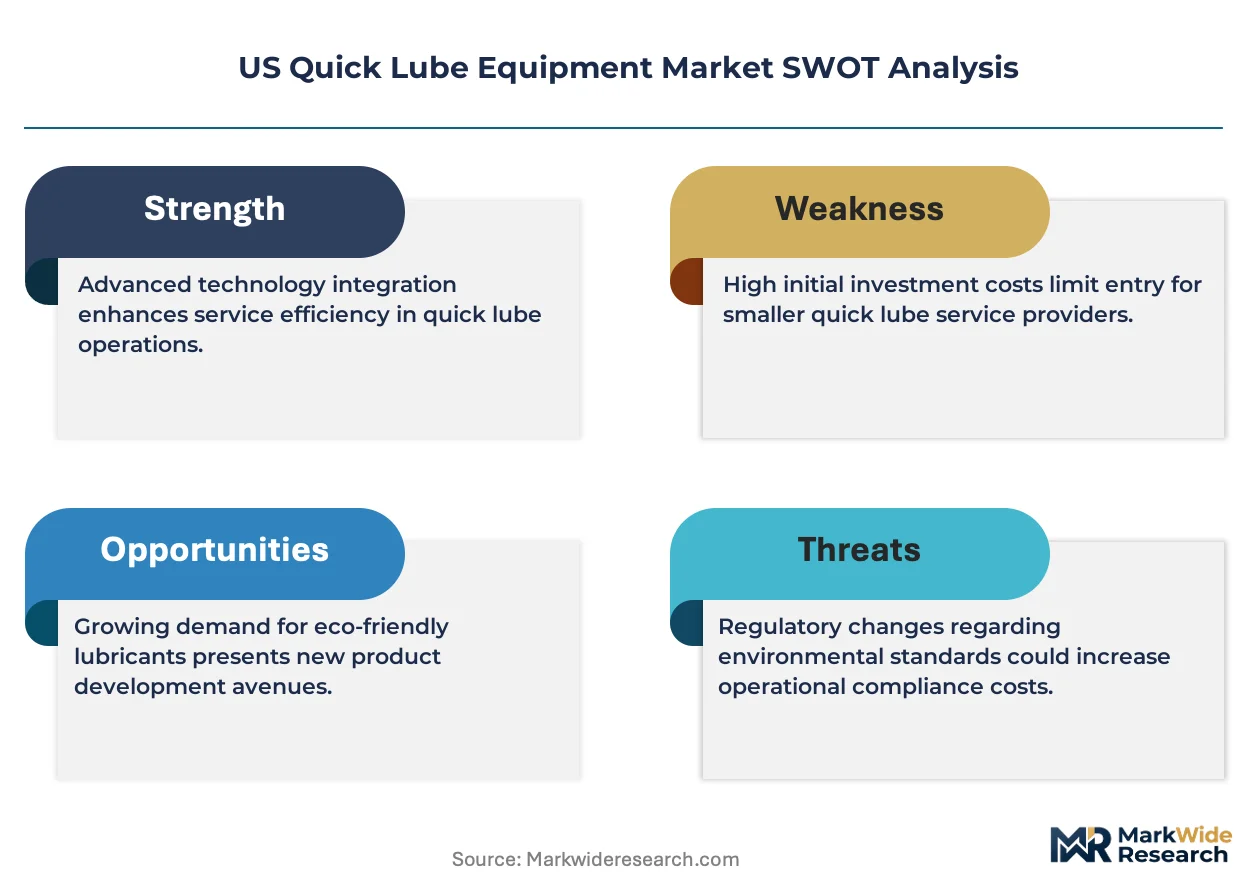
EPA Resource Conservation and Recovery Act provisions govern waste oil storage and handling, compelling equipment upgrades with secondary containment and leak detection. OSHA workplace exposure limits for petroleum distillates shape ventilation and splash-guard specifications on new installations. State-level environmental agencies in California and Texas layer additional discharge and reporting requirements that filter equipment eligibility. Stakeholders must weigh capital allocation between proven manual systems and connected platforms that preempt regulatory audit exposure.
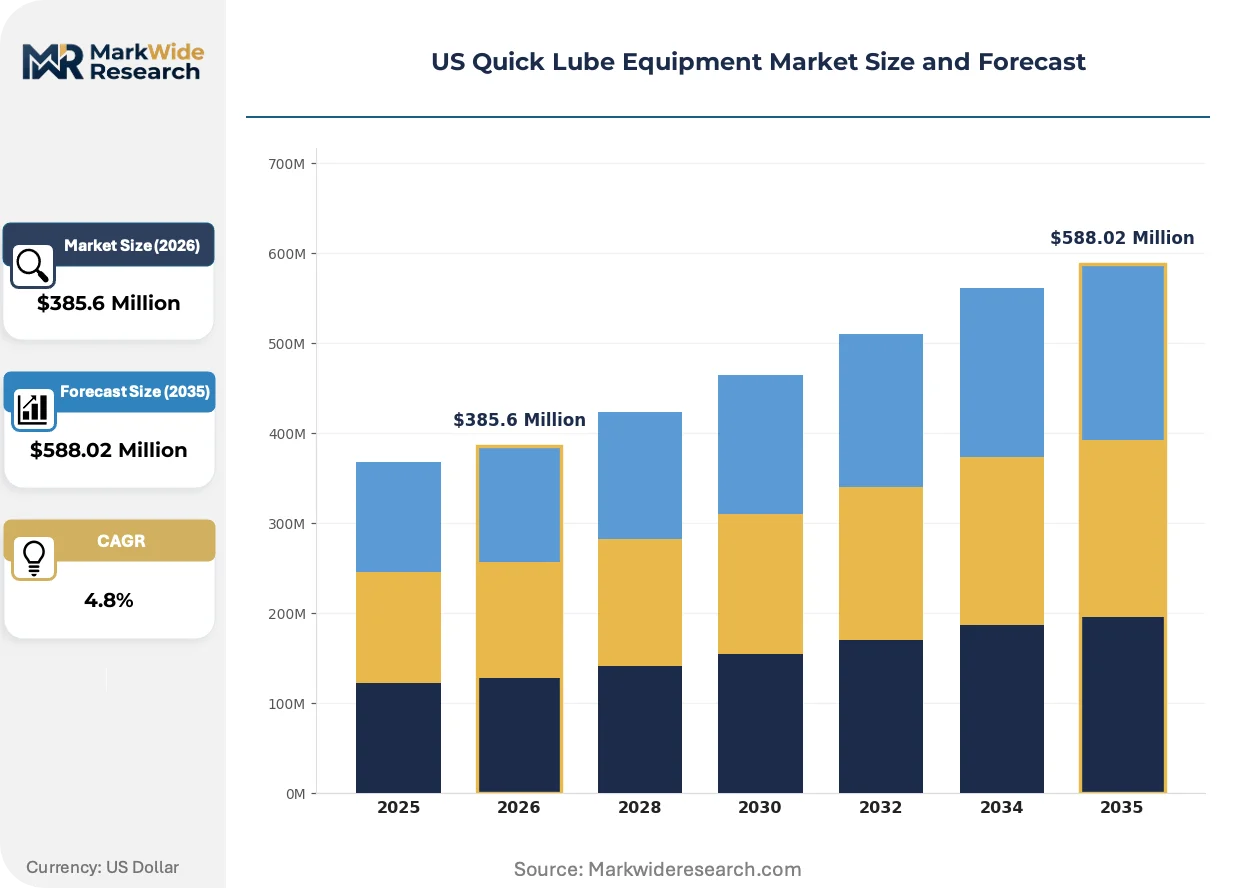
Market Dynamics
Fleet preventive maintenance programs are expanding service bay throughput requirements, forcing equipment suppliers to engineer higher-volume fluid handling systems with integrated compliance monitoring.
Growth Catalysts
- EPA Resource Conservation and Recovery Act:Secondary containment mandates are compelling service operators to replace aging storage tanks with leak-detection-equipped systems, creating replacement demand across California and Texas corridors.
- Fleet electrification transition:Mixed-fleet maintenance programs require quick-lube bays to handle both conventional lubricants and thermal management fluids, expanding equipment capability requirements.
- IoT tank-level monitoring:Connected sensors are enabling predictive inventory management, reducing downtime and allowing multi-site operators to centralize procurement decisions.
Market Restraints
- Steel and aluminum input volatility:Dispensing system fabricators face margin compression from commodity price swings affecting reel housings and pump components.
- Single-source pneumatic component suppliers:Concentrated supply of precision valves and actuators from Midwest manufacturing clusters creates vulnerability for just-in-time equipment assembly.
- SAE viscosity grade proliferation:Equipment must accommodate expanding synthetic and low-viscosity formulations, complicating pump calibration and meter accuracy specifications.
Strategic Opportunities
- ASE Blue Seal certification expansion:Uncredentialed shops in secondary Texas and California markets represent conversion targets for compliant equipment packages.
- Mobile fleet service units:On-site preventive maintenance for logistics and municipal fleets requires portable dispensing and containment systems with DOT transport compliance.
- Infrared fluid analysis integration:Convergence of spectroscopic sensors with dispensing hardware enables real-time contamination detection, differentiating premium equipment tiers.
Industry Challenges
- EPA audit documentation:Waste oil tracking and manifest systems require staff training on digital logging protocols, extending implementation timelines for smaller operators.
- Legacy pneumatic-to-digital retrofit:Existing bay configurations demand costly electrical infrastructure upgrades to support connected monitoring and automated service logging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Quick Lube Equipment Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $588.02 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil Change Equipment, Fluid Dispensing Machines, Diagnostic Tools, Lifting Equipment End User: Service Stations, Automotive Shops, Fleet Operators, Dealerships Technology: Manual Systems, Automated Systems, IoT-enabled Equipment, Mobile Solutions Service Type: Preventive Maintenance, Full-Service Oil Changes, Diagnostics Services, Lubrication Services |
| Companies Covered | JohnDow Industries, Devon Industries, Lincoln Industrial, Trico Corporation, American Lubrication Equipment, Graco Inc., Balcrank Corporation, Denco Lubrication, Alemlube USA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Quick Lube Equipment Market Emerging Trajectories
Connected equipment architectures are redefining competitive differentiation, with sensor integration and automated compliance documentation becoming baseline requirements rather than premium features.
Automated meter calibration systems are displacing manual viscosity compensation in high-throughput installations. Fleet operators with centralized procurement functions are adopting these systems fastest, prioritizing volume accuracy over initial capital outlay. This shift is displacing traditional mechanical meter technologies that require frequent technician adjustment and introduce compliance audit risk.
OSHA workplace exposure limits for petroleum distillates are tightening ventilation and splash-guard specifications on new equipment installations. Manufacturers must now engineer integrated fume extraction and sealed dispensing interfaces to satisfy inspection protocols. Automotive service chains in California are responding fastest, driven by state-level discharge reporting requirements layered atop federal mandates.
Buyer consolidation among multi-site fleet operators is compressing equipment procurement cycles and unbundling after-sales service contracts. Large logistics and municipal fleets now negotiate direct equipment supply agreements, bypassing traditional distribution channels. This pattern concentrates most visibly across Texas interstate corridors where density of fleet maintenance facilities enables volume-based supplier relationships.
US Quick Lube Equipment Market Segmentation
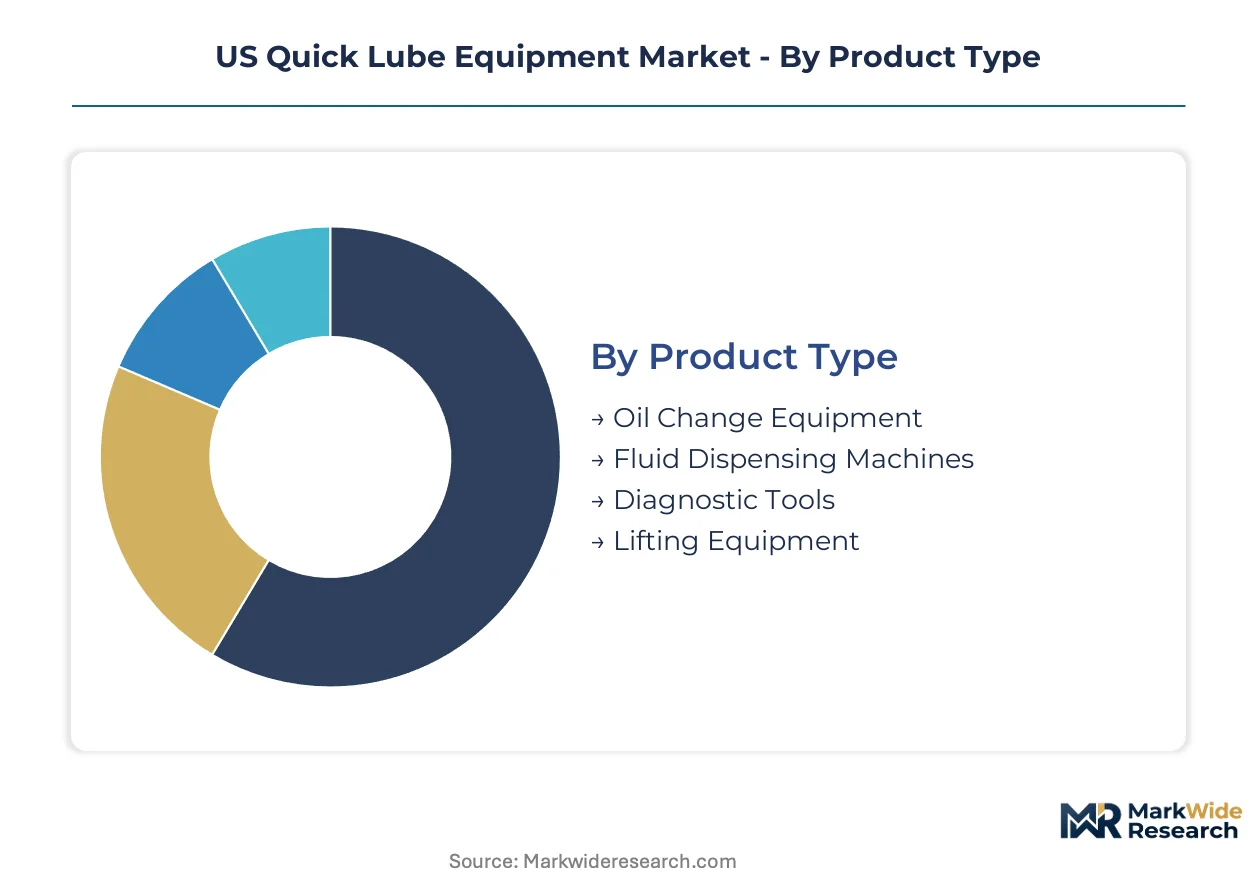
Equipment segmentation in the US quick lube market reveals distinct margin profiles across product configurations, with technology tiers and end-user scale driving procurement decisions. Understanding these divisions exposes where suppliers can defend premium positioning and where volume commoditization pressures dominate.
Product Type:
Margin concentration pools in precision dispensing hardware where EPA secondary containment mandates and SAE viscosity calibration requirements create specification barriers for low-cost entrants.
- Oil Change Equipment:Gravity-fed and pneumatic evacuation systems dominate bay installations, handling petroleum and synthetic lubricants across SAE viscosity grades. Demand concentrates in Texas and California service corridors where fleet density and state-level discharge reporting compel equipment upgrades. EPA Resource Conservation and Recovery Act provisions on leak detection drive replacement cycles in aging facilities.
- Fluid Dispensing Machines:High-pressure pump and meter assemblies operating at 750-1500 PSI form the revenue core, with integrated reel configurations from specialized manufacturers. Automotive shops in high-throughput lanes prioritize fixed automated systems for volume efficiency, while fleet procurement emphasizes accuracy certification for warranty compliance.
- Diagnostic Tools:Infrared spectroscopic sensors for real-time contamination detection are gaining traction among premium service tiers.
- Lifting Equipment:Hydraulic and pneumatic service bay lifts complete the workflow infrastructure for under-vehicle fluid access.
The dominant share belongs to Oil Change Equipment, while Fluid Dispensing Machines is closing the gap fastest as accuracy specifications tighten.
End User:
Customer scale determines procurement sophistication, with multi-site operators leveraging centralized purchasing to unbundle after-sales service and compress supplier margins.
- Fleet Operators:Logistics and municipal fleets with preventive maintenance programs demand mobile dispensing units and DOT-compliant containment for multi-site service. Texas interstate corridor density enables direct supplier negotiations, bypassing traditional distribution. These buyers prioritize volume accuracy and centralized inventory visibility over initial capital outlay.
- Automotive Shops:Quick-lube chains and independent service centers focus on lane throughput and ASE Blue Seal certification compliance. California shops respond fastest to OSHA ventilation and splash-guard specifications, driven by layered state and federal mandates. Fixed automated systems with IoT tank-level monitoring reduce downtime and preempt regulatory audit exposure.
- Service Stations:Convenience-store-anchored facilities emphasize compact footprint and minimal technician training requirements.
- Dealerships:OEM-affiliated service departments integrate manufacturer-specified equipment for warranty documentation.
Fleet Operators command the largest procurement volumes, though Automotive Shops are expanding equipment capability requirements most rapidly through mixed-fleet electrification transitions.
Technology:
Connectivity premiums are collapsing as sensor integration and automated compliance documentation shift from optional upgrades to baseline competitive requirements.
- IoT-enabled Equipment:Tank-level monitoring sensors and automated service logging platforms enable predictive inventory management across multi-site operations. Fleet operators with centralized procurement functions adopt these systems fastest, reducing downtime and enabling procurement consolidation. California and Texas service corridors show highest penetration where regulatory documentation burdens are heaviest.
- Automated Systems:Meter calibration automation displaces manual viscosity compensation in high-throughput installations, eliminating technician adjustment errors and audit risk.
- Manual Systems:Pneumatic and gravity-fed configurations persist in cost-sensitive secondary markets and legacy bay retrofits.
- Mobile Solutions:Portable dispensing and containment systems serve on-site fleet maintenance with DOT transport compliance requirements.
IoT-enabled Equipment holds the technology premium, while Automated Systems are penetrating highest-volume installations most aggressively.
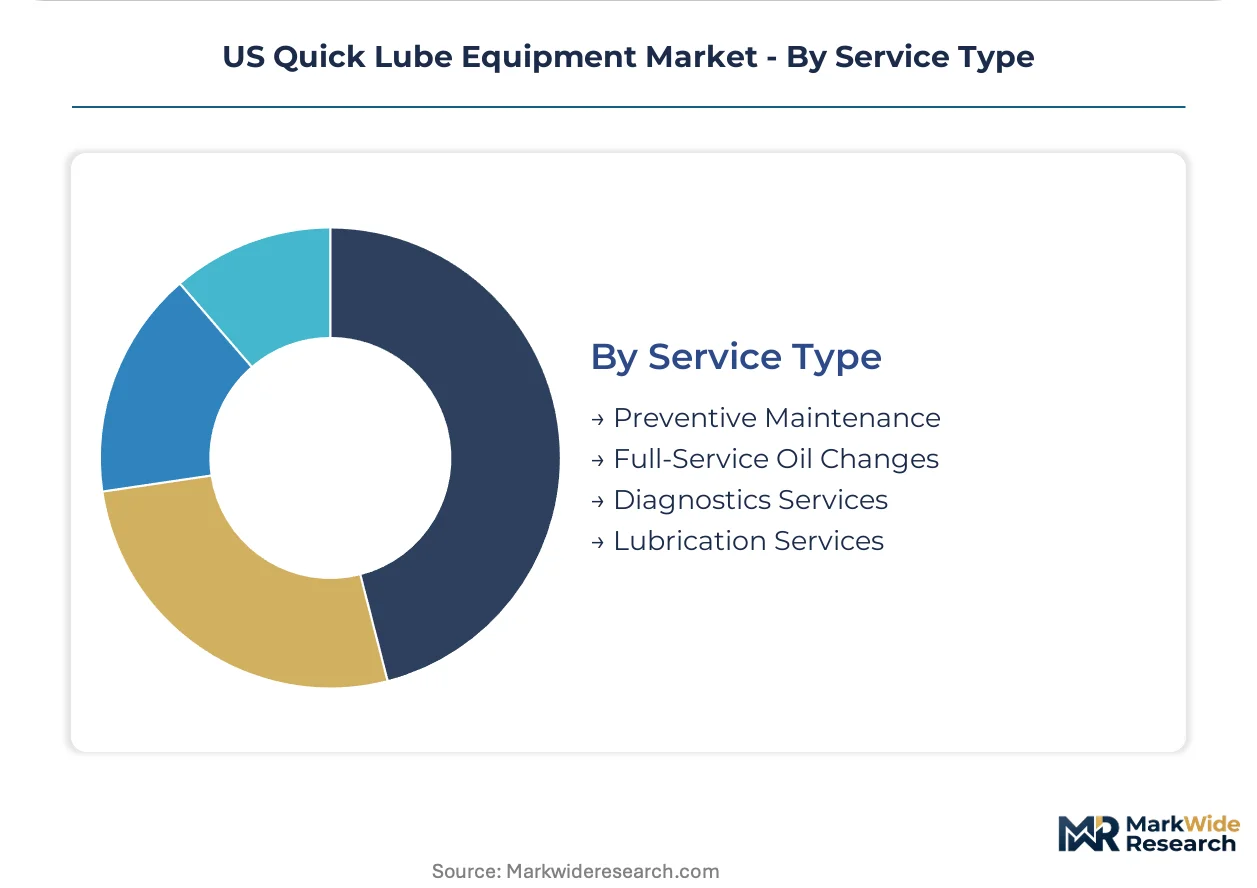
Service Type:
Service bundling intensity varies by customer type, with preventive maintenance programs creating recurring equipment utilization patterns that justify capital investment.
- Preventive Maintenance:Scheduled fluid replacement programs for fleet and commercial vehicles generate predictable bay throughput and equipment depreciation schedules. Demand concentrates among logistics operators and municipal fleets expanding service programs across Texas and California corridors. Equipment specifications emphasize speed and documentation automation for compliance audit trails.
- Full-Service Oil Changes:Consumer-facing quick-lube operations compete on lane turnaround time and ASE certification visibility.
- Diagnostics Services:Fluid analysis and condition monitoring add premium service tiers requiring specialized sensor integration.
- Lubrication Services:Grease and specialty fluid applications serve heavy-duty and off-road equipment segments.
Preventive Maintenance anchors equipment utilization rates, while Diagnostics Services are expanding fastest as infrared fluid analysis converges with dispensing hardware.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate 10 and Interstate 35 corridors anchor equipment demand concentration, linking Texas Gulf Coast petrochemical capacity to California emissions compliance zones through dense fleet maintenance infrastructure.
Texas
Logistics fleet density along the Houston-Dallas-San Antonio triangle drives preventive maintenance program expansion. EPA Resource Conservation and Recovery Act secondary containment mandates accelerate tank replacement cycles in aging Dallas-Fort Worth service facilities. The Permian Basin energy corridor generates parallel demand from oilfield service vehicle fleets requiring mobile dispensing compliance.
California
CARB discharge reporting requirements layered atop federal OSHA exposure limits force ventilation and splash-guard upgrades in Los Angeles and Bay Area quick-lube chains. ASE Blue Seal certification penetration concentrates in Southern California automotive service corridors. Central Valley agricultural fleet operators adopt IoT tank-level monitoring to preempt multi-site audit exposure.
Illinois
Chicago metropolitan freight rail interchanges sustain Great Lakes fleet maintenance demand for high-volume fluid handling systems. State environmental agency spill prevention rules govern secondary containment specifications in Cook County service bays. Rockford industrial corridor manufacturers supply precision pneumatic components to national equipment fabricators.
Ohio
Columbus-to-Cleveland logistics corridors anchor Midwest fleet operator procurement for automated meter calibration systems. Ohio EPA waste oil manifest documentation requirements shape digital logging platform adoption. Cincinnati-area automotive service chains prioritize fixed automated installations for lane throughput efficiency.
Georgia
Atlanta interstate distribution hubs drive southeastern fleet preventive maintenance program growth. State-level underground storage tank regulations accelerate leak-detection-equipped system replacements. Savannah port logistics corridors generate demand for DOT-compliant mobile dispensing units serving drayage and container transport fleets.
US Quick Lube Equipment Market Vendor Landscape
Listed leaders compete with private specialists across capital access and customization agility, producing a tiered structure where scale-driven incumbents defend high-volume installations against nimble regional fabricators. Strategic archetypes separate into integrated fluid handling conglomerates, specialized reel and hose configuration shops, and mobile fleet solution providers. Competitive moves concentrate on portfolio diversification into IoT-enabled platforms and geographic expansion through distribution channel consolidation.
Among established fluid handling specialists, Graco Inc., Lincoln Industrial, and Balcrank Corporation exemplify distinct competitive positioning archetypes. Graco Inc. occupies the integrated engineering tier, leveraging heritage capabilities across precision dispensing applications. Lincoln Industrial anchors the continuous-duty bay operation segment through pump and meter system integration. Balcrank Corporation represents specialized configuration expertise, focusing on reel and hose arrangements calibrated to quick-lube throughput specifications. These three entities collectively illustrate how technical differentiation in pressure ratings, viscosity handling, and compliance documentation shapes procurement decisions across Texas and California service corridors.
| Leading Market Players |
|---|
| JohnDow Industries |
| Devon Industries |
| Lincoln Industrial |
| Trico Corporation |
| American Lubrication Equipment |
| Graco Inc. |
| Balcrank Corporation |
| Denco Lubrication |
| Alemlube USA |
| Others |
Supply Flow & Price Mechanics
Steel-to-aluminum substitution in reel housings and pump components is simultaneously shifting procurement geography toward Midwest manufacturing clusters and compressing margin structures across equipment tiers as commodity volatility feeds through to contract negotiations.
Pricing Analysis
Volume-discount tiering structures dominate procurement between multi-site fleet operators and equipment fabricators, with centralized buyers extracting 15-20 point differentials over independent shop purchases. Price differentiation hinges on ASE Blue Seal certification bundling and after-sales service unbundling, with certified packages commanding substantial premiums. Cost compression in economy-tier pneumatic systems is intensifying because steel input volatility erodes fabricator margins. Fleet operators with direct supplier agreements show lowest price sensitivity, while independent automotive shops in secondary Texas markets exhibit highest elasticity.
Supply Chain Analysis
Inbound logistics costs from Port of Houston congestion and container availability constraints on Asia-Pacific trade lanes are elevating landed costs for precision pneumatic valves and electronic sensor components. Domestic fabrication draws from Ohio, Illinois, and Michigan for pump assemblies, while aluminum extrusions and specialty hoses source from domestic mills and Mexican maquiladora operations. Single-source vulnerability concentrates in Midwest precision valve manufacturing clusters. Distribution runs through authorized equipment distributors serving Texas and California service corridors, with direct OEM relationships bypassing traditional channels for large fleet accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US quick lube equipment market is entering a cyclical recovery phase as EPA tank replacement mandates and fleet electrification transitions force capital refresh cycles across aging service bay infrastructure.
For Market Incumbents: Consolidate aftermarket service networks in Texas and California corridors to preempt distributor disintermediation by large fleet accounts. Deepen backward integration into precision pneumatic component production to offset single-source vulnerability in Midwest manufacturing clusters. Prioritize IoT platform certification investments that embed compliance documentation into recurring revenue streams.
For New Entrants and Emerging Players: ASE Blue Seal certification fast-tracks offer the most penetrable entry vector for uncredentialed shops in secondary Texas markets seeking compliant equipment packages. Target mobile fleet service units for municipal and logistics operators requiring DOT-compliant portable dispensing systems. Pursue white-label manufacturing partnerships with established reel and hose specialists to bypass capital-intensive pump engineering barriers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fluid handling conglomerates seeking platform roll-up opportunities in fragmented reel and hose configuration specialists. Long-term viability centers on IoT-enabled equipment architectures that shift revenue from transactional hardware to recurring compliance and monitoring services. Monitor EPA enforcement intensity in California and Texas as the primary inflection signal for replacement demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| IoT Platform Integration | Connected tank-level monitoring transforms capital equipment into recurring compliance revenue streams for fleet operators. |
| Backward Integration into Pneumatics | In-house valve production insulates margins from Midwest supplier concentration and commodity price swings. |
| ASE Certification Bundling | Certified equipment packages capture premium positioning as uncredentialed shops face competitive collapse. |
| Mobile Fleet Solution Development | DOT-compliant portable systems address on-site preventive maintenance demand from logistics and municipal accounts. |
| Distribution Channel Consolidation | Direct supplier relationships with multi-site operators preempt traditional distributor disintermediation. |
Methodological Framework
Cross-validation between equipment fabricator production data and fleet operator procurement records anchors the qualitative findings in observable transaction patterns. Primary interviews with maintenance directors at logistics fleets, quick-lube chain operations managers, OEM procurement teams, and aftermarket service heads combined with secondary validation from EPA enforcement databases, state environmental agency discharge records, and SEC equipment manufacturer filings. Bottom-up installation counts triangulate against top-down market sizing across the analysis window.
Sensitivity analysis on steel and aluminum input price scenarios shapes the forecast framework across product type, end user scale, technology tier, and service type segmentation dimensions. CAGRs derive from equipment replacement cycle modeling and regulatory compliance deadline alignment. Fleet electrification transition pace and EPA audit enforcement intensity serve as industry-specific forecast inputs throughout the projection horizon.
Underlying assumptions cover stable regulatory enforcement timelines and uninterrupted commodity supply chains, with deviation risk concentrated in tariff exposure on Asian electronic components and accelerated fleet electrification adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Global Street Sweeper Brushes Market
Automotive Services
Automotive E-Tailing Market
Automotive Services
Europe MRO Distribution Market
Automotive Services
Car Wash Franchise Market
Automotive Services
Automotive Quality Service Market
Automotive Services
Vehicles for Disabled Market
Automotive Services
Luxury Car Rental Market
Automotive Services
Auto Leasing Services Market
Automotive Services
Airbag Repair Service Market
Automotive Services
Authorized Car Service Center Market
Automotive Services
Global Automotive Engineering Services Outsourcing Market
Automotive Services
Car Subscription Market
Automotive Services
Car Wash Services Market
Automotive Services
Europe Car Wash Market
Automotive Services
Qatar Car Rental Market
Automotive Services
Driver's License Market