
 Automotive MRO Market | 2026-2036
Automotive MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive MRO Market Outlook
Aging diesel technician expertise is collapsing across North America and Western Europe, forcing fleet operators and independent garages to outsource complex engine rebuilds and emissions-system overhauls. Robert Bosch GmbH leverages its diagnostic equipment portfolio to anchor aftermarket service networks in Germany and the United States. Snapon Incorporated dominates mobile tool distribution and technician training programs, sustaining loyalty among independent repair shops. Toyota Industries Corporation extends its reach through forklift and industrial vehicle MRO, occupying a specialized equipment niche with captive parts availability.
Automotive MRO encompasses the maintenance, repair, and overhaul of vehicles after original sale, spanning scheduled servicing, component replacement, and refurbishment to extend operational life and ensure regulatory compliance; critical specifications include OEM-grade tolerances for brake systems, SAE viscosity grades for lubricants, and OBD-II diagnostic protocols for fault detection. Spare parts and lubricants command the largest product-type revenue pools, though tools and equipment generate higher margins through recurring calibration and replacement cycles. Fleet operators represent the most structured customer segment, with long-term service contracts consolidating demand around workshop and mobile delivery models while independent garages fragment procurement across e-commerce and traditional wholesale channels.
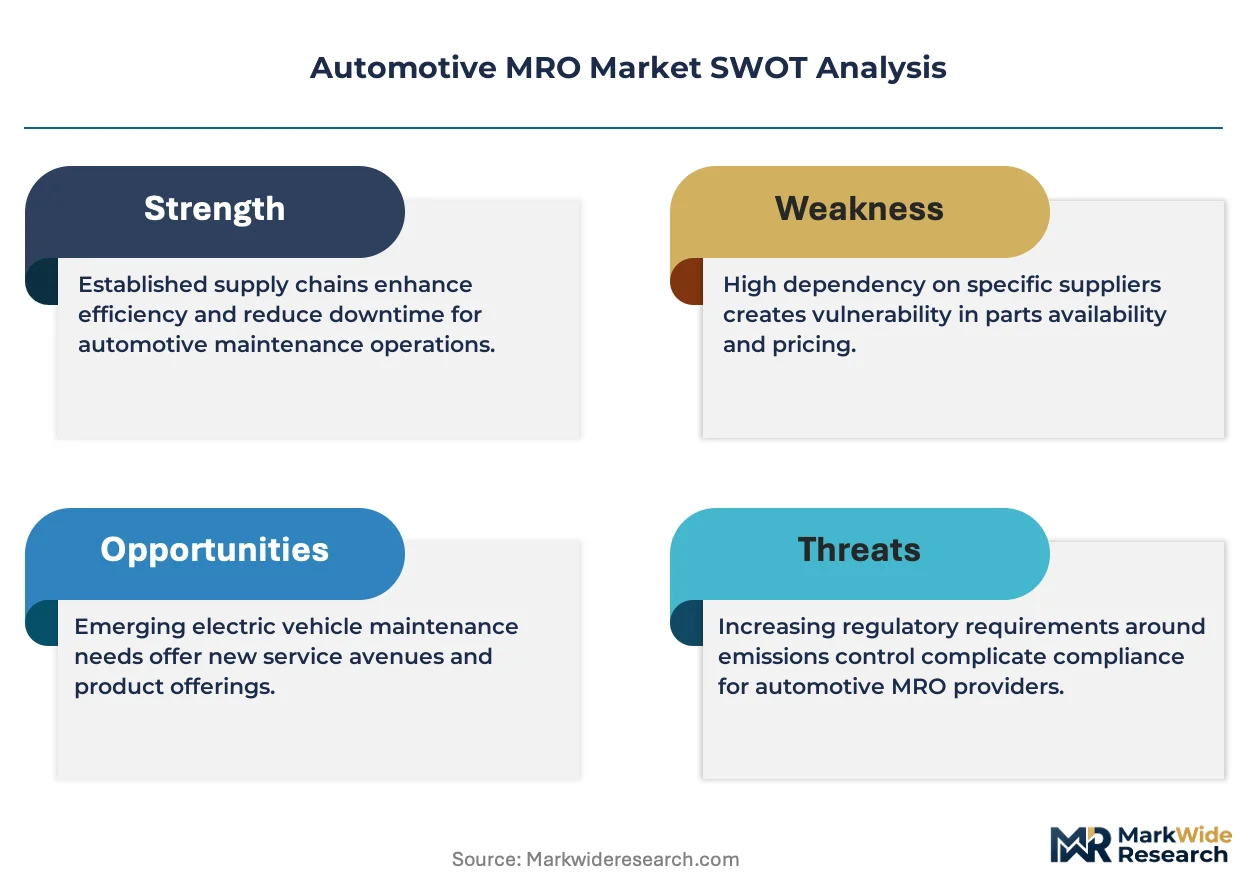
The U.S. NHTSA enforces Federal Motor Vehicle Safety Standards that mandate specific replacement part performance for brake and steering systems, while the EPA regulates refrigerant handling and emissions component integrity through Section 609 certification requirements. Germany's KBA enforces periodic technical inspection frameworks that create predictable demand cycles for inspection and replacement services. Stakeholders must monitor how battery-electric vehicle penetration reshapes technician skill requirements and whether aftermarket access to EV powertrain data becomes restricted through manufacturer-controlled digital service platforms.
Market Dynamics
The Automotive MRO market is being fundamentally restructured by the collapse of aging diesel technician expertise across North America and Western Europe, forcing fleet operators to outsource complex engine rebuilds and emissions-system overhauls to specialized service networks.
Growth Catalysts
- EPA Section 609 Certification Mandates:The EPA's refrigerant handling requirements create recurring training and equipment upgrade cycles for service workshops, sustaining demand for compliant recovery machines and technician credentialing programs.
- Commercial Fleet Preventive Maintenance Expansion:Fleet operators are consolidating procurement around long-term service contracts that bundle scheduled maintenance, mobile delivery, and predictive diagnostics to minimize vehicle downtime.
- Germany's KBA Periodic Inspection Framework:The KBA's technical inspection cycles generate predictable replacement demand for brake systems, steering components, and exhaust aftertreatment hardware across the country's dense commercial vehicle population.
Market Restraints
- Specialized Technician Labor Scarcity:The retirement of experienced diesel mechanics without adequate replacement pipeline creates bottlenecks for complex powertrain repairs and emissions system overhauls.
- OEM-Controlled Diagnostic Access:Manufacturers are restricting aftermarket access to proprietary diagnostic protocols and powertrain calibration data, limiting independent garage capabilities.
- Input Cost Volatility in Specialized Lubricants:Base oil and additive supply fluctuations compress margins for high-viscosity commercial vehicle lubricants formulated to SAE J300 specifications.
Strategic Opportunities
- Battery-Electric Vehicle Powertrain Service Gap:The absence of standardized high-voltage technician training and safety protocols creates first-mover advantage for service networks developing EV-specific maintenance capabilities.
- Digital Service Platform Integration:Convergence of telematics data streams with predictive maintenance algorithms enables remote fault detection and just-in-time parts positioning before component failure.
- Industrial Vehicle MRO Specialization:Forklift and material handling equipment segments remain underserved by traditional automotive service networks, offering captive parts and service contract opportunities.
Industry Challenges
- High-Voltage Safety Certification Timelines:Technician credentialing for battery-electric vehicle systems requires substantial capital investment in insulated tooling and facility upgrades alongside extended training periods.
- Legacy Diagnostic Equipment Obsolescence:Independent garages face write-downs on OBD-II scan tools as manufacturers encrypt powertrain data behind subscription-based digital service platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive MRO Market |
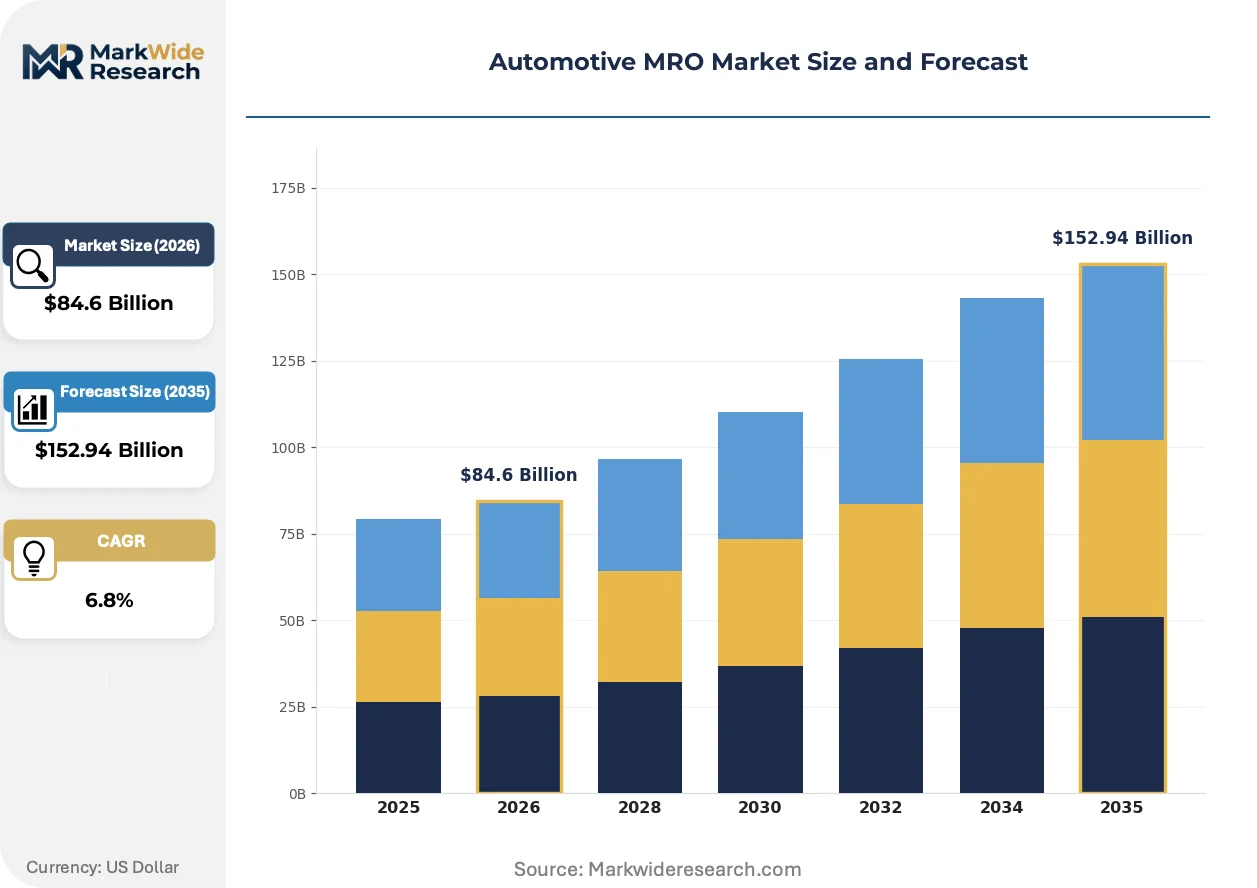
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $152.94 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
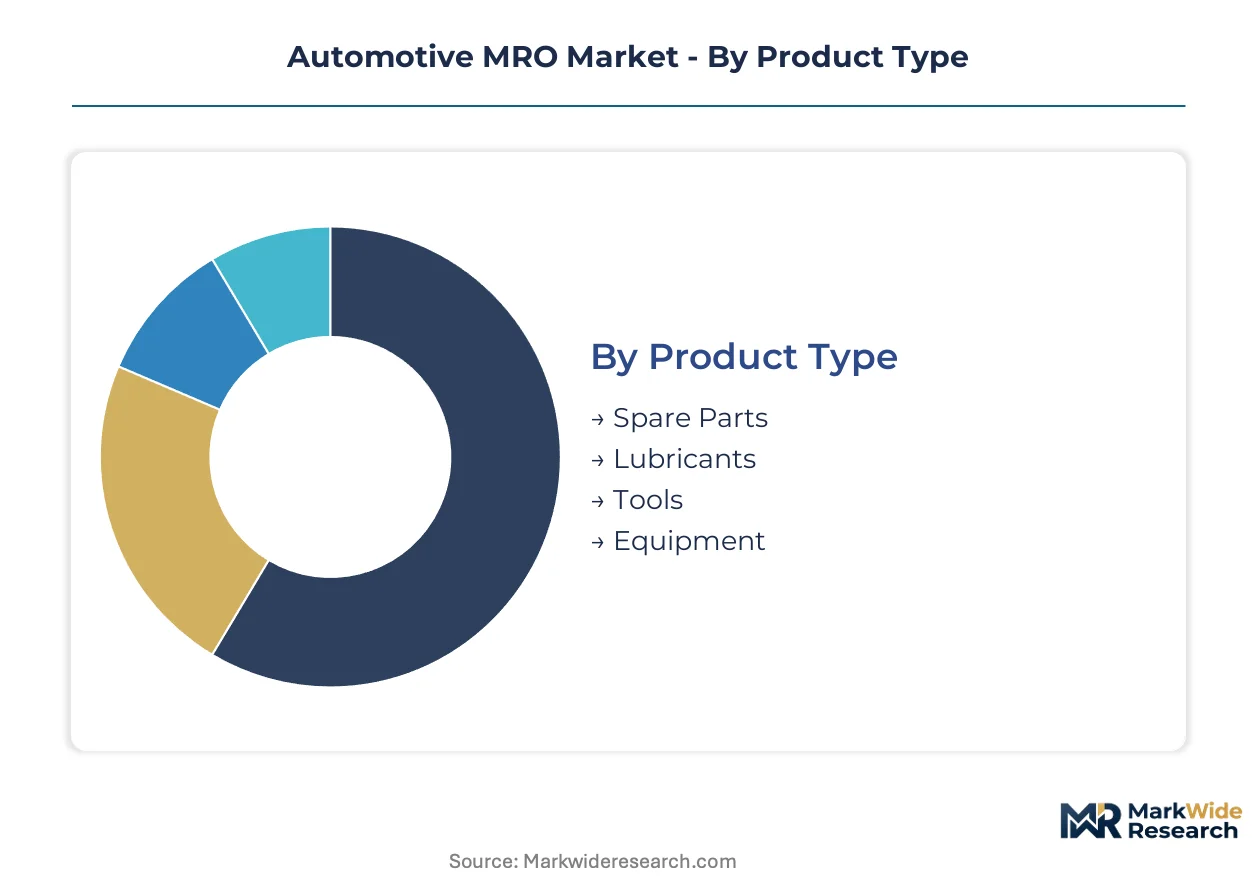
| Segmentation | Product Type: Spare Parts, Lubricants, Tools, Equipment Customer Type: Fleet Operators, Dealerships, Independent Garages, Aftermarket Suppliers Service Type: Maintenance Services, Repair Services, Inspection Services, Replacement Services Delivery Model: On-site Service, Mobile Service, Workshop Service, E-commerce |
| Companies Covered | Honeywell International Inc, General Electric Company, Robert Bosch GmbH, ZF Friedrichshafen AG, Bridgestone Corporation, Snapon Incorporated, Toyota Industries Corporation, Motorcraft, Tenneco Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive MRO Market Strategic Shifts
Diagnostic equipment is miniaturizing and embedding directly into vehicle telematics architectures, compressing the traditional workshop visit model while forcing service providers to develop remote-first maintenance capabilities.
Portable emissions measurement systems are miniaturizing from laboratory-grade analyzers to handheld devices capable of roadside NOx and particulate verification. Fleet compliance officers in California and Texas are deploying these units for spot-checking older diesel inventories. This compression is enabling real-time regulatory enforcement and shifting liability exposure toward operators with non-compliant hardware.
The EPA's tightening enforcement of Federal Motor Vehicle Safety Standards for replacement brake and steering components is mandating OEM-grade performance certification for aftermarket suppliers. This regulatory pressure is consolidating procurement around verified part networks and disqualifying uncertified manufacturers from fleet operator approved vendor lists. Independent garages in the United States are responding by narrowing supplier relationships to Tier-1 distributors with documented traceability.
Buyer concentration among national fleet operators is compressing procurement cycles and demanding outcome-based service level agreements with guaranteed uptime penalties. Traditional time-and-materials billing is losing share to fixed-price maintenance contracts bundled with telematics monitoring. This shift is most visible in the long-haul trucking segment, where operators with thousand-plus unit fleets now specify predictive parts replacement schedules based on engine duty cycle data rather than mileage intervals.
Automotive MRO Market Segmentation
Automotive MRO procurement patterns diverge sharply across customer archetypes, with fleet operators consolidating through long-term contracts while independent garages fragment demand across digital and traditional channels. Understanding these segment boundaries clarifies where margin pools concentrate and which service models capture sustainable pricing power.
Product Type:
Channel mix varies dramatically by product category—spare parts and lubricants flow predominantly through wholesale distributors and e-commerce platforms, while tools and equipment concentrate around specialized distributors with calibration service capabilities.
- Spare Parts:Brake rotors, steering linkages, and emissions aftertreatment hardware must meet OEM-grade tolerances under NHTSA Federal Motor Vehicle Safety Standards. Fleet operators in the United States and Germany are consolidating procurement around Tier-1 distributors with documented traceability to minimize liability exposure from non-compliant components.
- Lubricants:Commercial vehicle engine oils and transmission fluids are formulated to SAE J300 viscosity specifications with additive packages for extended drain intervals. Demand concentrates among long-haul trucking fleets operating in Texas and California, where extreme duty cycles and EPA emissions compliance requirements drive premium product selection.
- Tools:Diagnostic scan tools, torque wrenches, and specialized service equipment generate recurring revenue through calibration cycles and software updates. Mobile tool distributors dominate independent garage penetration in North America.
- Equipment:Vehicle lifts, alignment racks, and refrigerant recovery machines require substantial capital investment and facility footprint. Workshop service networks in Germany prioritize equipment standardization across multi-site operations.
By volume, Spare Parts leads. By growth pace, Tools is expanding most quickly as diagnostic capabilities embed into connected vehicle architectures.
Customer Type:
Cost tier stratification separates this category—fleet operators command volume discounts and outcome-based pricing, while independent garages absorb spot-market volatility with thinner margins.
- Fleet Operators:National trucking and logistics companies with thousand-plus unit inventories negotiate fixed-price maintenance contracts bundled with telematics monitoring. These stakeholders specify predictive parts replacement based on engine duty cycle data rather than mileage intervals, compressing procurement cycles.
- Dealerships:Authorized service networks retain captive demand for warranty repairs and software updates, though their cost structure limits competitiveness on out-of-warranty powertrain overhauls. Manufacturer-controlled diagnostic access reinforces their position for complex electronic repairs.
- Independent Garages:Small and mid-sized repair shops fragment procurement across e-commerce platforms, traditional wholesale channels, and mobile tool distributors. Labor scarcity for diesel emissions system repairs is forcing many to outsource complex overhauls to specialized service networks.
- Aftermarket Suppliers:Tier-1 and Tier-2 manufacturers of replacement components compete for placement on fleet-approved vendor lists, with EPA and KBA certification requirements consolidating procurement around verified part networks.
By revenue concentration, Fleet Operators dominate. By channel fragmentation, Independent Garages show the steepest expansion trajectory as digital procurement platforms erode traditional wholesale relationships.
Service Type:
Application context determines service scheduling—regulatory inspection cycles create predictable demand spikes, while unscheduled repairs generate emergency procurement with premium pricing.
- Maintenance Services:Scheduled oil changes, filter replacements, and preventive inspections follow manufacturer-prescribed intervals. Fleet operators in Germany align these cycles with KBA periodic technical inspection frameworks to minimize downtime.
- Repair Services:Unscheduled component replacement and powertrain overhauls respond to failure events or telematics-generated fault codes. Technician scarcity for complex diesel engine rebuilds is pushing repair demand toward specialized networks with certified mechanics.
- Inspection Services:Mandatory safety and emissions verification creates recurring revenue pools tied to regulatory calendars. California Air Resources Board enforcement programs sustain demand for roadside emissions verification capabilities.
- Replacement Services:Component swap programs for brake systems, steering hardware, and exhaust aftertreatment equipment prioritize rapid turnaround. Fleet operators specify guaranteed uptime penalties for delayed completion.
By frequency, Maintenance Services leads. By margin expansion, Replacement Services is gaining share fastest as outcome-based contracts replace time-and-materials billing.
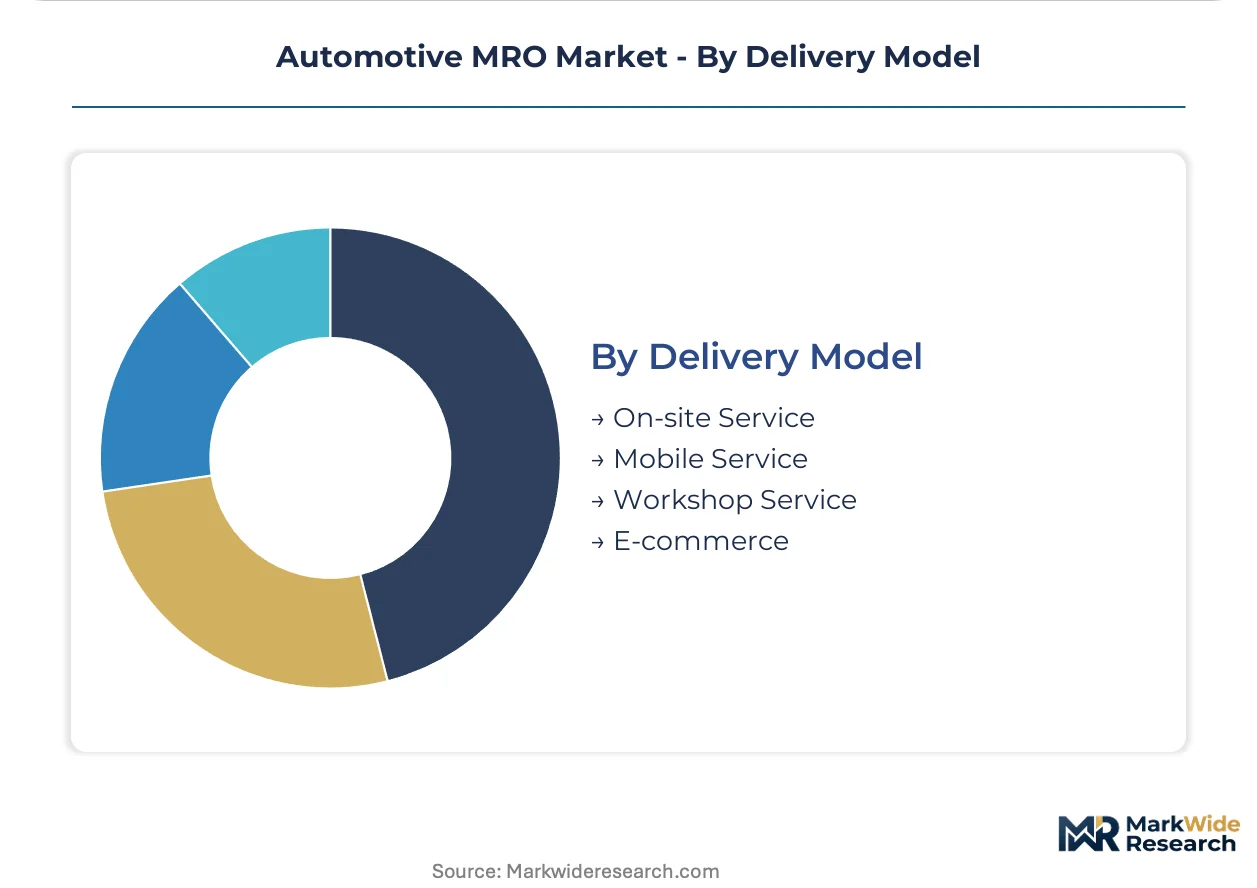
Delivery Model:
Geography and customer density shape delivery economics—urban clusters support workshop consolidation, while dispersed operations require mobile service penetration.
- On-site Service:Dedicated maintenance facilities at fleet depots and distribution centers enable rapid turnaround for high-rotation vehicle inventories. Capital intensity limits this model to operators with sufficient unit density.
- Mobile Service:Technician teams equipped with portable diagnostic and repair capabilities deploy directly to vehicle locations. This model captures share among distributed fleet operations and emergency repair scenarios where towing costs exceed service premiums.
- Workshop Service:Fixed-location service bays with heavy equipment capabilities handle complex overhauls requiring lifts, alignment systems, and emissions testing hardware. Germany's dense autobahn network sustains substantial workshop volumes.
- E-commerce:Digital platforms for parts procurement and service scheduling are compressing traditional distributor margins while expanding independent garage access to specialized components. EPA Section 609 certification requirements for refrigerant handling create friction for pure digital models.
By installed base, Workshop Service leads. By share gain, Mobile Service is climbing the fastest as fleet operators prioritize uptime over facility convenience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EPA anchors the dominant geography through refrigerant handling mandates and emissions enforcement that sustain workshop certification cycles across the United States. Fleet operators in Texas and California drive preventive maintenance adoption under tightening compliance frameworks.
United States
Long-haul trucking fleets operating across the I-10 and I-40 corridors consolidate procurement around predictive maintenance contracts. The EPA's Section 609 certification requirements create recurring demand for compliant recovery equipment. Dallas-Fort Worth anchors substantial workshop volumes serving cross-border commercial traffic.
Germany
Dense commercial vehicle populations along the autobahn network sustain inspection-driven replacement cycles. The KBA enforces periodic technical inspection frameworks that generate predictable demand for brake and steering components. Stuttgart and Munich concentrate specialized service networks handling complex powertrain overhauls.
China
Expanding logistics fleets in the Yangtze River Delta and Pearl River Delta drive aftermarket parts consumption. The Ministry of Ecology and Environment tightens diesel emissions standards for commercial vehicles in major metropolitan zones. Shanghai anchors diagnostic equipment distribution serving both domestic and export-oriented service networks.
Japan
Aging commercial vehicle stocks in the Kanto and Kansai regions sustain refurbishment demand for industrial equipment. METI promotes technician training programs addressing high-voltage safety requirements for emerging electric vehicle fleets. Nagoya's manufacturing corridor concentrates captive parts distribution for material handling equipment.
India
Commercial vehicle operators in Maharashtra and Gujarat expand preventive maintenance programs to minimize downtime on national highway corridors. The Central Pollution Control Board enforces emissions compliance deadlines for older diesel fleets. Mumbai-Pune industrial belt anchors independent garage networks fragmenting procurement across digital platforms.
Automotive MRO Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the upper layer controlling diagnostic platforms and captive parts networks while mid-scale operators compete on service velocity. The structure rewards scale in certification-heavy segments and proximity in emergency repair scenarios. Strategic archetypes include integrated system suppliers anchoring aftermarket networks, mobile tool distributors capturing independent garage loyalty, and industrial equipment specialists occupying captive service niches. Consolidation through diagnostic data partnerships and geographic expansion of mobile service capabilities represent dominant competitive vectors.
Within the integrated system supplier tier, Robert Bosch GmbH and ZF Friedrichshafen AG exemplify archetypes leveraging diagnostic equipment portfolios to anchor service network relationships. Snapon Incorporated occupies a distinct position among mobile tool distributors, sustaining technician engagement through training program integration. Toyota Industries Corporation represents the industrial equipment specialist archetype, with its corporate structure suggesting embedded aftermarket capabilities in material handling segments.
| Leading Market Players |
|---|
| Honeywell International Inc |
| General Electric Company |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Bridgestone Corporation |
| Snapon Incorporated |
| Toyota Industries Corporation |
| Motorcraft |
| Tenneco Inc |
| Others |
Value Chain & Pricing Dynamics
Synthetic lubricant formulations displacing mineral-based products in commercial fleet applications simultaneously shift procurement geography toward additive manufacturing clusters in the United States and Germany while compressing margin structures for distributors unable to secure volume-tier pricing with base oil suppliers.
Pricing Analysis
Price spreads between workshop service networks in Germany and independent garages in India exceed threefold for equivalent brake system overhauls, reflecting labor cost differentials and certification overhead. Pricing stratifies across OEM-certified, Tier-1 verified, and uncertified economy tiers, with fleet operators in Texas and California commanding volume discounts through predictive maintenance contracts. Cost compression in the independent garage segment intensifies as mobile tool distributors consolidate procurement leverage. Fleet operators exhibit lowest price sensitivity due to uptime guarantees, while small independent garages absorb spot-market volatility with minimal bargaining power.
Supply Chain Analysis
Inventory buffers for emissions aftertreatment hardware have compressed from twelve-week to six-week cycles as fleet operators adopt just-in-time replacement scheduling tied to telematics data. Manufacturing concentrates in Germany, China, and Mexico, with specialized diagnostic equipment production anchored in Stuttgart and Shanghai. The supply chain draws from rare earth elements for catalytic substrates, high-grade steel for brake components, and lithium compounds for emerging EV service tooling. Single-source vulnerability persists for EPA-compliant refrigerant recovery machines. Distribution runs through Tier-1 distributors with calibration service capabilities, bypassing traditional wholesale channels for certified components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-electric vehicle powertrain service capabilities threaten to displace incumbent diesel-focused networks unless stakeholders secure high-voltage technician credentials and insulated tooling infrastructure before regulatory mandates accelerate.
For Market Incumbents: Compound diagnostic platform advantages by embedding telematics integration into subscription-based service offerings, locking fleet operators into predictive maintenance ecosystems. Acquire specialized EV training providers in Germany and the United States to preempt technician certification bottlenecks. Backward integration into remanufactured parts production captures margin from emissions aftertreatment hardware replacement cycles. For New Entrants and Emerging Players: EPA Section 609 fast-track certification programs offer immediate service network access without multi-year apprenticeship requirements. Target mobile service deployment in India's Maharashtra-Gujarat corridor where fleet density exceeds workshop capacity. Lead with refrigerant handling compliance bundled with roadside emissions verification to capture CARB enforcement-driven demand. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mobile tool distributors possessing captive technician relationships but lacking EV transition roadmaps. Five-to-ten year viability hinges on diagnostic data access rights rather than physical service footprint. Monitor OEM encryption of OBD-II protocols as the inflection signal determining independent garage survival.| Strategic Initiative | Industry Significance |
|---|---|
| High-Voltage Technician Certification Investment | EPA and KBA alignment on EV safety standards creates first-mover credentialing advantage for service networks. |
| Telematics Platform Integration | Predictive fault detection compresses procurement cycles and locks fleet operators into proprietary diagnostic ecosystems. |
| Remanufactured Parts Network Expansion | NHTSA certification requirements for brake and steering components consolidate procurement around verified remanufacturing facilities. |
| Mobile Service Capability Buildout | Distributed fleet operations in Texas and California prioritize uptime over workshop convenience, rewarding rapid-response deployment. |
| Diagnostic Data Access Partnership | Manufacturer-controlled OBD-II encryption threatens independent garage viability, making data rights negotiations critical for survival. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EPA enforcement databases, KBA inspection frameworks, and commercial vehicle registration data. Interviews with fleet maintenance directors, aftermarket distributor procurement leads, diagnostic equipment engineers, and independent garage operators provided operational validation. Trade data from U.S. Census Bureau and Eurostat complemented SEC filings from listed component manufacturers. Bottom-up service volume estimates triangulated against top-down fleet size and utilization assumptions.
Segmentation dimensions modeled span product type, customer archetype, service category, and delivery model across the projection horizon. CAGRs derived from fitted growth curves applied to baseline service event frequencies and parts replacement rates. Industry-specific inputs include diesel fleet age distributions, EV penetration trajectories, and regulatory inspection calendar densities. Regional weighting reflects commercial vehicle population concentration along the I-10 corridor, German autobahn networks, and India's Golden Quadrilateral highway system.
Decision-makers should treat outputs as directional under sustained EPA emissions enforcement and stable fleet utilization assumptions; material deviation in electrification pace or technician training pipeline would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Automatic Tire Changer Market
Automotive Services
Garage and Service Station Service Market
Automotive Services
Automotive Garage Equipment Market
Automotive Services
Automotive Digital Assistant Market
Automotive Services
Auto Leasing Services Market
Automotive Services
Driver's License Market
Automotive Services
United States Automotive Service Market
Automotive Services
Automotive Performance Tuning and Engine Remapping Services Market
Automotive Services
Motorcycle Rental Market
Automotive Services
Vehicle Roadside Assistance Market
Automotive Services
Singapore Car Rental Market
Automotive Services
Automotive Register Market
Automotive Services
Automotive Remanufacturing Market
Automotive Services
Limousine Car Hire or Rental Market
Automotive Services
Automotive Quality Service Market
Automotive Services
Vehicle Subscription Market