
 Auto Leasing Services Market | 2026-2036
Auto Leasing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Auto Leasing Services Market Analysis
North American captive finance subsidiaries is pivoting toward subscription-style mobility products. BMW Financial Services dominates European premium leasing through captive control over residual value forecasting. Toyota Financial Services anchors Asian fleet operations with manufacturer-backed maintenance leasing programs.
Auto leasing services constitute contractual vehicle usage arrangements where lessors retain asset ownership while lessees pay for depreciation plus financing charges over fixed terms, typically incorporating mileage limits, residual value guarantees, and early termination clauses. Operational leasing absorbs the fastest demand growth as corporations outsource fleet management, maintenance, and disposal risk to specialized providers. Financial leasing sustains margin concentration among commercial borrowers seeking ownership transfer options and tax-advantaged equipment financing structures.
The US Consumer Financial Protection Bureau oversees lease disclosure standards under Regulation M, while the EU's Consumer Credit Directive harmonizes early termination protections across member states. China's MIIT and SAMR jointly enforce GB standards for connected vehicle data privacy in leased assets. Stakeholders must monitor how residual value algorithms adapt to accelerated EV depreciation curves and battery health verification requirements.
Market Dynamics
The US Federal Reserve's interest rate regime is compressing lease affordability margins and forcing residual value recalibration across all vehicle segments, with captive finance arms absorbing the largest repricing pressure.
Growth Catalysts
- Corporate Fleet Outsourcing:Logistics operators in Germany and the Netherlands are transferring entire vehicle pools to operational lessors to eliminate balance-sheet asset weight and maintenance liability.
- REACH Compliance Deadlines:European Union environmental mandates on end-of-life vehicle processing are accelerating lessor investment in closed-loop refurbishment infrastructure.
- Telematics Integration:Embedded connected vehicle platforms are automating mileage verification and enabling dynamic pricing adjustments mid-contract.
Market Restraints
- Lithium-Ion Battery Volatility:Raw material price swings for cobalt and nickel are destabilizing residual value forecasting for electric vehicle lease portfolios.
- Regional Production Concentration:Semiconductor supply remains concentrated in Taiwan and South Korea, creating delivery uncertainty for lessor fleet orders.
- GDPR Data Architecture:European Union privacy requirements impose costly technical retrofitting on legacy telematics systems tracking driver behavior.
Strategic Opportunities
- Indian Commercial Vehicle Leasing:India's logistics sector shows minimal captive finance penetration, creating white space for operational lease entrants with maintenance bundling.
- Battery Subscription Unbundling:Chinese EV manufacturers are separating battery costs from vehicle leases, enabling lower monthly payments and residual risk transfer.
- US Inflation Reduction Act Credits:Federal tax incentives for commercial clean vehicle acquisition are expanding qualified lease customer pools in North American fleet segments.
Industry Challenges
- Residual Value Algorithm Talent:Lessors face acute scarcity of data scientists capable of modeling accelerated electric vehicle depreciation curves against battery health degradation.
- Multi-Jurisdiction Compliance:Cross-border fleet operators must reconcile divergent early termination protections under the EU Consumer Credit Directive with US Regulation M disclosure frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Auto Leasing Services Market |
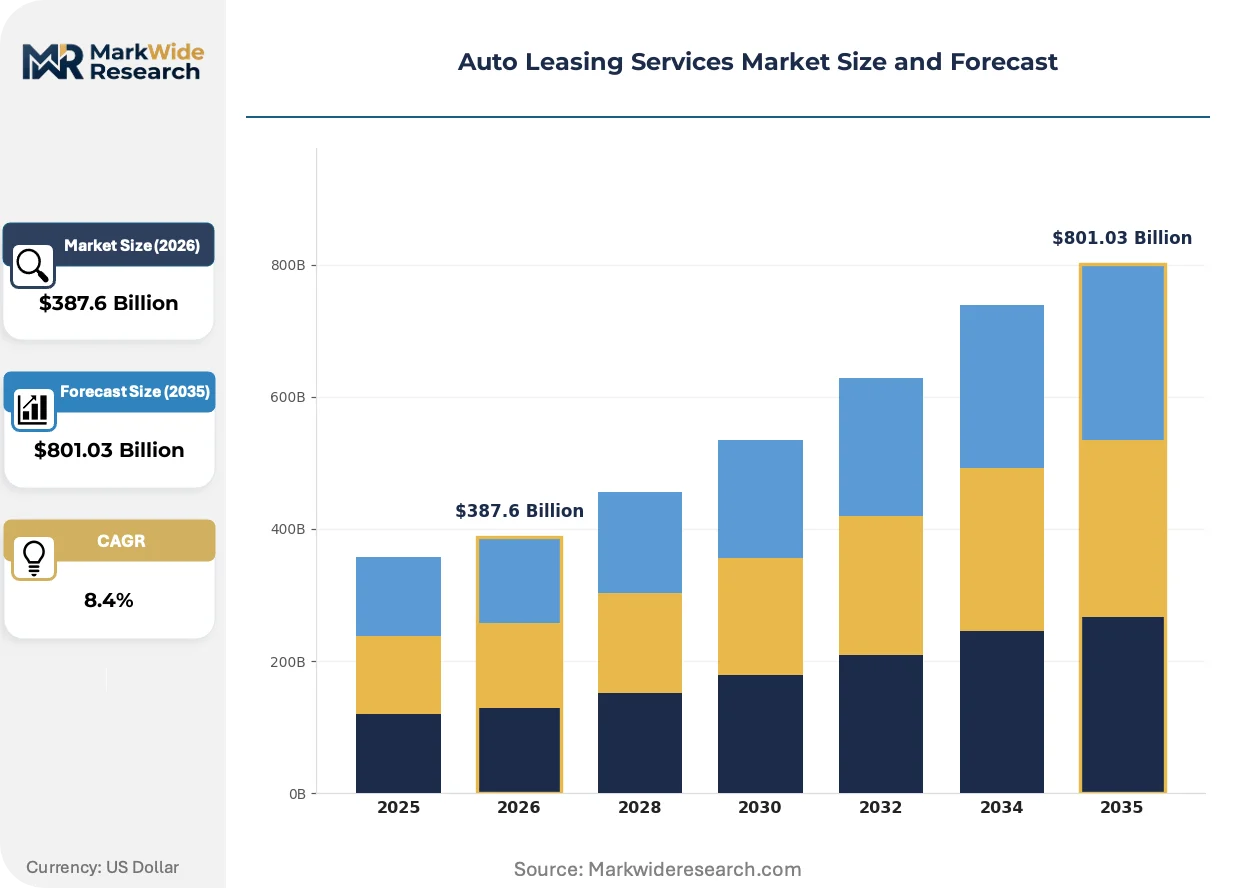
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $801.03 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Operational Leasing, Financial Leasing, Maintenance Leasing, Closed-End Leasing Customer Type: Private Individuals, Small Businesses, Corporations, Government Agencies Vehicle Type: Passenger Cars, SUVs, Trucks, Vans Lease Duration: Short-Term, Medium-Term, Long-Term, Flexible Leasing |
| Companies Covered | Honda Financial Services, Kia Finance America, Ally Financial, Audi Financial Services, BMW Financial Services, Volkswagen Financial Services, Hyundai Capital America, GM Financial, Toyota Financial Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Auto Leasing Services Market Emerging Trajectories
Connected vehicle data streams and battery health telemetry are reconstituting how lessors price risk, manage asset lifecycles, and structure end-of-term options across passenger and commercial segments.
Artificial intelligence-driven residual value forecasting is automating lease pricing adjustments in real-time based on regional market depreciation, vehicle condition telemetry, and macroeconomic indicators. Fleet management companies in the United States and United Kingdom are deploying these systems to compress quote-to-contract timelines from days to hours. The technology is automating manual underwriting processes that previously required extensive human appraiser intervention.
The EU's Corporate Sustainability Reporting Directive now mandates granular disclosure of leased asset emissions and circular economy performance across corporate vehicle fleets. Lessors serving European multinational clients must retrofit reporting infrastructure to capture Scope 3 data from subcontracted maintenance and disposal partners. Commercial lease contracts in Germany and France are increasingly incorporating CSRD-aligned sustainability clauses with financial penalties for non-compliance.
Usage-based insurance bundling is displacing traditional fixed-premium fleet coverage as telematics-enabled risk scoring matures. Large logistics operators in Canada and Australia are negotiating integrated lease-insurance packages where monthly payments fluctuate with actual driver safety metrics. This convergence is most visible in long-haul trucking segments where per-mile cost transparency directly impacts route profitability calculations.
Auto Leasing Services Market Segmentation
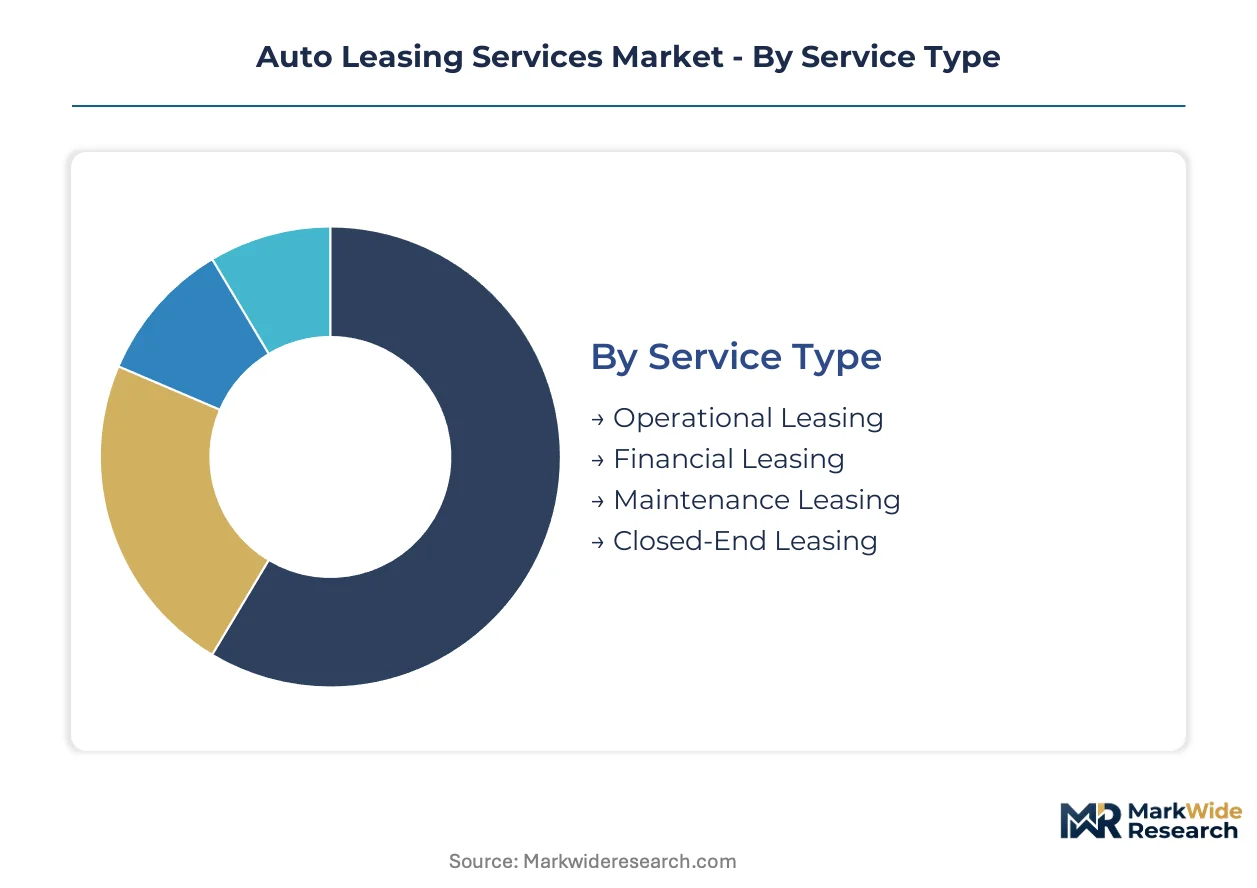
Auto leasing services fragment across service models, customer profiles, vehicle categories, and contract durations. Each dimension carries distinct risk-weighting methodologies and capital deployment requirements that shape lessor portfolio construction.
Service Type:
Buyers select service types based on balance-sheet treatment preferences and residual risk tolerance.
- Operational Leasing:Full-service contracts bundle asset management, maintenance scheduling, and disposal logistics under fixed monthly payments. Corporations in Germany and the Netherlands are migrating entire fleet pools to operational lessors to eliminate maintenance liability and asset-weighted balance sheets.
- Financial Leasing:Structures emphasize ownership transfer options with tax-advantaged equipment financing for commercial borrowers. Financial leasing sustains margin concentration among borrowers seeking depreciation deductions and end-of-term asset acquisition rights.
- Maintenance Leasing:Manufacturer-backed programs integrate scheduled servicing and component replacement into base payment structures. Toyota Financial Services anchors Asian fleet penetration through bundled maintenance offerings that reduce total cost of ownership uncertainty.
- Closed-End Leasing:Fixed residual value guarantees protect lessees from depreciation volatility at contract termination. Closed-end structures dominate North American consumer leasing where captives absorb residual risk through captive finance subsidiary balance sheets.
Operational leasing leads on scale; maintenance leasing leads on momentum.
Customer Type:
Customer segmentation reflects divergent contract complexity, credit underwriting depth, and fleet management service requirements.
- Private Individuals:Retail lessees prioritize monthly payment predictability and mileage flexibility over ownership equity accumulation. BMW Financial Services dominates European premium retail leasing through residual value forecasting precision that compresses consumer qualification friction.
- Corporations:Large fleet operators demand telematics integration, sustainability reporting alignment, and cross-border contract standardization. The EU's Corporate Sustainability Reporting Directive now mandates granular leased asset emissions disclosure from corporate vehicle fleets.
- Small Businesses:Mid-market entities seek operational lease structures that preserve credit lines for core business investment. Small business demand concentrates in China's tier-one cities where domestic EV manufacturers bundle leasing with battery subscription unbundling.
- Government Agencies:Public sector procurement emphasizes total cost of ownership transparency and domestic content requirements. US Inflation Reduction Act commercial clean vehicle credits are expanding qualified lease customer pools in North American public fleet segments.
Corporations lead on scale; small businesses lead on momentum.
Vehicle Type:
Vehicle classification determines residual value algorithm complexity and depreciation curve steepness.
- Passenger Cars:Sedan and hatchback leasing maintains established residual forecasting models with mature secondary market liquidity. China's MIIT and SAMR enforce GB standards for connected vehicle data privacy that reshape passenger car lease contract telemetry clauses.
- SUVs:Sport utility vehicles command premium monthly payments reflecting higher acquisition costs and sustained resale value performance. SUVs absorb disproportionate demand share in North American captive finance portfolios.
- Trucks:Commercial trucking leases integrate usage-based insurance bundling where telematics-enabled risk scoring displaces fixed-premium coverage. Canadian and Australian logistics operators negotiate integrated lease-insurance packages with per-mile cost transparency.
- Vans:Last-mile delivery vehicles face accelerated depreciation from high-utilization duty cycles and rapid electrification transitions. Van lessors confront lithium-ion battery volatility as cobalt and nickel price swings destabilize residual value forecasting for electric van portfolios.
Passenger cars lead on scale; trucks lead on momentum.
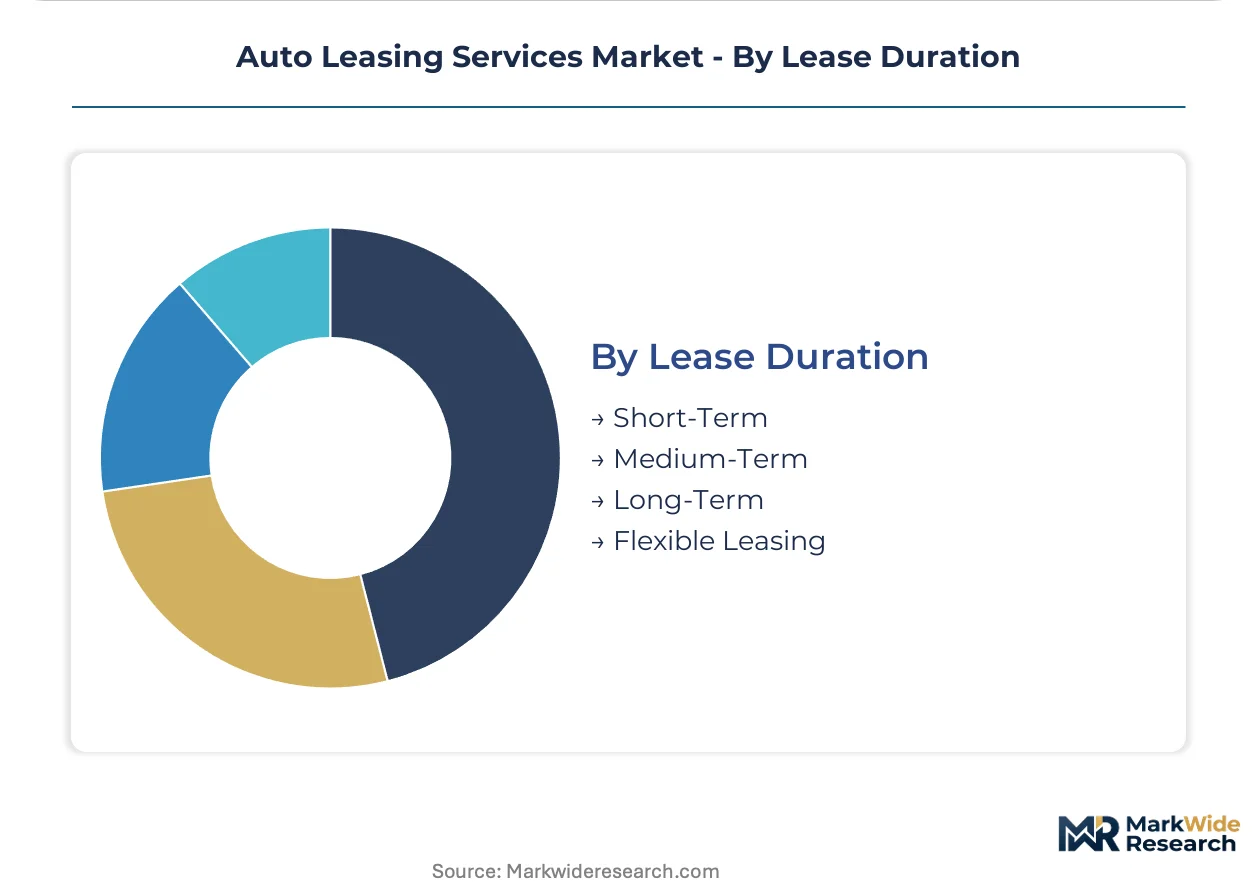
Lease Duration:
Duration selection balances payment affordability against flexibility premiums and early termination penalty exposure.
- Short-Term:Sub-12-month structures serve project-based fleet requirements and seasonal demand spikes. Short-term contracts command premium per-month rates that reflect elevated remarketing frequency and administrative overhead.
- Medium-Term:24-to-36-month contracts optimize the intersection of depreciation curve steepness and lessee commitment horizon. Medium-term structures dominate European premium leasing where BMW Financial Services calibrates residual guarantees.
- Long-Term:48-to-60-month agreements minimize monthly payments through extended depreciation schedules. Long-term leasing sustains penetration among US Federal Reserve interest rate environments where monthly affordability thresholds constrain qualification.
- Flexible Leasing:Mileage-adjustable and early-exit provisions accommodate demand uncertainty in volatile logistics markets. Telematics integration enables dynamic pricing adjustments mid-contract as embedded connected vehicle platforms automate mileage verification.
Medium-term leads on scale; flexible leasing leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's operational leasing penetration exceeds United States consumer-focused structures, while China's battery-subscription bundling creates distinct contract economics unavailable in Western markets.
United States
Fleet managers at logistics companies expand lease portfolios to preserve capital flexibility amid Federal Reserve interest rate volatility. The US Consumer Financial Protection Bureau oversees lease disclosure standards under Regulation M, compressing quote-to-contract timelines. Captive finance subsidiaries in Detroit and Chicago pivot toward subscription-style mobility products with integrated telematics.
Germany
Logistics operators transfer entire vehicle pools to operational lessors to eliminate balance-sheet asset weight. REACH compliance deadlines on end-of-life vehicle processing accelerate lessor investment in closed-loop refurbishment infrastructure. The KBA enforces stringent type-approval standards that reshape residual value forecasting for electric fleet assets in Bavaria and North Rhine-Westphalia.
China
Domestic EV manufacturers in Shanghai and Shenzhen bundle leasing with battery subscription services to lower monthly payments. The MIIT and SAMR jointly enforce GB standards for connected vehicle data privacy in leased assets. Tier-one cities concentrate demand where telematics-enabled dynamic pricing adjusts mid-contract based on actual mileage verification.
United Kingdom
Corporate fleet operators demand sustainability reporting alignment with the EU's Corporate Sustainability Reporting Directive despite post-Brexit regulatory divergence. Usage-based insurance bundling displaces fixed-premium coverage as telematics-enabled risk scoring matures. Fleet management companies in London and Birmingham deploy artificial intelligence-driven residual value forecasting to compress underwriting timelines.
India
The logistics sector shows minimal captive finance penetration, creating white space for operational lease entrants with maintenance bundling. The RBI regulates non-banking financial company leasing structures through prudential norms on asset classification. Maharashtra and Karnataka host emerging fleet hubs where commercial vehicle lessors pilot battery-swapping infrastructure for electric last-mile delivery vans.
Auto Leasing Services Market Vendor Landscape
North American captive finance arms anchor one tier; European manufacturer-backed subsidiaries hold premium residual value forecasting capabilities. The vendor base concentrates around automotive OEM financial services divisions rather than independent lessors, creating consolidated pricing power in passenger segments. Three archetypes dominate: manufacturer captives with residual control, bank-affiliated lessors with balance-sheet scale, and fleet management specialists with telematics integration. Competitive moves center on battery health verification technology licensing and cross-border fleet contract standardization.
Within the manufacturer-captive tier, BMW Financial Services and Toyota Financial Services exemplify divergent regional strategies. BMW Financial Services occupies a position in European premium leasing through precision residual value guarantees that compress consumer qualification friction. Toyota Financial Services anchors Asian fleet operations with manufacturer-backed maintenance leasing programs that reduce total cost of ownership uncertainty. Ally Financial represents the bank-affiliated archetype with balance-sheet capacity to absorb residual risk across multiple vehicle segments without OEM tethering.
| Leading Market Players |
|---|
| Honda Financial Services |
| Kia Finance America |
| Ally Financial |
| Audi Financial Services |
| BMW Financial Services |
| Volkswagen Financial Services |
| Hyundai Capital America |
| GM Financial |
| Toyota Financial Services |
| Others |
Supply Flow & Price Mechanics
Captive finance integration through manufacturer-owned subsidiaries anchors pricing power by internalizing residual value risk and compressing bid-ask spreads between fleet procurement and secondary market disposal. This vertical control over asset lifecycles allows captives like BMW Financial Services and Toyota Financial Services to price below independent lessors while protecting margins through proprietary depreciation algorithms.
Pricing Analysis
Capacity additions in China's tier-one cities are reshaping price floors as domestic EV manufacturers bundle battery subscription services with base vehicle leases. Pricing stratifies across premium, standard, and economy tiers based on residual guarantee strength and telematics integration depth. Cost compression in operational leasing is intensifying because logistics operators demand per-mile transparency and dynamic mid-contract adjustments. Small businesses in India's logistics corridors exhibit highest price sensitivity, while European corporate fleets prioritize total cost of ownership predictability over monthly payment minimization.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale fleet demand through captive finance subsidiaries, while independent lessors rely on dealer networks and telematics-enabled remarketing platforms. Semiconductor supply concentrates in Taiwan and South Korea, with battery cell production anchored in China and South Korea. Raw material dependencies on cobalt, nickel, and lithium carbonate expose lessors to commodity volatility that destabilizes residual value forecasting. Single-source vulnerability in Taiwanese chip fabrication creates delivery uncertainty for lessor fleet orders. Distribution runs through manufacturer-captive subsidiaries, bank-affiliated lessors, and specialized fleet management companies with integrated telematics infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in auto leasing services rests on algorithmic residual value precision and battery health verification technology licensing that commands premium pricing from risk-averse fleet operators.
For Market Incumbents: Acquire telematics data platforms and battery health verification technology to defend against fintech entrants with AI-driven pricing engines. Incumbent captives should deepen backward integration into refurbishment infrastructure to capture end-of-lease residual value uplift. Consolidation of regional fleet management specialists in India and Southeast Asia protects against operational lease entrants with maintenance bundling. For New Entrants and Emerging Players: Enter via India's commercial vehicle leasing white space where captive finance penetration remains minimal and logistics operators seek maintenance-inclusive contracts. Target battery subscription unbundling models proven in China's tier-one cities, adapting for regional regulatory frameworks. Partner with domestic EV manufacturers to access vehicle allocation priority and co-develop residual value algorithms. For Investors and Strategic Acquirers: Consolidation pressure builds where operational lessors lack proprietary telematics infrastructure and depend on third-party data providers for mileage verification. Long-term viability favors acquirers of fleet management platforms with embedded AI residual forecasting and cross-border contract standardization capabilities. Monitor battery chemistry patent filings and cobalt-nickel price volatility indices as inflection indicators for electric vehicle lease portfolio risk repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Health Verification Technology Licensing | Proprietary algorithms for lithium-ion degradation tracking command premium pricing from risk-averse fleet operators. |
| Cross-Border Fleet Contract Standardization | Unified terms across EU Consumer Credit Directive and US Regulation M jurisdictions reduce compliance overhead for multinational logistics clients. |
| Telematics-Enabled Dynamic Pricing Deployment | Real-time mileage verification and usage-based adjustments compress quote-to-contract timelines from days to hours. |
| Closed-Loop Refurbishment Infrastructure Investment | EU REACH compliance deadlines on end-of-life vehicle processing create first-mover advantage in circular economy positioning. |
| Battery Subscription Unbundling Partnership | Separating battery costs from vehicle leases lowers monthly payments and transfers residual risk to specialized energy storage lessors. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's fleet management executives, captive finance subsidiary directors, telematics platform engineers, and logistics procurement officers. Secondary validation draws from SEC 10-K filings of listed lessors, vehicle production databases, IHS Markit registration data, and central bank interest rate policy records. Bottom-up lease contract analysis triangulates against top-down macroeconomic indicators across the analysis window.
Rate-of-change decomposition separates volume growth from pricing dynamics across service type, customer profile, vehicle category, and lease duration dimensions. Segmentation modeling incorporates propulsion architecture, telematics integration depth, and regional regulatory framework clusters. CAGRs derive from historical lease origination trends, residual value realization rates, and fleet operator capital expenditure survey data. Battery degradation curves and semiconductor delivery lead times inform electric vehicle lease portfolio risk adjustments.
Inputs from OEM captive finance disclosures and fleet operator procurement databases were available through the study window; gaps in private lessor residual value realization data introduce uncertainty bands around electric vehicle segment forecasts. Forecasts reflect assumptions on Federal Reserve interest rate trajectory, EU battery regulation implementation timing, and China EV subsidy phase-out schedules. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Services
Global Automotive Engineering Services Outsourcing Market
Automotive Services
Automotive Repair and Service Market
Automotive Services
Automatic Vehicle Washing System Market
Automotive Services
Online Car-Hailing Service Market
Automotive Services
Qatar Car Rental Market
Automotive Services
Americas MAP Market
Automotive Services
Sub Saharan Africa Automotive Market
Automotive Services
Motorcycle Rental Market
Automotive Services
Vehicle Analytics Market
Automotive Services
Automotive Acoustic Engineering Services Market
Automotive Services
Global Car Wash Market
Automotive Services
Emergency Ambulance Vehicle Market
Automotive Services
France Car Rental Market
Automotive Services
Automotive E-Tailing Market
Automotive Services
ADAS Recalibration Services Market
Automotive Services
Automotive Retail Market