
 Liquid Capsule Filling Machines Market | 2026-2036
Liquid Capsule Filling Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Capsule Filling Machines Market Analysis
Buyer concentration among pharmaceutical contract manufacturers is realigning procurement priorities toward high-throughput, validation-ready equipment. Syntegon leverages its integrated processing portfolio to anchor large-scale biopharma accounts across Europe. LTPM CHINA competes aggressively on modular system configurations tailored to mid-tier Asian manufacturers. Rich Packing specializes in small-to-medium capacity units that occupy price-sensitive segments in emerging markets.
Liquid capsule filling machines are precision dosing systems engineered to fill hard or soft gelatin capsules with liquids, suspensions, or semi-solids at fill weights typically ranging from 0.1 mL to 1.5 mL per capsule, serving pharmaceutical and nutraceutical manufacturing where bioavailability enhancement or moisture-sensitive active ingredients require liquid encapsulation rather than powder compression. Automatic machines dominate installed base value due to throughput requirements in commercial pharmaceutical operations, while robotics-enabled systems represent the fastest-expanding technology segment as manufacturers pursue reduced human intervention for aseptic compliance. Modular systems attract contract manufacturers seeking line reconfigurability between batch sizes without dedicated capital for each product format.
FDA cGMP regulations and EU GMP Annex 1 standards collectively enforce barrier isolation and in-process monitoring requirements that elevate machine specification thresholds for market access. The EPA and OSHA frameworks in the United States impose containment and operator exposure limits that shape equipment enclosure designs for potent compound handling. Stakeholders must monitor evolving EMA guidance on continuous manufacturing qualification to anticipate validation protocol changes that will favor adaptable, data-integrated filling platforms.
Market Dynamics
Pharmaceutical contract manufacturers face simultaneous pressure from FDA cGMP and EU GMP Annex 1 revisions demanding reduced human intervention, forcing capital redeployment toward robotics-enabled filling platforms with integrated barrier isolation systems.
Growth Catalysts
- EU GMP Annex 1 revisions:The 2022 update mandates continuous viable and non-viable particle monitoring, compelling manufacturers to replace legacy open-filling stations with closed robotic systems to maintain aseptic processing licenses.
- Softgel nutraceuticals:Omega-3 fatty acid and vitamin D formulations requiring liquid encapsulation for bioavailability are expanding production lines across North American and European dietary supplement contract manufacturers.
- Hyderabad and Ahmedabad clusters:Indian pharmaceutical export zones are consolidating specialized liquid filling capacity to serve ANDA filings for complex generic injectables and ophthalmic suspensions.
Market Restraints
- Stainless steel and HEPA filter cost volatility:Pharmaceutical-grade 316L stainless steel pricing fluctuations and extended lead times for certified filtration assemblies compress margin visibility for equipment fabricators.
- German and Swiss component concentration:Precision dosing pumps and servo-motion controllers source predominantly from Mittelstand suppliers, creating single-source vulnerability for non-European machine builders.
- Cross-contamination validation burden:FDA cGMP requirements for dedicated product-contact parts or verified cleaning protocols extend qualification timelines for multi-product contract manufacturing organizations.
Strategic Opportunities
- Brazilian ANVISA alignment:The regulator's 2023 harmonization with PIC/S standards creates upgrade demand among domestic manufacturers previously operating under less stringent local protocols.
- Continuous manufacturing qualification:EMA guidance development on real-time release testing favors adaptable filling platforms with integrated PAT sensors, rewarding early movers with validation protocol influence.
- Cell and gene therapy media filling:Viral vector suspension encapsulation for oral delivery formats represents an unaddressed application space with distinct containment and cold-chain requirements from small-molecule liquids.
Industry Challenges
- Mechatronics and aseptic engineering talent scarcity:The intersection of precision fluid handling, robotics programming, and pharmaceutical microbiology requires hybrid skill sets concentrated among experienced German and Swiss technicians.
- Legacy SCADA integration friction:Brownfield pharmaceutical facilities operate validated distributed control systems from the 1990s, complicating data integrity compliance for new equipment with modern Ethernet-based architectures.
- IQ/OQ/PQ timeline compression:Accelerated ANDA approval targets squeeze commissioning windows, forcing contract manufacturers to accept higher validation risk or delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Capsule Filling Machines Market |
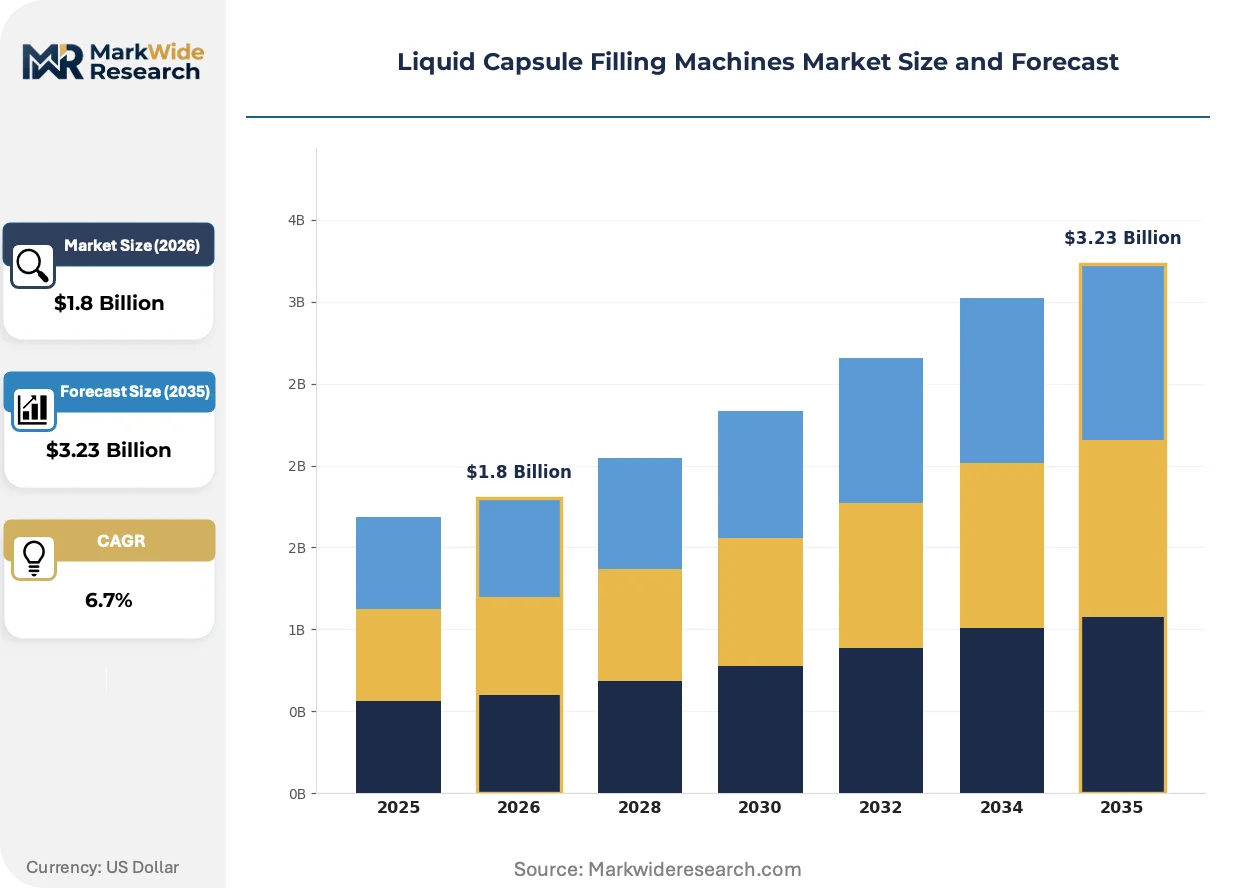
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Machines, Semi-Automatic Machines, Manual Machines, Modular Systems End User: Pharmaceutical Companies, Contract Manufacturers, Nutraceuticals, Research Institutions Technology: Thermal Gelation, Cold Filling, Dual Filling, Robotics Capacity: Small Scale, Medium Scale, Large Scale, Custom Solutions |
| Companies Covered | Amcor, Finetech, Syntegon, Furis Group, LFA Machines, LTPM CHINA, Hunan Migrand Machinery Technology, Rich Packing, Qualipac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Capsule Filling Machines Market Emerging Trajectories
Robotics-enabled filling architectures are compressing the competitive gap between high-throughput pharmaceutical operations and mid-tier contract manufacturers seeking aseptic compliance without dedicated cleanroom infrastructure.
Isolator-integrated liquid capsule filling systems combine unidirectional airflow enclosures with robotic pick-and-place mechanisms for capsule handling. Large-scale biopharma manufacturers in Germany and the United States are specifying these configurations for new commercial facilities. Closed-barrier technology is overtaking conventional laminar-flow benches as the baseline for FDA pre-approval inspection readiness.
EMA guidance on continuous manufacturing qualification is reshaping equipment specification requirements for European pharmaceutical operations. The framework emphasizes process analytical technology integration and real-time release testing capabilities. Filling platform vendors serving EMA-regulated markets are prioritizing PAT-compatible sensor architectures over standalone mechanical systems.
Contract manufacturing organizations are unbundling equipment procurement from validation service contracts, creating direct purchasing relationships with specialized commissioning firms. This disintermediation of OEM service dependencies is most pronounced among Indian pharmaceutical exporters seeking faster qualification timelines for US ANDA submissions.
Liquid Capsule Filling Machines Market Segmentation
Liquid capsule filling machines segment across operational intensity, buyer sophistication, and production scale. Each axis reveals distinct specification thresholds and procurement patterns that equipment vendors must address separately.
Product Type:
Automation intensity defines capital allocation priorities across pharmaceutical manufacturing tiers.
- Automatic Machines:Continuous-motion rotary systems achieve throughput exceeding 150,000 capsules per hour with integrated weight-check and reject functions. Large-scale commercial operations in Germany and the United States specify these for FDA pre-approval inspection readiness, though stainless steel cost volatility compresses margin visibility for fabricators.
- Modular Systems:Reconfigurable platforms enable rapid changeover between batch sizes without dedicated capital for each product format. Contract manufacturers in India favor these for ANDA submission flexibility, particularly Hyderabad and Ahmedabad export clusters serving complex generic portfolios.
- Semi-Automatic Machines:Operator-assisted filling stations suit mid-tier nutraceutical producers with variable batch requirements.
- Manual Machines:Benchtop units serve research-scale operations and early-phase clinical material preparation.
Automatic machines lead on scale; modular systems lead on momentum.
End User:
Buyer type determines validation burden and service contract structure.
- Contract Manufacturers:Multi-product facilities face cross-contamination validation burdens under FDA cGMP that extend qualification timelines. These buyers are unbundling equipment procurement from OEM service contracts, creating direct relationships with specialized commissioning firms to accelerate ANDA revenue recognition.
- Pharmaceutical Companies:Integrated biopharma operations specify isolator-integrated architectures with unidirectional airflow enclosures for commercial facilities in Germany and the United States. Closed-barrier technology is overtaking conventional laminar-flow benches as baseline for regulatory inspection readiness.
- Nutraceuticals:Omega-3 and vitamin D formulators require liquid encapsulation for bioavailability enhancement.
- Research Institutions:Early-phase development centers prioritize flexibility over throughput for clinical trial material supply.
Contract manufacturers dominate procurement volume; pharmaceutical companies set specification standards.
Technology:
Process mechanism determines active ingredient stability and containment requirements.
- Robotics:Pick-and-place mechanisms with integrated barrier isolation reduce human intervention for EU GMP Annex 1 compliance. EMA-regulated manufacturers specify these for continuous viable and non-viable particle monitoring mandates, with vendors prioritizing PAT-compatible sensor architectures.
- Thermal Gelation:Temperature-controlled band sealing suits gelatin-based softgel formulations with precise shell thickness requirements.
- Cold Filling:Low-temperature processing preserves heat-sensitive actives in suspension formulations.
- Dual Filling:Sequential liquid and semi-solid deposition enables combination products with distinct release profiles.
Robotics commands premium positioning; thermal gelation maintains installed base dominance.
Capacity:
Production scale aligns with facility validation tier and regulatory jurisdiction.
- Large Scale:High-throughput lines serve commercial pharmaceutical operations with dedicated cleanroom infrastructure. These installations concentrate in Germany and the United States where FDA and EU GMP Annex 1 stringency justifies capital intensity.
- Small Scale:Compact systems address emerging market price sensitivity and research institution flexibility requirements.
- Medium Scale:Mid-tier output suits regional nutraceutical contract manufacturers with moderate batch volumes.
- Custom Solutions:Engineered configurations address atypical containment or cold-chain specifications for specialized applications.
Large scale anchors revenue concentration; small scale expands geographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands specification standards for isolator-integrated systems while India drives procurement volume through contract manufacturing expansion. The United States anchors regulatory compliance investments. Brazil and Switzerland represent emerging upgrade cycles and precision component sourcing respectively.
Germany
Large-scale biopharma manufacturers specify closed-barrier robotic architectures for commercial facilities. EU GMP Annex 1 revisions mandate continuous particle monitoring, compelling replacement of legacy open-filling stations. The Mittelstand supplier belt around Stuttgart and Munich concentrates precision dosing pump and servo-motion controller fabrication.
United States
Pharmaceutical companies deploy isolator-integrated systems for FDA pre-approval inspection readiness. EPA and OSHA frameworks impose containment and operator exposure limits shaping equipment enclosure designs. The Research Triangle Park and Boston-Cambridge clusters concentrate biopharma manufacturing capacity serving complex generic portfolios.
India
Contract manufacturers expand equipment procurement to serve accelerated ANDA submission timelines. CDSCO alignment with FDA cGMP standards tightens aseptic processing requirements for export-oriented facilities. Hyderabad and Ahmedabad pharmaceutical export zones consolidate specialized liquid filling capacity for ophthalmic suspensions and complex generics.
Brazil
Domestic manufacturers face upgrade demand following ANVISA's 2023 harmonization with PIC/S standards. The country's national pharmaceutical regulator now enforces barrier isolation requirements previously absent under local protocols. São Paulo and Rio de Janeiro industrial corridors host contract manufacturers retrofitting legacy lines for international market access.
Switzerland
Precision mechatronics suppliers concentrate dosing pump and motion control component fabrication for global machine builders. Swissmedic maintains stringent device qualification protocols that shape validation service requirements. The Basel-Zurich corridor anchors specialized engineering talent for aseptic processing equipment development.
Liquid Capsule Filling Machines Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct specification tiers. The vendor base organizes around three strategic archetypes: integrated processing portfolio holders anchoring large-scale biopharma accounts, modular system configurators serving mid-tier contract manufacturers, and price-optimized fabricators capturing emerging market volume. M&A activity concentrates on validation service capabilities while geographic expansion targets Indian and Brazilian upgrade cycles.
Among Germany-based diversified processors, Syntegon anchors the integrated portfolio archetype across European biopharma accounts. LTPM CHINA and Rich Packing occupy positions within the Asia-focused modular and price-optimized tiers respectively, with the former exemplifying reconfigurable platform specialization and the latter representing small-to-medium capacity unit fabrication for cost-sensitive segments.
| Leading Market Players |
|---|
| Amcor |
| Finetech |
| Syntegon |
| Furis Group |
| LFA Machines |
| LTPM CHINA |
| Hunan Migrand Machinery Technology |
| Rich Packing |
| Qualipac |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical-grade 316L stainless steel pricing fluctuations flow through equipment fabricator margins into three-tier pricing structure across premium, standard, and economy levels, with German and Swiss precision component concentration amplifying cost pass-through to robotics-enabled system tiers.
Pricing Analysis
Capacity additions in India are reshaping price floors for modular liquid capsule filling platforms as Hyderabad and Ahmedabad contract manufacturers scale procurement volumes. Price differentiation centers on EU GMP Annex 1 certification grade and integrated PAT sensor architecture, with robotics-enabled isolator systems commanding premium positioning against semi-automatic economy tiers. Cost compression in standard-capacity segments is intensifying because stainless steel and HEPA filter lead time volatility compresses fabricator margin visibility. Contract manufacturers serving ANDA submission timelines exhibit highest price sensitivity, while large-scale biopharma operations in Germany and the United States prioritize validation-ready specifications over unit economics.
Supply Chain Analysis
Refurbishment flows for legacy SCADA-integrated filling stations create secondary equipment channels serving mid-tier Indian and Brazilian contract manufacturers upgrading from manual operations. Component fabrication concentrates in Germany, Switzerland, and China, with precision dosing pumps and servo-motion controllers drawing from Mittelstand suppliers around Stuttgart and Munich. Supply chain risk hinges on single-source vulnerability for pharmaceutical-grade 316L stainless steel and certified HEPA filtration assemblies. Distribution runs through OEM-direct sales for large-scale pharmaceutical accounts and specialized commissioning firms disintermediating service contracts for Indian export clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in liquid capsule filling equipment rests on robotics-enabled platform premiums and validation service bundling as contract manufacturers accelerate procurement for FDA and EU GMP compliance.
For Market Incumbents: Acquire specialized commissioning firms with FDA cGMP and EU GMP Annex 1 validation expertise to capture unbundled service contracts from Indian contract manufacturers. Defend against modular system configurators by anchoring large-scale biopharma accounts through integrated barrier isolation architectures with PAT-compatible sensor architectures. For New Entrants and Emerging Players: Enter via cell and gene therapy media filling applications for viral vector oral delivery formats, an unaddressed space with distinct cold-chain containment requirements. Target Brazilian ANVISA-aligned upgrade demand among São Paulo and Rio de Janeiro contract manufacturers retrofitting legacy lines for PIC/S harmonization, positioning on rapid qualification timelines. For Investors and Strategic Acquirers: Consolidation pressure builds where validation service capabilities concentrate among German and Swiss engineering firms with hybrid mechatronics and aseptic processing expertise. Long-term viability favors platforms with adaptable data architectures for continuous manufacturing qualification under evolving EMA guidance. Monitor EMA real-time release testing protocol developments as inflection signal for PAT-integrated filling platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| Validation Service Capability Acquisition | Captures unbundled commissioning contracts from Indian ANDA-focused contract manufacturers. |
| PAT Sensor Architecture Integration | Positions equipment for EMA continuous manufacturing qualification and real-time release testing. |
| Modular Platform Reconfigurability Investment | Addresses Hyderabad and Ahmedabad demand for batch-size flexibility without dedicated capital. |
| Isolator-Integrated Robotics Development | Meets EU GMP Annex 1 particle monitoring mandates for German and US commercial facilities. |
| Brazilian Market Localization Partnership | Accelerates ANVISA-aligned retrofit timelines for São Paulo contract manufacturing corridors. |
Methodological Framework
Bottom-up pharmaceutical contract manufacturer modeling reconciled against top-down precision component supply tracking forms the analytical core of this study. Primary interviews with equipment procurement directors, validation engineering leads, aseptic processing consultants, and aftermarket service heads combined with secondary validation against FDA 483 observation databases, EMA inspection findings, CDSCO export facility registrations, and SEC filings from diversified processing conglomerates. Triangulation across stakeholder inputs and regulatory documentation ensures segment-level accuracy.
Historical trendline analysis of installed base value and technology substitution patterns informs projection modeling across automation intensity, end-user sophistication, process mechanism, and production scale dimensions. CAGRs derive from segment growth rate reconciliation against macro pharmaceutical capital expenditure indicators and regulatory compliance investment cycles. Forecast inputs incorporate ANDA submission velocity, EU GMP Annex 1 revision implementation timelines, and continuous manufacturing guidance development trajectories.
Inputs from FDA, EMA, and CDSCO regulatory databases were available through the study window; gaps in real-time equipment procurement transaction data introduce uncertainty bands around contract manufacturer segment sizing. Forecasts reflect documented assumptions on stainless steel cost stabilization and precision component lead time normalization. Practitioners should monitor EMA continuous manufacturing qualification protocol finalization and ANVISA PIC/S harmonization enforcement intensity for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Barcode Labeller Machine Market
Packaging Machinery
Granule Filling Machine Market
Packaging Machinery
Strapping Machine Market
Packaging Machinery
Bottle Capping Machines Market
Packaging Machinery
Lidding Machines Market
Packaging Machinery
Automatic Thermoforming Vacuum Machine Market
Packaging Machinery
Product Dispensing Machinery Market
Packaging Machinery
LAMEA Printing Machinery Market
Packaging Machinery
Shrink Label Machine Market
Packaging Machinery
Flow Wrapper Market
Packaging Machinery
Die Cutting Machine Market
Packaging Machinery
Puffer Machines Market
Packaging Machinery
Kraft Paper Machines Market
Packaging Machinery
Cling Wrap Machine Market
Packaging Machinery
Aerosol Filling Machines Market
Packaging Machinery
Screw Capping Machines Market