
 Pre-Made Pouch Packaging Machines Market | 2026-2036
Pre-Made Pouch Packaging Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Made Pouch Packaging Machines Market Outlook
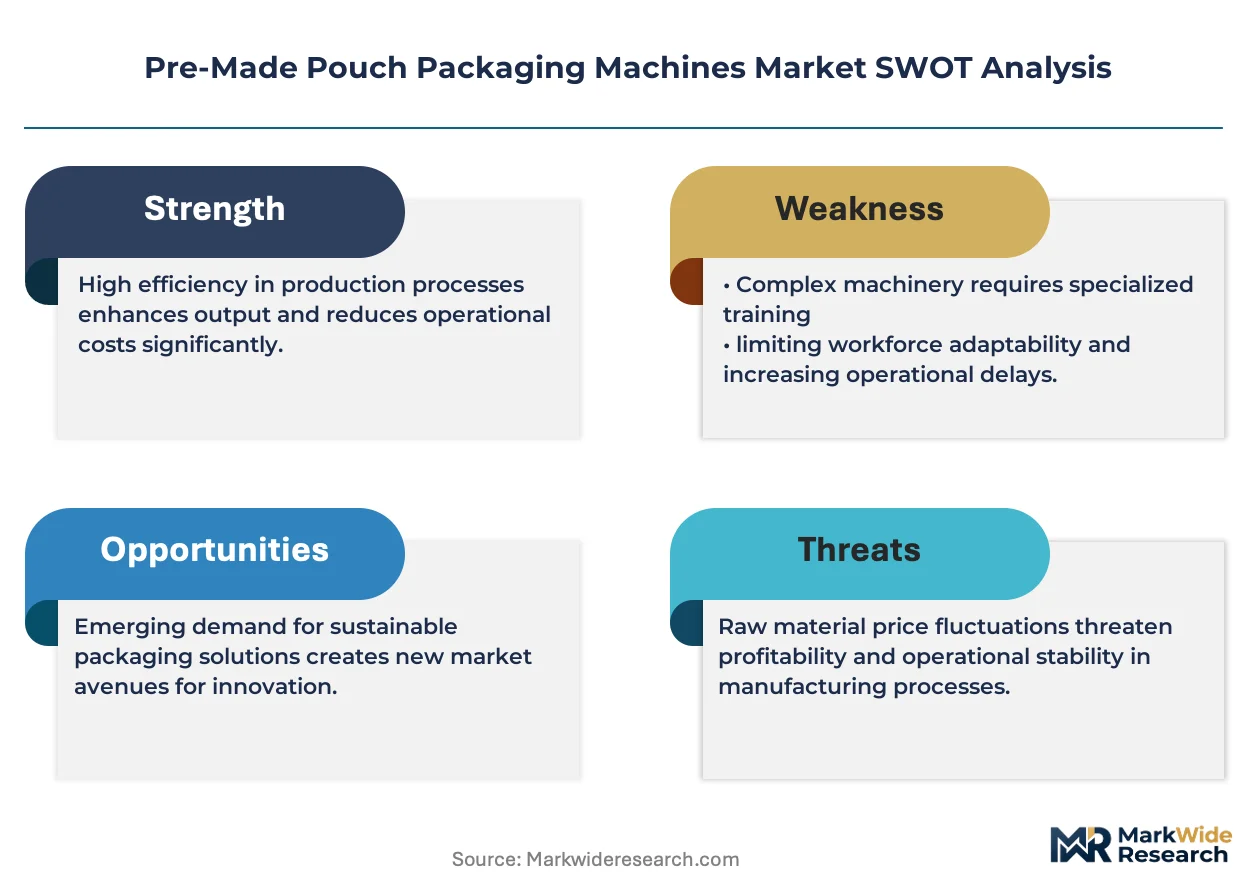
Contract packagers is collapsing the traditional buyer mix that long favored in-house manufacturer ownership of filling lines. Viking Masek leverages its vertical integration into film handling and sealing modules to serve co-manufacturing hubs in the Upper Midwest. Matrix Packaging anchors its position through R&D intensity in quick-changeover tooling that reduces format conversion downtime for multi-SKU contract operations. SN Maschinenbau specializes in clean-room-compatible architectures that pharmaceutical contract packagers require for aseptic pouch filling.
Pre-made pouch packaging machines are automated systems that open, fill, and seal pre-formed flexible pouches at speeds ranging from 30 to 300 cycles per minute depending on lane configuration and product viscosity. These systems employ heat-sealing bars, vacuum-assisted pouch opening grippers, and auger or piston dosing units to handle liquids, powders, and solids across food, pharmaceutical, and personal care production environments. Premade pouch fill seal configurations command margin pools in premium applications where product integrity and shelf appeal outweigh capital cost sensitivity, while servo-driven technology leads growth due to precision control over seal temperature and pressure that reduces material waste. Horizontal form fill seal remains mature in mass-market beverage stick packs where throughput maximization dominates purchasing criteria over flexibility.
FDA cGMP standards for pharmaceutical contact surfaces and USDA sanitation requirements for dairy and meat pouch filling shape machine design specifications and validation protocols in the United States. The EU Machinery Directive and CE marking impose safety interlock and ergonomic access standards that European OEMs must satisfy for market access, while REACH compliance constrains sealant material chemistry and lubricant selection. Stakeholders must monitor how California's SB 54 extended producer responsibility rules and parallel EU Packaging and Packaging Waste Regulation developments will mandate design-for-recycling specifications that retrofit timelines and new equipment procurement criteria.
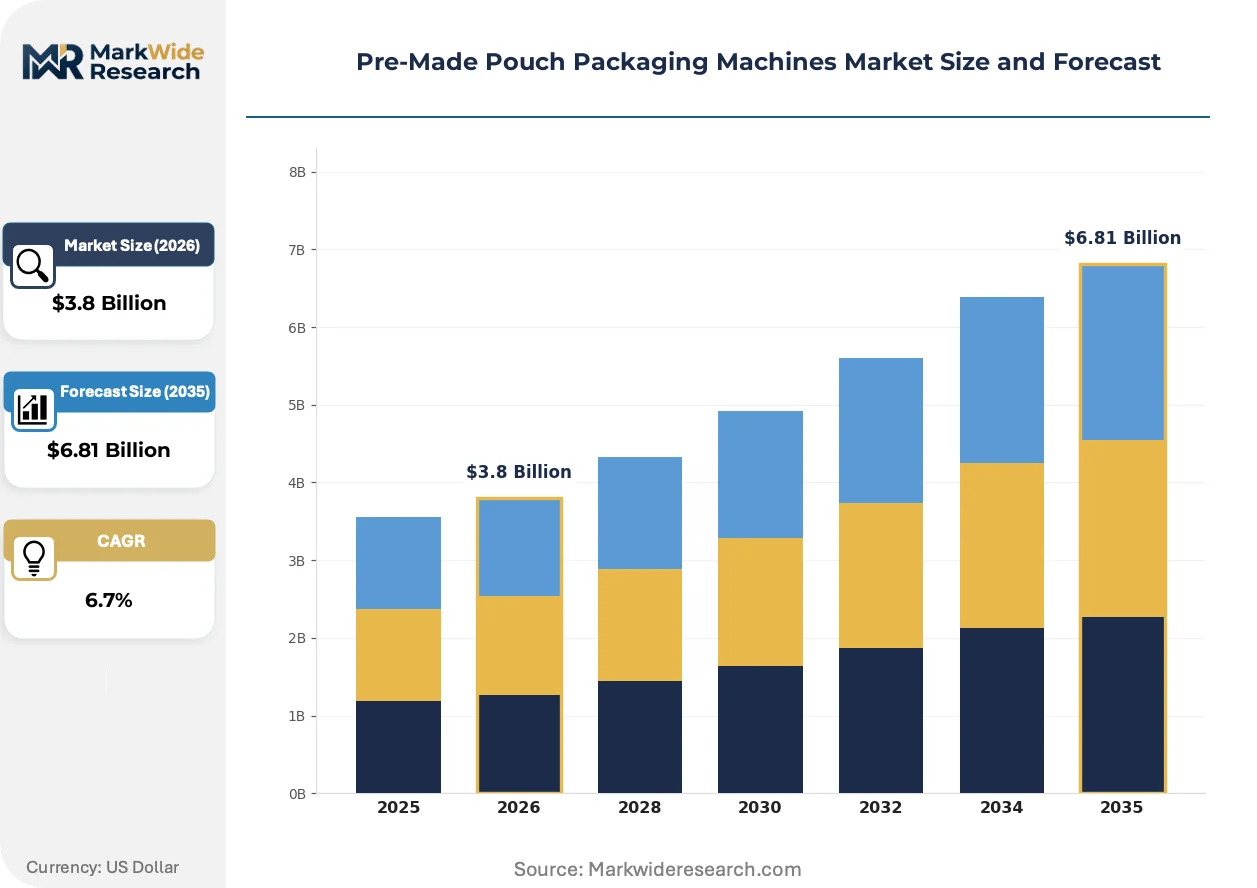
Market Dynamics
Contract packagers are collapsing the traditional buyer mix that long favored in-house manufacturer ownership of filling lines, while EU F-Gas Regulation and REACH compliance push machine builders toward servo-driven electric systems that eliminate hydraulic fluids and reduce carbon footprint.
Growth Catalysts
- REACH compliance mandates:Chemical restrictions on sealants and lubricants accelerate replacement of pneumatic systems with electric servo drives in European installations.
- Snack food producers:Germany's retrofit wave for recyclable mono-material pouches creates replacement demand for heat-sealing modules compatible with PE and PP substrates.
- Pet food contract manufacturing:Co-manufacturing hubs in the Upper Midwest expand capacity for premium wet and dry pet food pouch formats.
Market Restraints
- Copper and rare earth magnet costs:Servo motor supply chains concentrate in China, exposing European OEMs to input price volatility and export control risks.
- Technical limitation of mono-material seal integrity:Current heat-seal bar designs struggle to achieve hermetic seals on ultra-thin PE films without zipper failure.
- California SB 54 extended producer responsibility:Pending design-for-recycling specifications create procurement paralysis as brands delay capital commitments until compliance thresholds clarify.
Strategic Opportunities
- Pharmaceutical aseptic pouch filling:Clean-room-compatible architectures remain underpenetrated relative to vial and syringe packaging, with FDA cGMP validation creating high switching costs for early movers.
- Quick-changeover tooling convergence:Integration of RFID-enabled format parts with servo-driven changeover sequences reduces SKU transition downtime for multi-product contract packagers.
- USDA dairy and meat sanitation requirements:Washdown-rated machine designs open replacement cycles in Wisconsin and California dairy processing corridors.
Industry Challenges
- Mechatronics technician scarcity:Servo system commissioning and predictive maintenance require skills that vocational programs have not scaled to match equipment complexity.
- Legacy Allen-Bradley and Siemens PLC integration:Retrofitting servo axes onto existing line control architectures demands custom gateway programming that extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Made Pouch Packaging Machines Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Form Fill Seal, Horizontal Form Fill Seal, Premade Pouch Fill Seal, Multi-Lane Pouch Machine Technology: Electromechanical, Pneumatic, Hybrid, Servo-Driven Application: Food, Beverages, Pharmaceuticals, Personal Care End User: Manufacturers, Contract Packagers, Retailers, Distributors |
| Companies Covered | Viking Masek, Matrix Packaging, General Packer, SN Maschinenbau, Topack, Alliedflex Technologies, Massman Automation, WeighPack Systems, Paxiom Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Made Pouch Packaging Machines Market Strategic Shifts
Servo-driven motion control is displacing pneumatic and hydraulic actuation across filling, sealing, and indexing functions, while regulatory chemistry constraints and buyer procurement model evolution reshape competitive positioning.
Inductive heating seal bars are miniaturizing thermal mass and improving temperature uniformity across seal jaws. Pharmaceutical contract packagers in Germany and Switzerland adopt these systems for narrow-tolerance aseptic applications. The technology is miniaturizing the footprint of sealing stations while cutting energy consumption per cycle by eliminating resistive element thermal lag.
The EU F-Gas Regulation phases down hydrofluorocarbon use in refrigeration and heat pump systems, indirectly pressuring machine builders to eliminate pneumatic cooling circuits that rely on compressed air drying with HFC refrigerants. OEMs in Italy and the Netherlands respond by specifying closed-loop water cooling for servo drives. Food brands with Scope 3 emissions targets now audit supplier equipment for F-Gas compliance.
Co-manufacturing procurement is consolidating vendor relationships as contract packagers standardize on single OEM platforms to reduce spare parts inventory and technician training overhead. Multi-SKU operators in the Upper Midwest now specify identical HMI architectures across filling lines. This concentration is most visible in pet food and ready-meal segments where brand owners outsource entire packaging operations.
Pre-Made Pouch Packaging Machines Market Segmentation
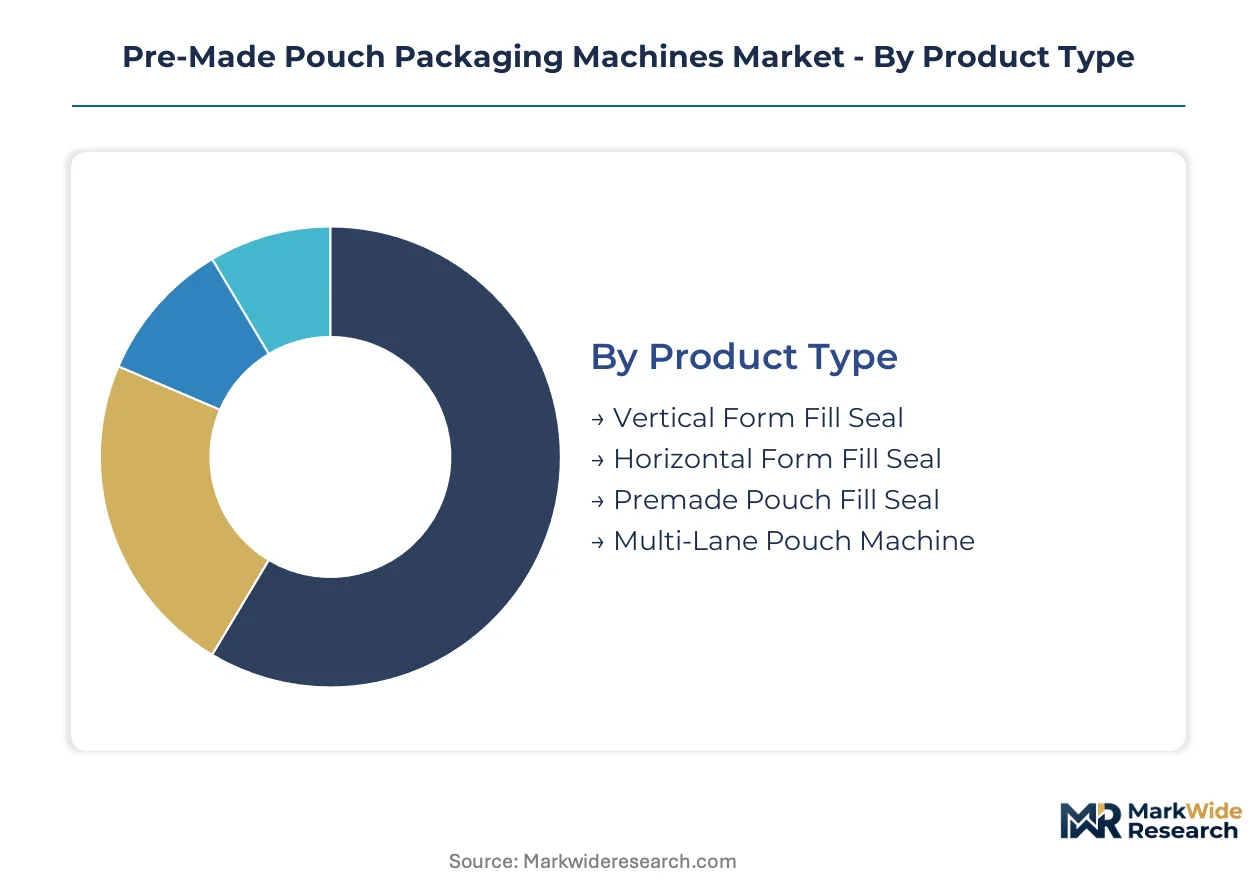
Segmentation reveals how substitution pressures and regulatory compliance reshape procurement priorities across machine configurations. Buyers now trade off throughput maximization against format flexibility as contract manufacturing restructures the customer base.
Product Type:
Horizontal form fill seal faces the strongest substitution threat as premade pouch fill seal systems capture premium applications demanding superior shelf appeal and seal integrity.
- Vertical Form Fill Seal:These systems form pouches from rollstock film before filling, achieving the lowest per-unit capital cost for high-volume commodity products. Snack food producers in Germany retrofit these lines for recyclable mono-material PE substrates under EU Packaging and Packaging Waste Regulation pressure.
- Horizontal Form Fill Seal:Optimized for stick packs and sachets, these machines dominate beverage and condiment single-serve formats. Beverage brands in the Upper Midwest specify these for throughput maximization where SKU variety remains limited.
- Premade Pouch Fill Seal:Systems handling pre-formed pouches command margin pools in premium segments where product integrity outweighs capital cost sensitivity. Pharmaceutical contract packagers specify these for aseptic filling under FDA cGMP validation protocols.
- Multi-Lane Pouch Machine:Parallel lane configurations multiply output for uniform SKUs without scaling footprint proportionally. Pet food co-manufacturers deploy these for dry kibble formats requiring consistent fill weights across high-speed production.
Vertical form fill seal anchors the volume base while premade pouch fill seal gains share at the steepest rate.
Technology:
Cost tier stratification separates established pneumatic installations from premium servo-driven replacements as energy efficiency and precision control reshape capital allocation.
- Electromechanical:Cam-driven mechanical systems deliver consistent motion profiles for standardized pouch formats with minimal electronic complexity. Legacy installations in mature dairy processing corridors retain these for mechanical simplicity and technician familiarity.
- Pneumatic:Compressed air actuation dominates legacy installed bases but faces phase-out pressure from EU F-Gas Regulation compliance costs and compressed air energy intensity. REACH chemical restrictions on lubricants accelerate replacement timelines in European installations.
- Servo-Driven:Closed-loop electric motion control enables programmable seal temperature and pressure profiles that reduce material waste on thin films. Inductive heating seal bars paired with servo indexing cut energy consumption per cycle while improving temperature uniformity for narrow-tolerance pharmaceutical applications.
- Hybrid:Mixed electromechanical and servo architectures preserve capital in partial retrofits where full replacement proves uneconomical. Wisconsin dairy processors specify these for washdown-rated lines requiring USDA sanitation compliance without complete line reconstruction.
Pneumatic technology retains the largest installed base while servo-driven configurations expand most quickly.
Application:
Application segmentation tracks how margin structures and regulatory intensity concentrate demand in formats requiring validated aseptic handling or extended shelf-life protection.
- Food:Snack, pet food, and ready-meal producers drive the largest equipment volume, with Germany's retrofit wave for recyclable mono-material pouches creating replacement demand for heat-sealing module upgrades. Mono-material seal integrity limitations on ultra-thin PE films constrain format migration timelines.
- Beverages:Stick packs and single-serve concentrates favor horizontal form fill seal configurations where throughput maximization dominates purchasing criteria. California's SB 54 extended producer responsibility rules create procurement paralysis as brands delay capital commitments.
- Pharmaceuticals:Aseptic pouch filling for oral solids and reconstitutable powders remains underpenetrated relative to vial packaging, with FDA cGMP validation creating high switching costs for early movers in clean-room-compatible architectures.
- Personal Care:Single-use sachets for cosmetics and hygiene products demand cosmetic-grade seal appearance and precise fill volumes. Swiss and German contract packagers specify servo-driven systems for narrow-tolerance dosing of high-viscosity creams.
Food processing anchors the volume base while pharmaceuticals climbs the fastest on aseptic penetration expansion.
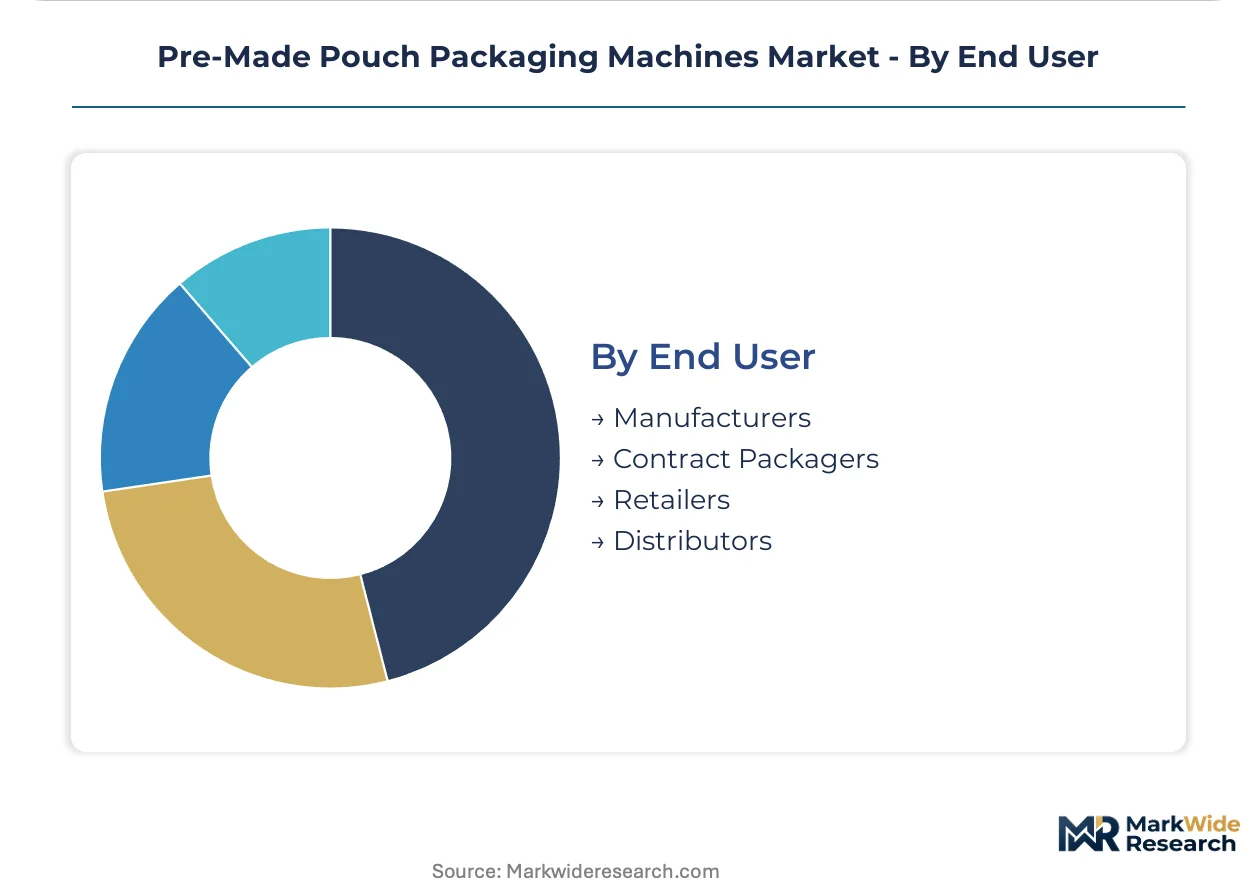
End User:
Customer type segmentation captures the structural shift from in-house manufacturer ownership toward outsourced contract manufacturing that collapses traditional buyer relationships.
- Manufacturers:Brand owners retaining in-house filling lines prioritize quick-changeover tooling for seasonal SKU proliferation and private label flexibility. Multi-SKU operators specify identical HMI architectures across lines to reduce technician training overhead.
- Contract Packagers:Co-manufacturing hubs consolidate vendor relationships to standardize spare parts inventory and maintenance protocols. Upper Midwest pet food contract manufacturers expand capacity for premium wet and dry pouch formats.
- Retailers:Private label packaging operations for store brands concentrate procurement through centralized technical specifications. European retailers audit supplier equipment for F-Gas compliance under Scope 3 emissions targets.
- Distributors:Equipment resale and refurbishment channels extend machine life cycles for budget-constrained entrants. Secondary markets concentrate in regions with high legacy installed base density.
Manufacturers retain the largest installed base while contract packagers gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain infrastructure underwrites Europe's dominance in perishable pouch filling, while the Union Pacific rail corridor links Upper Midwest pet food clusters to West Coast export terminals.
United States
Pet food contract manufacturers in Wisconsin and Minnesota expand wet and dry pouch capacity for premium brands. FDA cGMP validation requirements for pharmaceutical aseptic filling shape machine specifications in New Jersey and Pennsylvania corridors. California's SB 54 extended producer responsibility rules create procurement hesitation among beverage brands until compliance thresholds clarify.
Germany
Snack food producers in Bavaria and Baden-Württemberg retrofit lines for recyclable mono-material PE pouches under EU Packaging and Packaging Waste Regulation pressure. REACH chemical restrictions on sealants and lubricants accelerate pneumatic-to-servo system replacements. Stuttgart-area machine builders supply heat-sealing modules optimized for thin-film mono-material seal integrity.
China
Servo motor supply chains concentrate in Jiangsu and Zhejiang provinces, exposing European OEMs to rare earth magnet price volatility and export control exposure. Domestic food brands in the Yangtze River Delta adopt premade pouch systems for ready-meal and snack applications. GB standards for food contact materials constrain sealant chemistry selections in local machine specifications.
Japan
Cosmetics and personal care contract packagers in Osaka and Tokyo prefectures specify servo-driven dosing systems for high-viscosity cream sachets. METI energy efficiency guidelines favor closed-loop electric motion control over pneumatic actuation. Pharmaceutical manufacturers in Kansai region pilot clean-room-compatible pouch architectures for oral solid dose formats.
India
FMCG brand owners in Maharashtra and Gujarat outsource pouch filling to emerging co-manufacturing hubs. FSSAI food safety standards for packaging material migration shape machine material specifications in Mumbai-Pune industrial corridor. Domestic equipment fabricators in Ahmedabad supply electromechanical systems for budget-conscious dairy processors.
Pre-Made Pouch Packaging Machines Market Competitive Environment
Concentration sits with specialized machinery fabricators serving contract packaging hubs. The vendor base spans three tiers: European precision-engineering houses, North American mid-scale specialists, and Asian volume producers. Competitive moves center on backward integration into film handling modules and strategic partnerships with sealant chemistry suppliers to address mono-material compatibility constraints.
Among Upper Midwest-based specialists, Massman Automation and WeighPack Systems occupy positions serving pet food co-manufacturing expansion. Viking Masek anchors the European precision tier with upstream control over sealing module production. Matrix Packaging exemplifies the R&D-intensive archetype focused on quick-changeover tooling architectures.
| Leading Market Players |
|---|
| Viking Masek |
| Matrix Packaging |
| General Packer |
| SN Maschinenbau |
| Topack |
| Alliedflex Technologies |
| Massman Automation |
| WeighPack Systems |
| Paxiom Group |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Jiangsu and Zhejiang servo motor foundries concentrates supplier pricing power among Chinese rare earth processors, while European OEMs absorb input volatility through selective premium-tier markups on pharmaceutical-grade installations. This scale asymmetry stratifies machine pricing across contract packager and in-house manufacturer buyer archetypes.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical aseptic systems at premium certification grades from standard food-grade configurations. Pricing stratifies across premium, standard, and economy tiers based on FDA cGMP validation level and servo-axis count. Cost compression in standard-tier pneumatic replacements is intensifying because REACH compliance accelerates European retrofit timelines. Contract packagers exhibit highest price sensitivity due to consolidated vendor standardization mandates, while pharmaceutical manufacturers accept premium positioning for validated clean-room architectures.
Supply Chain Analysis
Rotterdam port congestion and container availability constraints on the Asia-Europe trade lane elevate inbound logistics costs for European machine builders sourcing inductive heating components. Servo motor production concentrates in China, Germany, and Japan, with rare earth magnet supply drawing from Chinese processing facilities. Single-source vulnerability in neodymium supply chains exposes OEMs to export control risks. Distribution runs through direct OEM sales for large pharmaceutical installations and regional distributor networks for mid-scale food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward contract packagers as co-manufacturing hubs consolidate vendor relationships and standardize platform specifications across multi-SKU operations.
For Market Incumbents: Consolidate spare parts inventory control through captive production of heat-sealing modules, mirroring Viking Masek's upstream integration strategy. Deepen technician certification programs to counter mechatronics skills scarcity threatening servo system commissioning quality. Lock in pharmaceutical contract packagers through FDA cGMP validation partnerships that create switching cost barriers against emerging European precision-engineering competitors. For New Entrants and Emerging Players: Predictive maintenance software layers represent a service gap where incumbents under-serve mid-scale dairy processors in Wisconsin and California corridors. Target USDA washdown-rated retrofit opportunities where legacy Allen-Bradley PLC integration complexity delays incumbent response times. Deploy subscription-based remote diagnostics as a go-to-market angle to bypass capital-intensive machine manufacturing barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors servo-drive specialists with inductive heating seal bar capabilities over legacy pneumatic system fabricators. The five-to-ten year viability window rewards acquisition of clean-room-compatible architecture developers serving pharmaceutical aseptic filling. Watch FDA cGMP validation queue lengths as an inflection indicator for switching cost durability in premium segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sealing Modules | Viking Masek's captive production of heat-sealing components insulates margin pools from rare earth input volatility. |
| Quick-Changeover Tooling R&D Investment | Matrix Packaging's RFID-enabled format parts reduce SKU transition downtime for Upper Midwest pet food contract manufacturers. |
| Clean-Room Architecture Certification | SN Maschinenbau's FDA cGMP validation creates high switching costs in pharmaceutical aseptic pouch filling. |
| Servo-Driven System Replacement Programs | REACH chemical restrictions on pneumatic lubricants accelerate European retrofit demand for electric motion control. |
| Regional Service Hub Expansion | Massman Automation's Wisconsin presence captures USDA dairy sanitation upgrade cycles in the Upper Midwest corridor. |
Study Parameters
A standing panel of plant engineers at contract packaging hubs, OEM procurement directors, and aftermarket service technicians provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC filings of listed machinery fabricators, EU Machinery Directive compliance databases, and F-Gas Regulation implementation tracking. Bottom-up equipment shipment tallies by configuration type triangulated against top-down capital expenditure surveys from food and pharmaceutical processors.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning machine configuration, actuation technology, end-use application, and customer type. CAGRs were derived from installed base replacement cycles and greenfield capacity expansion patterns. Forecast inputs incorporated REACH compliance phase-out timelines for pneumatic systems and California SB 54 extended producer responsibility rulemaking progress.
Underlying assumptions cover regulatory enforcement continuity and rare earth supply chain stability, with deviation risk concentrated in export control escalations and mono-material seal integrity technical limitations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Tray Sealer Machines Market
Packaging Machinery
Stacking Machine Market
Packaging Machinery
Meal Tray Sealing Machines Market
Packaging Machinery
Combination Filler Machine Market
Packaging Machinery
Tray Forming Machine Market
Packaging Machinery
North America Printing Machinery Market
Packaging Machinery
Die Cutting Machine Market
Packaging Machinery
Global Vial Cap Sealing Machines Market
Packaging Machinery
Pallet Drum Filler Capper Market
Packaging Machinery
Bundling Machine Market
Packaging Machinery
Automatic Filling Machine Market
Packaging Machinery
Vertical Injection Molding Machine Market
Packaging Machinery
Form-Fill-Seal (FFS) Packaging Machine Market
Packaging Machinery
Rotary Sealers Market
Packaging Machinery
Twist Tie Machines Market
Packaging Machinery
Global Film Coating Machine Market