
 Barcode Labeller Machine Market | 2026-2036
Barcode Labeller Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Barcode Labeller Machine Market Outlook
Single-source to multi-source procurement is restructuring supply relationships across the barcode labeller machine industry. Zebra Technologies Corporation dominates enterprise-grade thermal transfer installations through captive component sourcing. SATO Holdings Corporation anchors Asian manufacturing networks with precision print-engine specialization. TSC Auto ID Technology Co., Ltd. competes aggressively on cost-optimized desktop units for mid-volume operations.
A barcode labeller machine is an electromechanical device that applies adhesive labels carrying encoded data to products, packages, or pallets, typically achieving print resolutions of 203 to 600 dots per inch and operating at speeds exceeding 14 inches per second in industrial configurations. Its primary purpose is to enable automated identification, inventory tracking, and regulatory traceability across supply chains. Automatic product type systems command the widest deployment footprint in high-throughput logistics hubs where downtime costs dwarf equipment premiums. Thermal transfer technology leads in durability-critical applications such as chemical labeling and outdoor asset tracking, while direct thermal segments expand fastest in short-lifecycle shipping operations where label longevity requirements remain minimal.
FDA Unique Device Identification mandates and EU MDR traceability requirements are forcing healthcare end users toward validated labelling systems with audit-ready print logs. REACH compliance on adhesive substrates and RoHS restrictions on electronic components constrain material choices for manufacturers serving European markets. ISO 15415 and ISO 15416 print quality standards govern barcode grading protocols that determine scanner readability in automated distribution environments. Stakeholders must weigh total cost of ownership against compliance certification depth when selecting between regional suppliers and vertically integrated global platforms.
Market Dynamics
E-commerce fulfillment velocity requirements and FDA UDI traceability mandates are compressing equipment replacement cycles while forcing validation depth that favors integrated platform suppliers over modular assemblers.
Growth Catalysts
- EU MDR traceability expansion:Medical device manufacturers across Germany, France, and Italy must deploy validated labelling systems with immutable audit logs, pulling premium thermal transfer configurations into hospital supply chains and sterilization facilities.
- Thermal transfer durability premium:Chemical processing and outdoor asset tracking operations in the US Gulf Coast and Rotterdam port zones specify ribbon-based systems for 10-year legibility, insulating this technology segment from direct thermal commoditization.
- Automatic product type deployment:High-throughput logistics hubs in the Netherlands and Singapore are standardizing on inline applicators with encoder-synchronized dispensing to eliminate manual staging bottlenecks.
Market Restraints
- Print-engine supply concentration:Precision thermal printheads and piezoelectric inkjet assemblies concentrate among Japanese and German component specialists, exposing OEMs to 16-24 week lead time volatility.
- Silicon substrate cost exposure:Controller boards and HMI panels depend on foundry capacity in Taiwan and South Korea, where wafer pricing fluctuations transmit directly to equipment BOMs.
- Direct thermal substitution ceiling:Short-lifecycle shipping labels in ambient distribution centers face competition from RFID inlay pilots at Amazon and DHL facilities, capping segment expansion in temperature-controlled corridors.
Strategic Opportunities
- India pharmaceutical serialization:CDSCO track-and-trace mandates for active pharmaceutical ingredients create first-mover advantage for suppliers offering Hindi-localized software and 21 CFR Part 11 validation packages.
- Battery supply chain marking:UN 38.3 lithium-ion transport regulations and EU Battery Passport requirements are opening demand for high-temperature-resistant labels in cell manufacturing and recycling facilities.
- Cloud-native fleet management:Remote diagnostics and predictive maintenance APIs are enabling subscription-based service models that displace traditional break-fix arrangements in mid-volume operations.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for real-time print quality verification requires expertise in ISO/IEC 15415 grading algorithms that competes with automotive and medical device sectors for talent.
- Legacy WMS integration friction:Brownfield distribution centers running SAP EWM or Manhattan Associates configurations face 6-9 month deployment timelines for API-native labelling controllers.
- Multi-site validation coordination:Pharmaceutical and medical device manufacturers must synchronize IQ/OQ/PQ documentation across FDA, EMA, and PMDA jurisdictions, extending commissioning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Barcode Labeller Machine Market |
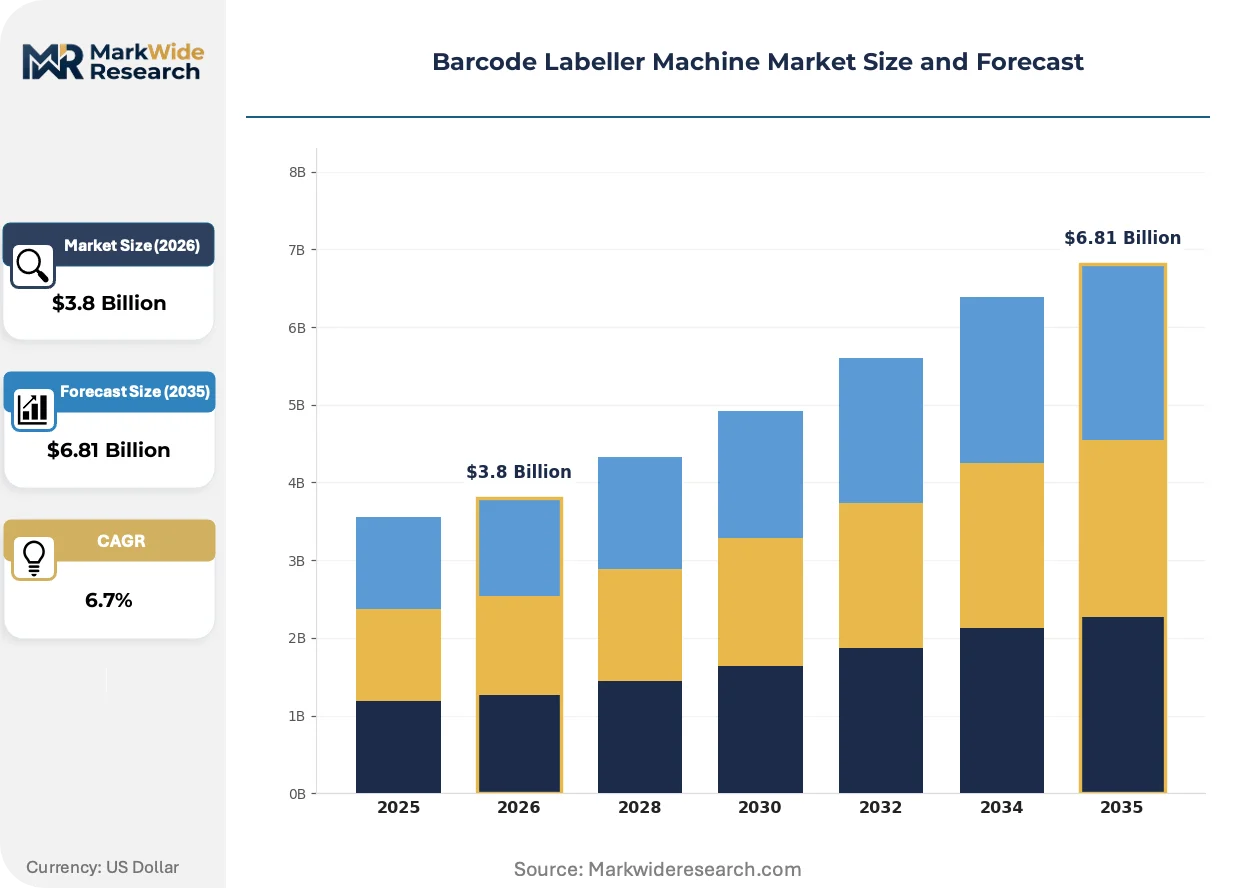
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semi-Automatic, Automatic, Manual, Industrial Technology: Thermal Transfer, Direct Thermal, Inkjet, Laser Application: Retail, Manufacturing, Logistics, Healthcare End User: SMEs, Large Enterprises, E-Commerce, Hospitality |
| Companies Covered | Zebra Technologies Corporation, SATO Holdings Corporation, Toshiba TEC Corporation, Honeywell International Inc., TSC Auto ID Technology Co., Ltd., Brother Industries, Ltd., Seiko Epson Corporation, Brady Corporation, Bixolon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Barcode Labeller Machine Market Strategic Shifts
Intelligent printhead diagnostics, sustainable substrate chemistry, and servitized ownership models are converging to redefine equipment value propositions and supplier-customer relationships.
UV-curable inkjet print engines with MEMS-controlled droplet placement are rewriting durability benchmarks in chemical drum and hazardous materials labeling. BASF and Dow chemical facilities in Ludwigshafen and Freeport have piloted these systems for GHS-compliant pictogram printing at 600 dpi, eliminating thermal ribbon inventory and enabling on-demand color hazard communication that static monochrome transfers cannot match.
REACH Annex XVII restrictions on adhesive solvent content and ECHA SVHC candidate list expansions are forcing reformulation of permanent and removable pressure-sensitive adhesives. Labelstock converters serving European healthcare and food contact applications must now validate alternative acrylic and hot-melt chemistries through migration testing protocols, with German industrial laundries and French cosmetics packagers absorbing 8-12% material cost premiums for compliant substrates.
Outcome-based service contracts with guaranteed uptime SLAs are displacing capital purchase arrangements in third-party logistics networks. DHL Supply Chain and GXO Logistics facilities in the UK Midlands and US Midwest have shifted to per-label pricing models where suppliers retain equipment ownership and absorb maintenance risk, concentrating vendor selection on telemetry sophistication and regional service density rather than hardware specifications alone.
Barcode Labeller Machine Market Segmentation
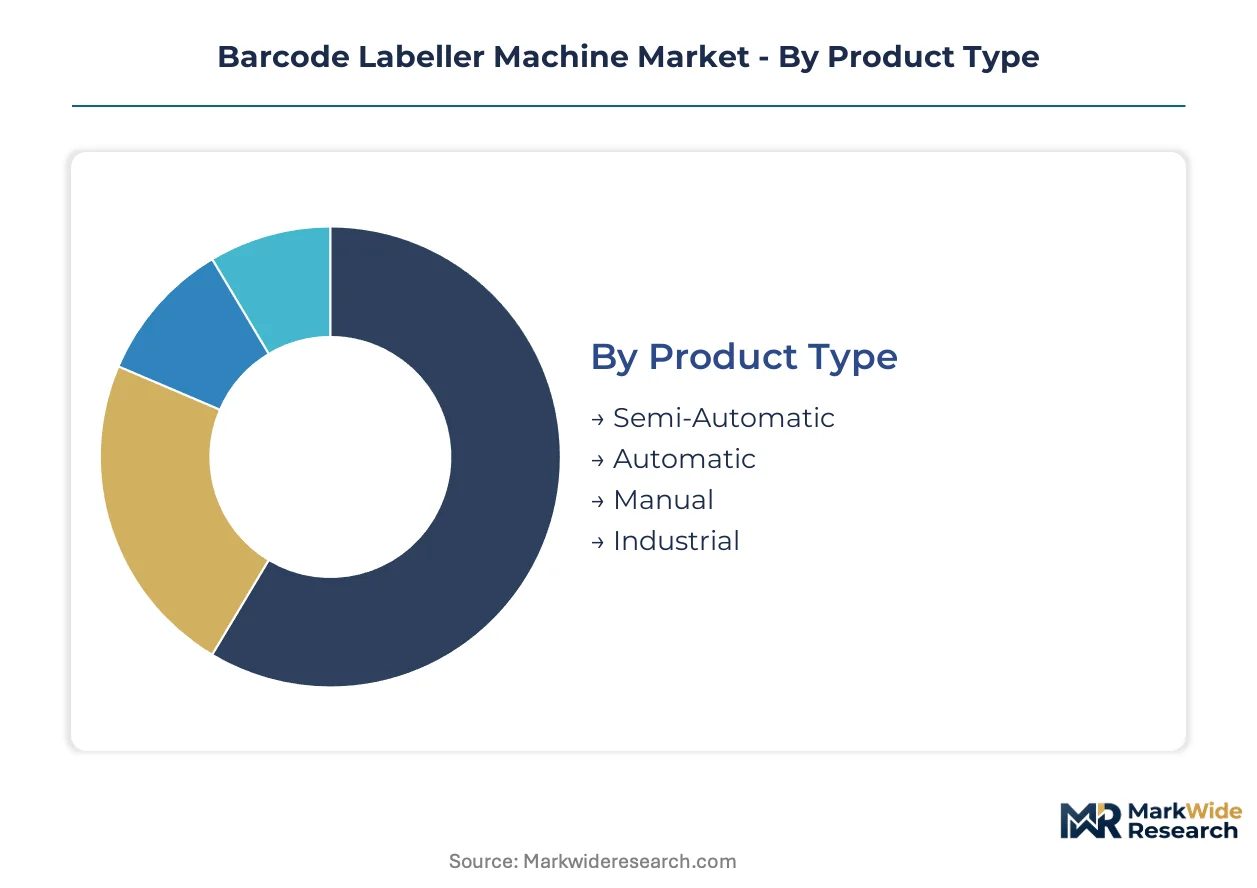
Barcode labeller machine segmentation reveals distinct integration architectures across the value chain. Standalone desktop units serve fragmented SME operations while inline automatic systems embed directly into conveyor-driven fulfillment infrastructure. Technology choices and end-user scale determine supplier margin structures and service model viability.
Product Type:
Integration depth separates standalone operator-dependent units from encoder-synchronized inline systems that eliminate manual staging entirely. Semi-automatic and automatic configurations dominate high-throughput environments where downtime costs exceed equipment premiums, while manual and industrial variants anchor opposite ends of the volume spectrum.
- Automatic:Encoder-synchronized inline applicators achieve speeds exceeding 14 inches per second with print resolutions of 203 to 600 dots per inch. E-commerce fulfillment centers in the Netherlands and Singapore specify these systems to eliminate manual bottlenecks in high-velocity distribution corridors.
- Semi-Automatic:Operator-triggered dispensing systems bridge mid-volume operations where full automation cannot justify capital deployment. German automotive component suppliers and French cosmetics packagers deploy these units for batch-lot traceability without conveyor integration complexity.
- Manual:Hand-held applicators serve micro-operations and secondary labeling stations in retail backrooms and hospital pharmacies where throughput requirements remain minimal.
- Industrial:Heavy-duty configurations withstand washdown protocols and temperature extremes in chemical processing and food manufacturing environments.
Automatic systems lead volumes today; semi-automatic configurations are gaining share fastest in mid-tier manufacturing verticals.
Technology:
Print durability requirements and total cost per label drive technology selection across end-use applications. Ribbon-based thermal transfer commands premium positioning in chemical and outdoor asset tracking, while direct thermal and inkjet alternatives compete on operational simplicity and color capability.
- Thermal Transfer:Wax-resin and resin ribbon systems deliver 10-year legibility in harsh chemical and UV-exposed environments. BASF and Dow facilities in Ludwigshafen and Freeport specify these for GHS-compliant drum labeling where substrate adhesion failure risks regulatory penalty.
- Inkjet:UV-curable piezoelectric engines with MEMS-controlled droplet placement enable on-demand color hazard communication at 600 dpi. This technology eliminates thermal ribbon inventory while meeting chemical drum pictogram requirements that monochrome transfers cannot satisfy.
- Direct Thermal:Heat-sensitive coating systems minimize consumable complexity in short-lifecycle shipping operations where label longevity requirements remain under 12 months.
- Laser:Ablation and etching systems mark directly onto substrates in permanent asset identification applications where adhesive labels face removal risk.
Thermal transfer maintains the largest installed base; inkjet configurations are climbing the fastest in chemical and hazardous materials labeling.
Application:
Regulatory traceability mandates and operational velocity requirements create divergent specification profiles across vertical markets. Healthcare and logistics applications demand validated systems with immutable audit logs, while retail and manufacturing prioritize throughput economics.
- Healthcare:FDA UDI and EU MDR traceability requirements force validated labelling systems with 21 CFR Part 11-compliant print logs. Hospital supply chains and sterilization facilities in Germany, France, and Italy specify premium thermal transfer configurations with IQ/OQ/PQ documentation packages.
- Logistics:E-commerce fulfillment velocity requirements compress equipment replacement cycles while favoring integrated platform suppliers over modular assemblers. Third-party logistics networks in the UK Midlands and US Midwest are shifting to outcome-based service contracts with guaranteed uptime SLAs.
- Retail:Price marking and inventory management applications in supermarket chains and specialty stores drive demand for cost-optimized desktop units with minimal IT integration requirements.
- Manufacturing:Work-in-process tracking and finished goods identification span automotive, electronics, and consumer packaged goods operations with varying throughput and durability specifications.
Logistics applications command the largest equipment deployment; healthcare represents the steepest expansion trajectory driven by regulatory compliance deadlines.
End User:
Procurement sophistication and total cost of ownership calculation methods vary sharply across customer scale categories. Large enterprises and e-commerce operators negotiate servitized contracts while SMEs and hospitality segments prioritize capital expenditure minimization.
- E-Commerce:Fulfillment velocity requirements and SKU proliferation drive demand for automatic inline systems with cloud-native fleet management APIs. Amazon and DHL facilities pilot RFID inlay integration alongside traditional barcode labeling in temperature-controlled corridors.
- Large Enterprises:Multi-site pharmaceutical and medical device manufacturers must synchronize validation documentation across FDA, EMA, and PMDA jurisdictions, extending commissioning cycles and favoring vertically integrated global platforms over regional suppliers.
- SMEs:Mid-volume operations in specialty manufacturing and regional distribution face 6-9 month deployment timelines for API-native labelling controllers integrated with legacy WMS configurations.
- Hospitality:Food service and hotel operations require compact units for ingredient labeling and guest amenity identification with minimal technical support infrastructure.
Large enterprises dominate current procurement volumes; e-commerce operators are expanding most quickly through subscription-based service model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial automation corridor concentrates the densest deployment of validated labelling systems for pharmaceutical and automotive traceability. FDA UDI mandates, EU MDR deadlines, and CDSCO serialization rules are compressing equipment replacement cycles across North America, Europe, and Asia-Pacific.
United States
E-commerce fulfillment velocity requirements from Amazon and DHL facilities drive automatic inline system adoption. FDA UDI traceability mandates for medical devices force validated thermal transfer configurations with 21 CFR Part 11-compliant audit logs. The US Gulf Coast chemical processing cluster specifies ribbon-based systems for GHS-compliant drum labeling with 10-year legibility requirements.
Germany
EU MDR traceability expansion pulls premium thermal transfer configurations into hospital supply chains and sterilization facilities across Bavaria and North Rhine-Westphalia. REACH compliance on adhesive substrates constrains material choices for manufacturers serving European healthcare markets. The Ludwigshafen chemical hub pilots UV-curable inkjet engines for on-demand color hazard communication at BASF and Dow facilities.
China
Battery supply chain marking demand accelerates for UN 38.3 lithium-ion transport regulations and emerging EU Battery Passport alignment. The country's national pharmaceutical regulator tightens track-and-trace requirements for active pharmaceutical ingredients. Yangtze River Delta cell manufacturing and recycling facilities specify high-temperature-resistant labels for electrode and module identification.
India
CDSCO track-and-trace mandates for active pharmaceutical ingredients create first-mover advantage for suppliers offering Hindi-localized software and 21 CFR Part 11 validation packages. Maharashtra and Gujarat pharmaceutical clusters drive demand for mid-volume semi-automatic systems with IQ/OQ/PQ documentation. Mumbai-Pune corridor contract manufacturers upgrade from manual to encoder-synchronized applicators for export compliance.
Japan
PMDA validation requirements for medical device manufacturers synchronize with FDA and EMA jurisdictions, extending commissioning cycles for multi-site pharmaceutical operations. Precision thermal printhead supply concentration among domestic component specialists exposes OEMs to 16-24 week lead time volatility. Kanto region logistics hubs standardize on cloud-native fleet management APIs for predictive maintenance subscription models.
Barcode Labeller Machine Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue cloud-native service models and sustainable substrate chemistry. The vendor base stratifies across three tiers: vertically integrated global platforms with captive component sourcing, regional specialists with precision print-engine partnerships, and cost-optimized assemblers competing on desktop unit economics. Strategic archetypes include validation-heavy healthcare suppliers, throughput-focused logistics integrators, and subscription-based servitized operators. Dominant competitive moves center on backward integration into precision thermal printheads and outcome-based service contracts with guaranteed uptime SLAs.
Among US-based diversified technology conglomerates, Honeywell International Inc. and Zebra Technologies Corporation exemplify vertically integrated global platforms with enterprise-grade thermal transfer installations. Japanese precision specialists including SATO Holdings Corporation and Toshiba TEC Corporation anchor Asian manufacturing networks with print-engine specialization and regional service density. These named entities represent distinct competitive archetypes rather than exhaustive market coverage, with each occupying positions that reflect their structural advantages in compliance depth, geographic reach, or cost positioning.
| Leading Market Players |
|---|
| Zebra Technologies Corporation |
| SATO Holdings Corporation |
| Toshiba TEC Corporation |
| Honeywell International Inc. |
| TSC Auto ID Technology Co., Ltd. |
| Brother Industries, Ltd. |
| Seiko Epson Corporation |
| Brady Corporation |
| Bixolon |
| Others |
Value Chain & Pricing Dynamics
Firmware engineering talent concentration in Japan's Kanto and Kansai industrial belts widens pricing-tier spreads, as OEMs absorb premium labor costs for ISO/IEC 15415-compliant print quality verification while cost-optimized desktop assemblers in Taiwan draw from lower-cost embedded systems labor pools.
Pricing Analysis
Input-cost pass-through from precision thermal printhead and piezoelectric inkjet component pricing shapes equipment margins across tiers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated healthcare systems from mid-volume logistics configurations and entry-level retail units. Pricing pressure stems from direct thermal commoditization in short-lifecycle shipping operations. SMEs exhibit highest price sensitivity; multi-site pharmaceutical manufacturers prioritize compliance certification depth over capital expenditure minimization.
Supply Chain Analysis
REACH and RoHS certification requirements gate European market access for adhesive substrate and electronic component suppliers. Manufacturing concentrates in Japan, Germany, and Taiwan, with precision print-engine assembly anchored in Japanese industrial corridors. Controller boards and HMI panels draw from foundry capacity in Taiwan and South Korea. Single-source vulnerability in thermal printhead supply exposes OEMs to lead time volatility. Distribution runs through vertically integrated global platforms with captive component sourcing and regional specialist networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on servitized ownership models displacing capital purchases, alongside premium-tier demand from FDA UDI and EU MDR compliance deadlines that insulate validated system suppliers from direct thermal commoditization.
For Market Incumbents: Cement platform stickiness through cloud-native fleet management API deployment and predictive maintenance subscription models that lock in third-party logistics networks. Deepen backward integration into precision thermal printheads to reduce exposure to Japanese and German component specialist lead times. Counter emerging servitized entrants by absorbing maintenance risk in outcome-based contracts with guaranteed uptime SLAs. For New Entrants and Emerging Players: Enter via India's CDSCO track-and-trace mandate window for active pharmaceutical ingredients, where Hindi-localized software and 21 CFR Part 11 validation packages command first-mover premiums. Target battery supply chain marking for UN 38.3 lithium-ion transport regulations and EU Battery Passport alignment in China's Yangtze River Delta cell manufacturing corridor. Pursue white-label partnerships with regional labelstock converters seeking REACH-compliant adhesive reformulation capabilities. For Investors and Strategic Acquirers: Valuations sit cheapest among cost-optimized desktop assemblers lacking servitized revenue streams, while premium-tier healthcare validation specialists trade at scarcity premiums. Long-term viability favors suppliers with telemetry sophistication and regional service density over hardware-centric margin profiles. Watch cloud-native fleet management API adoption rates in third-party logistics networks as the inflection signal for subscription revenue durability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Printheads | Captive thermal printhead production at Zebra and SATO reduces 16-24 week lead time exposure. |
| Cloud-Native Fleet Management Platform | Remote diagnostics APIs enable per-label pricing models with DHL and GXO Logistics. |
| REACH-Compliant Adhesive Reformulation | Alternative acrylic chemistries validate through migration testing for BASF and Dow chemical facilities. |
| 21 CFR Part 11 Validation Package | IQ/OQ/PQ documentation bundles capture FDA UDI mandate demand in German hospital supply chains. |
| UV-Curable Inkjet Engine Deployment | MEMS-controlled droplet placement at 600 dpi eliminates thermal ribbon inventory for GHS pictogram printing. |
Study Parameters
Multiple input streams — primary interviews with plant engineers and OEM procurement teams, aftermarket service heads and maintenance directors, regulatory affairs leads at medical device manufacturers — were reconciled against secondary validation from SEC filings, customs and trade data, FDA UDI registration databases, and EU MDR notified body documentation. Bottom-up equipment shipment tallies by product type and technology were cross-referenced against top-down market sizing from industry association disclosures.
Historical volume trajectories were cross-referenced against expert panel inputs across the analysis window. Segmentation modeling spanned product type, technology, application, and end-user scale dimensions. CAGRs were derived from slope-intercept analysis of annualized shipment values. Forecast inputs incorporated e-commerce fulfillment velocity requirements, regulatory compliance deadline clustering, and print-engine technology substitution curves.
Inputs from hospital procurement databases and GPO contracts were available through the study window; gaps in real-time cloud-native fleet management API adoption metrics introduce uncertainty bands around servitized revenue projections. Deviation in FDA UDI enforcement timelines or EU MDR notified body capacity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Piston Fillers Market
Packaging Machinery
Meter-Mix Dispensing Machine Market
Packaging Machinery
Powder Auger Fillers Market
Packaging Machinery
Candy Wrapping Machine Market
Packaging Machinery
Puffer Machines Market
Packaging Machinery
Meal Tray Sealing Machines Market
Packaging Machinery
Pillow Packing Machine Market
Packaging Machinery
Sliding Injection Molding Machine Market
Packaging Machinery
Liquid Filling Machines Market
Packaging Machinery
Bagging Machine Market
Packaging Machinery
Global Wrapping Machine Market
Packaging Machinery
Cartridge Filling System Market
Packaging Machinery
Bubble Wrap Machine Market
Packaging Machinery
Robotic Carton Loading Machine Market
Packaging Machinery
Food Powder Packaging Machine Market
Packaging Machinery
Lamination Systems Market