
 Automatic Filling Machine Market | 2026-2036
Automatic Filling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Filling Machine Market Outlook
Aftermarket service revenue is reconfiguring profit pools across the automatic filling machine landscape. Krones AG leverages its global installed base to capture recurring retrofit and spare parts contracts. GEA Group AG anchors its position through specialized pharma-grade aseptic filling systems with intensive R&D programs. Syntegon Technology GmbH competes by dominating intelligent inspection and digital line integration capabilities.
An automatic filling machine is a programmable industrial system that dispenses measured quantities of liquid, powder, granule, or tablet product into containers at speeds ranging from dozens to thousands of units per minute, employing pneumatic actuators, servo-driven pumps, or vacuum chambers to achieve precise volumetric or gravimetric accuracy for compliant packaging operations. Liquid fillers command the largest installed base due to beverage and pharmaceutical volume demand, while powder fillers represent the fastest-expanding segment as protein formulations and dry nutraceuticals multiply. Gravity filling technology leads in water and non-carbonated applications, though auger filling systems capture premium margins in pharmaceutical powder dosing where batch consistency mandates exceed standard tolerances.
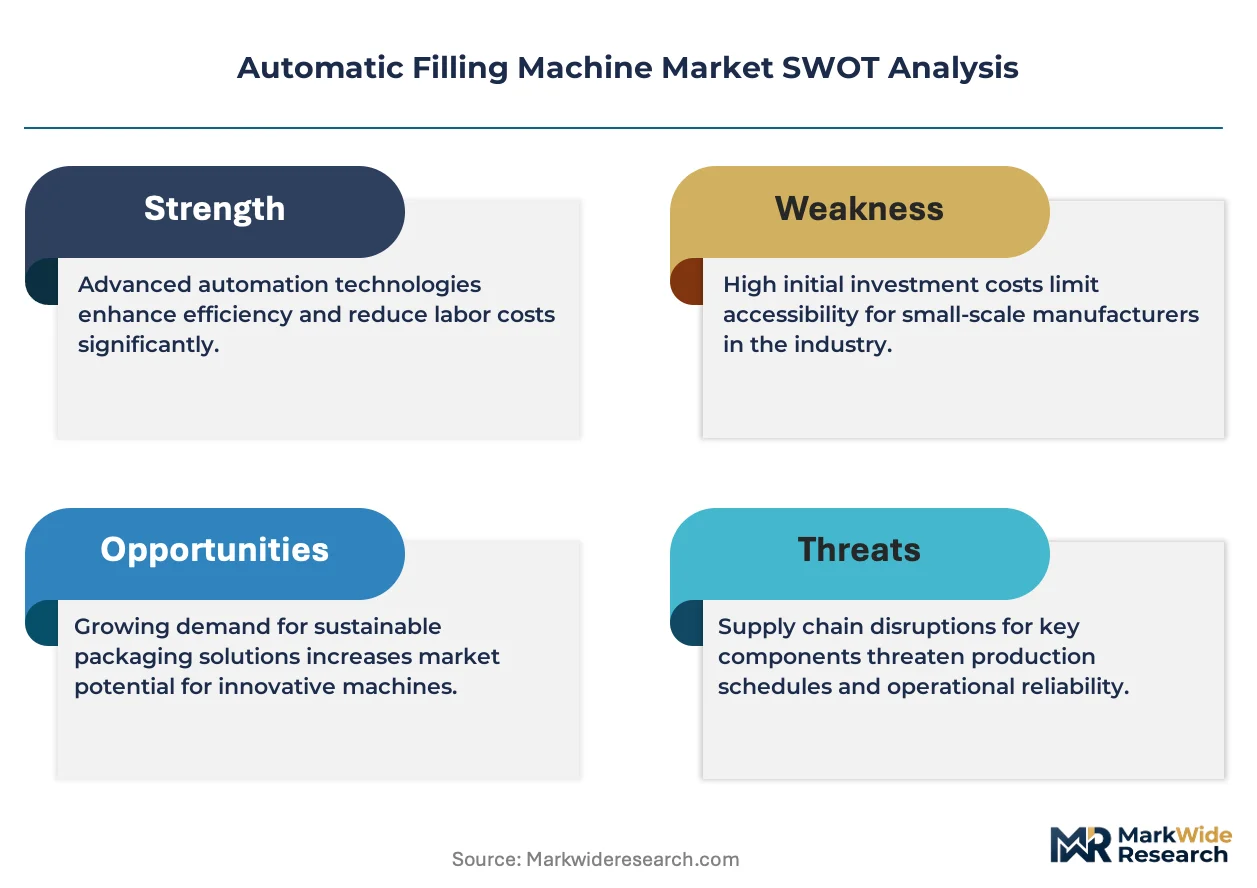
FDA validation requirements and EMA Annex 1 revisions on sterile manufacturing compel pharmaceutical producers to replace legacy equipment with isolator-integrated filling lines, directly accelerating replacement cycles. CE marking and EU MDR compliance for machinery safety and traceability further filter market access for non-European suppliers. Stakeholders must weigh total cost of ownership against modular upgrade paths as regulatory stringency diverges between aseptic pharmaceutical standards and conventional food-grade specifications.
Market Dynamics
Pharmaceutical batch integrity mandates and isolator-integrated aseptic requirements are compressing replacement cycles for legacy filling equipment across packaging lines.
Growth Catalysts
- FDA validation protocols:Sterile manufacturing requirements under 21 CFR Part 211 compel pharmaceutical producers to upgrade toward aseptic-ready systems with isolator integration.
- Protein formulations:Biologics and dry nutraceuticals multiply demand for auger filling systems capable of sub-milligram dosing precision.
- Germany precision clusters:Stuttgart and Bavaria engineering corridors concentrate servo-driven pump expertise that anchors European pharmaceutical equipment supply.
Market Restraints
- Stainless steel input volatility:Grade 316L pharmaceutical-grade alloy price swings compress margins for equipment fabricators dependent on consistent metallurgical specifications.
- Isolator lead times:Specialized containment barrier fabrication concentrates among limited European suppliers, extending delivery schedules for integrated lines.
- CE marking friction:EU MDR machinery safety and traceability compliance filters market access for non-European original equipment manufacturers.
Strategic Opportunities
- India CDMO expansion:Contract development and manufacturing organization capacity buildout creates demand for modular filling lines with rapid product changeover capabilities.
- Digital line integration:Convergence of machine vision inspection with servo-driven dosing enables real-time batch release protocols that reduce quarantine inventory.
- Aftermarket retrofit services:Spare parts and validation documentation contracts capture recurring revenue from installed bases aging past original warranty periods.
Industry Challenges
- Validation engineer scarcity:FDA 21 CFR Part 11 and EU Annex 15 computer systems validation expertise concentrates among specialists commanding premium compensation.
- Legacy SCADA integration:Proprietary communication protocols from 1990s-era filling lines resist seamless connectivity with modern manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Filling Machine Market |
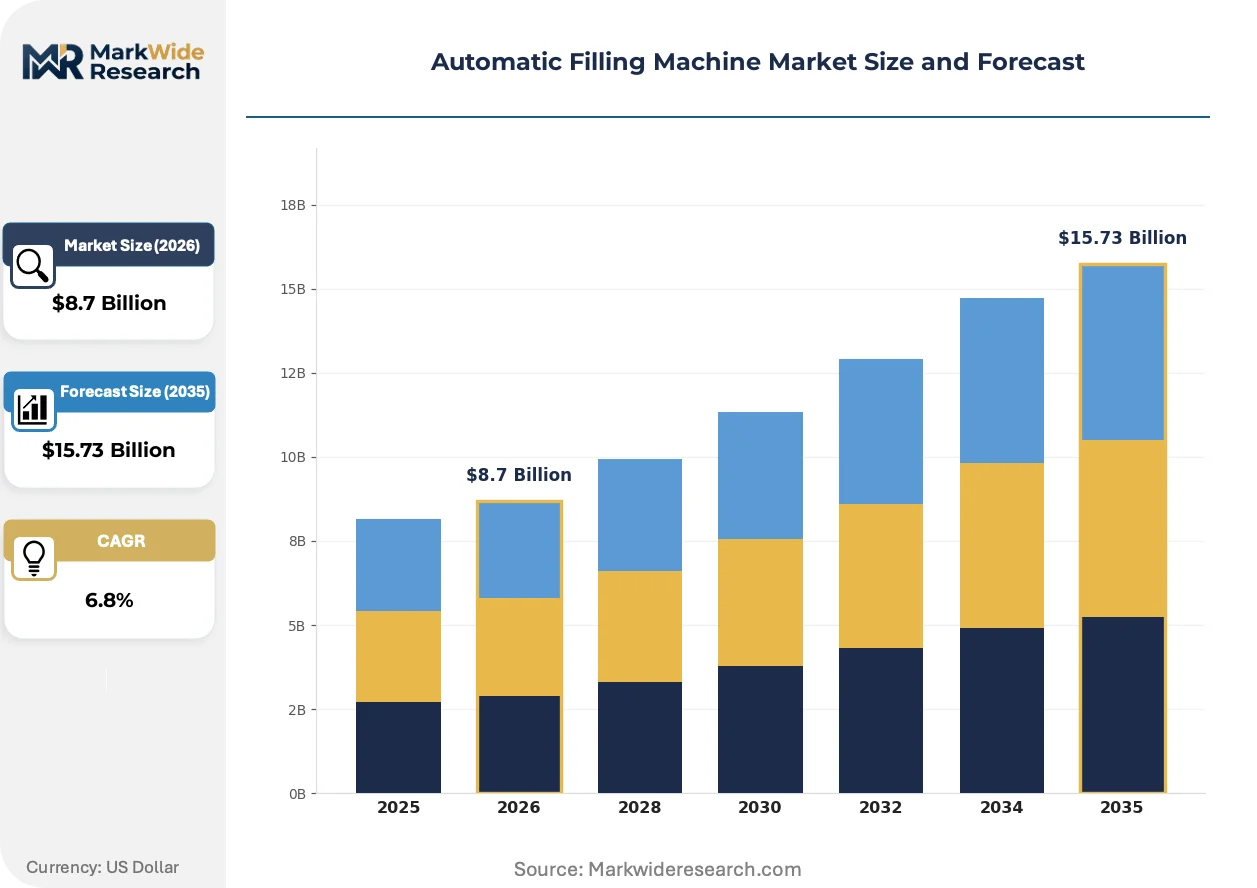
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Fillers, Powder Fillers, Granule Fillers, Tablet Fillers End User: Food & Beverage, Pharmaceutical, Cosmetics, Chemicals Technology: Gravity Filling, Pressure Filling, Vacuum Filling, Auger Filling Installation: Stationary, Portable, Semi-Automatic, Fully Automatic |
| Companies Covered | Krones AG, KHS GmbH, GEA Group AG, Syntegon Technology GmbH, ProMach Inc., JBT Corporation, Accutek Packaging Equipment Companies Inc., OPTIMA packaging group GmbH, IMA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Filling Machine Market Strategic Shifts
Single-use fluid path technologies and real-time release testing protocols are compressing the traditional boundary between production and quality assurance functions.
Disposable peristaltic pump tubing and bag assemblies are collapsing the cleaning validation burden that previously governed multi-product pharmaceutical filling suites. Contract manufacturers in North America and Western Europe adopt these systems to compress campaign changeover intervals from days to hours. The technology is collapsing capital allocation toward stainless steel permanent installations as finance teams favor operating expense models.
EMA Annex 1 revisions on sterile manufacturing mandate barrier technology and automated decontamination cycles for all new aseptic filling installations. Pharmaceutical producers interpret these requirements as prohibiting conventional cleanroom designs without isolator or restricted access barrier systems. Parenteral dosage form manufacturers in Germany, Switzerland, and Italy accelerate replacement timelines for open-filling legacy equipment.
Outcome-based service contracts tie equipment supplier compensation to operational availability metrics rather than discrete spare parts transactions. Large pharmaceutical consolidates procurement under enterprise agreements that bundle validation support, predictive maintenance, and regulatory documentation. This model concentrates in North American and European markets where internal engineering resources face pressure to outsource non-core technical functions.
Automatic Filling Machine Market Segmentation
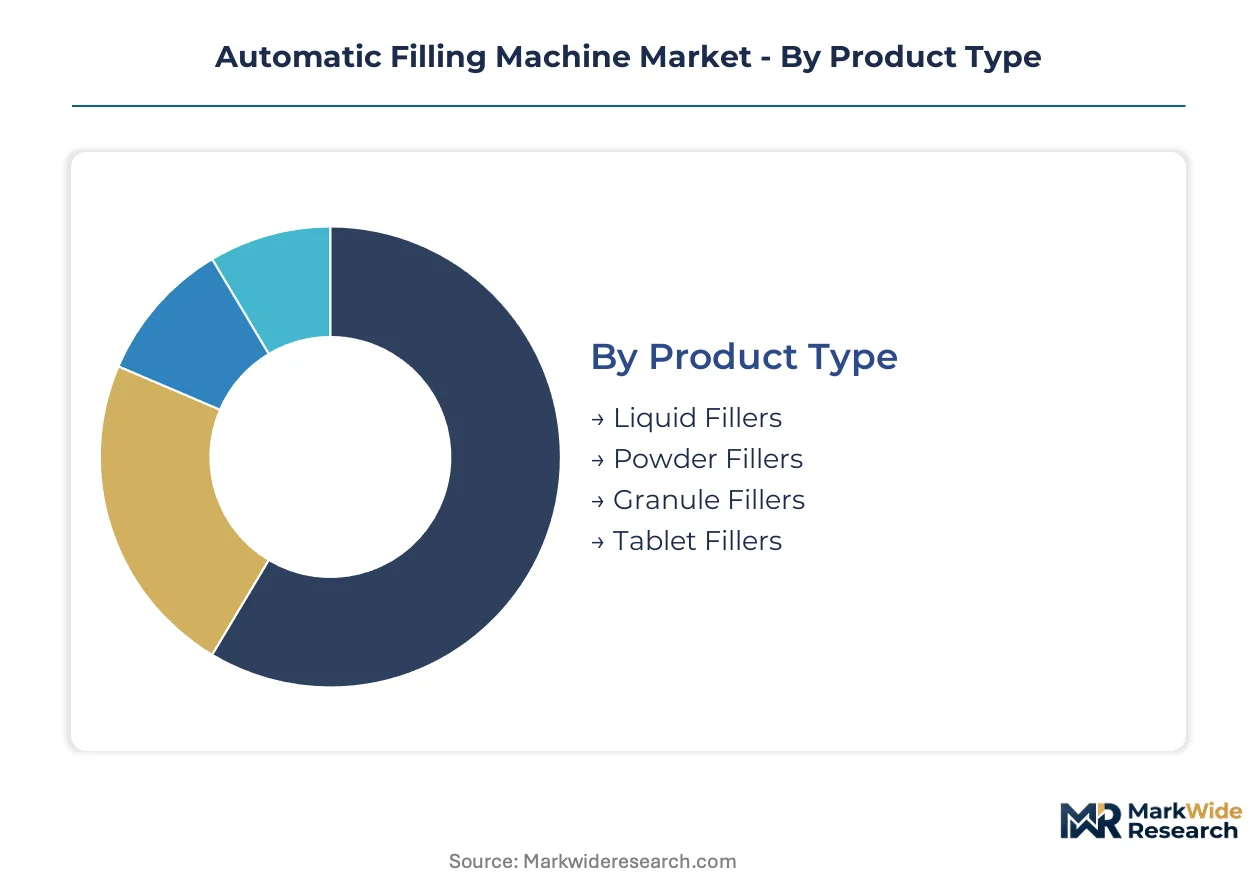
Automatic filling machine segmentation reveals divergent engineering requirements across product states and regulatory environments. Equipment specifications for sterile pharmaceutical liquids bear little resemblance to dry powder nutraceutical systems or carbonated beverage lines. Understanding these dimensional splits clarifies where capital allocation concentrates and which technology platforms capture margin premiums.
Product Type:
Mature liquid systems anchor the installed base while powder technologies emerge as the fastest-expanding frontier.
- Liquid Fillers:Pneumatic piston pumps and peristaltic systems dispense aqueous, viscous, or volatile formulations into vials, bottles, and ampoules. Beverage bottlers in Germany and pharmaceutical parenteral manufacturers in Switzerland drive replacement demand toward aseptic-ready isolator integration.
- Powder Fillers:Auger mechanisms and vacuum-assisted dosing achieve sub-milligram precision for protein formulations and dry nutraceuticals. Biologics contract manufacturers in India and North American CDMOs compress campaign changeover intervals through single-use fluid path adoption.
- Granule Fillers:Vibratory bowl and cup-filling systems handle free-flowing particulates for agricultural and chemical applications.
- Tablet Fillers:Counting-based rotary mechanisms integrate with blister packaging lines for solid oral dosage forms.
Liquid fillers handle the majority of throughput; powder fillers are the fastest mover on share.
End User:
Application intensity varies sharply between regulated life sciences and conventional industrial processing.
- Food & Beverage:High-speed rotary gravity fillers dominate water and juice bottling at throughputs exceeding 60,000 units per hour. Carbonated soft drink producers in Bavaria and mineral water bottlers in the Italian Alps prioritize servo-driven precision to minimize product giveaway.
- Pharmaceutical:Isolator-integrated aseptic lines command capital budgets exceeding conventional food-grade systems by multiples. EMA Annex 1 sterile manufacturing mandates and FDA 21 CFR Part 211 validation protocols compress replacement cycles for open-filling legacy equipment across Germany, Switzerland, and Italy.
- Cosmetics:Viscous cream and lotion fillers employ positive displacement pumps with heated product paths.
- Chemicals:Corrosion-resistant construction and explosion-proof actuators address aggressive solvent and flammable material handling.
Pharmaceutical applications absorb the highest capital intensity per line; food and beverage delivers the greatest unit volume.
Technology:
Cost tiers separate commodity gravity systems from precision auger platforms serving regulated dosing.
- Gravity Filling:Open-nozzle atmospheric dispensing suits thin, free-flowing liquids where fill accuracy tolerances remain relaxed. Water bottlers and non-carbonated beverage producers favor these systems for capital efficiency and minimal maintenance complexity.
- Pressure Filling:Counter-pressure mechanisms maintain carbonation integrity during high-speed beer and soft drink packaging. German brewing equipment specialists anchor global supply of these systems.
- Vacuum Filling:Negative-pressure chambers draw product into containers, enabling consistent fills for foamy or volatile formulations.
- Auger Filling:Rotating screw mechanisms dose dry powders with precision reaching ±1% by weight. Pharmaceutical batch consistency mandates and protein formulation complexity position these systems at the premium margin tier.
Gravity technology commands the broadest installed footprint; auger systems claim the steepest expansion trajectory.
Installation:
Customer type splits between high-volume stationary infrastructure and flexible semi-automatic configurations.
- Fully Automatic:Continuous motion rotary systems integrate unscrambling, filling, capping, and labeling at throughputs exceeding 200 units per minute. Large pharmaceutical consolidates and multinational beverage bottlers in Stuttgart engineering corridors standardize on these lines.
- Semi-Automatic:Operator-assisted indexing tables bridge manual and automatic operation for mid-scale contract manufacturers. Indian CDMO capacity buildout favors these configurations for rapid product changeover and lower capital commitment.
- Stationary:Fixed-base permanent installations dominate high-volume production environments.
- Portable:Skid-mounted and caster-based units enable flexible deployment across multi-product manufacturing suites.
Fully automatic lines absorb the majority of capital expenditure; semi-automatic configurations are expanding most quickly in emerging manufacturing geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Indian contract manufacturers prioritize semi-automatic configurations for capital efficiency, while German pharmaceutical producers absorb premium pricing for isolator-integrated aseptic lines without volume contraction.
Germany
Stuttgart and Bavaria engineering corridors concentrate servo-driven pump expertise for pharmaceutical-grade systems. EMA Annex 1 revisions on sterile manufacturing compel open-filling legacy replacements. Krones AG and Syntegon Technology GmbH anchor precision clusters serving parenteral dosage form producers across Baden-Württemberg.
United States
Biologics contract manufacturers in Massachusetts and North Carolina drive single-use fluid path adoption for protein formulation filling. FDA 21 CFR Part 211 validation protocols compress replacement cycles for legacy equipment. Boston-Cambridge biotech corridor demands real-time release testing integration for batch integrity assurance.
India
CDMO capacity buildout in Hyderabad and Ahmedabad creates demand for modular lines with rapid changeover capabilities. CDSCO pharmaceutical manufacturing regulations align with international GMP standards for export-oriented facilities. Gujarat pharmaceutical equipment fabricators specialize in cost-optimized semi-automatic configurations for emerging market price points.
Switzerland
Parenteral manufacturers in Basel and Zürich command the highest capital intensity per filling line globally. Swissmedic sterile manufacturing requirements exceed EMA baselines for local regulatory filing. Basel-Land canton hosts isolator-integrated system integration expertise serving global pharmaceutical consolidates.
China
Domestic vaccine producers in Jiangsu and Zhejiang provinces upgrade toward isolator-ready systems for international market access. NMPA Good Manufacturing Practice standards for biological products tighten equipment validation requirements. Yangtze River Delta pharmaceutical machinery clusters expand servo-driven dosing capabilities for biologics export compliance.
Automatic Filling Machine Market Competitive Environment
Capability concentration sits with precision-engineering specialists; scale advantage sits with diversified industrial conglomerates. The market structure divides between German-origin precision fabricators with isolator integration expertise and North American packaging integrators with beverage sector scale. Three archetypes dominate: servo-driven dosing specialists, aseptic barrier system integrators, and modular line configurators for contract manufacturing. M&A activity concentrates among pharmaceutical-grade capability acquisitions, while geographic expansion targets Indian CDMO procurement offices.
Among German-origin precision engineering groups, Krones AG, GEA Group AG, and Syntegon Technology GmbH occupy positions spanning beverage automation through pharmaceutical aseptic systems. These entities exemplify the capability-intensive tier where isolator integration and validation documentation bundling command margin premiums. Their geographic concentration in Stuttgart and Bavaria corridors reinforces technical talent access for FDA and EMA compliance engineering.
| Leading Market Players |
|---|
| Krones AG |
| KHS GmbH |
| GEA Group AG |
| Syntegon Technology GmbH |
| ProMach Inc. |
| JBT Corporation |
| Accutek Packaging Equipment Companies Inc. |
| OPTIMA packaging group GmbH |
| IMA Group |
| Others |
Value Chain & Pricing Dynamics
Stuttgart and Bavaria engineering corridors concentrate servo-driven pump fabrication capacity, granting German-origin fabricators substantial pricing power over pharmaceutical-grade aseptic systems. This geographic concentration of precision-engineering talent enables premium positioning for isolator-integrated lines while compressing margins for commodity gravity fillers sourced from lower-cost manufacturing zones.
Pricing Analysis
Aftermarket service contracts and spare parts revenue now drive lifetime value capture across the installed base. Three-tier pricing structure across premium isolator-integrated, standard servo-driven, and economy pneumatic systems reflects certification grade and validation documentation bundling. Cost compression in commodity liquid fillers is intensifying because stainless steel input volatility compresses fabricator margins. Contract manufacturers in India exhibit highest price sensitivity, while Swiss parenteral producers absorb premium positioning without volume contraction.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities now structure procurement relationships between European equipment fabricators and multinational pharmaceutical consolidates. Component sourcing draws from Germany for precision servo systems, Italy for isolator barrier fabrication, and China for standardized pneumatic actuators. Grade 316L pharmaceutical-grade alloy dependency creates single-source vulnerability for metallurgical specifications. Distribution runs through direct OEM sales forces for large pharmaceutical accounts and specialized equipment distributors for mid-scale CDMO procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive positioning as digital line integration and machine vision convergence create interoperability standards that reshape equipment procurement. Real-time batch release protocols and predictive maintenance bundling are compressing the traditional boundary between hardware vendors and pharmaceutical manufacturing operations.
For Market Incumbents: Entrench isolator integration expertise through captive supply of barrier system components and validation documentation bundling. Acquire specialized pharma-grade aseptic engineering talent in Basel and Stuttgart corridors to defend against modular line configurators. CE marking compliance investment anchors European market access against non-European entrants. For New Entrants and Emerging Players: Establish a beachhead in Indian CDMO semi-automatic configurations where rapid product changeover capabilities command procurement preference. Target Gujarat and Hyderabad equipment fabricators for cost-optimized modular lines with export-oriented GMP alignment. Lead with single-use fluid path integration as the go-to-market differentiator against legacy stainless steel permanent installations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors servo-driven dosing specialists with isolator integration capabilities over diversified beverage-scale conglomerates. Long-term viability hinges on outcome-based service contract penetration and recurring aftermarket revenue attachment. Watch FDA validation protocol stringency and EMA Annex 1 enforcement consistency as the primary inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Integration Partnership | EMA Annex 1 compliance mandates barrier technology for all new aseptic installations in Germany and Switzerland. |
| Single-Use Fluid Path Adoption | Biologics CDMOs in Massachusetts and North Carolina compress campaign changeover intervals from days to hours. |
| Outcome-Based Service Contract | Operational availability metrics tie supplier compensation to performance rather than discrete spare parts transactions. |
| Digital Line Integration Platform | Machine vision convergence with servo-driven dosing enables real-time batch release protocols reducing quarantine inventory. |
| Indian CDMO Geographic Expansion | Hyderabad and Ahmedabad capacity buildout creates demand for modular semi-automatic configurations with rapid changeover. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with equipment procurement managers, validation engineering directors, and aftermarket service heads at pharmaceutical manufacturers and CDMOs; and secondary validation through FDA 510(k) filings, EMA qualification reports, customs machinery trade data, and SEC equipment supplier disclosures. Bottom-up segmentation modeling triangulated against top-down macro pharmaceutical capital expenditure patterns anchored the value projections.
Forecast inputs considered product type segmentation across liquid, powder, granule, and tablet fillers; technology tier differentiation between gravity, pressure, vacuum, and auger systems; and end-user intensity variation between pharmaceutical, food and beverage, cosmetics, and chemical applications. CAGRs were derived from replacement cycle compression analysis under evolving FDA and EMA regulatory stringency. Isolator lead time dynamics and stainless steel input cost trajectories shaped the projection sensitivity bands.
Sensitivities concentrate around regulatory enforcement consistency for sterile manufacturing mandates and commodity alloy price volatility. Forecasts reflect documented assumptions regarding CDMO capacity expansion rates in India and biologics formulation growth in North America. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Vacuum Chamber Packaging Machines Market
Packaging Machinery
Stick Pack Packaging Machine Market
Packaging Machinery
Slitter Rewinder Machines Market
Packaging Machinery
Blind Box Machine Market
Packaging Machinery
Package Closing Machines Market
Packaging Machinery
Tube Sealing Machines Market
Packaging Machinery
Deblistering Machines Market
Packaging Machinery
Vertical Strapping Machines Market
Packaging Machinery
Kitchen/ Toilet Roll Converting Machines Market
Packaging Machinery
Stretch Blow Molding Machines Market
Packaging Machinery
Packaging Machine Heaters Market
Packaging Machinery
Cigarette Packaging Machine Market
Packaging Machinery
Vertical Injection Molding Machine Market
Packaging Machinery
Global Paper Napkin Making Machine Market
Packaging Machinery
Volumetric Boom Filling Machine Market
Packaging Machinery
Toilet Roll Converting Lines Market