
 Polyisoprene Latex Market | 2026-2036
Polyisoprene Latex Market Size, Share, and Industry Trends Forecast 2026-2036
Polyisoprene Latex Market Outlook
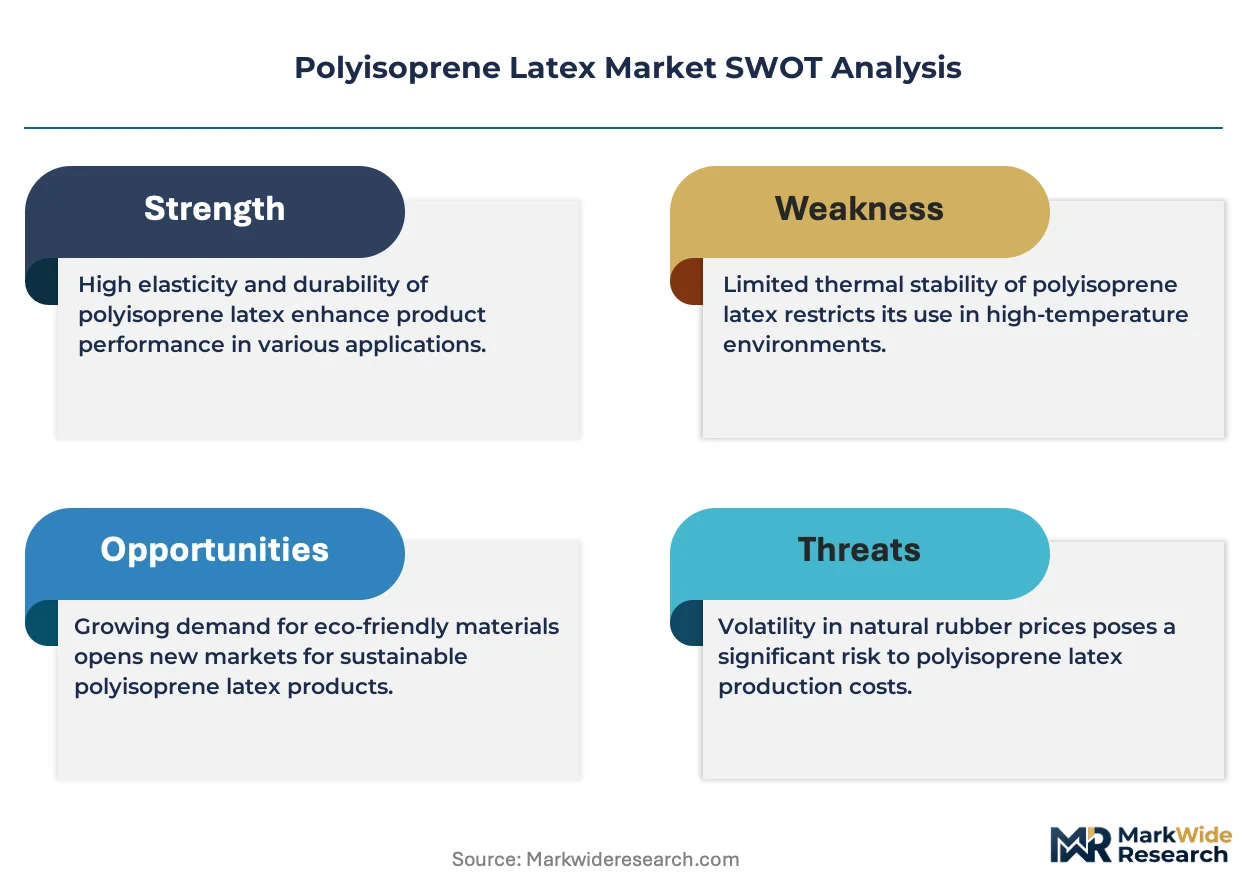
Specialized polymer chemist availability is unwinding capacity expansion timelines across Southeast Asian production hubs. Kuraray Co., Ltd. leverages captive isoprene monomer supply to maintain cost discipline in medical-grade latex. Zeon Corporation anchors its position through proprietary anionic polymerization technology that yields ultra-low protein content. Kraton Performance Polymers, Inc. competes by extending its Cariflex brand into high-purity pharmaceutical applications.
Polyisoprene latex is a synthetic elastomer dispersion produced through the emulsion polymerization of isoprene, yielding a cis-1,4-polyisoprene structure with tensile properties approximating natural rubber latex without allergenic proteins. The material serves as a critical input for thin-film dip-molded products, pressure-sensitive adhesives, and medical barrier devices requiring both elasticity and biocompatibility. Medical gloves command the dominant product type position, absorbing the majority of high-purity volumes, while adhesives represent the fastest-growing application segment as water-based formulations displace solvent systems in automotive assembly. Among end users, hospitals drive premium pricing through stringent certification requirements, whereas manufacturers in consumer goods extract value through volume scale and formulation flexibility.
FDA biocompatibility standards under ISO 10993 govern U.S. market access for medical-grade polyisoprene latex, while EMA's MDR framework imposes post-market surveillance obligations on European suppliers. China's NMPA and GB standards for medical rubber products create parallel compliance pathways that domestic producers like Puyang Linshi Chemical navigate with localized testing infrastructure. Stakeholders must monitor regulatory divergence between jurisdictions, as divergent protein-content thresholds and migration testing protocols will determine which production assets qualify for premium healthcare segments.
Market Dynamics
Medical device procurement teams are consolidating synthetic latex sourcing around certified supply chains as protein-content thresholds tighten under EU MDR and FDA biocompatibility protocols. This consolidation is compressing supplier margins while rewarding integrated producers with captive monomer supply.
Growth Catalysts
- EU MDR biocompatibility mandates:Post-market surveillance obligations are pushing European glove manufacturers toward certified synthetic latex with documented ultra-low protein content.
- Water-based adhesive displacement:Automotive assembly plants are replacing solvent-borne systems with polyisoprene latex formulations to meet volatile organic compound emission limits.
- Malaysian glove production clusters:Concentrated dip-molding capacity in Selangor and Penang is absorbing expanding volumes of medical-grade polyisoprene latex for export markets.
Market Restraints
- Isoprene monomer supply concentration:Feedstock availability is tightening as crackers prioritize ethylene production, elevating raw material cost volatility for latex producers without backward integration.
- Specialized polymer chemist scarcity:Southeast Asian production hubs face elongated commissioning timelines for new emulsion polymerization lines due to limited talent pools in anionic polymerization process control.
- Natural rubber latex price arbitrage:When Hevea brasiliensis harvests recover, price-sensitive consumer goods manufacturers revert to commodity natural rubber, eroding synthetic latex volume in non-medical segments.
Strategic Opportunities
- Pharmaceutical high-purity applications:Drug-device combination products requiring extractables and leachables compliance are opening premium pricing tiers for certified polyisoprene latex barrier components.
- China NMPA pathway localization:Domestic producers building GB-standard testing infrastructure can capture hospital procurement contracts previously held by imported medical-grade supply.
- Pressure-sensitive adhesive growth:Electronics manufacturing in Vietnam and Thailand is creating demand for clean-room compatible polyisoprene latex tapes and labels.
Industry Challenges
- ISO 10993 certification timeline compression:Extended biocompatibility study durations are delaying product launches for converters entering hospital supply chains.
- Anionic polymerization process control:Maintaining cis-1,4 microstructure consistency across batch scale-up requires rare expertise in living polymerization kinetics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyisoprene Latex Market |
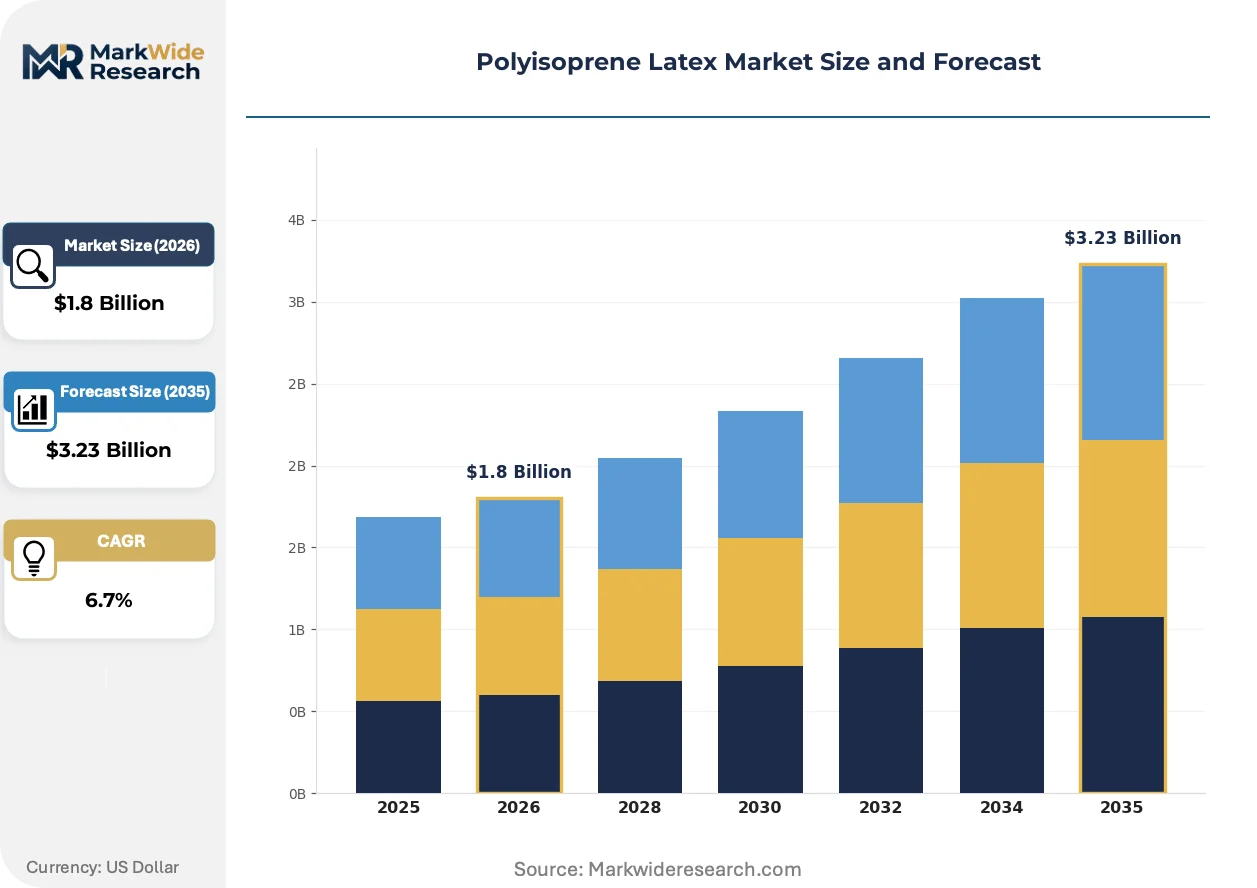
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Gloves, Adhesives, Coatings, Sealants Application: Healthcare, Automotive, Consumer Goods, Textiles End User: Hospitals, Manufacturers, Retailers, Laboratories Form: Liquid, Solid, Powdered, Foam |
| Companies Covered | Kuraray Co., Ltd., Zeon Corporation, JSR Corporation, Kraton Performance Polymers, Inc., Cariflex, Synthomer plc, Kent Elastomers, Puyang Linshi Chemical & New Material Co., Ltd., Dipped Products Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyisoprene Latex Market Strategic Shifts
Polyisoprene latex production technology is fragmenting into parallel tracks serving divergent end-use purity requirements. This technological divergence is reshaping capital allocation and competitive positioning across the supply base.
Emulsion polymerization reactor design is bifurcating between high-throughput continuous stirred-tank configurations for industrial adhesives and precision batch systems for medical-grade latex. Automotive Tier 1 suppliers are adopting the continuous formats for cost-sensitive pressure-sensitive adhesive lines. This split is compressing margins for mid-scale batch producers caught between volume and purity demands.
EMA's MDR framework is tightening post-market surveillance obligations on European medical device suppliers, requiring documented supply chain traceability for latex-derived components. Manufacturers must now maintain batch-level protein-content records across multi-year retention periods. Hospital procurement teams in Germany and France are responding by pre-qualifying only those converters with integrated testing laboratories.
Certification-driven preference shifts are concentrating hospital purchasing power around suppliers holding simultaneous FDA, ISO 10993, and EMA MDR registrations. Group purchasing organizations are narrowing approved vendor lists to reduce compliance audit burdens. This consolidation is most visible in U.S. acute care networks, where procurement committees now mandate synthetic latex documentation for all new glove contracts.
Polyisoprene Latex Market Segmentation
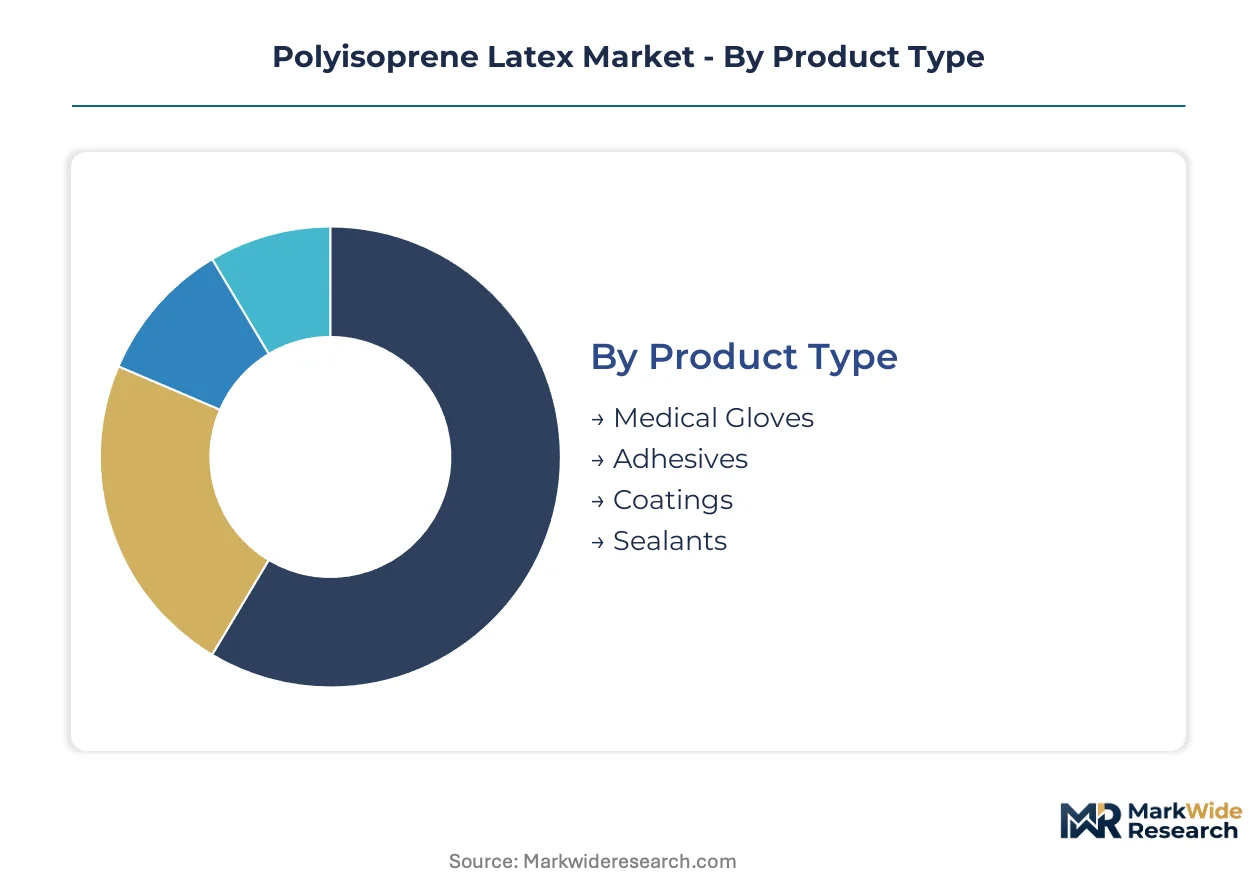
Polyisoprene latex demand fragments across purity grades, form factors, and certification tiers that command radically different margin structures. Procurement teams in medical device supply chains enforce strict segmentation protocols that determine which production assets qualify for premium pricing pools.
Product Type:
Medical-grade specifications capture the deepest margin pools, while industrial formulations compete on throughput scale and raw material efficiency.
- Medical Gloves:High-purity emulsion polymerization yields ultra-low protein content meeting FDA biocompatibility and EU MDR traceability mandates. Hospital procurement networks in Germany and the United States concentrate demand around certified converters with integrated ISO 10993 testing laboratories, compressing supplier margins while rewarding backward-integrated producers.
- Adhesives:Water-based polyisoprene latex displaces solvent-borne systems in automotive assembly plants facing volatile organic compound emission limits. Tier 1 suppliers in Vietnam and Thailand are adopting continuous stirred-tank reactor formats for cost-sensitive pressure-sensitive adhesive lines serving electronics manufacturing clean rooms.
- Coatings:Barrier films and protective layers for industrial textiles and packaging substrates.
- Sealants:Elastic joint compounds for construction and transportation applications requiring weather resistance.
The dominant share belongs to Medical Gloves, while Adhesives is closing the gap fastest as automotive water-based formulation mandates expand.
Application:
End-use concentration patterns split between regulated healthcare procurement and cost-driven industrial adoption cycles.
- Healthcare:Surgical and examination glove manufacturing absorbs the majority of high-purity volumes under stringent biocompatibility protocols. Malaysian production clusters in Selangor and Penang process expanding medical-grade latex imports for export markets, with procurement teams consolidating around certified supply chains.
- Automotive:Assembly plants replace solvent systems with polyisoprene latex adhesives to meet emission regulations. The shift toward electric vehicle manufacturing is amplifying demand for lightweight bonding solutions in battery module assembly and interior component attachment.
- Consumer Goods:Price-sensitive manufacturers revert to natural rubber latex when Hevea brasiliensis harvests recover.
- Textiles:Fabric coatings and elastic thread applications in apparel and technical textiles.
Healthcare commands the revenue concentration, yet Automotive exhibits the steepest expansion trajectory as water-based mandates tighten across manufacturing jurisdictions.
End User:
Purchasing power aggregates around institutions with compliance audit capabilities versus volume buyers extracting formulation flexibility.
- Hospitals:Acute care networks mandate synthetic latex documentation for all new glove contracts, narrowing approved vendor lists to reduce compliance burdens. Group purchasing organizations in the United States pre-qualify only converters holding simultaneous FDA, ISO 10993, and EMA MDR registrations.
- Manufacturers:Industrial formulators in consumer goods and automotive segments prioritize volume scale and raw material cost stability over certification premiums.
- Retailers:Distributors serving small-scale buyers and specialty product channels.
- Laboratories:Research and diagnostic facilities requiring small-batch high-purity supply.
Hospitals extract the steepest certification premiums, while Manufacturers generate the highest absolute volume throughput.
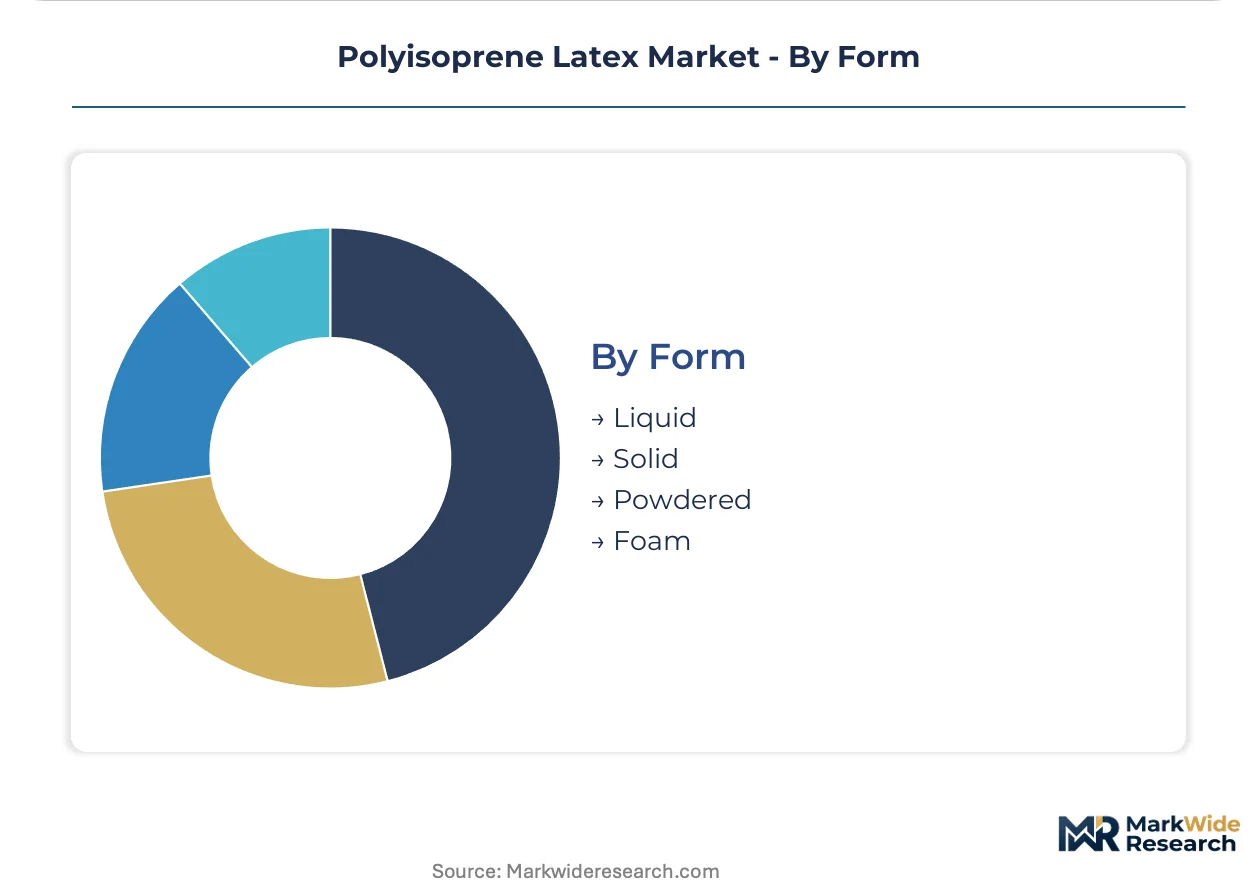
Form:
Physical state determines handling infrastructure, storage protocols, and compatibility with downstream processing equipment.
- Liquid:Standard emulsion dispersions for dip-molding and coating processes dominate medical glove and adhesive manufacturing. Malaysian glove producers operate dedicated liquid latex receiving terminals adjacent to Selangor and Penang production facilities.
- Solid:Crumb or bale forms for compounding and custom formulation by specialized rubber processors.
- Powdered:Dried particulate for specific compounding applications and geographic markets with distinct handling preferences.
- Foam:Expanded cellular structures for cushioning, sealing, and insulation applications in automotive and consumer goods.
Liquid maintains the installed base dominance, though Solid forms are gaining share in regional compounding hubs seeking supply security.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA biocompatibility protocols under ISO 10993 anchor the United States as the dominant geography for premium medical-grade polyisoprene latex procurement. Hospital group purchasing organizations concentrate purchasing power around certified supply chains. Production clusters across four additional countries shape regional supply dynamics.
United States
Acute care networks in Texas and California mandate synthetic latex documentation for all new glove contracts under FDA biocompatibility surveillance. The EPA volatile organic compound emission limits push automotive assembly plants toward water-based adhesive formulations. Michigan and Ohio production facilities process expanding volumes for battery module assembly in electric vehicle manufacturing.
Malaysia
Selangor and Penang glove production clusters absorb significant medical-grade polyisoprene latex volumes from Japanese and Korean suppliers. The country's national pharmaceutical regulator enforces post-market surveillance obligations aligned with EU MDR traceability standards. Port Klang logistics hubs coordinate export distribution to European and North American hospital procurement networks.
Germany
EMA MDR framework requirements tighten biocompatibility testing protocols for medical devices entering German hospital supply chains. Bavaria and North Rhine-Westphalia host integrated testing laboratories that pre-qualify converters for group purchasing organization vendor lists. Stuttgart automotive assembly plants displace solvent-borne adhesive systems with polyisoprene latex formulations.
China
NMPA GB standards for medical rubber products create parallel compliance pathways that domestic producers navigate with localized testing infrastructure. Yangtze River Delta pharmaceutical manufacturers demand high-purity barrier components for drug-device combination products. Shandong Province chemical clusters expand emulsion polymerization capacity for regional adhesive markets.
Japan
METI industrial standards govern pressure-sensitive adhesive quality specifications for electronics manufacturing applications. Kansai and Chubu regions concentrate polymer chemistry expertise for anionic polymerization process control. Osaka-based suppliers maintain captive isoprene monomer supply chains for medical-grade latex production.
Polyisoprene Latex Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the polyisoprene latex supply base. The market structure concentrates around backward-integrated chemical conglomerates and specialized polymer producers with proprietary process control. Three archetypes dominate: captive monomer suppliers with integrated latex production, licensing-focused technology specialists, and regional compounders serving cost-sensitive industrial segments. Capacity expansion and certification-driven portfolio diversification represent the dominant competitive moves as procurement teams consolidate around qualified supply chains.
Within the technology-specialist tier, Zeon Corporation and Kuraray Co., Ltd. exemplify players with proprietary polymerization capabilities. Kraton Performance Polymers, Inc. occupies a position bridging medical-grade purity requirements and industrial-scale adhesive applications. These three anchors demonstrate how process control expertise and captive feedstock access determine qualification for premium healthcare procurement segments.
| Leading Market Players |
|---|
| Kuraray Co., Ltd. |
| Zeon Corporation |
| JSR Corporation |
| Kraton Performance Polymers, Inc. |
| Cariflex |
| Synthomer plc |
| Kent Elastomers |
| Puyang Linshi Chemical & New Material Co., Ltd. |
| Dipped Products Plc |
| Others |
Value Chain & Pricing Dynamics
Water-based adhesive displacement in automotive assembly simultaneously redraws supply geography toward Southeast Asian electronics corridors and compresses formulation economics for mid-tier producers caught between medical-grade purity premiums and industrial volume scale.
Pricing Analysis
Japanese and Korean suppliers command spreads against Southeast Asian compounders due to captive isoprene monomer supply and integrated ISO 10993 testing infrastructure. Three-tier pricing structure across medical-grade, industrial-grade, and commodity-grade levels separates certified hospital procurement from automotive adhesive volumes and price-sensitive consumer goods applications. Cost compression in industrial tiers is intensifying because Malaysian glove clusters negotiate consolidated offtake agreements. Automotive manufacturers exhibit highest price sensitivity, while hospital GPOs absorb certification premiums without volume elasticity.
Supply Chain Analysis
Isoprene monomer supply concentration in Japanese petrochemical complexes and Korean cracking facilities creates feedstock vulnerability for non-integrated latex producers. Malaysia, Thailand, and Vietnam concentrate dip-molding capacity and electronics assembly demand. Raw material flows draw from Japanese isoprene refiners, Korean polymerization specialists, and Chinese compounding hubs. Single-source vulnerability runs through Kuraray and Zeon captive supply networks. Distribution runs through Port Klang logistics terminals and regional chemical distributor networks serving Selangor glove producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyisoprene latex incumbents face substitution defense against nitrile and polyurethane alternatives in medical barrier applications, requiring portfolio repositioning around biocompatibility certification moats.
For Market Incumbents: Consolidate backward integration into isoprene monomer supply to offset feedstock volatility from ethylene cracker prioritization shifts. Deepen ISO 10993 and EU MDR certification assets to defend hospital procurement relationships against nitrile glove substitution in European acute care networks. For New Entrants and Emerging Players: Lead with China NMPA pathway localization to capture domestic hospital contracts previously held by imported medical-grade supply. Target pharmaceutical high-purity applications for drug-device combination products, leveraging extractables and leachables compliance as differentiation wedge against established industrial-grade suppliers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Malaysian glove manufacturers seeking polymerization technology upgrades. Five-to-ten year viability hinges on regulatory divergence between FDA, EMA, and NMPA biocompatibility protocols. Watch for EU MDR protein-content threshold tightening as inflection signal for synthetic latex preference acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isoprene Monomer | Kuraray and Zeon demonstrate how captive feedstock supply insulates margin structures from cracker output volatility. |
| ISO 10993 Testing Laboratory Integration | Hospital GPOs in Texas and California pre-qualify only converters with in-house biocompatibility validation capabilities. |
| China NMPA GB-Standard Certification | Domestic producers like Puyang Linshi Chemical capture procurement contracts through localized compliance infrastructure. |
| Continuous Stirred-Tank Reactor Scale-Up | Automotive Tier 1 suppliers in Vietnam adopt high-throughput formats for cost-sensitive pressure-sensitive adhesive lines. |
| Pharmaceutical High-Purity Grade Development | Drug-device combination product demand opens premium pricing tiers for extractables and leachables certified supply. |
Study Parameters
Cross-validation between primary interviews with polymer chemists, glove manufacturing procurement leads, automotive adhesive formulators, and hospital GPO contract managers and secondary sources including FDA 510(k) filings, EMA MDR technical documentation, Malaysian customs export records, and SEC filings from listed chemical producers anchors the qualitative findings. Bottom-up capacity assessments from Selangor and Penang production facilities triangulate against top-down demand modeling from healthcare procurement databases.
Sensitivity analysis across isoprene monomer price scenarios, EU MDR implementation timelines, and natural rubber latex harvest recovery patterns informs the analytical framework. Segmentation dimensions include purity grade tier, end-use industry vertical, geographic production hub, and certification status. CAGRs derive from installed capacity expansion announcements, hospital procurement contract durations, and automotive water-based adhesive mandate adoption curves. Forecast inputs incorporate Malaysian glove cluster utilization rates and Chinese pharmaceutical manufacturing growth trajectories.
The analysis sits within stated boundaries; outcomes outside sustained EU MDR enforcement intensity, continued FDA biocompatibility surveillance, or stable isoprene feedstock availability would require recalibration. Forecasts reflect assumptions regarding certification timeline compression and specialized polymer chemist scarcity persistence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
BMI Resins Market
Polymers & Resins
Polymer Microinjection Molding Market
Polymers & Resins
Global Epoxy Primer Market
Polymers & Resins
Europe Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
North America Super Absorbent Polymers (SAP) Market
Polymers & Resins
Bio-Based Polypropylene Market
Polymers & Resins
Polyamide-Imide (PAI) Market
Polymers & Resins
Gel Polymer Electrolytes Market
Polymers & Resins
Fluorinated Polyimide Market
Polymers & Resins
South America Thermoplastics Market
Polymers & Resins
Basic Methacrylate Copolymer Market
Polymers & Resins
Agar Resin Market
Polymers & Resins
Orthophthalic Resins Market
Polymers & Resins
Africa Polyether Ether Ketone (PEEK) Market
Polymers & Resins
Rigid Colored PU Foam Market
Polymers & Resins
Plastisols Market