
 Polylactic Acid Market | 2026-2036
Polylactic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Polylactic Acid Market Analysis
Advanced fermentation and polymerization is reconfiguring how lactic acid transforms into high-performance bioplastics at commercial scale. NatureWorks LLC leverages its integrated corn-to-PLA supply chain to dominate North American food packaging grades. TotalEnergies Corbion anchors European production through its Thai sugarcane feedstock operations and Rotterdam finishing capacity. Zhejiang Hisun Biomaterials Co., Ltd. competes on cost-optimized fermentation routes serving Asian textile and consumer goods markets.
Polylactic acid is an aliphatic polyester synthesized from renewable biomass feedstocks, typically exhibiting a glass transition temperature near 60°C and melting point around 155-170°C depending on stereochemical purity. It functions primarily as a drop-in replacement for conventional petroleum-derived plastics in thermoformed articles, melt-spun fibers, and extruded films. Among applications, packaging commands the largest volume position due to compostable food-service mandates, while medical supplies represent the highest-margin segment where sterilizable PLA variants command premium pricing. Films and fibers are gaining structural share as downstream converters develop barrier-coated and high-tenacity variants for performance-sensitive uses.
The EU Green Deal and F-Gas Regulation in Europe, alongside FDA food-contact notifications in the United States and BIS biopolymer standards in India, collectively shape product certification requirements and market access conditions for PLA manufacturers. ECHA REACH compliance adds testing burdens for imported resins, while China's GB standards and dual carbon goals redirect domestic capacity toward certified biodegradable grades. Stakeholders must monitor how divergent composting infrastructure investments across Germany, the United States, and China determine which PLA formulations achieve viable end-of-life economics.
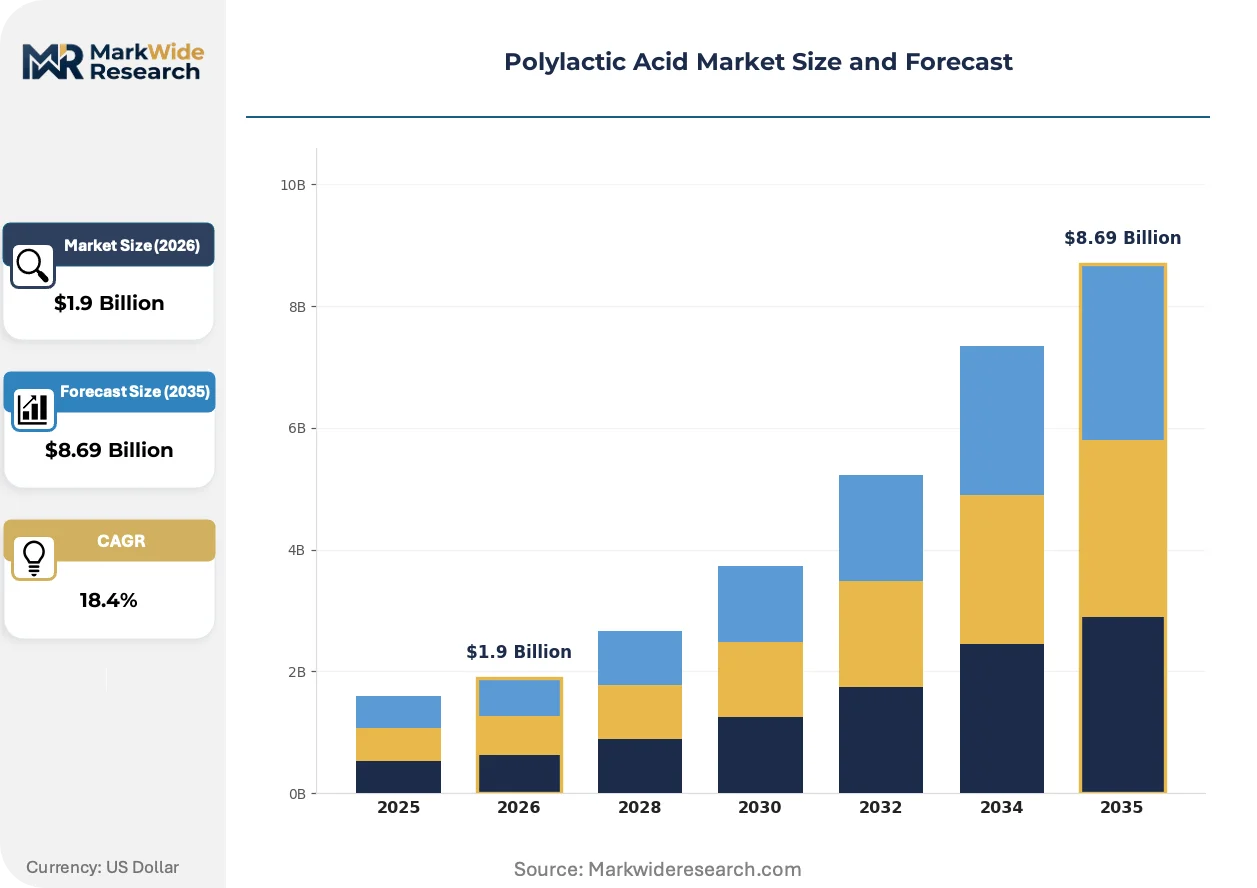
Market Dynamics
EU Green Deal mandates and F-Gas Regulation enforcement are compressing the substitution timeline for petroleum-based packaging, forcing converters to validate PLA formulations against industrial composting infrastructure before legacy resin contracts expire.
Growth Catalysts
- EU Green Deal packaging mandates:Brussels has set binding biopolymer content thresholds for food-contact applications, compelling German and French converters to accelerate PLA tray and film qualification programs.
- High-purity lactide polymerization:Advances in stereochemical control now yield PLA grades with melting points above 165°C, opening thermoformed hot-fill packaging to PLA substitution.
- Thailand:Government sugarcane-ethanol diversion policies have expanded feedstock availability for lactic acid fermentation, anchoring Southeast Asian export capacity.
Market Restraints
- Corn price volatility:NatureWorks and North American producers remain exposed to Midwest grain futures, compressing margin visibility across quarterly production cycles.
- Rotterdam-Thai supply concentration:TotalEnergies Corbion's integrated sugarcane-to-PLA chain controls a disproportionate share of European food-grade resin, creating single-source vulnerability.
- Industrial composting scarcity:Fewer than twelve German municipalities operate the sustained thermophilic conditions required for PLA disintegration, limiting end-of-life viability claims.
Strategic Opportunities
- Indian textile spinning:BIS biopolymer certification and DGFT preferential tariff structures position PLA fiber as a cotton displacement candidate in Surat and Tiruppur weaving clusters.
- Sterilizable medical grades:Gamma-stable PLA variants for surgical sutures and orthopedic implants command pricing multiples above packaging resins, attracting fermentation specialists.
- Barrier-coated flexible films:Convergence of atomic layer deposition and PLA substrate casting enables oxygen transmission rates competitive with EVOH laminates for modified-atmosphere produce packaging.
Industry Challenges
- Food-contact notification timelines:FDA pre-market clearance for novel PLA copolymers stretches eighteen to thirty months, delaying commercialization of high-heat formulations.
- Skilled fermentation engineers:The lactic acid-to-PLA value chain requires hybrid expertise in industrial microbiology and polymer rheology that university programs have not scaled to match capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polylactic Acid Market |
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $8.69 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Resins, Films, Fibers Application: Packaging, Textiles, Medical Supplies, 3D Printing End User: Food Industry, Textile Industry, Healthcare Sector, Consumer Goods Distribution Channel: Online Retail, Brick-and-Mortar Stores, Wholesalers, Direct Sales |
| Companies Covered | NatureWorks LLC, TotalEnergies Corbion, BASF SE, Futerro, COFCO, Zhejiang Hisun Biomaterials Co., Ltd., Toray Industries, Inc., Evonik Industries, Mitsubishi Chemical Group Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polylactic Acid Market Emerging Trajectories
Active fermentation optimization and downstream polymer architecture engineering are compressing the performance gap between biobased and petroleum-derived thermoplastics, with particular intensity in barrier properties and thermal stability.
Ring-opening polymerization catalysts are migrating from tin-based systems to organometallic zirconium complexes that yield higher molecular weight PLA with reduced residual lactide. Packaging converters in the Netherlands and Belgium are adopting these grades for thermoformed deli containers that must withstand microwave reheating. The technology is migrating from laboratory-scale demonstration to commercial lines at rates that outpace regulatory update cycles.
ECHA REACH compliance for imported PLA resins now requires comprehensive substance identity dossiers covering oligomer content and additive migration profiles. This regulatory burden has redirected Asian export volumes toward domestic Chinese certification under GB standards rather than European registration. Medical device manufacturers face the steepest documentation requirements, as EMA biocompatibility expectations layer onto base polymer registration.
Food-service distributors are consolidating purchasing authority into centralized procurement platforms that specify compostability certification as a non-negotiable bid criterion. Independent operators and regional converters without BPI or OK Compost INDUSTRIAL marks are losing shelf placement to certified competitors. This concentration is most visible in German and Austrian food retail, where REWE and Spar Group banner standards have eliminated conventional PS and PET alternatives from private-label food packaging tenders.
Polylactic Acid Market Segmentation
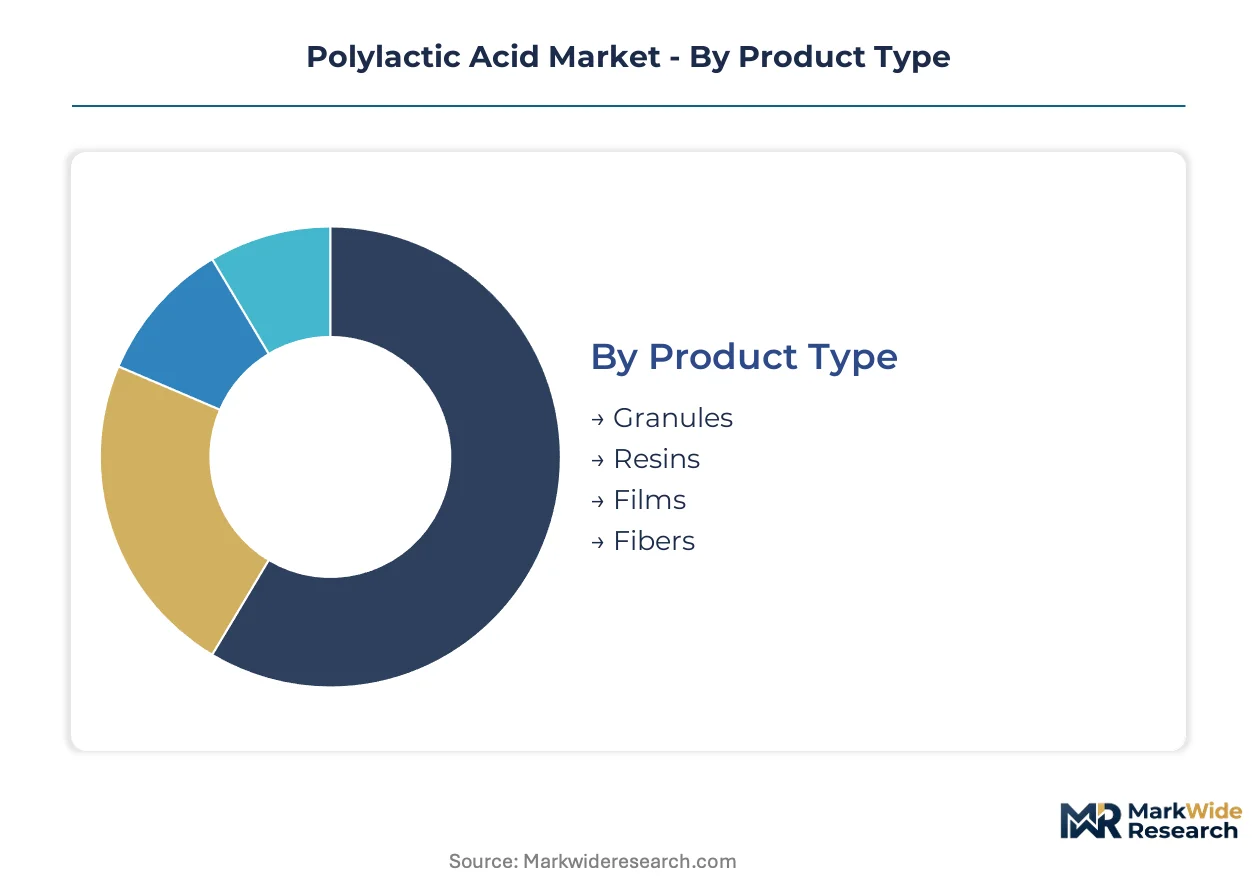
Polylactic acid segmentation reveals divergent margin structures across physical forms and end-use applications. Each category carries distinct inventory velocity, certification burden, and customer concentration that reshapes go-to-market economics for resin suppliers.
Product Type:
Granules turn inventory fastest through toll compounding arrangements, while medical-grade resins sit in validation queues for quarters before first shipment.
- Granules:Pelletized PLA with controlled particle size distribution feeds thermoforming and injection molding lines. German packaging converters specify food-contact certified granules under EU Green Deal biopolymer mandates for deli tray production.
- Resins:Unfinished polymer intermediate requiring downstream processing into final articles. Thailand's sugarcane-derived resin output anchors European food-grade supply through Rotterdam finishing operations.
- Films:Extruded sheet and blown film grades for flexible packaging applications.
- Fibers:Melt-spun filament and staple for textile weaving and nonwoven production.
Granules dominate installed base. Resins are where expansion concentrates.
Application:
Packaging absorbs volume at commodity margins, while medical applications sustain pricing multiples through sterilization certification barriers.
- Packaging:Thermoformed trays, films, and food-service items displacing petroleum-based plastics. REWE and Spar Group tender requirements in Germany and Austria have eliminated non-compostable alternatives from private-label procurement.
- Medical Supplies:Surgical sutures, orthopedic implants, and drug delivery systems requiring gamma-stable PLA variants. EMA biocompatibility expectations layer onto base polymer registration, extending qualification timelines.
- Textiles:Fiber and fabric applications competing with cotton and polyester in spinning operations.
- 3D Printing:Filament feedstock for fused deposition modeling in prototyping and small-batch manufacturing.
Packaging commands volume leadership. Medical supplies capture margin expansion.
End User:
Food industry procurement runs on annual contract cycles with compostability certification as gatekeeper, while healthcare sector purchasing stretches across multi-year validation programs.
- Food Industry:Processors and distributors specifying PLA for direct food contact. BPI and OK Compost INDUSTRIAL marks have become non-negotiable bid criteria for centralized food-service procurement platforms.
- Healthcare Sector:Hospitals, device manufacturers, and pharmaceutical companies requiring sterilizable grades. FDA pre-market clearance for novel PLA copolymers stretches eighteen to thirty months.
- Textile Industry:Spinning mills and weaving clusters in Surat and Tiruppur evaluating PLA fiber as cotton displacement under BIS biopolymer certification.
- Consumer Goods:Durable and disposable items targeting environmentally positioned retail channels.
Food industry anchors current offtake. Healthcare sector represents the steepest expansion trajectory.
Distribution Channel:
Direct sales concentrate among large-volume food packagers with technical service requirements, while online retail fragments across small-batch 3D printing filament purchasers.
- Direct Sales:Long-term supply agreements between PLA producers and major converters. NatureWorks and TotalEnergies Corbion anchor volume through captive relationships with North American and European packaging leaders.
- Wholesalers:Regional distributors stocking standard grades for mid-tier processors.
- Online Retail:E-commerce platforms serving filament buyers and small-scale manufacturers.
- Brick-and-Mortar Stores:Physical distribution for craft, hobby, and educational material segments.
Direct sales lock in foundation volumes. Online retail is climbing the fastest among channel alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand exports sugarcane-derived resin through Rotterdam to supply German and French packaging converters under EU Green Deal mandates. This trade corridor anchors European food-grade PLA procurement while Midwest corn streams feed North American thermoforming operations.
United States
Midwest grain processors supply NatureWorks with corn feedstock for integrated PLA production. FDA food-contact notifications govern resin qualification timelines for thermoformed food-service items. Minneapolis-St. Paul packaging clusters validate compostable tray formulations against BPI certification standards.
Germany
REWE and Spar Group procurement tenders mandate OK Compost INDUSTRIAL marks for private-label packaging. EU Green Deal biopolymer thresholds accelerate converter qualification programs. Industrial composting infrastructure in Bavaria and Baden-Württemberg sustains end-of-life viability claims for deli container applications.
Thailand
Government sugarcane-ethanol diversion policies expanded lactic acid fermentation feedstock availability. TotalEnergies Corbion anchors Southeast Asian export capacity through integrated sugarcane-to-PLA operations. Rayong province hosts finishing capacity serving Rotterdam distribution.
China
GB standards and dual carbon goals redirect domestic capacity toward certified biodegradable grades. Zhejiang Hisun Biomaterials competes on cost-optimized fermentation routes. Yangtze River Delta textile clusters evaluate PLA fiber as cotton displacement for export garment production.
India
BIS biopolymer certification and DGFT preferential tariff structures position PLA fiber in Surat and Tiruppur weaving clusters. FSSAI food-contact standards govern import resin qualification for food-service applications. Maharashtra packaging converters pilot thermoformed tray production for domestic quick-service restaurant chains.
Polylactic Acid Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. The vendor base clusters around three strategic archetypes: integrated agribusiness-to-polymer operators, standalone fermentation specialists, and diversified chemical conglomerates with biopolymer divisions. Capacity expansion and strategic partnerships dominate competitive moves as producers secure feedstock offtake and distribution access.
Within the integrated operator tier, NatureWorks LLC and TotalEnergies Corbion exemplify channel-controlling positions through captive feedstock and finishing capacity. Zhejiang Hisun Biomaterials Co., Ltd. occupies a cost-optimized specialist position serving Asian textile markets. BASF SE represents diversified chemical conglomerate participation through portfolio diversification into biodegradable polymer segments.
| Leading Market Players |
|---|
| NatureWorks LLC |
| TotalEnergies Corbion |
| BASF SE |
| Futerro |
| COFCO |
| Zhejiang Hisun Biomaterials Co., Ltd. |
| Toray Industries, Inc. |
| Evonik Industries |
| Mitsubishi Chemical Group Corporation |
| Others |
Supply Flow & Price Mechanics
Rayong province fermentation complexes anchor Southeast Asian resin output, and their capacity utilization rates directly dictate pricing leverage for European food-grade PLA converters facing EU Green Deal procurement deadlines. Midwest corn futures volatility feeds through to NatureWorks' quarterly contract negotiations, compressing margin predictability for North American packaging buyers locked into annual offtake agreements.
Pricing Analysis
Prior-generation tin-catalyzed PLA grades trade at commodity discounts against next-generation zirconium-catalyzed high-molecular-weight variants capable of microwave reheating applications. Contract-based long-term offtake dominates, with price differentiation hinging on food-contact certification tier and volume scale. Pricing pressure stems from corn price volatility squeezing fermentation economics, while small-batch 3D printing filament buyers exhibit highest price sensitivity against medical device manufacturers accepting sterilization-grade premiums.
Supply Chain Analysis
Extended payment terms from Thai sugarcane processors to Rotterdam distributors have become standard working-capital fixtures in the lactic acid-to-PLA value chain. Supply concentrates in Thailand, the United States, and China, with raw material dependencies on corn starch, sugarcane sucrose, and fermentation nutrients. Single-source vulnerability runs through TotalEnergies Corbion's integrated Thai-European corridor. Distribution runs through direct sales to large-volume converters with technical service requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polylactic acid demand cycles track EU packaging mandate implementation phases, with current biopolymer substitution thresholds driving converter qualification waves that resemble prior compliance-driven procurement surges.
For Market Incumbents: Pre-empt capacity bottlenecks by securing captive sugarcane offtake in Thailand before government ethanol diversion policies tighten feedstock availability. Defend position by accelerating FDA food-contact notification timelines for high-heat copolymers, insulating against emerging fermentation specialists targeting sterilizable medical grades. For New Entrants and Emerging Players: Build out BIS-certified fiber production capacity serving Surat and Tiruppur textile clusters, where DGFT preferential tariffs create import displacement economics. White-space concentrates in Indian medical spinning and barrier-coated flexible films for modified-atmosphere produce packaging. Go-to-market leverage rests on atomic layer deposition partnerships with Dutch packaging converters. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated sugarcane-to-PLA operators with Rotterdam finishing capacity and captive European food-service distribution. Long-term viability favors backward-integrated fermentation assets with multi-feedstock flexibility. Signal to monitor: ECHA REACH registration completion rates for Asian resin exporters, which indicate competitive pressure release timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Captive sugarcane or corn starch supply insulates margin from agricultural commodity volatility. |
| FDA Food-Contact Notification Acceleration | Eighteen-month pre-market clearance compression enables faster commercialization of high-heat PLA grades. |
| Rotterdam Distribution Hub Expansion | European finishing capacity proximity to German REWE and Spar Group procurement centers reduces logistics friction. |
| Barrier Coating Technology Partnership | Atomic layer deposition convergence with PLA substrates unlocks modified-atmosphere packaging applications. |
| BIS Biopolymer Certification Investment | Indian textile spinning qualification opens Surat and Tiruppur weaving clusters to PLA fiber displacement. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with fermentation plant managers, packaging converter procurement leads, and medical device regulatory affairs directors; and secondary validation through ECHA REACH registration databases, FDA food-contact notification filings, EU Green Deal implementation trackers, and customs trade flow records. Bottom-up capacity modeling triangulated against top-down demand segmentation across packaging, medical, and textile applications.
Forecast inputs encompassed grade-tier differentiation, end-use industry demand elasticity, regional regulatory cluster adoption timelines, and composting infrastructure maturity. Segmentation dimensions spanned product form, application vertical, and distribution channel. CAGRs were derived from supply-demand balance modeling across the projection horizon, incorporating fermentation yield improvements and polymerization catalyst technology transitions as industry-specific variables.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed fermentation specialists would shift outcomes. Macroeconomic agricultural commodity spikes, accelerated EU biopolymer mandate tightening, or breakthrough petroleum-plastic recycling economics would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polypropylene Homopolymer (PPH) Market
Polymers & Resins
Asia-Pacific Polymer Emulsion Market
Polymers & Resins
Liquid Polybutadiene [LPBD] Market
Polymers & Resins
Middle East and Africa Hydroxyl-Terminated Polybutadiene (HTPB) Market
Polymers & Resins
Soil Release Polymer Market
Polymers & Resins
Soft PVC Sealing Strip Market
Polymers & Resins
Global Resin Market
Polymers & Resins
Bio Based Resin Market
Polymers & Resins
South America Fluoropolymer Market
Polymers & Resins
Global Medical Superabsorbent Polymers Market
Polymers & Resins
Global Polyethyleneimine Market
Polymers & Resins
Global UV Curable Resins and Formulated Products Market
Polymers & Resins
Solid-Grade Thermoplastic Acrylic (Beads) Resin Market
Polymers & Resins
Bio-Based Polyvinyl Chloride Market
Polymers & Resins
Acetal (POM) Copolymer Market
Polymers & Resins
Asia-Pacific Geopolymer Market