
 Vacuum Tissue Processors Market | 2026-2036
Vacuum Tissue Processors Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Tissue Processors Market Analytics
Market Dynamics
China is rewriting competitive dynamics in vacuum tissue processing through expanded domestic manufacturing capacity for laboratory automation. Leica Biosystems leverages its Danaher-operated supply chain to sustain instrument placement in European histology labs. Sakura Finetek anchors its position through deep specialization in embedding and processing workflow integration. Thermo Fisher Scientific competes by extending its clinical diagnostics footprint into companion pathology platforms.
Technology and Segmentation
Vacuum tissue processors are laboratory instruments that use negative pressure cycles to sequentially dehydrate, clear, and infiltrate tissue specimens with paraffin, typically operating at pressures below 50 kPa to preserve cellular architecture for microscopic examination. The automatic product segment dominates capital procurement in high-throughput hospital pathology departments, while portable units are gaining traction in decentralized forensic field settings. Vacuum infiltration technology leads installed base metrics, though flow-through architectures are displacing legacy batch systems in research institutes pursuing multi-specimen throughput.
Regulatory Environment
The FDA regulates vacuum tissue processors as Class I medical devices under 21 CFR 864, while the EU MDR and IVDR frameworks impose strengthened clinical evidence and post-market surveillance obligations on manufacturers seeking CE marking. ISO 13485 quality management certification shapes supplier qualification criteria for public hospital tenders across OECD markets. Stakeholders must monitor evolving harmonization gaps between FDA device classification and EU risk-category determinations to anticipate dual-market registration burdens.
Market Dynamics
Centralized pathology networks in Germany are standardizing vacuum tissue processing workflows, forcing instrument vendors to align with interoperable automation protocols and EU MDR quality management mandates.
Growth Catalysts
- EU MDR compliance mandates:Strengthened clinical evidence requirements for in-vitro diagnostic equipment are accelerating hospital replacement cycles for legacy batch processors.
- Forensic field deployment:Portable vacuum units are penetrating decentralized crime scene laboratories requiring rapid specimen stabilization outside centralized facilities.
- Multi-specimen throughput demand:Research institutes are driving flow-through architecture adoption to replace single-batch systems in high-volume histology operations.
Market Restraints
- Paraffin and reagent cost volatility:Fluctuating petroleum-derived input prices compress margin structures for high-throughput processing consumables.
- Supply concentration in German optics:Precision vacuum pump and pressure sensor sourcing clusters in Bavaria and Baden-Württemberg create geographic single-point vulnerability.
- ISO 13485 certification timelines:Extended quality management system audits delay new entrant market access by 18-24 months in public tender markets.
Strategic Opportunities
- China laboratory automation expansion:Domestic manufacturing capacity growth creates white space for localized vacuum infiltration system production serving tier-two hospital networks.
- Companion diagnostics integration:Convergence of molecular pathology platforms with automated tissue processing opens new revenue streams in precision oncology workflows.
- Digital pathology workflow alignment:Whole-slide imaging standardization creates demand for processors with barcode tracking and LIS connectivity in academic medical centers.
Industry Challenges
- Histotechnologist workforce scarcity:Specialized tissue processing expertise gaps in clinical laboratories extend instrument commissioning and validation timelines.
- Legacy system integration complexity:Embedded batch processors in established pathology departments resist retrofit with vacuum infiltration architectures without workflow redesign.
- Dual-market registration burden:Divergent FDA Class I device classification and EU MDR risk-category determinations force redundant technical documentation for multinational vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Tissue Processors Market |
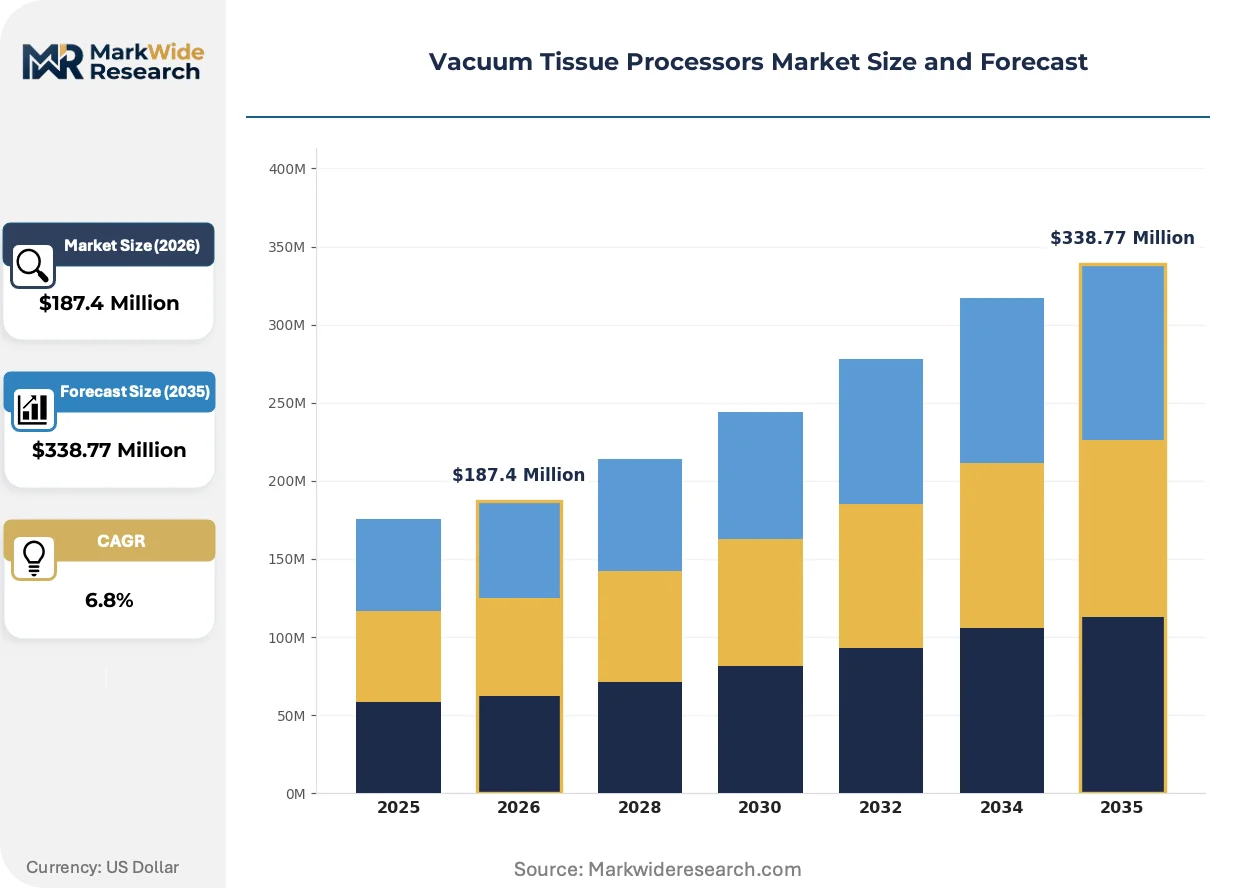
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Portable Technology: Vacuum Infiltration, Freeze Drying, Flow-Through, Direct Pour End User: Clinical Laboratories, Research Institutes, Educational Institutions, Hospitals Application: Histology, Pathology, Cytology, Forensic Analysis |
| Companies Covered | Leica Biosystems (Danaher), Sakura Finetek, Roche Diagnostics, Epredia (PHC), Milestone Medical, Thermo Fisher Scientific, SLEE medical GmbH, Bio-Optica, Medimeas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Tissue Processors Market Evolving Landscape
Digital connectivity and automated specimen tracking are redefining vacuum tissue processor specifications, with buyers prioritizing interoperability over standalone instrument performance.
RFID-enabled cassette tracking is digitizing chain-of-custody documentation in forensic and clinical laboratories. High-throughput hospital pathology departments in Germany and the Netherlands are deploying these systems to eliminate manual specimen logging errors. This connectivity architecture is digitizing audit trail compliance and compressing liability exposure for tissue processing facilities.
The EU MDR's post-market surveillance obligations are tightening adverse event reporting requirements for vacuum infiltration systems. Manufacturers must now maintain systematic clinical follow-up data for CE-marked devices, elevating documentation costs. European histology laboratories are responding by consolidating procurement around vendors with established notified body relationships and proven post-market surveillance infrastructure.
Service contract unbundling is fragmenting traditional capital equipment sales models. Academic medical centers and private pathology groups are separating instrument acquisition from maintenance and reagent supply, pressuring bundled pricing strategies. This disaggregation is most visible in the UK and Scandinavian markets, where procurement frameworks favor multi-vendor service arbitrage over single-source relationships.
Vacuum Tissue Processors Market Segmentation
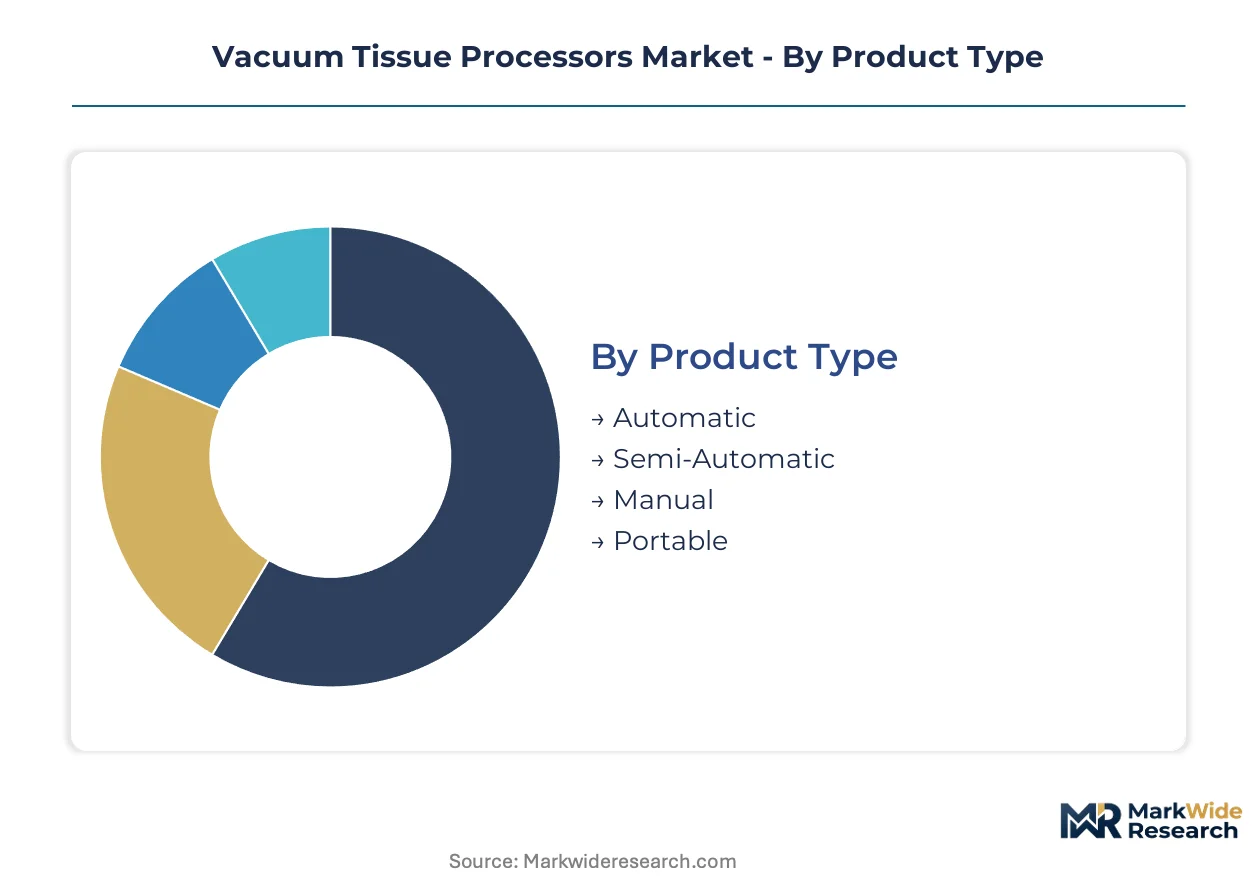
Vacuum tissue processor segmentation reveals distinct procurement patterns across automation levels, technical architectures, and institutional settings. Each dimension shapes vendor pricing power, service contract structures, and replacement cycle timing.
Product Type:
Automation intensity spans from fully programmed systems to field-deployable units, with cost tiers and throughput requirements driving institutional selection patterns.
- Automatic:Programmable systems execute dehydration, clearing, and paraffin infiltration cycles without operator intervention. High-throughput hospital pathology departments in Germany and the Netherlands concentrate procurement here, prioritizing integration with laboratory information systems and barcode tracking for digital pathology workflows.
- Portable:Battery-capable units operate at pressures below 50 kPa outside centralized facilities. Decentralized crime scene laboratories and mobile forensic teams drive uptake, requiring rapid specimen stabilization without transport to core facilities.
- Semi-Automatic:Systems blend programmed vacuum cycles with manual reagent loading, serving mid-volume clinical laboratories balancing throughput against capital constraints.
- Manual:Hand-operated vacuum chambers persist in resource-limited settings and educational training environments where cost minimization outweighs processing speed.
The dominant share belongs to Automatic systems, while Portable units are expanding most quickly as forensic networks decentralize specimen processing capabilities.
Technology:
Architectural approaches to tissue infiltration differentiate by specimen throughput capacity, cellular preservation quality, and integration complexity with downstream embedding stations.
- Vacuum Infiltration:Negative pressure cycles below 50 kPa sequentially replace aqueous tissue content with paraffin, preserving cellular architecture for microscopic examination. Academic medical centers across OECD markets anchor installed base metrics, though legacy batch configurations face displacement pressure from continuous-flow alternatives.
- Flow-Through:Continuous reagent perfusion architectures enable parallel multi-specimen processing without batch cycle interruptions. Research institutes pursuing high-volume histology operations drive adoption, replacing single-batch systems to compress turnaround times for translational studies.
- Freeze Drying:Lyophilization-based dehydration preserves heat-sensitive antigenic structures for immunohistochemistry applications, serving specialized molecular pathology workflows.
- Direct Pour:Gravity-assisted paraffin infiltration without vacuum assistance persists in basic research settings and developing market laboratories where infrastructure simplicity overrides processing efficiency.
Vacuum Infiltration retains the largest installed base, though Flow-Through architectures are gaining share fastest among research-intensive institutions.
End User:
Institutional procurement authority concentrates in distinct funding mechanisms, regulatory exposure profiles, and technical staffing levels across the customer landscape.
- Clinical Laboratories:CAP-accredited and ISO 15189-certified facilities process diagnostic specimens under stringent turnaround requirements. EU MDR compliance mandates and post-market surveillance obligations reshape vendor qualification criteria, favoring suppliers with established notified body relationships.
- Hospitals:Integrated pathology departments within academic medical centers drive standardization of automated vacuum infiltration workflows, particularly in Germany's centralized pathology networks.
- Research Institutes:Multi-specimen throughput demands and grant-funded capital cycles create distinct procurement timing and specification priorities compared to clinical settings.
- Educational Institutions:Training laboratories prioritize manual and semi-automatic systems for histotechnologist education, with procurement volumes tied to accreditation expansion and workforce development programs.
Clinical Laboratories command the dominant procurement volume, while Research Institutes are climbing the fastest as translational medicine funding expands.
Application:
Specimen type and diagnostic purpose shape processor specifications, with chain-of-custody requirements and regulatory scrutiny varying sharply across use cases.
- Histology:Routine tissue sectioning for morphological diagnosis represents the core volume application, with standardization pressures strongest in centralized European pathology networks.
- Forensic Analysis:Decentralized crime scene processing and legal chain-of-custody documentation drive portable unit specifications, with RFID-enabled cassette tracking digitizing audit trail compliance.
- Pathology:Diagnostic confirmation workflows in hospital settings integrate with whole-slide imaging platforms, requiring barcode tracking and LIS connectivity.
- Cytology:Liquid-based preparation and cell block processing for fine needle aspiration specimens demands adapted vacuum protocols distinct from solid tissue architectures.
Histology maintains the dominant application share, while Forensic Analysis is expanding most rapidly as field-deployable capabilities mature.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision vacuum pump and pressure sensor manufacturing clusters in Bavaria and Baden-Württemberg create geographic concentration risk for component sourcing. Germany's centralized pathology networks drive standardization across European procurement patterns. China's domestic laboratory automation expansion is rewriting competitive dynamics for mid-tier hospital networks.
Germany
Centralized pathology networks in Bavaria and North Rhine-Westphalia standardize vacuum tissue processing workflows across hospital consortia. The EU MDR tightens quality management system requirements for in-vitro diagnostic equipment, accelerating replacement cycles for legacy batch processors. Precision component manufacturing concentrates in Stuttgart and Munich industrial corridors.
United States
CAP-accredited clinical laboratories in academic medical centers expand procurement of automated vacuum infiltration systems with LIS connectivity. The FDA regulates these instruments as Class I medical devices under 21 CFR 864, creating streamlined pathways for instrument clearance. Histology automation clusters around Boston, San Francisco, and Research Triangle Park.
China
Tier-two hospital networks drive demand for localized vacuum infiltration system production as domestic manufacturing capacity expands. The NMPA strengthens clinical evidence requirements for medical device registration, elevating documentation burdens for multinational entrants. Laboratory automation manufacturing concentrates in Suzhou and Shenzhen industrial zones.
Netherlands
High-throughput hospital pathology departments deploy RFID-enabled cassette tracking to digitize specimen chain-of-custody documentation. The EU MDR post-market surveillance obligations reshape vendor qualification criteria toward established notified body relationships. Diagnostic technology clusters in Eindhoven and Utrecht medical device corridors.
United Kingdom
Academic medical centers and private pathology groups unbundle service contracts from instrument acquisition, favoring multi-vendor procurement frameworks. NHS procurement frameworks prioritize interoperability standards for digital pathology workflow integration. Histology research concentrates in London, Cambridge, and Oxford biomedical clusters.
Vacuum Tissue Processors Market Competitive Landscape
Diversified life science conglomerates and specialized histology equipment fabricators split the market into distinct capability tiers. Consolidation pressure intensifies as hospital networks standardize procurement around vendors with comprehensive service infrastructure and established regulatory relationships. Two strategic archetypes dominate: integrated diagnostics platforms leveraging clinical footprint expansion, and workflow specialists embedding deeply in tissue processing automation. Competitive moves center on companion diagnostics convergence and digital pathology interoperability certification.
Among diversified platform operators, Leica Biosystems and Thermo Fisher Scientific occupy positions anchored by clinical diagnostics infrastructure and laboratory automation portfolios. Sakura Finetek exemplifies the workflow specialization archetype through deep embedding in embedding and processing integration. These three entities represent the spectrum from broad diagnostics convergence to targeted histology automation excellence, with each archetype pursuing distinct paths to procurement preference in standardized European networks and expanding Asian hospital systems.
| Leading Market Players |
|---|
| Leica Biosystems (Danaher) |
| Sakura Finetek |
| Roche Diagnostics |
| Epredia (PHC) |
| Milestone Medical |
| Thermo Fisher Scientific |
| SLEE medical GmbH |
| Bio-Optica |
| Medimeas |
| Others |
Value Network & Pricing Analysis
The Rhine-Alpine freight corridor's cost dynamics amplify supply concentration effects in precision vacuum component sourcing while compressing margin structures for mid-tier instrument vendors competing against integrated diagnostics platforms.
Pricing Analysis
EU MDR dictates the pricing tier structure across the vacuum tissue processor landscape. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked systems with established notified body relationships from transitional legacy equipment and unbundled service contracts. Price differentiation rests on ISO 13485 certification status and after-sales service bundling. Cost compression in the standard tier is intensifying because academic medical centers are separating instrument acquisition from maintenance agreements. Mid-volume clinical laboratories exhibit the highest price sensitivity, while centralized German pathology networks prioritize interoperability over unit cost.
Supply Chain Analysis
Dual-use export controls on precision pressure sensors and vacuum pump technologies limit component flows from German manufacturing clusters to non-EU assembly operations. Geographic supply concentration centers on Germany, Switzerland, and Japan for precision optics and pressure control systems. Raw material dependencies draw from petroleum-derived paraffin formulations, specialized fluoropolymer seals, and medical-grade stainless steel. Single-source vulnerability in Bavarian precision machining creates chokepoint exposure for vacuum chamber fabrication. Distribution runs through authorized distributor networks serving hospital procurement committees and GPO contracts in OECD markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from flow-through tissue processing architectures that promise multi-specimen throughput without batch cycle limitations. Defense requires entrenchment through workflow integration rather than standalone instrument performance.
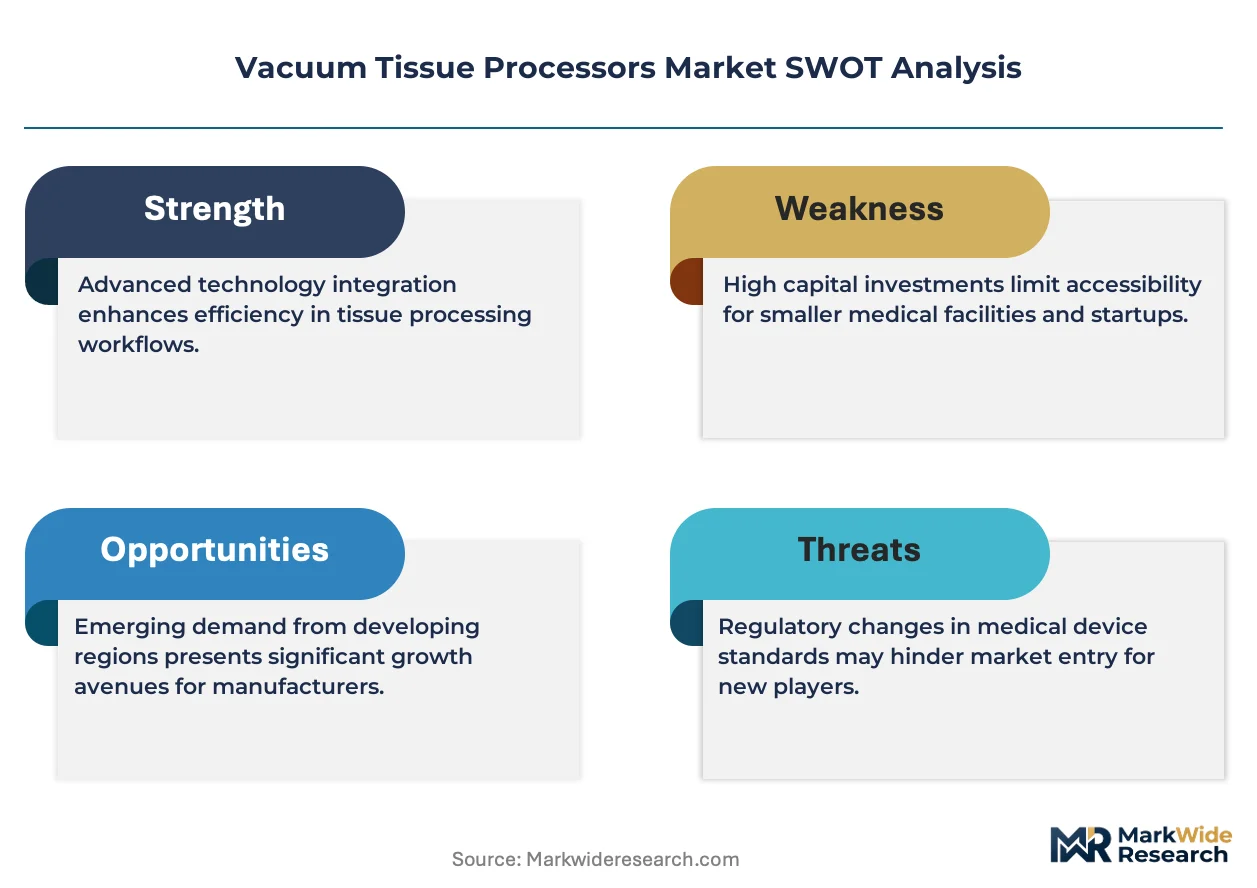
For Market Incumbents: Entrench market position by deepening backward integration into precision vacuum pump manufacturing and accelerating CE marking pathways for next-generation flow-through systems. The shift toward unbundled service contracts threatens recurring revenue streams; counter this by embedding proprietary reagent protocols that resist third-party maintenance arbitrage. Priority investment in ISO 13485-certified production capacity secures qualification for German centralized pathology tenders. For New Entrants and Emerging Players: Tier-two hospital networks in China's eastern provinces represent the most penetrable entry point for localized vacuum infiltration system production. Forensic field deployment of portable units offers a second white-space channel with lower regulatory barriers than clinical diagnostics. Go-to-market execution through domestic distribution partnerships bypasses extended NMPA registration timelines for multinational entrants. For Investors and Strategic Acquirers: EU MDR's full implementation reshapes the acquisition landscape toward targets with established notified body relationships and post-market surveillance infrastructure. Long-term viability favors workflow specialists with deep embedding in tissue processing automation over diversified diagnostics platforms facing margin compression. Monitor consolidation signals in German precision component manufacturing as the indicator for supply chain restructuring opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR compliance timelines determine competitive access to centralized European pathology procurement. |
| Hospital System Partnership | Academic medical centers in Germany and the Netherlands prioritize LIS-integrated workflow solutions. |
| Software Companion Development | Barcode tracking and RFID-enabled cassette management differentiate offerings in digital pathology environments. |
| Backward Integration into Vacuum Components | Captive supply of precision pressure sensors mitigates Bavarian sourcing concentration risk. |
| Reimbursement Strategy Alignment | Companion diagnostics integration opens precision oncology revenue streams beyond traditional histology. |
Research Methodology
Operator-level perspectives from histotechnologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers anchored the qualitative base. Secondary validation drew from FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and precision manufacturing trade data. Bottom-up instrument shipment analysis triangulated against top-down pathology laboratory capital expenditure surveys.
Scenario-bracketing around regulatory implementation timelines and laboratory automation adoption curves shaped the analytical framework across the projection horizon. Segmentation modeling incorporated automation intensity, architectural approach, institutional setting, and application type. CAGRs derived from instrument replacement cycle analysis and grant-funded research capital cycle patterns. Forecast inputs included EU MDR transition completion rates and NMPA registration pathway efficiency trends.
Macroeconomic conditions sit as an overlay; deviation in petroleum-derived input costs and precision manufacturing labor availability would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization progress and laboratory workforce expansion. Material shifts in EU MDR enforcement stringency or export control expansion on precision sensors would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Automated Blood Processing Equipment Market
Laboratory Equipment
Laboratory Rockers and Shakers Market
Laboratory Equipment
Asia Pacific Cell Counting Market
Laboratory Equipment
Lab Accessories Market
Laboratory Equipment
Ion-Selective Clinical Lab Analyzers Market
Laboratory Equipment
Pipettes and Accessories Market
Laboratory Equipment
Global Pipette Tips Market
Laboratory Equipment
Laboratory Refrigerators and Ovens Market
Laboratory Equipment
Automated Plate Readers Market
Laboratory Equipment
Global Laboratory Plasticware Market
Laboratory Equipment
Point of Care (POC) Coagulation Testing Devices Market
Laboratory Equipment
Blood Bank Analyzers Market
Laboratory Equipment
Platelet Shaker Market
Laboratory Equipment
Global Microplate System Market
Laboratory Equipment
Multi Channel Hotplate Magnetic Stirrers Market
Laboratory Equipment
Human Milk Analyzers Market