
 Ion-Selective Clinical Lab Analyzers Market | 2026-2036
Ion-Selective Clinical Lab Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Ion-Selective Clinical Lab Analyzers Market Foresight
Multi-source procurement for ion-selective electrode modules is restructuring supply relationships across the clinical analyzer value chain. Siemens Healthineers leverages captive sensor manufacturing to secure margin control over potentiometric consumables. Thermo Fisher Scientific sustains broad catalog breadth that competes across research and diagnostic channels simultaneously. Nova Biomedical specializes in compact, maintenance-light designs that occupy point-of-care settings where space and staffing constraints dominate purchasing criteria.
Ion-selective clinical lab analyzers employ potentiometric measurement with ion-selective electrodes to quantify electrolyte concentrations in biological fluids, typically achieving measurement ranges of 1–200 mmol/L with coefficient of variation below two percent for sodium, potassium, chloride, and ionized calcium. These instruments serve primarily to guide acute clinical decisions in critical care, renal dialysis, and perioperative management where rapid electrolyte imbalance correction prevents patient deterioration. Benchtop analyzers anchor installed base value in high-throughput hospital laboratories, while portable and handheld devices capture the fastest expansion as decentralized testing protocols extend into emergency departments and satellite clinics. Optical sensor variants remain niche but attract margin-focused investment where simultaneous multi-analyte detection reduces per-test consumable cost.
FDA premarket notification requirements and CLIA complexity categorization shape product development roadmaps by determining which analyzer classes qualify for waived or moderate-complexity certification. ISO 15189 medical laboratory accreditation and the EU In Vitro Diagnostic Regulation compel manufacturers to maintain extensive analytical performance documentation across reagent lots and instrument generations. Stakeholders must monitor evolving regulatory convergence between U.S. and European performance standards, as harmonized requirements would reshape competitive barriers for regional specialists and multinational platforms alike.
Market Dynamics
Hospital consolidation into integrated delivery networks is compressing purchasing cycles and favoring vendors with multi-site service capabilities over point-product specialists.
Growth Catalysts
- CLIA Complexity Waivers:Moderate-complexity certification expansion enables broader deployment of ion-selective analyzers into satellite clinics and emergency departments previously restricted to central laboratories.
- Perioperative Electrolyte Protocols:Surgical suites now mandate rapid ionized calcium and potassium verification, driving installed base expansion in ambulatory surgery centers across the United States.
- Sensor Miniaturization:Solid-state electrode fabrication advances reduce analyzer footprint by forty percent, unlocking point-of-care placement in space-constrained settings.
Market Restraints
- Precious Metal Input Volatility:Silver-silver chloride reference electrode production faces cost pressure from fluctuating silver spot markets, squeezing consumable margins.
- Single-Source Membrane Supply:Polyvinyl chloride matrix membranes with ionophore loading concentrate among three European specialty chemical suppliers, creating geographic concentration risk.
- Optical Multi-Analyte Substitution:Spectrophotometric platforms offering simultaneous electrolyte and metabolite panels threaten standalone ion-selective electrode market position in high-throughput laboratories.
Strategic Opportunities
- Rural Health Clinic Expansion:Federally qualified health centers in underserved United States counties lack on-site electrolyte capability, representing greenfield placement potential for compact analyzers.
- Home Hemodialysis Monitoring:Patient-managed potassium and calcium tracking creates demand for simplified, connectivity-enabled devices outside traditional clinical settings.
- FDA Breakthrough Device Pathway:Expedited review for novel electrode chemistries addressing unmet measurement needs accelerates time-to-market for differentiated platforms.
Industry Challenges
- Electrochemist Talent Scarcity:Ion-selective electrode design requires specialized expertise in potentiometry and membrane chemistry that academic programs produce in limited numbers.
- 510(k) Predicate Device Navigation:Substantial equivalence determinations for next-generation analyzers face unpredictable timelines when novel electrode materials lack established predicates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ion-Selective Clinical Lab Analyzers Market |
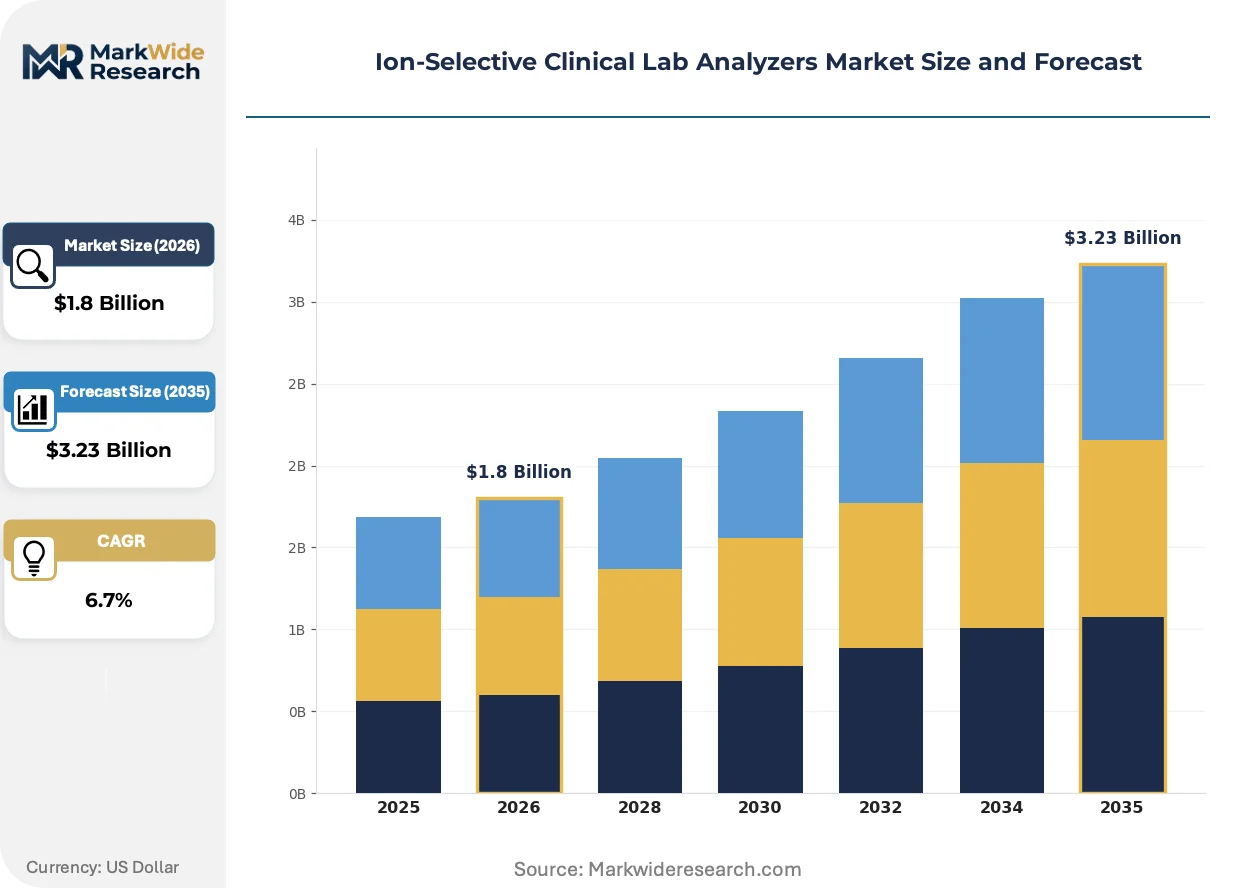
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop Analyzers, Portable Analyzers, Automated Analyzers, Handheld Devices Technology: Ion-Selective Electrodes, Optical Sensors, Conductivity Sensors, Potentiometric Sensors End User: Hospitals, Diagnostic Laboratories, Research Institutions, Point-of-Care Settings Application: Clinical Diagnostics, Environmental Testing, Pharmaceutical Analysis, Food Quality Testing |
| Companies Covered | Abbott Laboratories, Roche Diagnostics, Siemens Healthineers, Thermo Fisher Scientific, Beckman Coulter, Mindray Medical International, Horiba Ltd., Nova Biomedical, Randox Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ion-Selective Clinical Lab Analyzers Market Shifts & Advancements
Digital integration and electrode material science are converging to redefine performance benchmarks and service delivery models across the clinical analyzer landscape.
Microfabricated solid-state ion-selective electrodes are consolidating measurement reliability and calibration stability into single-use cartridge formats. Critical care units in tertiary hospitals are adopting these disposable sensor modules to eliminate maintenance downtime. The shift is consolidating aftermarket service revenue into consumable streams and compressing traditional field service organizations.
FDA premarket notification requirements for software-as-medical-device functionality are tightening cybersecurity and algorithm validation standards. Manufacturers must now submit extensive documentation for cloud-connected calibration and remote diagnostic features. Point-of-care analyzer portfolios face the steepest compliance burden as wireless data transmission becomes standard configuration.
Health system procurement departments are consolidating analyzer contracts into enterprise-wide agreements spanning multiple hospital campuses. Device vendors now compete on total cost-of-ownership analytics rather than instrument acquisition price alone. The United States exhibits the most pronounced concentration, where ten health systems control twenty-five percent of acute care beds and negotiate standardized equipment specifications.
Ion-Selective Clinical Lab Analyzers Market Segmentation
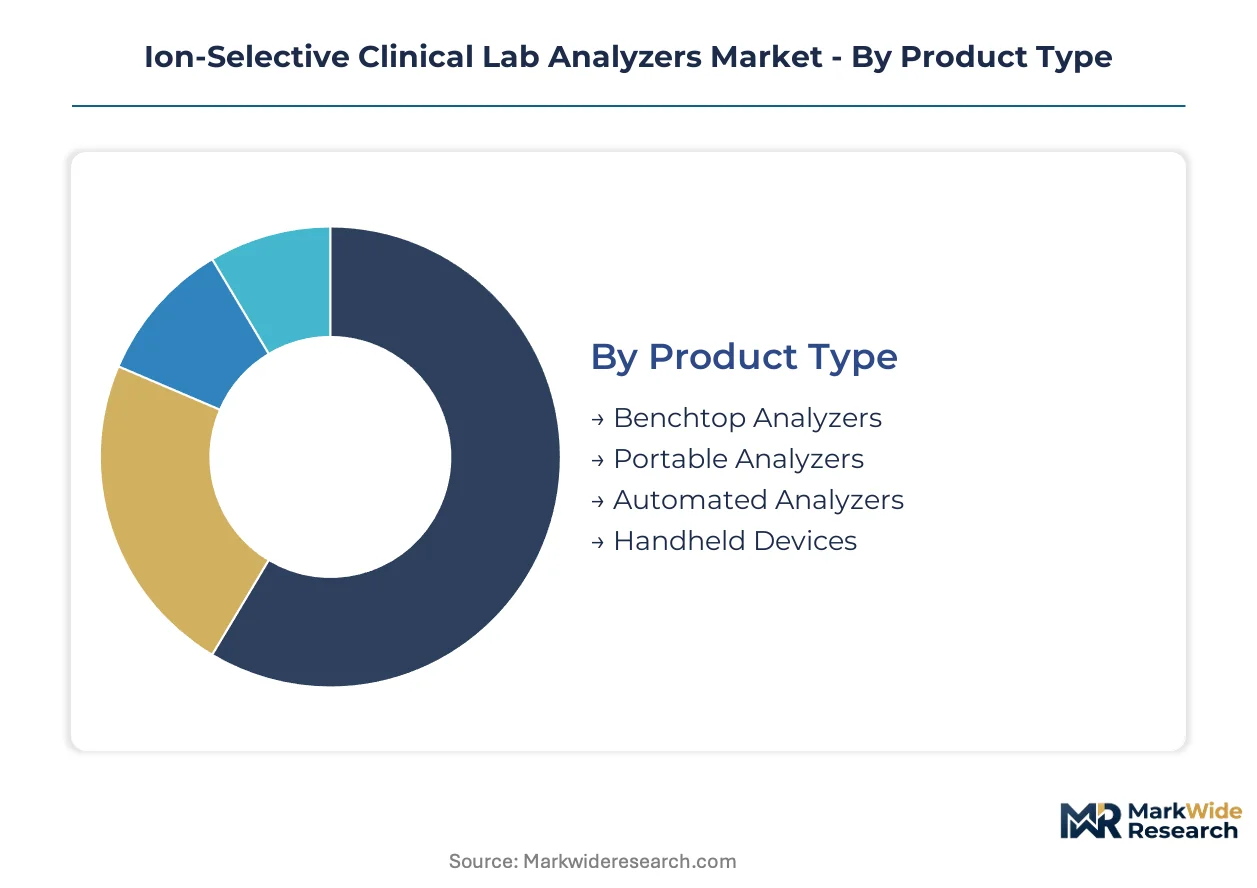
Analyzer configuration directly determines placement economics across the clinical workflow. Product architecture, sensing modality, and deployment setting each impose distinct cost structures and regulatory pathways that shape vendor competitive strategy.
Product Type:
Supply concentration in electrode manufacturing favors vendors with captive sensor production across all form factors.
- Benchtop Analyzers:High-throughput instruments with multi-channel ion-selective electrode arrays process 100-400 samples hourly. Hospital consolidation in the United States drives centralized laboratory procurement of these units for electrolyte panels.
- Portable Analyzers:Battery-operated devices with solid-state electrodes achieve measurement precision within 3% of benchtop reference values. Emergency departments and satellite clinics deploy these where rapid turnaround outweighs throughput volume.
- Automated Analyzers:Integrated sample handling and calibration systems reduce operator intervention for high-volume reference laboratories.
- Handheld Devices:Single-test disposable cartridges enable non-laboratory personnel to perform ionized calcium and potassium verification at bedside.
Benchtop analyzers absorb the bulk of installed capacity; handheld devices are expanding most quickly.
Technology:
Cost tier differentiation separates mature potentiometric platforms from emerging optical alternatives with multi-analyte capability.
- Ion-Selective Electrodes:Polyvinyl chloride matrix membranes with valinomycin or ionophore-based recognition elements deliver 1-200 mmol/L measurement range with Nernstian response slopes. These electrodes anchor installed base value in hospital central laboratories where CLIA moderate-complexity certification applies.
- Optical Sensors:Fluorescent or colorimetric transduction enables simultaneous electrolyte and metabolite detection without precious metal reference electrodes. High-throughput laboratories adopt these where reagent cost consolidation outweighs capital expenditure premiums.
- Conductivity Sensors:Cell-based conductometric measurement provides rapid total dissolved solids approximation for screening applications.
- Potentiometric Sensors:Solid-state reference electrode configurations eliminate liquid junction maintenance in point-of-care deployments.
Ion-selective electrodes retain dominant installed base position; optical sensors are climbing the fastest as multi-analyte consolidation accelerates.
End User:
Customer type dictates purchasing authority structure and service contract complexity.
- Hospitals:Integrated delivery networks negotiate enterprise-wide analyzer contracts spanning inpatient laboratories, emergency departments, and surgical suites. The United States exhibits pronounced health system concentration where ten networks control twenty-five percent of acute care beds.
- Diagnostic Laboratories:Commercial reference laboratories prioritize throughput density and automated quality control for high-volume electrolyte profiling.
- Research Institutions:Academic medical centers require flexible analytical ranges and method development capabilities for investigational protocols.
- Point-of-Care Settings:Federally qualified health centers and rural clinics seek waived-complexity certification for operator-independent testing.
Hospitals command the largest capital equipment allocation; point-of-care settings are gaining share fastest as decentralized testing protocols expand.
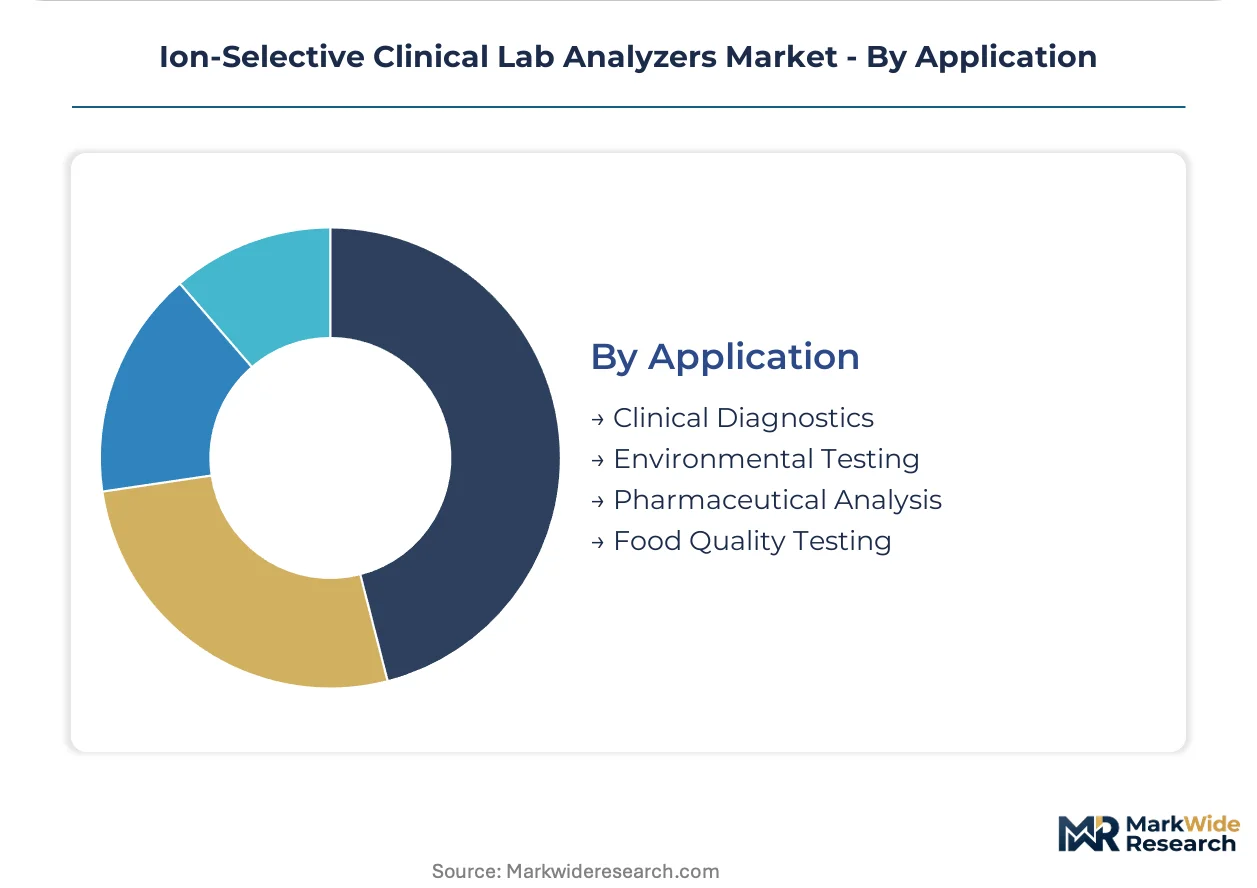
Application:
Volume concentration in clinical diagnostics shapes electrode and reagent production planning.
- Clinical Diagnostics:Acute care electrolyte panels for critical care, renal dialysis, and perioperative management drive sixty-plus percent of analyzer utilization. FDA premarket notification requirements and CLIA complexity categorization determine which device classes qualify for moderate-complexity or waived certification.
- Environmental Testing:Water quality monitoring for heavy metals and nutrient ions employs similar potentiometric principles with modified electrode selectivity coefficients.
- Pharmaceutical Analysis:Drug formulation stability testing and dissolution profiling require trace-level ion detection with validated analytical methods.
- Food Quality Testing:Sodium and potassium quantification in processed foods supports nutritional labeling compliance.
Clinical diagnostics absorbs the bulk of electrode consumption; pharmaceutical analysis is expanding most quickly as biologics manufacturing quality control tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German specialty chemical suppliers anchor ion-selective membrane production for electrode manufacturing. Silver mining regions in Mexico and Peru feed reference electrode fabrication. Health system procurement patterns diverge sharply across national regulatory environments.
United States
Hospital consolidation into ten dominant integrated delivery networks concentrates analyzer purchasing power across twenty-five percent of acute care beds. FDA premarket notification requirements and CLIA complexity waivers determine which device classes reach satellite clinics and emergency departments. The Boston-Cambridge medical device cluster drives solid-state electrode miniaturization for point-of-care deployment.
Germany
Industrial chemical capabilities in the Rhine-Ruhr region supply polyvinyl chloride matrix membranes with ionophore loading to global electrode manufacturers. The EU In Vitro Diagnostic Regulation compels extensive analytical performance documentation across reagent lots. Baden-Württemberg's precision engineering base supports automated sample handling systems for high-throughput reference laboratories.
China
Domestic hospital network expansion and diagnostic laboratory automation programs drive electrolyte analyzer installation in tier-two and tier-three cities. NMPA medical device registration requirements are converging toward international standards for analytical performance validation. The Yangtze River Delta manufacturing corridor concentrates potentiometric sensor assembly for both domestic consumption and export markets.
Japan
Aging demographics and chronic disease management protocols elevate electrolyte monitoring frequency in outpatient dialysis centers. PMDA regulatory timelines for novel electrode materials remain unpredictable when predicates lack established equivalence. The Kansai region's analytical instrumentation heritage supports method development capabilities for research medical centers.
India
Federally qualified health centers in underserved districts represent greenfield placement potential for compact waived-complexity devices. CDSCO medical device rules are tightening quality management system requirements for imported analyzers. Maharashtra's pharmaceutical manufacturing belt generates parallel demand for ion-selective electrodes in drug formulation stability testing.
Ion-Selective Clinical Lab Analyzers Market Competitive Landscape
Global majors compete with regional champions across regulatory certification and service network reach. The vendor base stratifies into three tiers: diversified life science conglomerates with captive sensor manufacturing, mid-scale diagnostic specialists with compact point-of-care portfolios, and regional assemblers serving price-sensitive procurement channels. Dominant competitive moves include backward integration into membrane chemistry and enterprise-wide contract consolidation spanning multi-site health systems.
Among diversified life science conglomerates, Siemens Healthineers and Thermo Fisher Scientific exemplify the integrated archetype with control over potentiometric consumable supply chains. Nova Biomedical occupies a specialist position in maintenance-light compact designs for space-constrained settings. Abbott Laboratories and Roche Diagnostics anchor the premium-tier installed base in high-throughput hospital laboratories where moderate-complexity CLIA certification applies.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Roche Diagnostics |
| Siemens Healthineers |
| Thermo Fisher Scientific |
| Beckman Coulter |
| Mindray Medical International |
| Horiba Ltd. |
| Nova Biomedical |
| Randox Laboratories |
| Others |
Supply & Pricing Matrix
Family-owned German specialty chemical houses anchor polyvinyl chloride matrix membrane production, translating concentrated upstream control into disciplined pricing power over ionophore-loaded electrode components. Their captive supply relationships with diversified life science conglomerates enforce stable long-term contract structures that resist spot-market volatility in silver reference electrode inputs.
Pricing Analysis
Warranty and field service bundling separates premium-tier benchtop analyzer contracts from unbundled portable device procurement. Three-tier pricing structure across premium, standard, and economy levels reflects CLIA certification grade and throughput capacity rather than raw sensor cost alone. Cost compression in handheld segments is intensifying because emergency department buyers prioritize disposable cartridge economics over capital expenditure. Federally qualified health centers exhibit highest price sensitivity; integrated delivery networks negotiating enterprise-wide contracts demonstrate lowest sensitivity due to total cost-of-ownership analytics.
Supply Chain Analysis
Dual-sourcing qualification requirements for ion-selective electrode membranes compel manufacturers to maintain approved supplier relationships with at least two of the three Rhine-Ruhr specialty chemical producers. Silver mining regions in Mexico and Peru feed reference electrode fabrication, while solid-state sensor assembly concentrates in China's Yangtze River Delta manufacturing corridor. Single-source vulnerability in European ionophore supply creates geographic concentration risk that tariff exposure on Chinese-assembled components could amplify. Distribution runs through authorized distributor networks serving hospital procurement committees and GPO contracts managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors with captive sensor manufacturing and multi-site service capabilities, as hospital network centralization squeezes point-product specialists lacking enterprise contract scale.
For Market Incumbents: Anticipate optical multi-analyte platform substitution by deepening backward integration into membrane chemistry and solid-state electrode fabrication. Siemens Healthineers and Thermo Fisher Scientific should expand captive sensor production capacity to defend consumable margin streams against emerging spectrophotometric competitors. Enterprise-wide contract consolidation spanning multi-site health systems represents the priority defensive lever.
For New Entrants and Emerging Players: Direct-to-clinic digital sales channels bypass established distributor relationships that lock out regional assemblers. Rural health clinics and federally qualified health centers in underserved United States counties offer the most penetrable white-space for compact waived-complexity devices. Home hemodialysis monitoring applications provide a second entry vector through connectivity-enabled simplified designs.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale diagnostic specialists with maintenance-light point-of-care portfolios in United States geographies. Long-term viability over the next decade hinges on FDA breakthrough device pathway navigation and CLIA complexity waiver expansion. Watch for health system procurement department consolidation announcements as inflection indicators signaling accelerated contract rationalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Chemistry | Captive ionophore production secures margin control against European specialty chemical concentration. |
| CLIA Waived-Complexity Certification Investment | FDA pathway expansion unlocks emergency department and rural clinic placement economics. |
| Hospital System Partnership | Enterprise-wide contracts with integrated delivery networks compress competitor field service organizations. |
| Software Companion Development | Cloud-connected calibration features satisfy FDA software-as-medical-device cybersecurity requirements. |
| Reimbursement Strategy | CPT code alignment for point-of-care electrolyte panels accelerates satellite clinic adoption. |
Research Methodology
Document review covered FDA 510(k) premarket notification databases, CLIA complexity categorization records, and EU In Vitro Diagnostic Regulation technical documentation, complemented by interviews with hospital laboratory directors, biomedical engineers, GPO contracts managers, and ion-selective electrode manufacturing specialists. Secondary validation drew from CMS Medicare reimbursement data, hospital procurement databases, and SEC filings of listed diagnostic equipment manufacturers. Bottom-up electrolyte analyzer installation estimates and top-down health system capital expenditure patterns were triangulated to establish market sizing.
Cross-referencing historical CLIA waiver expansion patterns against panel input from health system procurement officers shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include analyzer configuration, sensing modality, deployment setting, and end-user purchasing authority structure. CAGRs were derived from electrolyte testing volume trajectories and health system consolidation timelines. Forecast inputs incorporated silver spot price volatility assumptions and solid-state electrode miniaturization adoption curves.
The model holds under continued FDA-CLIA regulatory convergence and stable precious metal input costs; deviation in optical multi-analyte platform substitution rates or tariff escalation on Chinese-assembled sensors would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Laboratory Data Loggers Market
Laboratory Equipment
Laboratory Freezers Market
Laboratory Equipment
Vacuum Tissue Processors Market
Laboratory Equipment
Point of Care (POC) Coagulation Testing Devices Market
Laboratory Equipment
Vacuum Blood Collection Tube Market
Laboratory Equipment
Blood Bank Analyzers Market
Laboratory Equipment
Laboratory Rockers and Shakers Market
Laboratory Equipment
Global Laboratory Equipment and Disposables Market
Laboratory Equipment
Global Automated Analyzers Market
Laboratory Equipment
Cuvettes Market
Laboratory Equipment
Pipettes and Accessories Market
Laboratory Equipment
Laboratory Ovens Market
Laboratory Equipment
Histopathology Testing Equipment Market
Laboratory Equipment
Muffle Laboratory Furnaces Market
Laboratory Equipment
C-Reactive Protein Analyzers Market
Laboratory Equipment
Middle East and Africa Laboratory Hoods and Enclosure Market