
 Railway Interiors Market | 2026-2036
Railway Interiors Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Interiors Market Analysis
Lifecycle maintenance contracts for interior subsystems is repositioning supplier economics toward recurring revenue streams rather than one-time fit-outs. Faurecia leverages its automotive seating expertise to compete in rail-specific ergonomic platforms. Siemens Mobility anchors European high-speed interior refurbishments through integrated design-to-installation capabilities. Alstom SA dominates premium cabin configurations for cross-border corridors with fire-certified composite solutions.
Railway interiors encompass the complete fitted environment within passenger and crew compartments, including seating modules, lighting arrays, wall panels, flooring systems, and integrated safety hardware manufactured to EN 45545-2 fire standards and UIC 564-2 smoke toxicity protocols. Their primary purpose is to ensure occupant safety, comfort, and operational durability across rolling stock lifespans exceeding thirty years. Seating and flooring categories carry the largest installed base replacement cycles, while smart interiors and energy-saving systems represent the fastest-expanding margin pools as operators retrofit existing fleets. Metal and composite materials lead new-build specifications, though plastic formulations sustain demand in cost-sensitive commuter segments.
EU regulations including EN 45545-2, REACH, and the EU Green Deal push manufacturers toward low-emission material sourcing and end-of-life recyclability for interior components. China's NMPA and GB standards enforce fire-retardant certification parallel to European norms, creating dual-compliance burdens for multinational suppliers. Stakeholders must monitor divergence between regional fire-safety test protocols and carbon-accounting rules when configuring global product platforms.
Market Dynamics
Fire-safety certification mandates are compressing supplier qualification timelines while fleet renewal programs across Asia and Europe simultaneously expand procurement volumes for EN 45545-2 compliant interior systems.
Growth Catalysts
- EN 45545-2 Harmonization:Cross-border European rail corridors now require unified fire-safety certification, eliminating redundant testing and accelerating material approval cycles for composite seating and wall panel suppliers.
- China's Fleet Modernization:High-speed rail operators under NMPA and GB standards are replacing legacy interiors with smart cabin systems, creating concentrated demand for integrated lighting and passenger information displays.
- Composite Material Substitution:Fire-certified phenolic and thermoplastic composites are displacing traditional metal substrates in seating structures, reducing weight while meeting UIC 564-2 smoke toxicity thresholds.
Market Restraints
- Aluminum Price Volatility:Structural framing and flooring substrates remain exposed to London Metal Exchange fluctuations, compressing margins on fixed-price refurbishment contracts.
- Regional Certification Fragmentation:Divergence between China's GB standards and European EN protocols forces suppliers to maintain parallel testing facilities, inflating R&D overhead.
- Legacy Fleet Lock-In:Thirty-year rolling stock lifespans in North America and Eastern Europe delay interior replacement cycles, constraining near-term addressable market expansion.
Strategic Opportunities
- India's Dedicated Freight Corridors:Crew compartment upgrades for high-capacity freight routes present untapped demand for ergonomic seating and climate-controlled cabin systems under BIS certification pathways.
- EU Green Deal Material Mandates:End-of-life recyclability requirements for interior components are creating first-mover advantages for suppliers with closed-loop composite recovery processes.
- Predictive Maintenance Integration:Sensor-embedded flooring and seating modules that feed real-time wear data into fleet management platforms are opening recurring revenue streams beyond initial fit-out sales.
Industry Challenges
- Fire-Safety Certification Bottlenecks:EN 45545-2 testing queue backlogs at notified bodies extend product launch timelines by twelve to eighteen months, freezing working capital in pre-qualified inventory.
- Multi-Material Integration Complexity:Combining thermoplastic composites, metal substrates, and electronic systems within single cabin modules creates interface failures during thermal cycling validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Interiors Market |
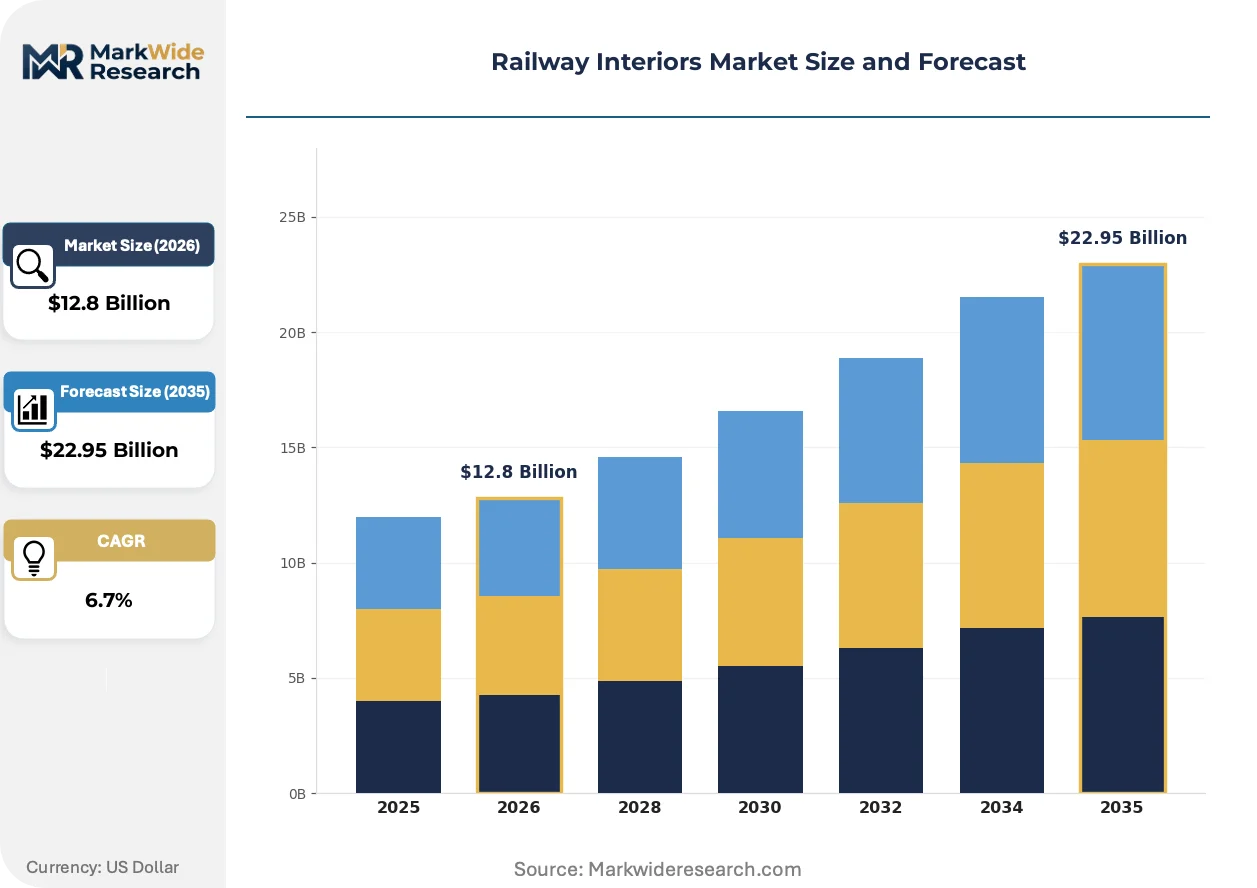
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seating, Lighting, Walls, Flooring Material: Metal, Wood, Plastic, Composite End User: Passenger Trains, Freight Trains, High-Speed Rail, Subways Technology: Smart Interiors, Energy-Saving Systems, Sound Insulation, Safety Systems |
| Companies Covered | CRRC Corporation Limited, Faurecia, Hitachi Rail Limited, Knorr-Bremse AG, GRAMMER AG, Siemens Mobility, Bombardier Transportation, Toshiba Corporation, Alstom SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Interiors Market Emerging Trajectories
Digital cabin ecosystems and sustainable material platforms are converging to redefine passenger experience specifications, with procurement criteria now weighting lifecycle carbon intensity alongside fire-safety performance.
Modular seating architectures with standardized rail-mount interfaces are consolidating supplier ecosystems around platform-based product families. European high-speed operators and Asian metro systems are adopting these systems to compress refurbishment downtime from weeks to days. This consolidation is compressing the addressable supplier base while elevating contract values for qualified platform providers.
REACH chemical restriction expansions are accelerating substitution of halogenated flame retardants in textile and foam applications. ECHA's 2023-2024 substance evaluation roadmap has designated several legacy fire-safety additives as Substances of Very High Concern, forcing reformulation of seat upholstery and insulation layers. German and French operators are now specifying phosphorus-based alternatives in tender documents, with compliance deadlines compressing material transition timelines.
Lifecycle service agreements are displacing transactional fit-out contracts as the dominant commercial model. Rolling stock lessors and maintenance providers are unbundling interior subsystem ownership from operator procurement, transferring obsolescence risk to specialized service firms. This restructuring is most visible in British and Japanese commuter fleets, where availability-based payment structures now govern seating, lighting, and HVAC refresh cycles.
Railway Interiors Market Segmentation
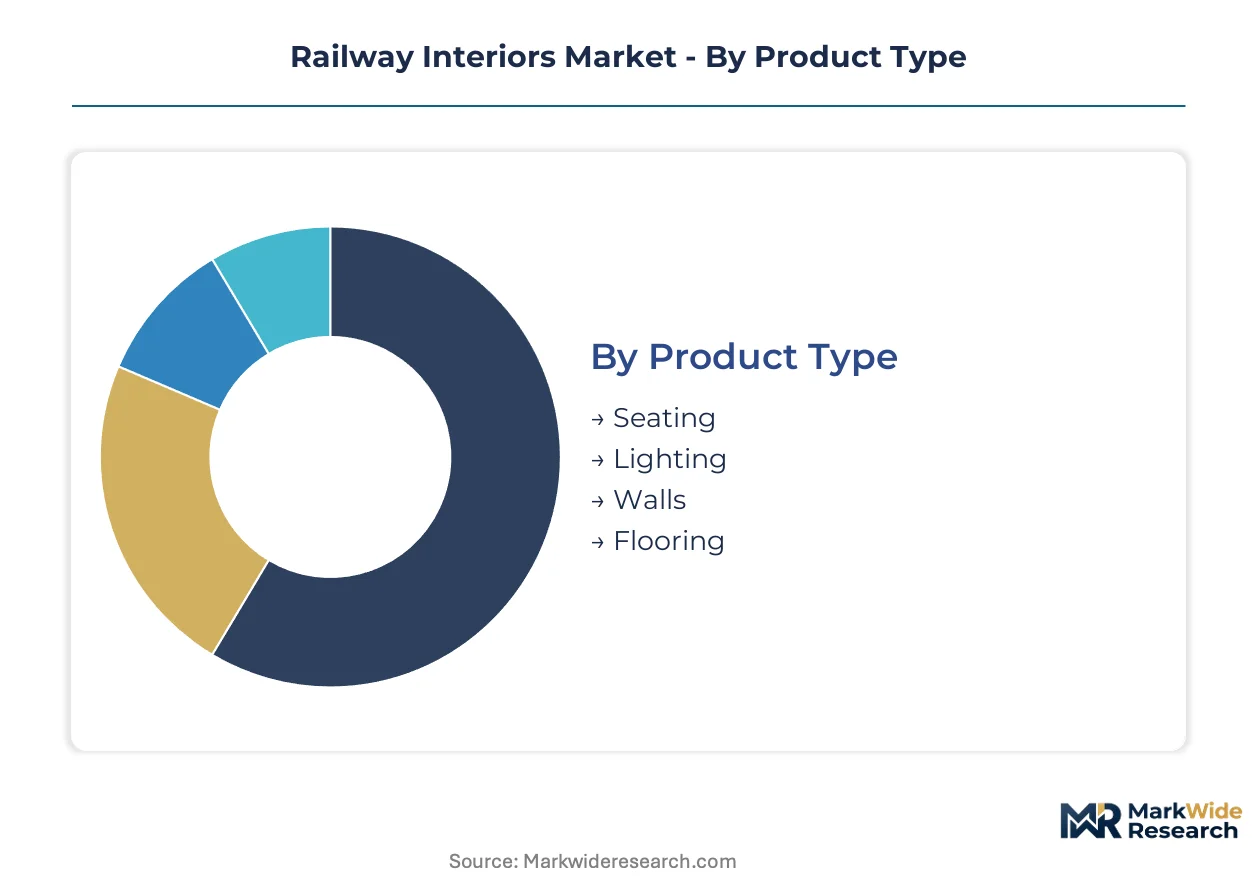
Railway interior procurement splits across four orthogonal dimensions, each carrying distinct certification burdens and margin profiles. Suppliers configure product platforms around fire-safety tiers rather than pure performance specifications, creating segment-specific qualification moats.
Product Type:
EN 45545-2 testing intensity varies sharply across product categories, with seating and wall panels facing the most stringent HL3 hazard level requirements while lighting arrays navigate electromagnetic compatibility overlays.
- Seating:Composite and metal-framed modules with fire-retardant upholstery must satisfy UIC 564-2 smoke density protocols alongside mechanical durability cycles. High-speed rail operators in Germany and Japan are consolidating procurement around platform-based families with standardized rail-mount interfaces.
- Lighting:LED arrays with integrated passenger information displays require dual certification under EN 45545-2 for fire performance and IEC 60598 for electrical safety. China's fleet modernization programs are absorbing concentrated volumes of smart cabin lighting with real-time occupancy sensors.
- Walls:Phenolic composite panels with low-smoke emissions dominate premium cabin configurations.
- Flooring:Rubber-aluminum substrates and sensor-embedded composites serve high-traffic corridors.
Seating sits at the top of the volume ranking, with lighting climbing the fastest.
Material:
Cost-to-weight ratios and end-of-life recyclability mandates are polarizing material selection between premium fleet renewals and cost-sensitive commuter segments.
- Metal:Aluminum and steel framing remains standard for structural seating substrates and flooring support grids. European high-speed corridors specify aluminum for weight reduction, though London Metal Exchange volatility compresses margin stability on fixed-price contracts.
- Composite:Fire-certified phenolic and thermoplastic formulations are displacing metal in seating shells and wall panels. REACH restrictions on halogenated flame retardants are accelerating phosphorus-based composite adoption in French and German tenders.
- Plastic:ABS and polycarbonate blends sustain demand in metro and commuter interiors where cost thresholds override premium specifications.
- Wood:Veneered plywood with intumescent coatings retains niche presence in luxury dining and lounge configurations.
Metal retains the largest installed base, with composite gaining share fastest.
End User:
Application context dictates fire-safety tier, passenger density, and refurbishment cycle frequency, with high-speed rail commanding premium specifications and freight presenting untapped retrofit potential.
- High-Speed Rail:Cross-border European services and Asian bullet trains require EN 45545-2 HL3 certification across all interior subsystems. Operators in China, Germany, and Japan are driving concentrated demand for integrated smart cabin ecosystems.
- Subways:High-frequency urban networks prioritize rapid-refurbishment modular seating and vandal-resistant surfaces. Fire-safety mandates align with EN 45545-2 but testing cycles compress due to accelerated wear profiles.
- Passenger Trains:Regional and intercity services balance cost constraints with mid-tier fire certification.
- Freight Trains:Crew compartment upgrades for long-haul routes under India's Dedicated Freight Corridors are opening specification windows for ergonomic seating and climate control.
High-speed rail commands the highest contract values, with freight train interiors expanding most quickly.
Technology:
Digital integration intensity separates legacy fit-outs from next-generation cabin platforms, with predictive maintenance capabilities now weighted in procurement scoring.
- Smart Interiors:Sensor-embedded seating, connected lighting, and passenger information displays feed real-time data into fleet management platforms. Japanese and British commuter fleets are adopting availability-based service contracts that transfer subsystem ownership to specialized providers.
- Safety Systems:Fire detection, emergency lighting, and evacuation signage must integrate with rolling stock control architectures. EN 45545-2 compliance extends to wiring harnesses and electronic enclosures.
- Energy-Saving Systems:LED lighting with occupancy-based dimming and HVAC-integrated climate zones reduce operational expenditure.
- Sound Insulation:Multi-layer composite panels and acoustic underlayment address noise criteria in high-speed tunnels.
Safety systems anchor procurement volumes, with smart interiors showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's fleet modernization programs generate procurement volumes that dwarf Germany's cross-border corridor upgrades, yet both markets enforce stringent fire-safety protocols that shape supplier qualification requirements.
China
NMPA and GB standards drive replacement of legacy interiors across high-speed rail networks. The national railway operator mandates EN 45545-2 parallel certification for all imported subsystems. CRRC Corporation and its supplier cluster in Changchun dominate domestic smart cabin integration for new-build rolling stock.
Germany
Deutsche Bahn's ICE fleet refurbishment creates concentrated demand for HL3-certified composite seating and wall panels. KBA enforcement of unified fire-safety rules accelerates material approval for cross-border services. Siemens Mobility anchors design-to-installation capabilities from its Munich and Erlangen engineering centers.
Japan
Shinkansen operators under METI guidelines adopt availability-based contracts for interior subsystems. JIS standards align with UIC protocols for smoke toxicity testing. The Nagoya-Osaka industrial corridor hosts specialized composite fabricators serving JR Central and JR East procurement programs.
India
Dedicated Freight Corridor projects under Indian Railways generate specification windows for crew compartment upgrades. BIS certification pathways for fire-retardant materials remain under development. Manufacturing clusters in Chennai and Pune supply seating modules for both passenger and emerging freight applications.
France
SNCF's TGV fleet renewal prioritizes REACH-compliant low-emission materials for premium cabin configurations. ANSM oversight of chemical restrictions accelerates phosphorus-based flame retardant adoption. Alstom SA leverages its Saint-Ouen design headquarters to coordinate cross-border corridor specifications.
Railway Interiors Market Vendor Landscape
Top-tier vendors anchor platform-based product families, while mid-tier specialists compete on modular refurbishment speed. The supplier base concentrates around three strategic archetypes: integrated rolling stock manufacturers with captive interior capabilities, independent seating and subsystem specialists, and automotive-tier suppliers extending into rail-specific ergonomic platforms. Competitive positioning hardens through M&A consolidation of testing and certification assets, plus long-term service agreements that transfer subsystem ownership from operators to vendors.
Among integrated rolling stock manufacturers, CRRC Corporation Limited, Siemens Mobility, and Alstom SA occupy positions that exemplify the convergence of design authority and installation capability. These entities represent the tier where fire-safety certification, smart cabin integration, and lifecycle service obligations consolidate into unified contract structures. Their geographic footprints span the primary procurement markets of China, Germany, and France respectively.
| Leading Market Players |
|---|
| CRRC Corporation Limited |
| Faurecia |
| Hitachi Rail Limited |
| Knorr-Bremse AG |
| GRAMMER AG |
| Siemens Mobility |
| Bombardier Transportation |
| Toshiba Corporation |
| Alstom SA |
| Others |
Supply Flow & Price Mechanics
Composite material substitution in seating structures and wall panels is compressing unit economics while redistributing procurement power toward suppliers with captive phenolic resin compounding capabilities. This production-method transition simultaneously lowers finished-goods weight and elevates supplier concentration around certified composite fabricators in Germany, Japan, and China's Changchun cluster.
Pricing Analysis
Capacity additions in China's Changchun and Germany's Bavaria industrial corridors are reshaping price floors for EN 45545-2 HL3-certified seating modules. Pricing stratifies across premium, standard, and economy tiers based on fire-safety certification level and after-sales service bundling. Cost compression in standard-tier commuter seating is intensifying because aluminum price volatility on London Metal Exchange contracts squeezes fixed-price refurbishment margins. Freight train operators exhibit highest price sensitivity due to unproven crew-compartment upgrade budgets, while high-speed rail procurement teams prioritize certification reliability over unit cost.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Nagoya, and Shanghai anchor hub-and-spoke patterns for just-in-time delivery to rolling stock assembly plants. Supply concentrates in Germany, China, and Japan for phenolic composite substrates, aluminum structural framing, and LED lighting arrays. The chain draws from petrochemical feedstocks for thermoplastic formulations, copper for electrical harnesses, and rare-earth elements for LED phosphors. Single-source vulnerability around EN 45545-2 testing queue backlogs at notified bodies creates twelve-to-eighteen-month inventory freezes. Distribution runs through Tier 1 subsystem integrators who consolidate multi-material modules before final fit-out.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in railway interiors rests on composite material substitution reducing aluminum dependency and smart cabin service contracts capturing recurring revenue streams. Premium-tier procurement for cross-border European corridors and Asian high-speed networks is accelerating this shift.
For Market Incumbents: Acquire fire-safety certification assets and testing facility capacity to compress product launch timelines threatened by notified body queue backlogs. Defensive consolidation around captive phenolic resin compounding secures input cost stability against petrochemical volatility. Siemens Mobility and Alstom SA anchor this strategy through integrated design-to-installation capabilities that transfer subsystem obsolescence risk to operators. For New Entrants and Emerging Players: The price-point gap between premium HL3-certified modules and economy-tier plastic formulations creates entry space for mid-tier composite specialists. India's Dedicated Freight Corridor crew-compartment upgrades present the most penetrable geography, with BIS certification pathways still under development. A go-to-market angle targeting availability-based service contracts for regional passenger fleets bypasses capital-intensive new-build procurement barriers. For Investors and Strategic Acquirers: Roll-up economics work for modular seating platform specialists because EN 45545-2 qualification moats protect recurring revenue streams across thirty-year rolling stock lifespans. Long-term viability over a five-to-ten-year horizon favors targets with closed-loop composite recovery processes aligned to EU Green Deal mandates. The signal to watch is REACH restriction expansions accelerating phosphorus-based flame retardant substitution, which rewards first-mover material reformulation capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Fire-Safety Certification Investment | Notified body partnerships compress EN 45545-2 testing queues that currently freeze working capital for twelve to eighteen months. |
| Closed-Loop Composite Recovery | End-of-life recyclability processes align with EU Green Deal mandates and create first-mover advantages in French and German tenders. |
| Predictive Maintenance Integration | Sensor-embedded seating modules feeding fleet management platforms open recurring revenue streams beyond initial fit-out sales. |
| Platform Standardization | Modular rail-mount interfaces compress refurbishment downtime from weeks to days across European high-speed and Asian metro networks. |
| Regional Distribution Footprint | Hub-and-spoke logistics in Stuttgart, Nagoya, and Shanghai reduce delivery lead times to CRRC Corporation and Siemens Mobility assembly plants. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with rolling stock manufacturers, interior subsystem procurement managers, fire-safety testing engineers, and fleet maintenance directors with secondary validation. Primary sources included EN 45545-2 certification databases, UIC smoke toxicity protocol filings, and customs records for aluminum and phenolic resin trade flows. Secondary sources encompassed Deutsche Bahn and SNCF tender documents, CRRC Corporation supplier disclosures, and ECHA substance evaluation roadmaps. Bottom-up segment sizing triangulated against top-down rolling stock production forecasts.
Comparable-period anchoring tied projection assumptions to historical fleet renewal cycles and material substitution patterns observed across the analysis window. The analytical framework modeled demand across product type, material grade, end-user application, and technology integration intensity. CAGRs derived from segment-level volume trajectories weighted by EN 45545-2 certification tier penetration. Industry-specific inputs included aluminum London Metal Exchange volatility assumptions and REACH restriction implementation timelines for halogenated flame retardants.
Caveats apply where divergence between China's GB standards and European EN protocols could materially shift the outlook for multinational supplier qualification costs. Forecasts reflect documented assumptions regarding fleet modernization program pacing and composite material adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Underbody Coatings Market
Automotive Interior & Exterior
Automotive Door Check Market
Automotive Interior & Exterior
Automotive Interior Leather Market
Automotive Interior & Exterior
Europe Automotive Upholstery Market
Automotive Interior & Exterior
Auto Ventilated Seats Market
Automotive Interior & Exterior
Automotive Interior Bovine Leather Market
Automotive Interior & Exterior
Automotive Center Stack Display Market
Automotive Interior & Exterior
Global Luxury Car Coachbuilding Market
Automotive Interior & Exterior
Automotive Floor Carpet Market
Automotive Interior & Exterior
Heated Steering Wheel Market
Automotive Interior & Exterior
Germany Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Outside Rearview Mirrors (ORVM) Market
Automotive Interior & Exterior
Asia Pacific Automotive Interiors Market
Automotive Interior & Exterior
Automotive Overhead Console Market
Automotive Interior & Exterior
Automotive Fridge Market
Automotive Interior & Exterior
India Automotive Adaptive Lighting System Market