
 Digital Infrared Thermometer Market | 2026-2036
Digital Infrared Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Infrared Thermometer Market Insights
Clinical-grade accuracy specifications is rotating demand away from consumer-grade units toward devices validated for hospital triage and fever screening. Welch Allyn leverages its diagnostic equipment heritage to anchor premium positioning in acute care settings. Exergen Corporation specializes in temporal artery measurement technology and competes on speed-of-reading protocols. OMRON Corporation extends its home health monitoring footprint into professional channels with multi-functional thermometer platforms.
A digital infrared thermometer measures thermal radiation emitted by surfaces or bodies using pyroelectric or thermopile sensors, converting infrared energy into electrical signals with typical response times under one second and accuracy tolerances of ±0.2°C in clinical variants. Its primary purpose spans fever detection in medical settings, food safety verification in commercial kitchens, and non-destructive thermal monitoring across industrial equipment. Handheld configurations dominate volume shipments due to portability requirements in point-of-care and field service environments, while fixed installations gain traction in automated access-control screening at institutional entrances. Fever Monitoring applications command the strongest margin pools as healthcare procurement prioritizes traceable calibration and compliance documentation over price sensitivity.
The FDA governs clinical infrared thermometers through 510(k) premarket notification requirements that mandate equivalence to predicate devices for accuracy and biocompatibility. EMA's Medical Device Regulation in Europe imposes stricter post-market surveillance and unique device identification obligations that raise compliance costs for non-EU manufacturers. China's NMPA enforces GB standard compliance for infrared clinical thermometers sold through hospital procurement channels. Stakeholders must monitor evolving convergence between consumer wellness positioning and regulated medical claims as enforcement agencies tighten advertising scrutiny on temperature devices marketed for diagnostic use.
Market Dynamics
The migration from mercury-based and contact thermometry toward non-contact infrared screening is compressing replacement cycles and elevating performance verification requirements across healthcare procurement.
Growth Catalysts
- Hospital triage protocols:Post-pandemic screening mandates in China's tier-one hospital systems and Germany's outpatient clinic networks sustain institutional procurement volumes for clinical-grade units.
- 510(k) pathway streamlining:FDA's updated clearance requirements for clinical infrared devices accelerate time-to-market for manufacturers meeting predicate equivalence standards.
- Food safety automation:Commercial kitchen chains deploy handheld infrared units for HACCP compliance, expanding the addressable base beyond medical applications.
Market Restraints
- Thermopile sensor concentration:Production of high-precision pyroelectric sensors concentrates among East Asian component suppliers, creating single-source vulnerability for Western device assemblers.
- GB standard compliance costs:China's NMPA registration reforms impose testing and documentation burdens that raise barriers for smaller manufacturers lacking in-country certification infrastructure.
- Smartphone thermal imaging substitution:Consumer-grade smartphone attachments with FLIR Lepton modules capture price-sensitive wellness monitoring demand that previously flowed to dedicated thermometers.
Strategic Opportunities
- Industrial predictive maintenance:Fixed-installation infrared monitoring for electrical panel and rotating equipment diagnostics opens equipment OEM channel partnerships beyond medical distributors.
- EMA MDR convergence:Stricter European post-market surveillance and unique device identification obligations favor manufacturers with established quality management systems, consolidating share among compliant suppliers.
- Remote patient monitoring integration:Home health platforms seek API-enabled thermometers that feed temperature data into telehealth dashboards, creating software-layer differentiation.
Industry Challenges
- Calibration technician scarcity:Traceable calibration documentation for clinical procurement requires certified metrology personnel that hospital systems and distributors struggle to retain.
- Legacy EMR integration complexity:Fever screening data capture at automated access-control points must interface with Epic, Cerner, and regional hospital information systems through non-standardized protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Infrared Thermometer Market |
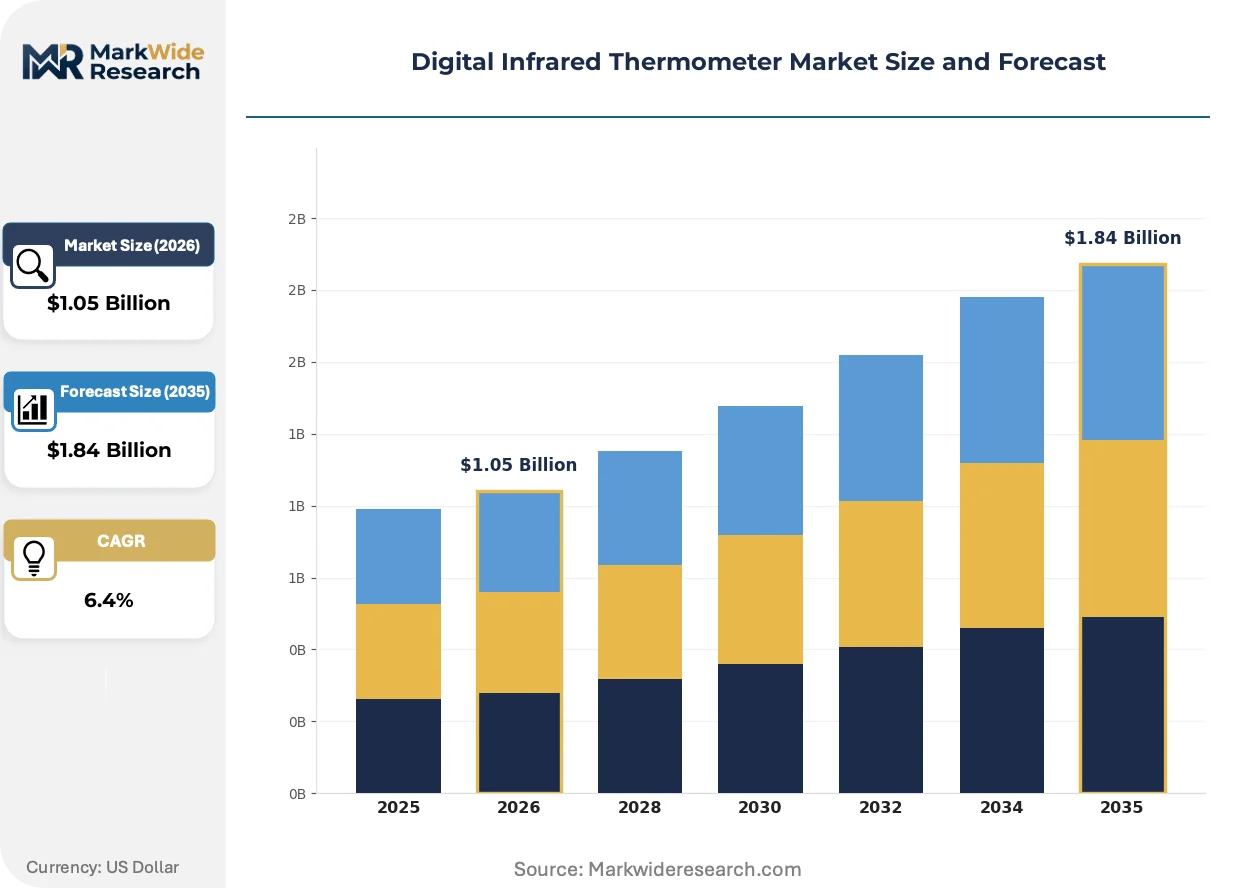
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Fixed, Wireless, Multi-Functional End User: Healthcare Facilities, Restaurants, Schools, Households Technology: Non-Contact, Laser, Infrared, Digital Application: Fever Monitoring, Cooking, Industrial, Veterinary |
| Companies Covered | Welch Allyn, Exergen Corporation, Geratherm Medical AG, Microlife Corporation, OMRON Corporation, Cardinal Health, CONTEC MEDICAL SYSTEMS, Fluke Corporation, Testo SE & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Infrared Thermometer Market Trends and Innovations
Sensor miniaturization and embedded connectivity are redefining device architecture, while regulatory convergence between wellness and medical claims tightens marketing boundaries.
Multi-sensor fusion arrays combining thermopile infrared with ambient temperature compensation and distance sensors are displacing single-element designs in premium clinical units. Acute care facilities in the United States and Japan prioritize these configurations for triage throughput. The shift compresses margin pools for basic handheld units while elevating firmware and algorithm development as competitive differentiators.
EMA's Medical Device Regulation imposes post-market clinical follow-up and periodic safety update reporting obligations that extend compliance timelines for infrared thermometers marketed with diagnostic claims. Manufacturers must maintain vigilance systems and trend analysis capabilities that consumer-grade suppliers rarely possess. European hospital procurement channels increasingly require MDR certificates as gatekeeping criteria, filtering out wellness-positioned competitors.
Buyers in China's hospital procurement systems now bundle infrared thermometers into broader infection control equipment frameworks rather than sourcing standalone devices. Distributor relationships with provincial procurement platforms determine access more than product specifications alone. This concentration of purchasing authority favors suppliers with established government sales infrastructure and documented GB standard compliance histories.
Digital Infrared Thermometer Market Segmentation
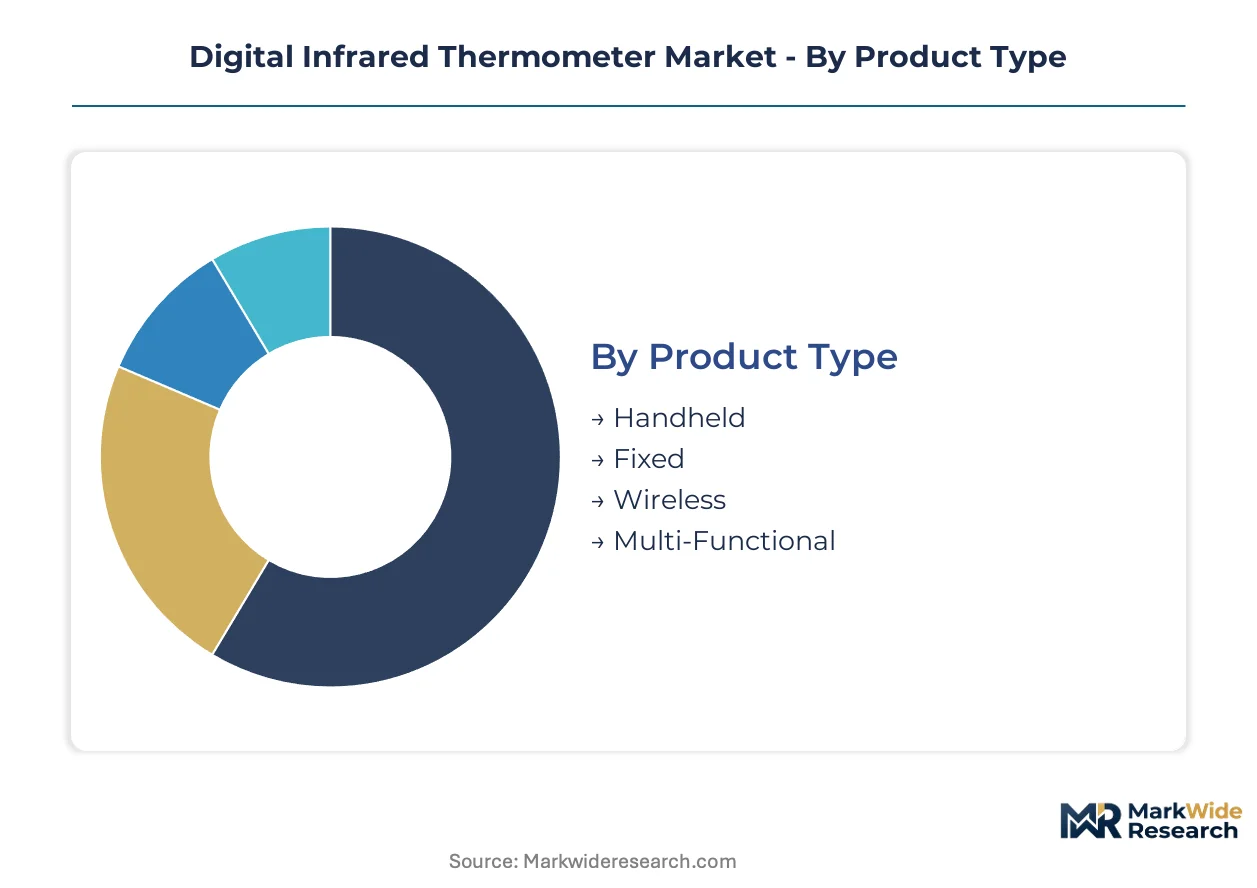
Segmentation in digital infrared thermometers reveals distinct procurement patterns across clinical, commercial, and consumer channels. Product architecture and connectivity features determine pricing power, while regulatory classification separates medical-grade from wellness-positioned units.
Product Type:
Handheld configurations dominate domestic hospital procurement in the United States and Germany, while fixed installations anchor export-led demand from Chinese manufacturing bases into automated access-control deployments.
- Handheld:Portable units with thermopile sensors and sub-one-second response times serve point-of-care triage and field service environments. Demand concentrates in China's tier-one hospital systems and Germany's outpatient clinic networks, driven by post-pandemic screening mandates requiring traceable calibration documentation.
- Fixed:Wall-mounted or gantry systems with multi-sensor fusion arrays enable automated fever screening at institutional entrances. Export volumes from Chinese OEMs into European and North American airport and corporate campus deployments are climbing the fastest as EMA MDR compliance becomes a procurement gatekeeper.
- Wireless:Bluetooth-enabled devices feed temperature data into telehealth dashboards and EMR systems through API protocols.
- Multi-Functional:Hybrid platforms combining infrared thermometry with pulse oximetry or blood pressure monitoring extend home health monitoring footprints into professional channels.
Handheld holds the largest share; momentum sits with fixed installations.
End User:
Cost tier stratification separates clinical procurement with compliance documentation requirements from price-sensitive household purchases lacking calibration traceability.
- Healthcare Facilities:Acute care hospitals and outpatient clinics in the United States, Germany, and China prioritize FDA 510(k)-cleared or NMPA-registered devices with ±0.2°C accuracy tolerances and biocompatibility testing. Procurement runs through group purchasing organizations and provincial platforms that bundle infrared thermometers into broader infection control frameworks.
- Restaurants:Commercial kitchen chains deploy handheld units for HACCP compliance verification at receiving docks and cooking stations. Chains with centralized supply contracts favor multi-unit purchases with standardized calibration intervals over individual franchisee sourcing.
- Schools:Educational institutions in Japan and South Korea adopt fixed-entry screening systems for morning arrival protocols.
- Households:Consumer wellness monitoring absorbs smartphone thermal imaging attachments and basic non-contact units through retail and e-commerce channels.
Healthcare Facilities command premium pricing; Restaurants represent the steepest expansion trajectory beyond medical applications.
Technology:
Application context determines sensor architecture selection, with clinical environments demanding thermopile precision and industrial settings tolerating broader measurement ranges.
- Non-Contact:Pyroelectric and thermopile sensor configurations measure thermal radiation without surface contact, eliminating cross-contamination risks in hospital triage. China's NMPA enforces GB standard compliance for clinical variants sold through hospital procurement channels.
- Laser:Targeting beams improve measurement repeatability in industrial predictive maintenance applications for electrical panels and rotating equipment.
- Infrared:Broad-spectrum thermal detection underlies all product architectures, with wavelength sensitivity tuning for medical versus industrial use cases.
- Digital:Embedded processors convert analog sensor signals with ambient temperature compensation algorithms, enabling accuracy claims that withstand FDA predicate equivalence scrutiny.
Non-Contact anchors clinical procurement; Digital signal processing capabilities differentiate premium tiers.
Application:
Customer type separation between regulated medical claims and unregulated wellness positioning creates divergent margin structures and marketing constraints.
- Fever Monitoring:Clinical-grade fever detection commands the strongest margin pools as healthcare procurement prioritizes traceable calibration, compliance documentation, and EMR integration over price sensitivity. FDA's updated 510(k) clearance pathways and EMA MDR post-market surveillance obligations filter out consumer-grade competitors.
- Cooking:Food safety verification in commercial kitchens and hospitality operations requires surface temperature measurement for HACCP documentation.
- Industrial:Non-destructive thermal monitoring for electrical infrastructure and mechanical equipment diagnostics opens equipment OEM channel partnerships beyond medical distributors.
- Veterinary:Animal health applications in livestock operations and companion animal clinics adapt human clinical designs for fur-bearing species with modified emissivity settings.
Fever Monitoring generates premium returns; Industrial applications are gaining share fastest through predictive maintenance adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany's outpatient clinic networks demonstrate the lowest price sensitivity, prioritizing EMA MDR compliance documentation over unit cost, while household consumers in India and Brazil absorb basic non-contact units through retail channels with minimal calibration requirements.
United States
Acute care hospitals in the United States prioritize FDA 510(k)-cleared devices with ±0.2°C accuracy tolerances for triage throughput. The FDA's updated premarket notification pathways accelerate clearance timelines for predicate-equivalent submissions. Hospital procurement in the Greater Boston and Pacific Northwest corridors bundles infrared thermometers into infection control frameworks through group purchasing organizations.
Germany
Germany's outpatient clinic networks sustain institutional procurement volumes for clinical-grade units with traceable calibration documentation. EMA's Medical Device Regulation imposes post-market surveillance and unique device identification obligations that filter out wellness-positioned competitors. Manufacturing concentration in Baden-Württemberg supplies precision thermopile sensor assemblies to Western European device assemblers.
China
China's tier-one hospital systems in Beijing, Shanghai, and Guangzhou drive demand for NMPA-registered clinical variants. The NMPA's GB standard compliance requirements and registration reforms impose testing burdens that raise barriers for smaller manufacturers. Yangtze River Delta manufacturing clusters export fixed-installation systems into European and North American automated access-control deployments.
Japan
Japanese educational institutions and corporate campuses adopt fixed-entry screening systems for morning arrival protocols. METI oversight of medical device quality management systems aligns with international standards for hospital procurement. Kanto region technology integrators embed multi-sensor fusion arrays into premium clinical units for acute care facilities.
India
India's price-sensitive household segment absorbs basic non-contact units through e-commerce and retail pharmacy channels lacking calibration traceability. CDSCO medical device regulations are tightening for clinical-grade imports sold through hospital procurement. Maharashtra and Karnataka-based distributors serve tier-two city healthcare facilities with cost-optimized handheld configurations.
Digital Infrared Thermometer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with precision sensor developers commanding premium positioning while scale manufacturers optimize for volume shipments in consumer channels. The market structures around three tiers: diagnostic equipment heritage brands, specialized temperature measurement technology developers, and diversified health monitoring platforms. Strategic moves concentrate on portfolio diversification into multi-functional platforms and geographic expansion through distributor partnerships in provincial procurement systems.
Within the diagnostic equipment tier, Welch Allyn anchors premium positioning in acute care settings through its heritage in clinical instrumentation. Exergen Corporation occupies a specialized position in temporal artery measurement technology, competing on speed-of-reading protocols. OMRON Corporation exemplifies the diversified health monitoring archetype, extending home health footprints into professional channels with multi-functional thermometer platforms.
| Leading Market Players |
|---|
| Welch Allyn |
| Exergen Corporation |
| Geratherm Medical AG |
| Microlife Corporation |
| OMRON Corporation |
| Cardinal Health |
| CONTEC MEDICAL SYSTEMS |
| Fluke Corporation |
| Testo SE & Co. KGaA |
| Others |
Pricing and Supply Chain Analysis
Thermopile sensor substitution for legacy pyroelectric configurations is redrawing component sourcing maps while compressing margin structures for Western device assemblers dependent on East Asian suppliers. China's NMPA registration reforms and FDA 510(k) pathway updates simultaneously elevate compliance documentation costs and filter pricing power toward manufacturers with captive metrology capabilities.
Pricing Analysis
After-market calibration service contracts and extended warranty bundles now drive lifetime value capture for clinical-grade manufacturers serving hospital procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared units with EMR integration from basic handheld configurations and consumer wellness devices. Cost compression in the standard tier is intensifying because smartphone thermal imaging attachments capture price-sensitive household demand. Healthcare facilities in Germany demonstrate the lowest price sensitivity, while India's retail pharmacy channels absorb basic units with minimal calibration traceability.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane are elevating inbound logistics costs for European device assemblers sourcing thermopile sensor assemblies. Manufacturing gravity centers on China's Yangtze River Delta, South Korea's sensor foundries, and Germany's precision optics clusters. Production draws from germanium substrates, MEMS fabrication capacity, and rare-earth coating materials. Single-source vulnerability concentrates in high-precision pyroelectric sensor supply. Distribution runs through hospital group purchasing organizations in the United States and provincial procurement platforms in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API-enabled thermometer platforms are redefining this market as a data-layer ecosystem, with interoperability requirements for Epic and Cerner integration creating winner-take-most dynamics among firmware-capable suppliers.
For Market Incumbents: Secure firmware and algorithm development talent pools before semiconductor firms and health IT platforms verticalize into temperature monitoring. Defend hospital procurement relationships through embedded EMR integration capabilities. Channel control via exclusive distributor contracts with provincial platforms in China and GPOs in the United States represents the priority defensive lever against emerging multi-functional health monitoring platforms. For New Entrants and Emerging Players: Anchor in industrial predictive maintenance applications for electrical panel and rotating equipment diagnostics, where FDA clearance requirements do not gate market access. The most penetrable white space sits with equipment OEM channel partnerships beyond medical distributors. Target food safety automation in commercial kitchen chains with HACCP-compliant handheld units. A direct sales model to maintenance directors at manufacturing plants bypasses entrenched medical distribution networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed diagnostic equipment specialists lacking connected health capabilities. The five-to-ten year viability window favors manufacturers with established quality management systems capable of EMA MDR compliance. Acquisition targets should display GB standard compliance histories for China's hospital procurement channels and documented predicate equivalence submissions to FDA. The signal to watch is consolidation among provincial procurement platforms in China, which will concentrate purchasing authority and favor scaled suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Epic and Cerner integration capabilities secure long-term procurement contracts with acute care networks. |
| Software Companion Development | API-enabled temperature data feeds differentiate premium units in telehealth dashboard deployments. |
| CE Marking Pathway | EMA MDR compliance documentation filters wellness-positioned competitors from European hospital channels. |
| Backward Integration into Sensors | In-house thermopile production mitigates single-source vulnerability from East Asian component suppliers. |
| Reimbursement Strategy | Traceable calibration documentation aligns with CMS quality metrics for hospital infection control protocols. |
Research Methodology
Cross-validation between hospital procurement database analysis and regulatory filing review anchors the qualitative findings in this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and infection control officers combined with secondary validation from FDA 510(k) clearances, NMPA registration records, EMA MDR certificates, and customs trade data. Bottom-up shipment estimates and top-down market sizing triangulate volume and value outputs.
Sensitivity analysis around thermopile sensor cost trajectories and hospital capital expenditure cycles informs the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, end-user channel, application context, and regional regulatory cluster. CAGRs derive from installed base replacement cycles and penetration rate assumptions for fixed-installation screening systems. Forecast inputs incorporate China's tier-one hospital expansion plans and Germany's outpatient clinic network investment programs.
Underlying assumptions cover sustained post-pandemic screening mandates, stable East Asian component supply, and gradual EMA MDR enforcement tightening, with deviation risk concentrated in smartphone thermal imaging substitution rates and calibration technician scarcity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Non-Contact Infrared Thermometer Market
Sensors and Controls
Inline Quality Control Sensors Market
Sensors and Controls
Europe Air Purifier Market
Sensors and Controls
Smart Temperature Management Market
Sensors and Controls
US Digital Thermometer Market
Sensors and Controls
60GHz Radar Evaluation Kit Market
Sensors and Controls
Active Sensor Market
Sensors and Controls
Inline Viscosity Sensor Market
Sensors and Controls
Active Vibration Control Market
Sensors and Controls
Atomic Clock Market
Sensors and Controls
ECG Sensor Market
Sensors and Controls
Semiconductor Pyrometers Market
Sensors and Controls
Digital Sensor Sleeves Market
Sensors and Controls
Global Load Cell Market
Sensors and Controls
Biomedical Pressure Sensors Market
Sensors and Controls
Accelerometer and Gyroscope Market