
 Canola Meal Market | 2026-2036
Canola Meal Market Size, Share, and Industry Trends Forecast 2026-2036
Canola Meal Market Analysis
ISO 22000 certification is bifurcating the competitive landscape into qualified suppliers and marginal participants. Cargill leverages its integrated crush-to-export infrastructure across the Canadian prairies. Viterra sustains origination dominance through controlled elevator networks in Saskatchewan and Alberta. Bunge Limited competes via specialized containerized shipment protocols for Asian aquaculture clients.
Canola meal denotes the solvent-extracted residue of Brassica napus seed processing, typically containing 36-40% crude protein and residual oil below 3% by weight. This coproduct serves primarily as a rumen-degradable protein source in formulated livestock diets and as an organic nitrogen input in precision agriculture systems. Pellet form commands logistical premiums in transoceanic trade while powder variants penetrate regional compound feed mills. Animal feed applications anchor volume absorption, yet aquaculture end users represent the fastest-expanding demand pool as salmonid producers substitute fishmeal. Food manufacturers occupy a narrow but high-margin niche where defatted flour grades enter plant-protein ingredient portfolios.
CFIA phytosanitary protocols govern Canadian export eligibility, while EU REACH documentation requirements constrain market access for non-compliant processors. China's GB standards for imported oilseed meals impose additional testing burdens on origin facilities. Stakeholders must monitor evolving mycotoxin thresholds across destination jurisdictions to preserve contract continuity.
Market Dynamics
EU Green Deal sustainability criteria are bifurcating the canola meal trade into compliant and excluded supplier tiers, forcing crush facilities to document carbon intensity across prairie supply chains.
Growth Catalysts
- Aquaculture substitution:Salmonid producers in Norway and Chile are accelerating fishmeal replacement with high-protein oilseed meals. This dietary pivot is absorbing premium-grade pellet volumes.
- EU Green Deal:The EU Green Deal's embedded carbon thresholds are redirecting procurement toward Canadian prairie facilities with verified low-carbon crush processes.
- Precision agriculture:Organic nitrogen demand from controlled-environment vegetable operations is creating a secondary outlet for defatted flour grades.
Market Restraints
- Input cost volatility:Canola seed prices track rapeseed oil futures, compressing crush margins when biodiesel demand spikes.
- Supply concentration:Prairie province elevator networks create origination bottlenecks during harvest compression periods.
- Regulatory friction:China's GB standards impose mycotoxin testing regimes that disqualify marginal processors lacking laboratory infrastructure.
Strategic Opportunities
- Underpenetrated aquaculture:Vietnamese pangasius and shrimp operations remain undersupplied with certified oilseed protein.
- Regulatory tailwind:California's Low Carbon Fuel Standard creates indirect demand pull through biodiesel co-product economics.
- Technology convergence:Near-infrared spectroscopy and blockchain traceability are converging to automate quality verification at elevator intake points.
Industry Challenges
- Certification timeline:ISO 22000 and FSSC 22000 audits require 12-18 month implementation cycles that delay export eligibility.
- Capex intensity:Pelleting line upgrades and automated bagging systems demand capital deployment that mid-scale processors struggle to finance.
- Skill scarcity:Qualified oilseed chemists and crush process engineers command premiums that strain prairie facility staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canola Meal Market |
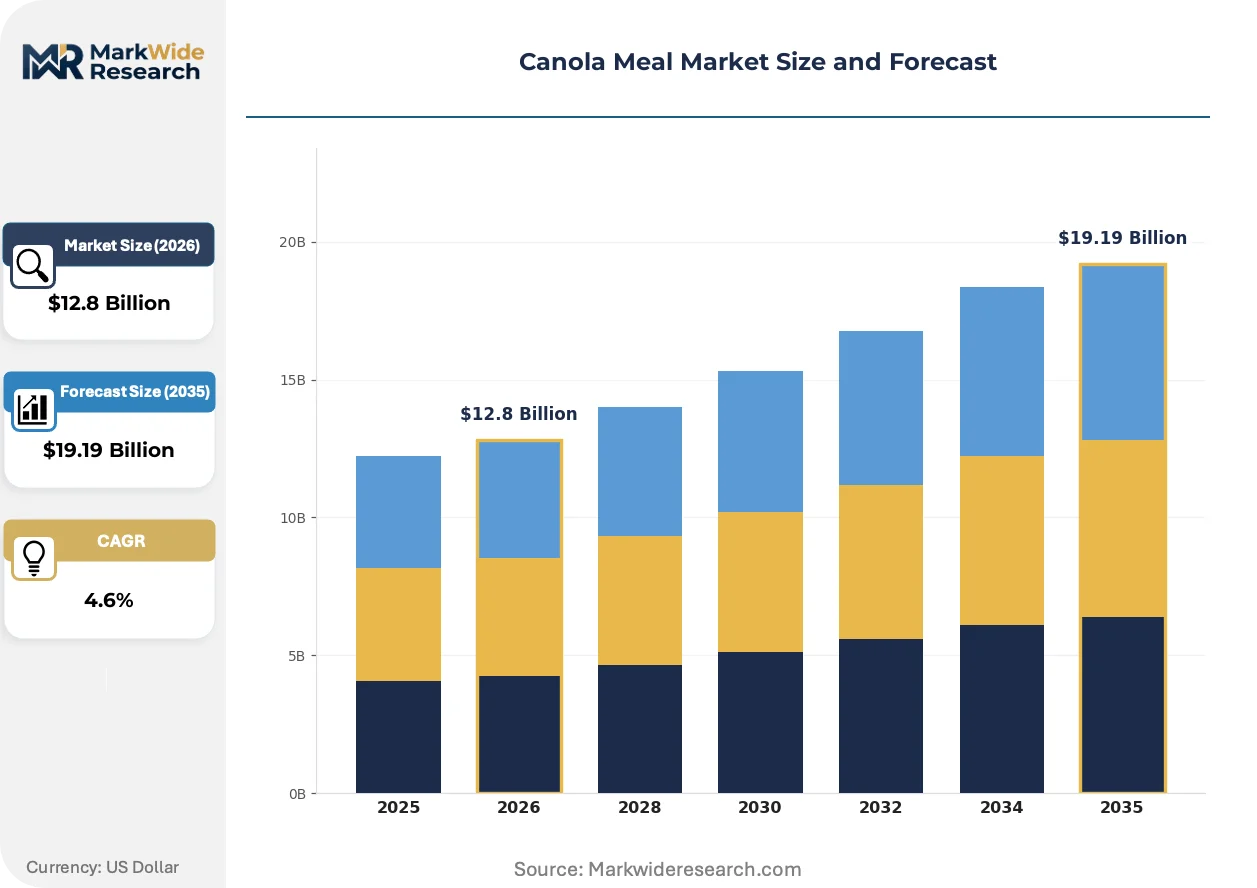
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Animal Feed, Fertilizers, Food Industry, Biofuels Form: Pellets, Powder, Cake, Granules End User: Cattle Farmers, Poultry Producers, Aquaculture, Food Manufacturers Packaging Type: Bags, Bulk, Totes, Containers |
| Companies Covered | Louis Dreyfus Company, Viterra, Cargill, Ag Processing Inc., Nutrien Ltd., Archer Daniels Midland, CHS Inc., MSM Milling, Bunge Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canola Meal Market Emerging Trajectories
Processing technology and verification systems are reshaping how canola meal quality is assured and traded, compressing the gap between origin and destination specifications.
Expeller-pressed canola meal with residual oil above 8% is displacing solvent-extracted standard grades in premium dairy rations. Northeast US organic dairies are adopting this variant at accelerating rates. The displacement is compressing price premiums for high-oil residual products across Atlantic seaboard feed markets.
REACH documentation requirements are forcing EU-bound exporters to submit full substance safety dossiers for each processing batch. This regulatory burden is consolidating export eligibility among crush facilities with dedicated compliance staff. Canadian prairie operators are responding by pre-certifying supply chains through controlled elevator partnerships.
Direct container contracting between prairie crush facilities and Asian aquaculture integrators is shortening traditional broker-mediated procurement cycles. This channel compression is most visible in South Korean salmon feed operations, where buyers now source through single-origin supply agreements rather than commodity traders.
Canola Meal Market Segmentation
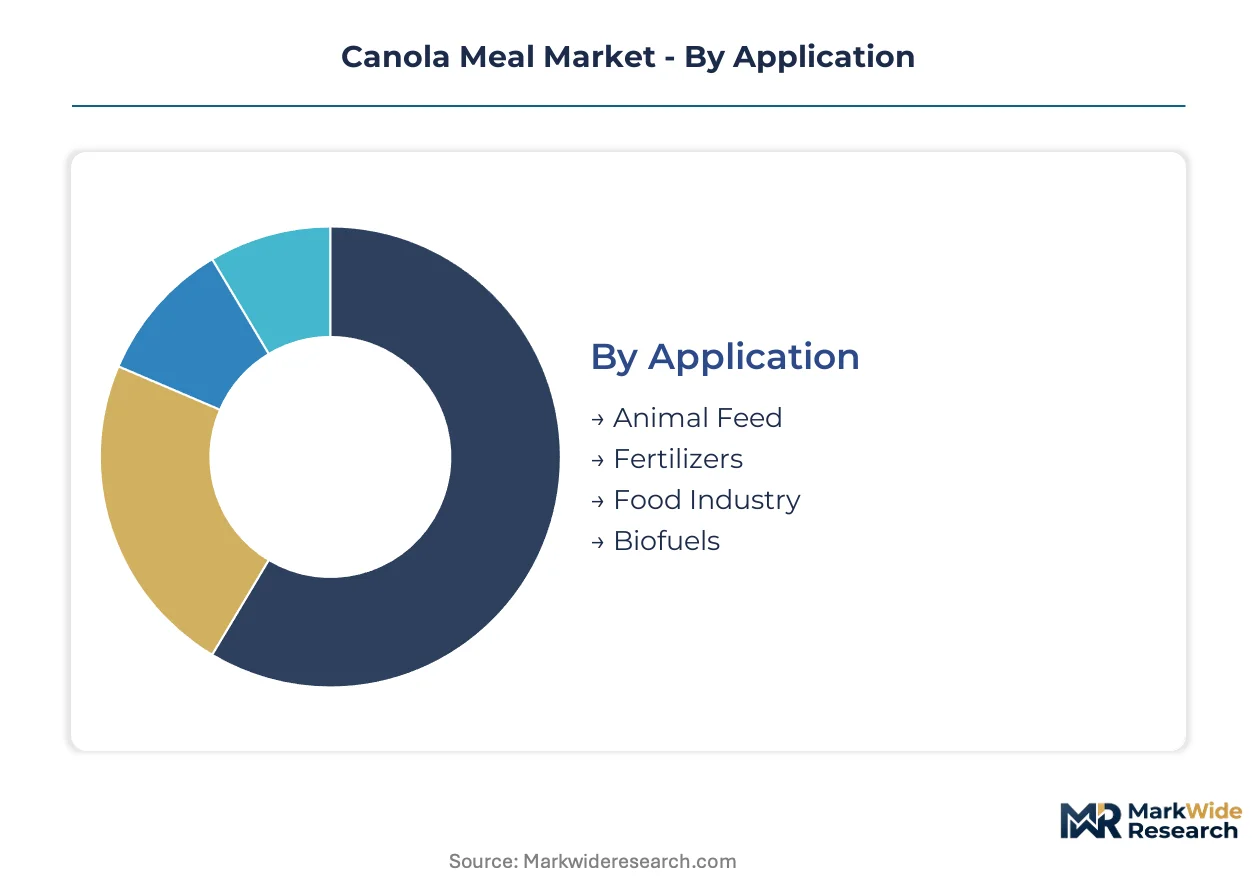
Segmentation in canola meal markets reveals how protein content, handling characteristics, and regulatory compliance create distinct value tiers. Buyers optimize procurement by matching form and application specifications to end-use nutritional requirements and logistics constraints.
Application:
Fishmeal displacement pressure varies sharply across use cases, with some segments facing immediate substitute competition while others maintain protein-source lock-in.
- Animal Feed:Rumen-degradable protein at 36-40% crude concentration anchors formulated diets for dairy and beef operations. Prairie crush facilities direct the majority of solvent-extracted output to North American cattle feeders seeking cost-effective nitrogen sources amid volatile soybean meal pricing.
- Fertilizers:Defatted flour grades deliver organic nitrogen to controlled-environment vegetable producers. Precision agriculture adoption in Canadian greenhouse clusters and California's Central Valley is absorbing secondary-processed meal diverted from feed channels.
- Food Industry:Ultra-low residual oil grades enter plant-protein ingredient portfolios for meat alternatives and bakery applications. Health Canada and FDA GRAS certifications constrain eligible supplier pools to ISO 22000-certified processors.
- Biofuels:High-fiber residual streams from pre-press extraction supply anaerobic digestion feedstock. EU Renewable Energy Directive sustainability criteria restrict eligibility to documented low-carbon supply chains.
Animal Feed retains volume leadership; Fertilizers holds the steepest expansion curve.
Form:
Handling economics and ocean freight rates stratify demand across physical formats, with density and flowability determining regional competitiveness.
- Pellets:Densified form reduces dust losses and improves ship hold utilization for transoceanic movements. Norwegian and Chilean salmonid producers specify pellet grades for automated feed mill handling, commanding logistical premiums over powder alternatives.
- Powder:Standard solvent-extracted meal serves regional compound feed mills with pneumatic conveying infrastructure. Prairie elevator networks deliver powder variants to US Midwest dairy operations within truck-radius economics.
- Cake:Expeller-pressed residues above 8% oil content displace solvent grades in premium organic dairy rations. Northeast US organic certification requirements restrict cake sourcing to mechanical crush facilities with verified non-GMO seed intake.
- Granules:Intermediate sizing bridges pellet flowability and powder cost positioning. Asian aquaculture integrators in Vietnam and Indonesia trial granule formats for shrimp and pangasius feed formulations.
Powder dominates regional procurement; Pellets captures the premium export tier.
End User:
Customer scale and certification sophistication fragment demand, with large integrators driving standardization while specialty producers tolerate supply fragmentation.
- Cattle Farmers:Dairy operations in Wisconsin and Alberta absorb rumen-degradable protein for high-production herds. CFIA and USDA organic protocols bifurcate sourcing between conventional crush output and certified mechanical extraction.
- Poultry Producers:Broiler and layer operations blend canola meal with soybean and distiller's grains for amino acid balance. Southeast US integrators specify low-glucosinolate grades to avoid thyroid interference in breeder flocks.
- Aquaculture:Salmonid producers in Norway, Chile, and British Columbia accelerate fishmeal substitution. Marine Harvest and Cermaq contract directly with prairie crush facilities for single-origin pellet supply with full batch traceability.
- Food Manufacturers:Defatted protein isolates enter meat alternative and sports nutrition formulations. EU REACH documentation and FDA GRAS filings restrict supply base to processors with dedicated compliance staff.
Cattle Farmers anchor volume absorption; Aquaculture generates the fastest share gains.
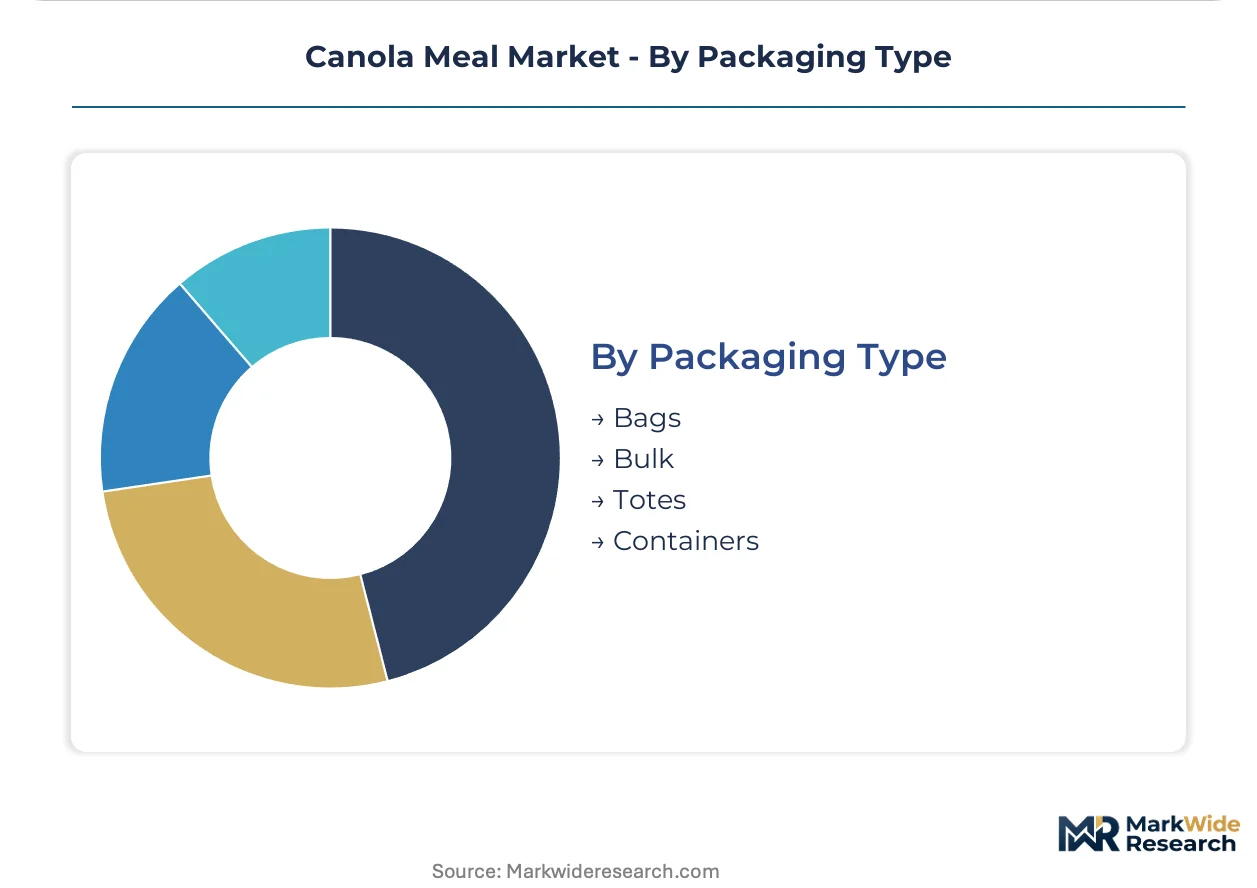
Packaging Type:
Shipment scale and contamination risk define packaging selection, with containerization enabling quality preservation for distant markets.
- Bags:25-50kg woven polypropylene serves small-scale poultry and dairy operations with limited storage infrastructure. Regional feed mills in Saskatchewan and Manitoba specify bagged delivery for just-in-time formulation.
- Bulk:Pneumatic discharge from hopper trucks dominates North American interior movements. Elevator-to-crush-facility bulk transfer minimizes handling costs for standard-grade solvent-extracted meal.
- Totes:Intermediate bulk containers bridge bag flexibility and bulk economics for mid-scale organic operations. California organic dairies specify food-grade totes to prevent cross-contamination with conventional feedstuffs.
- Containers:Sealed 20-foot units with moisture control preserve pellet integrity for Asian aquaculture destinations. South Korean salmon feed integrators mandate containerized shipment with blockchain-documented chain of custody.
Bulk commands domestic volume; Containers secure the export premium tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dairy integrators in Wisconsin and Alberta anchor procurement volume. Salmonid feed mills in Norway and Chile drive premium-grade pellet demand. Prairie province crush facilities serve as the origination backbone for transoceanic trade.
Canada
Prairie province elevator networks concentrate origination capacity in Saskatchewan and Alberta. CFIA phytosanitary protocols govern export eligibility for Asian-bound shipments. Crush facilities in Lloydminster and Lethbridge expand solvent extraction lines to meet aquaculture pellet specifications.
United States
Northeast organic dairies absorb expeller-pressed cake grades above 8% residual oil. EPA biodiesel mandates indirectly pull crush economics through renewable diesel co-product values. Wisconsin dairy cooperatives source rumen-degradable protein from Manitoba processors via Great Lakes rail corridors.
Norway
Marine Harvest and Cermaq contract directly for single-origin pellet supply with full batch traceability. EU Green Deal embedded carbon thresholds redirect procurement toward verified low-carbon prairie facilities. Bergen-area feed mills automate intake handling for densified pellet formats.
China
GB standards for imported oilseed meals impose mycotoxin testing burdens on origin facilities. NMPA registration requirements constrain food-grade protein isolate market access. Crush facilities in the Yangtze River Delta trial blockchain-documented chain of custody for premium aquaculture shipments.
Vietnam
Pangasius and shrimp operations remain undersupplied with certified oilseed protein. The country's national feed safety regulator tightens import documentation for transgenic traceability. Mekong Delta aquaculture clusters trial granule formats for semi-intensive pond systems.
Canola Meal Market Vendor Landscape
Player mix skews toward integrated agricultural conglomerates with captive origination infrastructure. Three tiers structure competitive positioning: multinational traders with containerized export protocols, regional crush specialists with elevator network control, and cooperative processors serving captive membership bases. Dominant moves include prairie elevator acquisition to secure origination flow and pelleting line upgrades to capture aquaculture premium tiers.
Within the integrated trader tier, Louis Dreyfus Company and Bunge Limited occupy positions defined by transoceanic logistics capabilities. Viterra exemplifies the elevator-network archetype through controlled origination infrastructure in Saskatchewan and Alberta. Cargill anchors the crush-to-export model with prairie processing assets.
| Leading Market Players |
|---|
| Louis Dreyfus Company |
| Viterra |
| Cargill |
| Ag Processing Inc. |
| Nutrien Ltd. |
| Archer Daniels Midland |
| CHS Inc. |
| MSM Milling |
| Bunge Limited |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between prairie crush facilities and Norwegian salmon feed integrators lock in supply access and price visibility across volatile rapeseed oil futures cycles. These agreements insulate buyers from spot market spikes while giving processors committed volume through harvest compression periods.
Pricing Analysis
Cost-plus contracts indexed to ICE canola futures and crush margin spreads dominate transoceanic trade. Price differentiation separates ISO 22000-certified pellet grades from standard solvent-extracted powder. Pricing pressure stems from biodiesel demand spikes that compress crush economics. Dairy cooperatives in Wisconsin exhibit highest price sensitivity; aquaculture integrators in Norway tolerate premiums for traceability guarantees.
Supply Chain Analysis
Canada and Australia anchor global canola meal origination through prairie elevator networks and controlled-environment agriculture clusters. Crush operations draw from Brassica napus seed stocks, solvent extraction chemicals, and pelleting binders. Single-source vulnerability concentrates in Saskatchewan elevator networks during harvest windows. Distribution runs through Great Lakes rail corridors for US Midwest dairy feed, with containerized shipment securing Asian aquaculture markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored in aquaculture feed formulation shifts. Salmonid producers accelerating fishmeal substitution provide the demand floor.
For Market Incumbents: Secure backward integration into prairie elevator networks to defend origination flow against Viterra's origination dominance. Invest in automated pelleting lines to capture aquaculture premium tiers before Bunge Limited extends containerized protocols. ISO 22000 certification maintenance is essential as EU Green Deal criteria harden compliance thresholds. For New Entrants and Emerging Players: FSSC 22000 fast-track programs open entry into EU-bound food-grade protein isolates. Vietnamese pangasius operations remain the most penetrable aquaculture segment, with granule format trials offering technical differentiation. Direct contracting with Mekong Delta feed mills bypasses established broker networks. For Investors and Strategic Acquirers: Mid-scale prairie processors with controlled elevator partnerships represent prime acquisition targets. Long-term viability hinges on crush capacity positioned for low-carbon certification under EU sustainability criteria. Watch for CFIA phytosanitary protocol amendments as inflection signals for export eligibility shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Crush Capacity Expansion | Lloydminster and Lethbridge facilities add solvent extraction lines for aquaculture pellet specifications. |
| Backward Integration into Elevators | Cargill and Viterra secure origination flow through controlled Saskatchewan and Alberta networks. |
| ISO 22000 Certification Program | Processors achieve export eligibility for EU food-grade protein isolate markets under REACH documentation. |
| Long-term Supply Agreement | Marine Harvest and Cermaq contract directly for single-origin pellet supply with full batch traceability. |
| Containerized Shipment Protocol | Bunge Limited and Louis Dreyfus Company automate quality preservation for South Korean salmon feed integrators. |
Methodological Framework
The analysis maps solvent-extracted meal, expeller-pressed cake, and food-grade isolate sub-sectors, each validated through crush facility operators, elevator network managers, aquaculture feed formulators, and dairy procurement officers. Primary interviews with prairie processing executives and Norwegian salmon integrators combined with secondary validation from CFIA export records, EU REACH documentation filings, and USDA crush statistics. Bottom-up volume modeling and top-down trade flow analysis provided triangulation.
Consistency checks against customs data and industry association crush reports validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include protein content tier, physical form, end-use application, and destination regulatory cluster. CAGRs derived from historical crush capacity utilization and aquaculture feed formulation adoption curves, with rapeseed oil futures correlation and biodiesel mandate elasticity as key inputs.
Underlying assumptions cover sustained fishmeal substitution rates and EU Green Deal compliance timelines, with deviation risk concentrated in Chinese GB standard amendments and prairie harvest yield volatility. Recalibration cycles align with material shifts in CFIA phytosanitary protocols and salmonid producer contracting patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Protein Hydrolysate Market
Ingredients
Mussel Oil and Powder Market
Ingredients
Interesterified CBE Market
Ingredients
Boysenberry Extract Market
Ingredients
Cocoa Based Polyphenols Market
Ingredients
Psyllium Husk Powder Market
Ingredients
Cocoa Bean Extract Market
Ingredients
Gluten-Free Flour Market
Ingredients
Egg Replacement Ingredients Market
Ingredients
Caramel Ingredient Market
Ingredients
North America Cocoa Products Market
Ingredients
Lipids Market
Ingredients
Rice Starch Market
Ingredients
Global Whey Protein Ingredients Market
Ingredients
Middle East Feed Palatability Enhancers Market
Ingredients
PDO/PGI-Linked Mediterranean Ingredient Collections Market