
 Boysenberry Extract Market | 2026-2036
Boysenberry Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Boysenberry Extract Market Analytics
Market Context
Specialized agronomic expertise in Rubus hybrid cultivation is collapsing across traditional growing regions, constraining raw material throughput for processors. Kerry Group leverages its integrated flavor systems portfolio to secure long-term berry extract supply contracts. Givaudan SA anchors its botanical extraction network through direct farmer partnerships in premium growing zones. Symrise AG competes on proprietary gentle-processing technologies that preserve volatile aromatic compounds.
Technical Definition and Segment Structure
Boysenberry extract is a concentrated derivative obtained from the Rubus ursinus × idaeus hybrid, typically standardized to anthocyanin content between 1% and 25% and processed through cold-press maceration or supercritical CO2 extraction for flavor and colorant applications. Liquid extract dominates volume throughput due to its ease of incorporation into beverage matrices, while powder extract commands margin premiums from dietary supplement manufacturers seeking shelf-stable formats. Food and Beverage end users sustain the largest demand share, though Cosmetics applications are displacing synthetic colorants as formulators reformulate toward plant-derived alternatives.
Regulatory Framework
FDA GRAS self-affirmation pathways govern boysenberry extract deployment in US food applications, while EFSA novel food assessments shape market access timelines for European entrants. USDA organic certification and EU Organic Regulation 2018/848 determine price-tier eligibility for premium distribution channels. Stakeholders must monitor evolving EU Green Deal agricultural sustainability criteria that will reshape berry sourcing compliance burdens.
Market Dynamics
Clean-label regulatory pressure from the EU Green Deal is forcing extract processors to reconfigure berry sourcing networks around certified organic supply chains. This structural pivot favors operators with backward integration into controlled cultivation zones.
Growth Catalysts
- EU Organic Regulation 2018/848:Premium channel eligibility now requires full traceability from field to extract, accelerating investment in certified cultivation partnerships across New Zealand and Tasmania.
- Supercritical CO2 extraction:This gentle-processing technology preserves volatile aromatic compounds that solvent-based methods destroy, enabling flavor-house customers to command higher formulation fees.
- Cosmetics colorant demand:Formulators in France and Germany are replacing synthetic azo dyes with anthocyanin-rich boysenberry extracts to meet clean-beauty certification standards.
Market Restraints
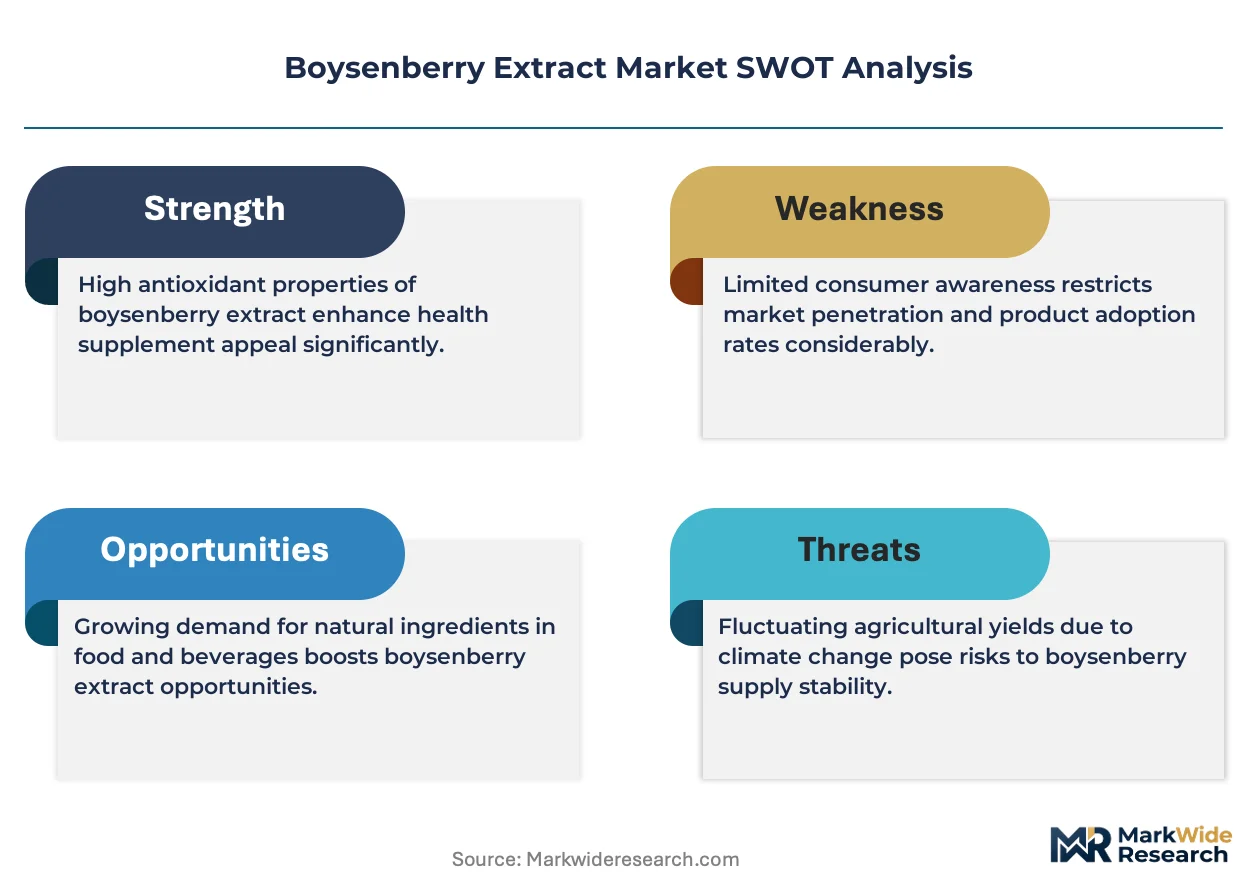
- Input cost volatility:Fresh boysenberry prices swing with frost damage in New Zealand's Nelson-Tasman growing cluster, compressing processor margins during poor harvest years.
- Supply concentration risk:Over 70% of commercial boysenberry cultivation sits within 200 kilometers of Motueka, creating single-point-of-failure exposure for global extract supply.
- Regulatory friction:EFSA novel food assessments impose 18-24 month market access timelines for new extract formats, delaying European revenue recognition for innovative suppliers.
Strategic Opportunities
- Underpenetrated geography:Australian processors can leverage Tasmania's emerging organic berry sector to establish counter-seasonal supply, reducing dependence on New Zealand harvest windows.
- Regulatory tailwind:The EU Green Deal's agricultural sustainability criteria will reward extractors with verified carbon-negative cultivation, creating first-mover certification advantages.
- Technology convergence:Combining supercritical CO2 extraction with nanofiltration concentration is enabling 40% higher anthocyanin yields per ton of raw fruit.
Industry Challenges
- Skill scarcity in Rubus hybrid agronomy:Specialized breeding expertise for boysenberry cultivar improvement is retiring across traditional growing regions without knowledge transfer programs.
- Capex intensity for organic certification:Converting conventional berry farms to EU Organic Regulation compliance requires three-year transition investments with no premium pricing during the conversion period.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boysenberry Extract Market |
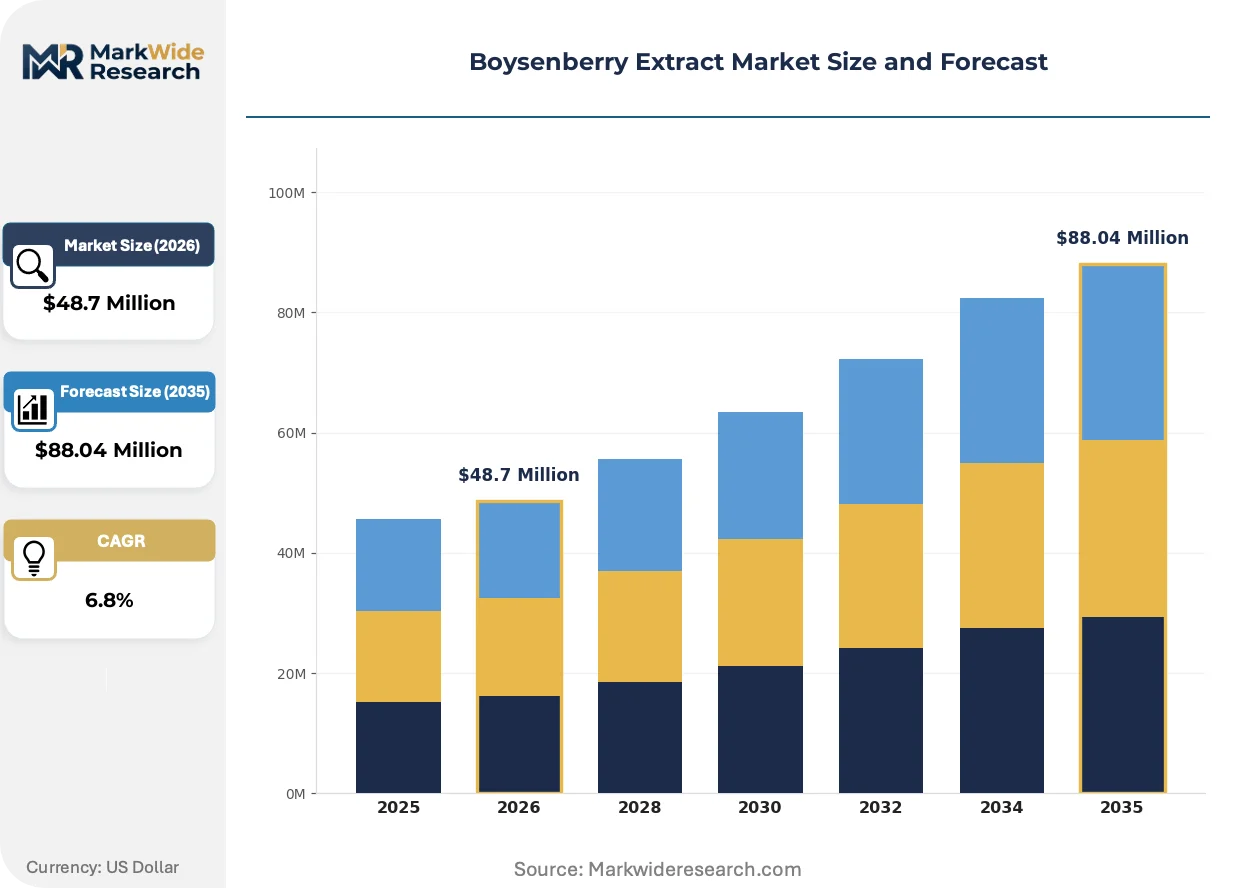
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
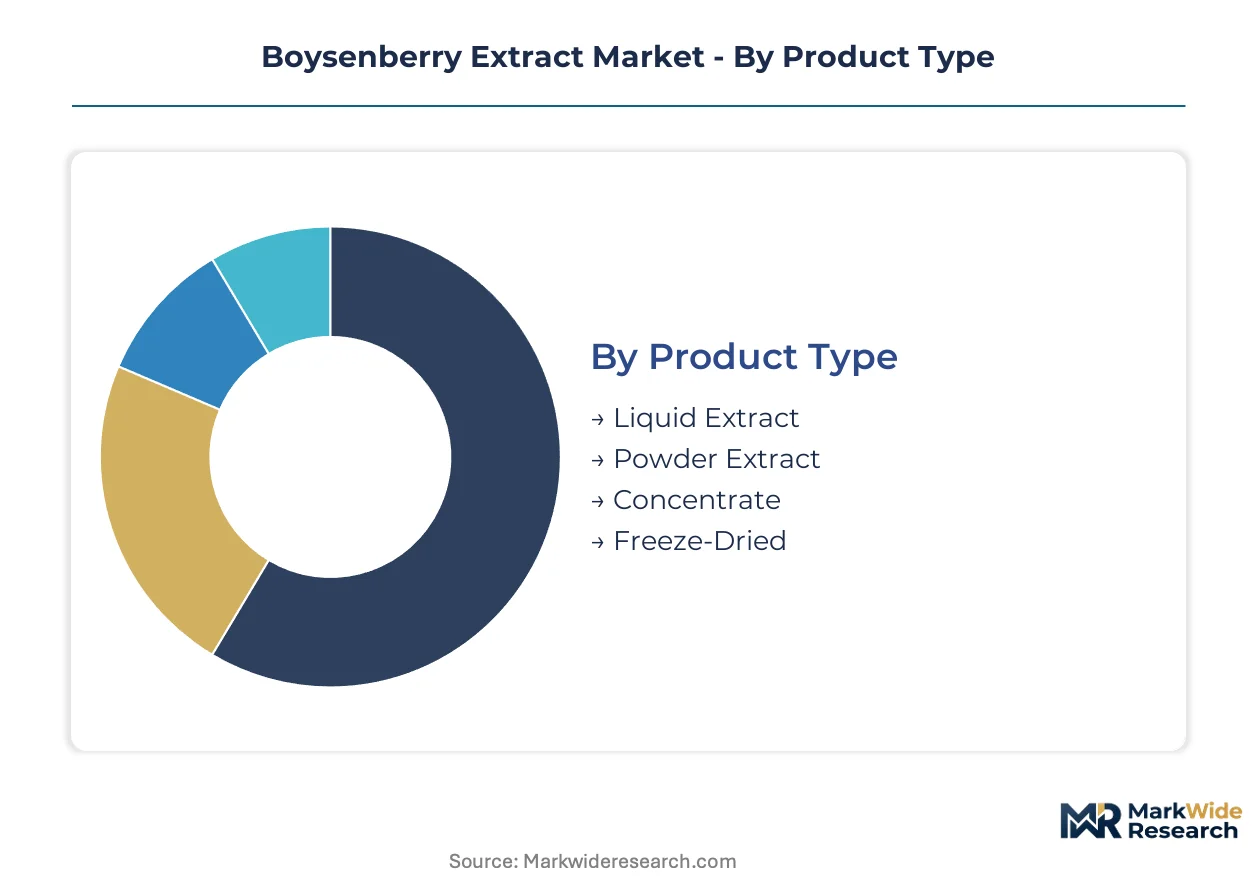
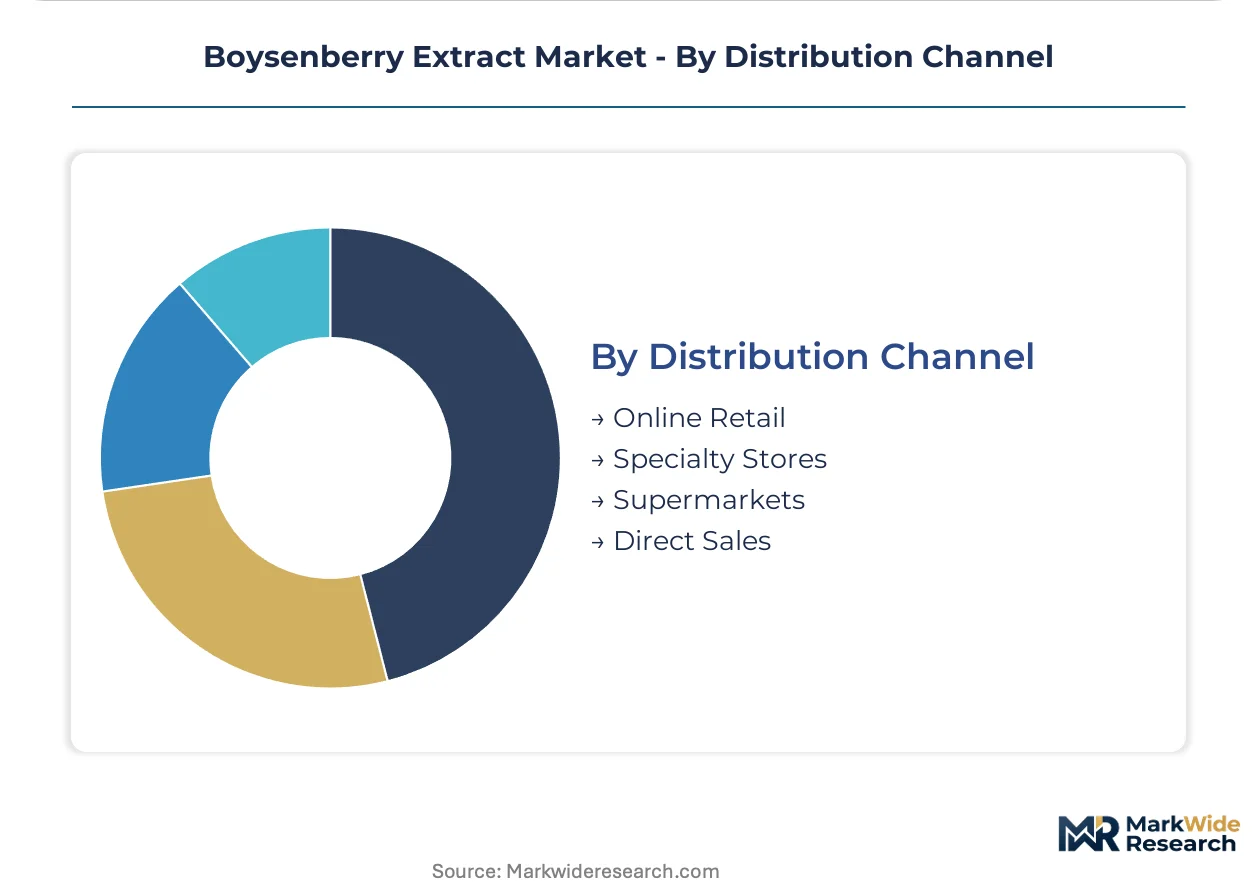
| Segmentation | Product Type: Liquid Extract, Powder Extract, Concentrate, Freeze-Dried End User: Food & Beverage, Dietary Supplements, Cosmetics, Pharmaceuticals Form: Organic, Conventional, Non-GMO, Gluten-Free Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Kerry Group, Givaudan SA, Symrise AG, McCormick & Company, Inc., Naturex, Kerr Concentrates, Inc., Amoretti, Flavor Producers, Vege Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boysenberry Extract Market Evolving Landscape
Processing technology diversification is fragmenting the competitive landscape between solvent-free extraction pioneers and incumbent maceration operators. This technological bifurcation is reshaping procurement relationships across flavor, colorant, and nutraceutical channels.
Supercritical CO2 extraction is fragmenting the incumbent solvent-based processing infrastructure. Flavor houses in Switzerland and Germany are adopting this technology to secure volatile compound profiles that meet clean-label briefs. The capital barrier is compressing market share among smaller maceration-only processors who cannot fund equipment upgrades.
EU Green Deal agricultural sustainability criteria are tightening berry sourcing compliance burdens for extractors serving European food and cosmetic manufacturers. Processors must now document carbon footprint per kilogram of extract and water stewardship practices at farm level. Premium distribution channels in France and Germany are responding by demanding third-party verified sustainability credentials as table stakes for contract renewal.
Direct-to-manufacturer sourcing contracts are displacing traditional broker-mediated berry procurement. Large flavor and fragrance houses are establishing exclusive cultivation partnerships in New Zealand's Motueka district, bypassing regional traders. This channel compression is most visible among Givaudan SA and Symrise AG, who are securing multi-year supply agreements with locked-in organic volume commitments.
Boysenberry Extract Market Segmentation
Boysenberry extract procurement patterns diverge sharply across product formats and end-use applications. New Zealand processors dominate export-oriented segments while domestic consumption concentrates in liquid formats for beverage manufacturing.
Product Type:
Liquid extract and powder extract command divergent geographic demand patterns, with liquid formats saturating Australasian beverage plants and powder extracts shipping to European nutraceutical compounders.
- Liquid Extract:Standardized to anthocyanin content between 1% and 25% through cold-press maceration, this format integrates seamlessly into beverage matrices without reconstitution. Demand concentrates in New Zealand's domestic food manufacturing sector, where Kerry Group maintains long-term supply contracts for flavor system integration.
- Powder Extract:Shelf-stable and high-concentration, this segment serves dietary supplement manufacturers seeking precise dosing control. European procurement through EFSA-compliant channels is accelerating as clean-label reformulation displaces synthetic additives in Germany and France.
- Concentrate:Reduced-volume format optimized for industrial-scale colorant applications in cosmetics manufacturing.
- Freeze-Dried:Premium preservation method retaining volatile aromatic compounds for high-end flavor house formulations.
Liquid extract holds the largest share; momentum sits with powder extract as European nutraceutical procurement expands.
End User:
Application-driven margin structures separate commodity food-grade procurement from premium cosmetic and pharmaceutical specifications.
- Food & Beverage:Volume anchor for the extract industry, spanning natural flavoring and colorant applications in juices, yogurts, and confectionery. FDA GRAS self-affirmation pathways govern US deployment, while EU Organic Regulation 2018/848 compliance determines European market access.
- Dietary Supplements:Anthocyanin-standardized extracts targeting antioxidant positioning in capsule and tablet formats. New Zealand export volumes to North American supplement brands are climbing as clean-label positioning hardens.
- Cosmetics:Anthocyanin-rich extracts replacing synthetic azo dyes in French and German clean-beauty formulations. EFSA novel food assessment timelines create 18-24 month lag for new supplier entry.
- Pharmaceuticals:Highest purity tier requiring documented traceability from field to extract for API-adjacent applications.
Food & Beverage commands volume leadership; Cosmetics is expanding most quickly as synthetic colorant bans tighten.
Form:
Certification tiering creates price stratification across premium organic, mid-tier non-GMO, and economy conventional grades.
- Organic:Full EU Organic Regulation 2018/848 traceability from cultivation through extraction. Three-year farm conversion investments with no premium pricing during transition periods constrain supply expansion.
- Conventional:Established cultivation without certification overhead, serving price-sensitive industrial food applications.
- Non-GMO:Identity-preserved supply chains documenting absence of genetic modification for US and European label claims.
- Gluten-Free:Processing protocol certification preventing cross-contamination for celiac-safe positioning in dietary supplements.
Conventional forms dominate current throughput; organic certification is climbing fastest as EU Green Deal procurement mandates harden.
Distribution Channel:
Channel compression is displacing traditional broker mediation as flavor houses pursue direct farmer partnerships.
- Online Retail:Emerging route for small-batch specialty extracts targeting artisan food producers and independent cosmetics formulators.
- Specialty Stores:Regional ingredient distributors serving mid-tier food manufacturers without direct procurement capabilities.
- Supermarkets:Limited to consumer-facing berry products; extract-grade volumes bypass this channel entirely.
- Direct Sales:Multi-year supply agreements with locked-in organic volume commitments characterize Givaudan SA and Symrise AG procurement in New Zealand's Motueka district.
Direct Sales captures the largest contract value; online retail is gaining share fastest among emerging specialty extractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA novel food assessments govern European market access timelines, while USDA organic certification anchors North American premium channel eligibility. The report examines five countries where extract procurement networks concentrate.
New Zealand
Motueka district cultivation clusters supply over 70% of commercial boysenberry raw material. MPI food safety standards regulate extract export certification. Nelson-Tasman growing regions face frost damage volatility that compresses processor margins during poor harvest years.
United States
North American dietary supplement brands drive anthocyanin-standardized powder extract procurement. FDA GRAS self-affirmation pathways govern food application deployment. California and Oregon processors serve clean-label beverage reformulation demand from West Coast manufacturing plants.
Germany
French and German cosmetics formulators replace synthetic azo dyes with anthocyanin-rich extracts. EU Organic Regulation 2018/848 compliance determines premium distribution channel access. Hamburg and Frankfurt ingredient distributors mediate contract volumes for mid-tier food manufacturers.
Australia
Tasmania's emerging organic berry sector offers counter-seasonal supply diversification. TGA therapeutic goods guidelines shape pharmaceutical-grade extract specifications. Victorian processors experiment with nanofiltration concentration technologies to boost anthocyanin yields.
Switzerland
Flavor houses in Geneva and Zurich adopt supercritical CO2 extraction for volatile compound preservation. Swissmedic food supplement regulations impose purity documentation requirements. Basel-area botanical extractors secure multi-year supply agreements with locked-in organic volume commitments.
Boysenberry Extract Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the boysenberry extract market. The vendor base separates into flavor-system integrators, gentle-processing specialists, and regional commodity processors. Three strategic archetypes dominate: integrated flavor houses with captive supply agreements, proprietary technology operators preserving volatile compounds, and price-competitive maceration-focused suppliers. Competitive moves concentrate on backward integration into certified cultivation zones and equipment upgrades for solvent-free extraction capacity.
Among integrated flavor houses, Kerry Group, Givaudan SA, and Symrise AG occupy positions exemplifying the direct-to-farmer procurement archetype. These Ireland-based and Swiss-registered entities represent the contract-locked supply tier, anchoring multi-year agreements in New Zealand's Motueka district. Their market presence reflects the channel compression pattern displacing traditional broker mediation across premium extract segments.
| Leading Market Players |
|---|
| Kerry Group |
| Givaudan SA |
| Symrise AG |
| McCormick & Company, Inc. |
| Naturex |
| Kerr Concentrates, Inc. |
| Amoretti |
| Flavor Producers |
| Vege Tech |
| Others |
Value Network & Pricing Analysis
EU Organic Regulation 2018/848 gates both supply qualification and price differentiation simultaneously, requiring full traceability from field to extract for premium channel eligibility while imposing three-year farm conversion investments that create entry barriers and sustain organic price premiums over conventional grades.
Pricing Analysis
New Zealand-origin liquid extracts command 15-25% premiums over Tasmanian supply due to Motueka district brand recognition among flavor houses. Three-tier pricing structure across organic, non-GMO, and conventional certification levels segments buyer budgets, with dietary supplement manufacturers showing least price sensitivity for anthocyanin-standardized powder formats. Cost compression in conventional grades is intensifying because frost damage volatility in Nelson-Tasman growing regions compresses processor margins during poor harvest years.
Supply Chain Analysis
New Zealand anchors global boysenberry raw material production, with Tasmania emerging as a counter-seasonal diversification source and Oregon serving North American clean-label beverage demand. The extract supply chain draws from fresh berry inputs, supercritical CO2 extraction equipment, and organic certification audit services. Single-source vulnerability concentrates in the Motueka district cluster where over 70% of commercial cultivation sits within 200 kilometers. Distribution runs through direct-to-manufacturer contracts displacing traditional broker mediation, with Givaudan SA and Symrise AG securing multi-year supply agreements with locked-in organic volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward integrated flavor houses as channel compression consolidates procurement leverage among Kerry Group, Givaudan SA, and Symrise AG, fragmenting negotiating position for smaller maceration-only processors.
For Market Incumbents: Consolidate backward integration into certified organic cultivation zones in New Zealand's Motueka district to defend against Tasmanian counter-seasonal supply entrants. Lock multi-year contracts with locked-in organic volume commitments before EU Green Deal sustainability criteria harden compliance burdens. Prioritize supercritical CO2 extraction equipment upgrades to preserve volatile aromatic compound profiles that solvent-based methods destroy. For New Entrants and Emerging Players: Differentiate on proprietary nanofiltration concentration technology enabling higher anthocyanin yields per ton of raw fruit. Target Australian Tasmania's emerging organic berry sector as the most penetrable geography, establishing counter-seasonal supply to reduce dependence on New Zealand harvest windows. Pursue direct farmer partnerships bypassing regional traders to secure raw material access. For Investors and Strategic Acquirers: EU Green Deal agricultural sustainability criteria reshape the acquisition landscape toward extractors with verified carbon-negative cultivation and documented water stewardship practices. Position for 5-10 year viability by targeting mid-tier processors with solvent-free extraction capacity and existing organic certification infrastructure. Watch EFSA novel food assessment timeline compression as the inflection signal indicating regulatory streamlining for innovative extract formats.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cultivation | Secures Motueka district supply against Tasmanian counter-seasonal competition and EU Green Deal compliance requirements. |
| Supercritical CO2 Extraction Capacity Addition | Preserves volatile aromatic compounds that Kerry Group and Givaudan SA demand for clean-label flavor system formulations. |
| Long-term Supply Agreement with Locked Volume | Locks in organic berry commitments before three-year farm conversion investments constrain certified supply expansion. |
| Nanofiltration Concentration Technology Licensing | Enables 40% higher anthocyanin yields per ton, differentiating powder extract offerings for European nutraceutical compounders. |
| Sustainability Certification Program | Documents carbon footprint per kilogram of extract for French and German clean-beauty procurement mandates. |
Research Methodology
Cross-validation between primary interviews with berry processors, flavor house procurement directors, and organic certification auditors anchors the qualitative findings, supplemented by secondary validation from MPI food safety export certifications, USDA organic handler databases, and EU Organic Regulation 2018/848 compliance registries. Bottom-up triangulation against top-down trade flow analysis from New Zealand export statistics and Tasmanian agricultural production surveys ensures consistency across estimation approaches.
Sensitivity analysis tests forecast robustness across alternative scenarios for frost damage frequency in Nelson-Tasman growing regions and EFSA novel food assessment timeline variations. The analytical framework segments by product format (liquid, powder, concentrate, freeze-dried), end-use application (food and beverage, dietary supplements, cosmetics, pharmaceuticals), and certification tier (organic, conventional, non-GMO, gluten-free) across the projection horizon. CAGRs derive from weighted average growth assumptions incorporating supercritical CO2 extraction adoption curves and EU Green Deal procurement mandate implementation rates.
Decision-makers should treat outputs as directional under base assumptions of stable organic certification farm conversion rates and sustained clean-label regulatory pressure from EU Green Deal criteria; material deviation in frost damage severity or EFSA streamlining would warrant model refresh. Recalibration cycles align with material shifts in EU Organic Regulation enforcement patterns and supercritical CO2 equipment cost trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
GCC Egg Powder Market
Ingredients
Centella Asiatica Extract Market
Ingredients
Glucose (Dextrose) Market
Ingredients
Industrial Sugar Market
Ingredients
Hydrogenated Palm Oil Market
Ingredients
Cocoa Fiber Market
Ingredients
Clean Label Starch Market
Ingredients
Bran Market
Ingredients
Immunity Support Ingredients Market
Ingredients
Canola Protein Market
Ingredients
Mirepoix Market
Ingredients
North America Gelatin Market
Ingredients
EPA and DHA Omega-3 Ingredient Market
Ingredients
Demineralized Whey Powder Ingredient Market
Ingredients
Bovine Gelatin Market
Ingredients
Honey Powder Market