
 United States Food Colorants Market | 2026-2036
United States Food Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
United States Food Colorants Market Analytics
The FDA's color additive certification mandate is broadening compliance burdens across the supply chain. Sensient Technologies Corporation leverages its vertical integration to sustain domestic manufacturing scale for certified dyes and lakes. Archer Daniels Midland Company anchors its position through extensive agricultural sourcing networks for natural colorant feedstocks. BASF SE competes on technology leadership in stable micronized pigment formulations for beverage applications.
Food colorants comprise dyes, pigments, lakes, and preparations that impart, preserve, or enhance color in edible products, typically specified by hue strength, pH stability, and lightfastness ratings for thermal processing conditions. Their primary commercial purpose spans visual differentiation, flavor expectation signaling, and shelf-life appearance retention across packaged goods. Natural Colors command premium positioning as clean-label formulations displace synthetic alternatives in dairy and beverage applications. Synthetic Dyes retain volume dominance in confectionery where vivid hue intensity and cost efficiency outweigh label concerns. Lakes dominate bakery applications requiring fat-dispersible pigments resistant to moisture migration.
FDA color additive regulations, USDA organic certification standards, and state-level California Proposition 65 enforcement collectively determine permissible colorant categories, labeling disclosures, and market access thresholds for domestic suppliers. The FDA's batch certification program for synthetic dyes creates structural barriers to entry that concentrate qualified supply among established manufacturers. Stakeholders must monitor evolving state-level additive restrictions and FDA petition backlogs for novel natural color sources to anticipate qualification timelines and reformulation requirements.
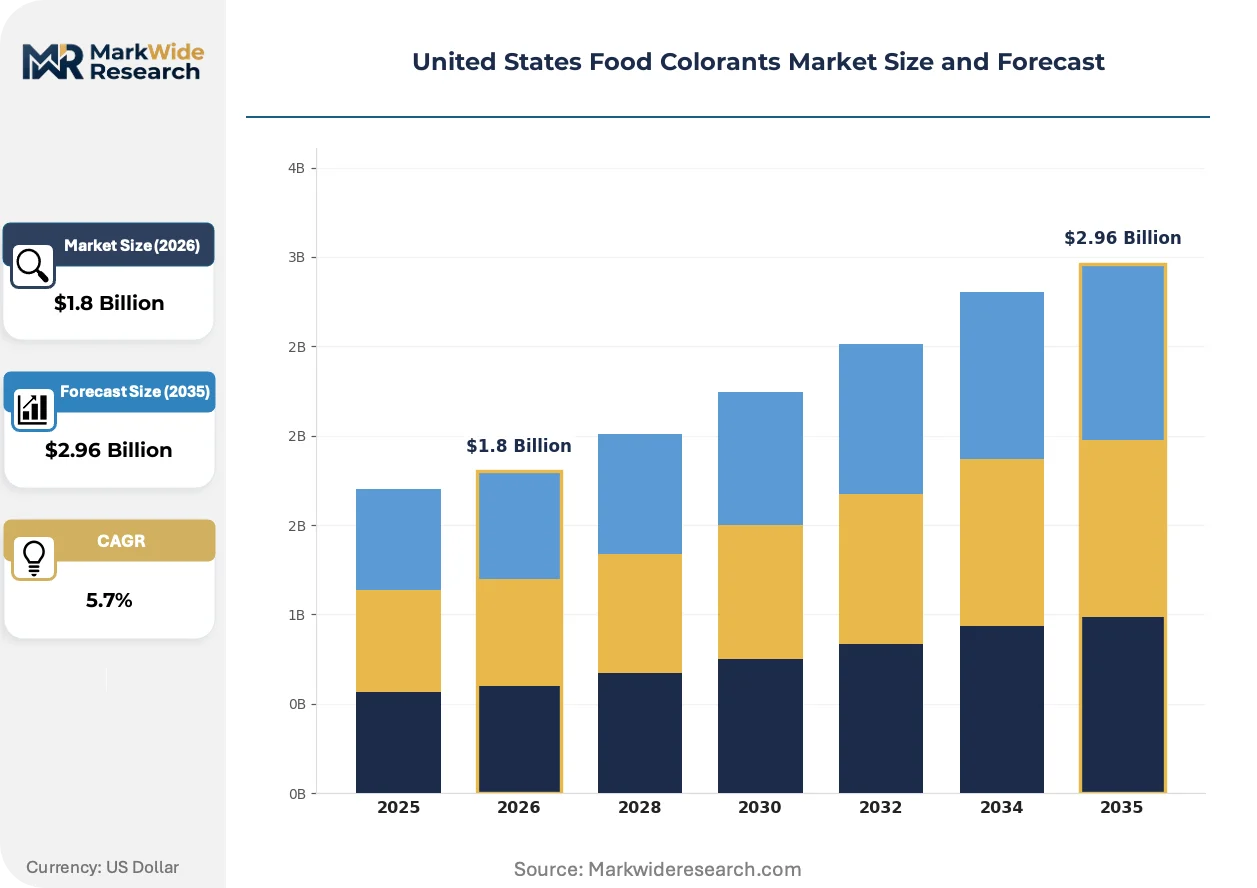
Market Dynamics
The FDA's batch certification mandate for synthetic color additives is compressing qualified supplier pools while beverage manufacturers accelerate reformulation toward anthocyanin and carotenoid alternatives. This regulatory friction is redrawing procurement relationships between certified dye manufacturers and clean-label formulators.
Growth Catalysts
- California Proposition 65 enforcement:Warning label requirements for synthetic additives are pushing confectionery and dairy processors toward exempt natural colorant categories. Reformulation investments in Los Angeles and San Francisco metro corridors are accelerating.
- Plant-based beverage innovation:Oat milk and almond milk producers require stable natural pigments that withstand ultra-high temperature processing. Anthocyanin blends with enhanced pH stability are capturing specification slots previously held by certified dyes.
- Clean-label retail commitments:Major grocery chains have established synthetic colorant elimination timelines for private label products. This is concentrating procurement volume with domestic natural colorant extractors.
Market Restraints
- Anthocyanin raw material volatility:Grape and berry concentrate prices fluctuate with California Central Valley harvest yields and irrigation water allocations. Input cost instability compresses margin predictability for natural colorant suppliers.
- FDA certification backlog concentration:Novel natural color source petitions face multi-year review timelines. The structural delay limits supplier diversification and entrenches incumbent certified dye manufacturers.
- Lake pigment technical constraints:Fat-dispersible aluminum salt complexes fail in high-moisture bakery applications. This technical ceiling prevents lake expansion into aqueous processing segments.
Strategic Opportunities
- Texas and Florida processed food corridors:Underpenetrated regional production clusters offer natural colorant suppliers proximity to expanding snack and ready-meal manufacturing capacity.
- Biotechnology-derived pigments:Precision fermentation platforms producing carotenoids and betalains without agricultural feedstock dependence represent white-space technology convergence.
- Direct-to-manufacturer digital procurement:Specialty ingredient marketplaces are disintermediating traditional distributor relationships for mid-volume bakery and confectionery accounts.
Industry Challenges
- FDA color additive petition expertise scarcity:Qualified toxicologists and regulatory affairs specialists capable of navigating GRAS self-determination and color additive petition pathways command premium compensation.
- Legacy synthetic dye inventory reconciliation:Manufacturers maintaining dual natural-synthetic product lines face working capital strain from extended reformulation transitions and obsolete stock write-downs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Food Colorants Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Colors, Synthetic Dyes, Lakes, Color Additives Application: Beverages, Dairy Products, Bakery, Confectionery Form: Liquid, Powder, Paste, Gel End User: Food Manufacturers, Beverage Producers, Restaurants, Retailers |
| Companies Covered | Sensient Technologies Corporation, Archer Daniels Midland Company, BASF SE, Givaudan S.A., International Flavors & Fragrances Inc., Oterra A/S, GNT Group, Döhler GmbH, Chr. Hansen Holding A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Food Colorants Market Evolving Landscape
Microencapsulation technology is reshaping natural colorant stability profiles while regulatory pressure on synthetic categories intensifies specification requirements. These forces are compressing the viable solution set for thermal-processed applications.
Microencapsulated anthocyanin systems using modified starch and gum arabic wall materials are consolidating supplier positions in beverage applications previously lost to synthetic alternatives. Sports drink and enhanced water manufacturers are adopting these systems at accelerated specification cycles. The technology is consolidating procurement volume among suppliers with in-house encapsulation capabilities.
FDA enforcement discretion letters and batch certification fee structures are tightening market access for imported synthetic dye lots. Domestic manufacturers with established FDA laboratory relationships face reduced qualification friction. Beverage concentrate producers are responding by diversifying toward exempt natural colorant categories with simpler compliance pathways.
Buyer specification committees at major retail chains are compressing supplier approval timelines while demanding extended stability documentation. Direct supplier-manufacturer technical partnerships are displacing traditional distributor-mediated relationships for complex natural colorant formulations. This pattern is most visible in California's plant-based dairy processing cluster.
United States Food Colorants Market Segmentation
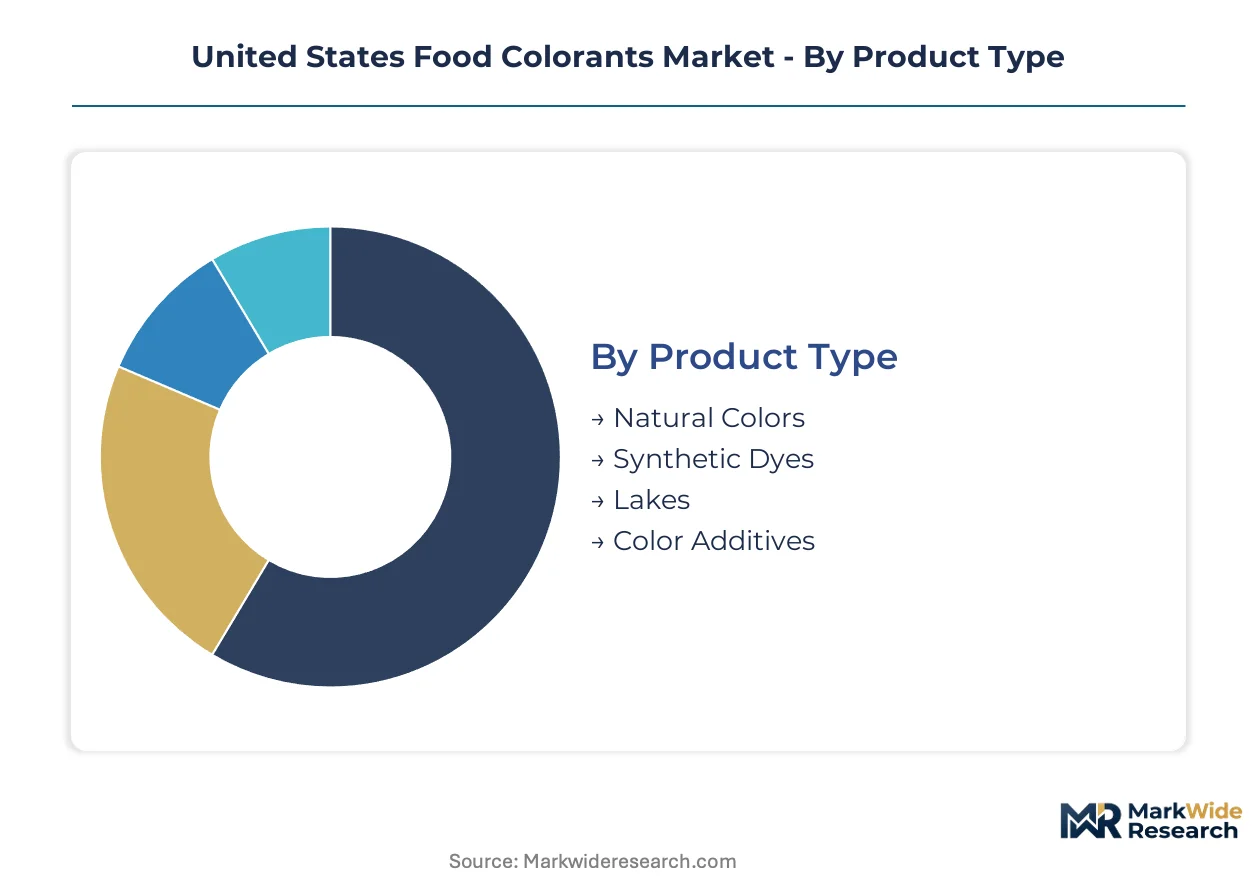
Segmentation in the United States food colorants market reveals how regulatory burden, application requirements, and supply chain configuration concentrate value across distinct product and customer categories. Procurement patterns diverge sharply between FDA-certified synthetic categories and exempt natural alternatives.
Product Type:
FDA batch certification requirements create asymmetric compliance costs across product categories, with synthetic dyes demanding laboratory validation while natural colorants navigate GRAS self-determination pathways.
- Natural Colors:Anthocyanins, carotenoids, and betalains extracted from agricultural feedstocks command premium positioning in California's plant-based dairy corridor. Reformulation timelines at major beverage producers are compressing specification windows for pH-stable natural systems.
- Synthetic Dyes:FD&C certified dyes and lakes require per-batch FDA laboratory certification, creating structural barriers that concentrate qualified supply among domestic manufacturers with established regulatory relationships. Confectionery applications in Chicago and Philadelphia metro areas sustain volume demand despite clean-label pressure.
- Lakes:Fat-dispersible aluminum salt complexes dominate bakery applications requiring moisture resistance.
- Color Additives:Blended preparations and custom formulations serve co-manufacturers seeking simplified procurement.
Leading the category by volume: Synthetic Dyes. Growing fastest: Natural Colors.
Application:
End-use thermal processing requirements dictate stability specifications and supplier technical support intensity across manufacturing segments.
- Beverages:Ultra-high temperature processing and acidic pH conditions demand microencapsulated anthocyanin systems with enhanced lightfastness. Sports drink manufacturers in Florida and Texas are driving specification adoption for modified starch wall materials.
- Dairy Products:Yogurt and plant-based milk alternatives require heat-stable natural pigments that survive homogenization and pasteurization. California's Central Valley processing cluster concentrates procurement volume for carotenoid blends.
- Bakery:Fat-dispersible lakes retain color through high-moisture dough systems and extended shelf-life distribution.
- Confectionery:Vivid hue intensity and cost efficiency sustain synthetic dye specification despite Proposition 65 warning label exposure in California.
Highest margin concentration: Dairy Products. Steepest expansion trajectory: Beverages.
Form:
Physical state determines handling infrastructure, dosing precision, and compatibility with automated manufacturing lines across customer facilities.
- Liquid:Pump-dispersed concentrates dominate high-volume beverage manufacturing with continuous processing lines. Midwest dairy processors favor liquid carotenoid emulsions for direct-injection color standardization.
- Powder:Dry blends serve bakery and confectionery dry mix applications with extended ambient stability and reduced shipping costs.
- Paste:High-solids formats concentrate pigment load for reduced inventory holding at mid-volume manufacturers.
- Gel:Viscous systems enable precise deposition in decorative and artisanal applications.
Dominant by procurement volume: Liquid. Gaining specification share fastest: Powder.
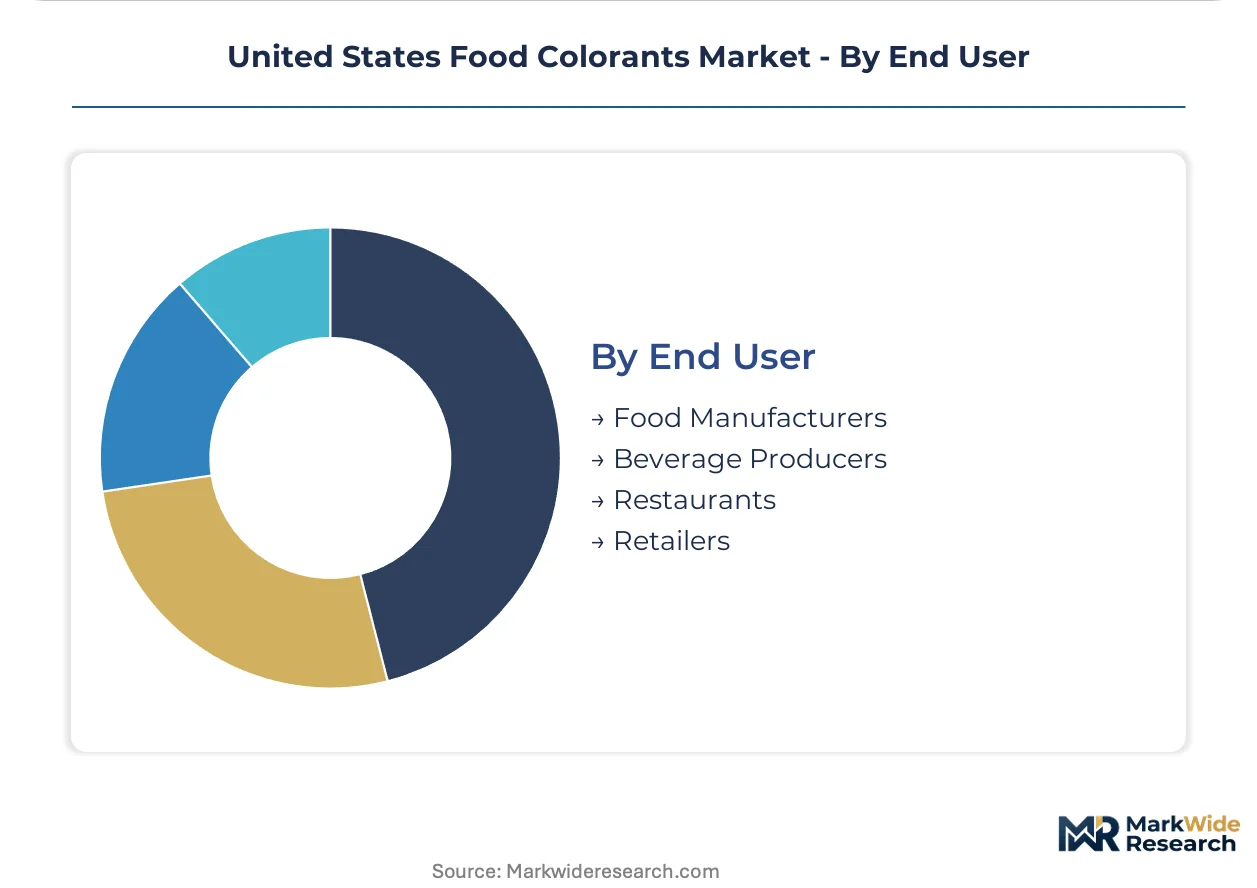
End User:
Customer scale and technical capability determine whether procurement flows through distributor relationships or direct supplier partnerships with embedded formulation support.
- Food Manufacturers:Large-scale processors in Ohio, Illinois, and California drive consolidated procurement through direct technical partnerships. Clean-label commitments at major CPG headquarters are restructuring supplier approval timelines.
- Beverage Producers:Plant-based innovation clusters in Los Angeles and San Francisco metro corridors concentrate demand for pH-stable natural colorants with simplified compliance pathways.
- Restaurants:Foodservice distributors mediate smaller-batch procurement for chain operators with limited in-house formulation resources.
- Retailers:Private label specification committees at grocery headquarters are eliminating synthetic colorant categories on accelerated timelines.
Controlling procurement volume: Food Manufacturers. Expanding most quickly: Beverage Producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Central Valley and Los Angeles-San Francisco corridor anchor domestic food colorant procurement, concentrating plant-based dairy innovation and beverage reformulation demand that reshapes national supply chain configuration.
California
Anthocyanin and carotenoid procurement concentrates in the Central Valley agricultural belt and Los Angeles metro processing clusters. FDA color additive certification requirements intersect with California Proposition 65 warning label mandates to accelerate synthetic dye displacement. Oakland and San Francisco plant-based beverage headquarters drive specification adoption for pH-stable natural pigments.
Texas
Sports drink manufacturing in the Dallas-Fort Worth corridor and Houston chemical processing infrastructure expand natural colorant demand for ultra-high temperature applications. State environmental regulations on industrial discharge affect extraction facility siting decisions. San Antonio and Austin foodservice distribution hubs mediate procurement for southwestern chain restaurant operators.
Illinois
Chicago metro confectionery production sustains certified synthetic dye volume despite clean-label pressure across other categories. USDA organic certification standards influence natural colorant sourcing for dairy processors in the broader Midwest supply radius. Rockford and Peoria distribution centers consolidate ingredient flows for bakery and snack manufacturers.
Florida
Orlando and Tampa beverage concentrate production drives specification demand for lightfast natural pigments in citrus-flavored applications. State agricultural extension programs support carotenoid crop trials for domestic feedstock security. Miami foodservice import channels mediate Latin American colorant sourcing for regional processors.
New York
Brooklyn and Queens artisanal food manufacturing clusters favor exempt natural colorant categories for clean-label positioning. State-level cosmetic and food additive disclosure requirements exceed federal baselines. Rochester and Buffalo dairy processing facilities anchor carotenoid emulsion procurement for fluid milk standardization.
United States Food Colorants Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification capability and formulation support intensity, creating a tiered structure where FDA laboratory relationships and encapsulation technology ownership separate price-realization levels. The vendor base concentrates among agricultural processors with captive extraction infrastructure and chemical manufacturers with dye synthesis heritage. Three archetypes dominate: vertically integrated natural extractors, certified synthetic dye specialists, and biotechnology-enabled pigment platforms. Competitive moves center on capacity expansion in Texas and Florida corridors and technology licensing for microencapsulation systems.
Within the certified synthetic tier, Sensient Technologies Corporation exemplifies domestic manufacturing scale sustained through FDA laboratory relationships. Archer Daniels Midland Company anchors agricultural sourcing networks for natural feedstock security. BASF SE occupies a position representing technology leadership in stable pigment formulations. These three entities illustrate how certification infrastructure, upstream agricultural control, and formulation science each anchor distinct competitive positions.
| Leading Market Players |
|---|
| Sensient Technologies Corporation |
| Archer Daniels Midland Company |
| BASF SE |
| Givaudan S.A. |
| International Flavors & Fragrances Inc. |
| Oterra A/S |
| GNT Group |
| Döhler GmbH |
| Chr. Hansen Holding A/S |
| Others |
Value Network & Pricing Analysis
Regulatory toxicologists and FDA petition specialists concentrated in the Washington DC metro corridor command compensation premiums that widen spreads between certified synthetic dye tiers and exempt natural colorant categories. This labor-cost differential compresses margins for novel natural colorant suppliers navigating multi-year GRAS self-determination pathways while reinforcing pricing power among established certified dye manufacturers with in-house regulatory affairs capabilities.
Pricing Analysis
Yield-guaranteed pricing for microencapsulated anthocyanin systems anchors value-based contracts in beverage applications, with cost-per-stable-liter metrics replacing traditional per-kilogram commodity structures. Price differentiation separates FDA-certified synthetic dyes from exempt natural categories, with certification grade and pH stability performance as tier drivers. Pricing pressure stems from California Proposition 65 compliance costs pushing confectionery accounts toward reformulation. Mid-volume bakery processors show highest price sensitivity due to thin margins on private label contracts, while plant-based dairy innovators in Los Angeles demonstrate lowest sensitivity for proven thermal-stable systems.
Supply Chain Analysis
Refurbishment flows for spent extraction solvents and aluminum salt recovery from lake pigment production create reverse logistics infrastructure concentrated in Illinois and Texas chemical processing corridors. Geographic supply concentration centers on California for grape and berry anthocyanin feedstocks, India for turmeric and annatto carotenoids, and China for paprika oleoresin and spirulina. Raw material dependencies include Central Valley irrigation water allocations, Indian monsoon patterns, and Chinese pigment processing capacity. Tariff exposure on imported natural colorant concentrates creates structural vulnerability for domestic formulators. Distribution runs through specialty ingredient distributors in Chicago and Los Angeles, with direct supplier relationships capturing share among large beverage manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States food colorants market sits in a technology-transition phase where microencapsulation systems displace unprotected natural pigments and certified synthetic dyes across thermal-processed applications. This displacement creates asymmetric opportunity windows for suppliers with in-house formulation science capabilities versus commodity extractors.
For Market Incumbents: Extend encapsulation technology licensing programs to mid-tier natural extractors lacking in-house R&D infrastructure, capturing royalty streams while defending against biotechnology-derived pigment platforms. Deepen backward integration into California Central Valley grape and berry contracting to secure anthocyanin feedstock priority amid irrigation water scarcity. FDA certification backlog concentration represents the critical threat to synthetic dye volume retention. For New Entrants and Emerging Players: Begin with precision fermentation platforms producing carotenoids without agricultural yield volatility, targeting the underpenetrated Texas and Florida sports drink manufacturing corridors where pH-stable natural demand outstrips qualified supply. Biotechnology-enabled pigment production offers the most penetrable white-space, with direct-to-manufacturer digital procurement as the go-to-market angle for mid-volume accounts bypassing traditional distributor markups. For Investors and Strategic Acquirers: The window for entry favors biotechnology platforms with fermentation-derived pigment pipelines and established GRAS self-determination pathways. Long-term viability hinges on regulatory affairs expertise scarcity creating durable moats around qualified suppliers. Watch FDA petition backlog clearance rates and California Proposition 65 enforcement expansion as inflection indicators for natural colorant category acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Captures value from beverage reformulation demand without capital-intensive capacity expansion. |
| Precision Fermentation Scale-Up | Eliminates agricultural feedstock dependence for carotenoid and betalain production. |
| California Central Valley Feedstock Contracting | Secures anthocyanin supply priority amid irrigation water allocation constraints. |
| Direct-to-Manufacturer Digital Platform | Disintermediates distributor relationships for mid-volume bakery and confectionery accounts. |
| FDA Regulatory Affairs Capability Acquisition | Accelerates novel natural colorant qualification timelines against petition backlog. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across formulation scientists at beverage manufacturers, procurement directors at CPG headquarters, regulatory affairs specialists at colorant suppliers, and technical sales managers at specialty ingredient distributors. FDA color additive petition databases, USDA organic certification registries, California Office of Environmental Health Hazard Assessment Proposition 65 filings, and USITC trade flow data provided validation benchmarks. Bottom-up segment modeling and top-down market reconciliation ensured cross-verification.
Data-stream reconciliation across product type, application, form, and end-user dimensions structured the analytical framework, with value outputs derived from pricing tier spreads and volume from procurement pattern analysis across the projection horizon. CAGRs emerged from segment-level growth rate blending weighted by base-year value contribution. Forecast inputs incorporated California Proposition 65 enforcement trajectory, FDA batch certification fee structures, and plant-based beverage innovation pipeline visibility.
Regulatory petition backlog duration, agricultural yield volatility, and biotechnology platform commercialization timing are the dominant revision risks to modeled outputs. Practitioners should monitor FDA enforcement discretion letters, Central Valley irrigation allocations, and precision fermentation scale-up announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Europe Food Flavor Market
Flavorings and Food Additives
Anthocyanin Food Colors Market
Flavorings and Food Additives
Food Colorants Market
Flavorings and Food Additives
1-Decanol Market
Flavorings and Food Additives
Flavor Drops Market
Flavorings and Food Additives
Tangerine Extract Market
Flavorings and Food Additives
Global Natural Food Colorants Market
Flavorings and Food Additives
Jujube Extracts Market
Flavorings and Food Additives
Royal Jelly Extract Market
Flavorings and Food Additives
France Food Flavor and Enhancer Market
Flavorings and Food Additives
Africa Food Flavor Market
Flavorings and Food Additives
Nature Identical Flavorings Market
Flavorings and Food Additives
Dry Powder Flavors Market
Flavorings and Food Additives
Caralluma Extract Market
Flavorings and Food Additives
Cocoa Extract Market
Flavorings and Food Additives
Savory Extract Market