
 Cheese Flavor Market | 2026-2036
Cheese Flavor Market Size, Share, and Industry Trends Forecast 2026-2036
Cheese Flavor Market Outlook
ISO 22000 certification is bifurcating the competitive landscape between qualified suppliers and commodity producers in the cheese flavor sector. FrieslandCampina leverages its cooperative dairy sourcing to secure consistent milk solids for enzymatic flavor development. Lactalis Ingredients anchors European supply through specialized fractionation capabilities that yield concentrated cheese essences. The Kraft Heinz Company sustains brand recognition across retail and foodservice channels with proprietary flavor formulations.
Cheese flavor encompasses concentrated dairy-derived extracts, enzyme-modified cheeses, and synthetic analogs formulated to deliver specific aromatic and taste profiles in finished foods. Manufacturers employ lipolysis and proteolysis to generate free fatty acids and peptides that replicate aged cheddar or parmesan sensory signatures. Sharp and blue flavor types command premium positioning due to extended aging requirements and concentrated intensity that reduces usage rates in snack applications. Creamy profiles dominate volume across sauces and dips where mouthfeel integration proves critical, while food manufacturers represent the deepest margin pool through long-term formulation partnerships.
FDA oversight of Generally Recognized As Safe determinations and EFSA flavoring substance evaluations constrain which molecules enter commercial formulations across major markets. The EU Green Deal pushes manufacturers toward enzymatic and fermentation-derived alternatives to synthetic cheese flavor compounds. Stakeholders must monitor evolving clean-label definitions and regional dairy quota structures that directly reshape raw material access and cost structures for flavor houses.
Market Dynamics
Enzymatic flavor development is compressing production cycles while EU Green Deal mandates accelerate synthetic compound phase-outs across European formulations.
Growth Catalysts
- Clean-label mandates:EU Green Deal and FDA modernization initiatives push manufacturers toward fermentation-derived alternatives, expanding natural flavor procurement pipelines.
- Extruded snack expansion:Snack food manufacturers integrate cheese flavoring into puffed product lines at accelerated rates, creating sustained volume demand.
- Enzyme engineering advances:Lipolysis and proteolysis refinements enable sharper cheddar and parmesan replications without extended aging infrastructure.
Market Restraints
- Milk solids volatility:Dairy commodity price swings directly compress margins for enzymatic flavor houses dependent on consistent protein and fat inputs.
- Regulatory fragmentation:Divergent FDA GRAS determinations and EFSA flavoring substance evaluations create formulation lock-in risks across export markets.
- Plant-based substitution:Nutritional yeast and fermented legume extracts displace dairy-derived flavors in vegan snack and sauce applications.
Strategic Opportunities
- Precision fermentation scale-up:Singapore and Netherlands biotech clusters offer regulatory sandboxes for novel dairy-identical protein flavor molecules.
- Convenience food premiumization:Ready-meal manufacturers seek concentrated cheese essences for clean-label positioning in refrigerated pasta and frozen pizza segments.
- Direct-to-manufacturer channels:Flavor houses bypass traditional distribution tiers through embedded R&D partnerships with multinational snack conglomerates.
Industry Challenges
- ISO 22000 certification backlog:Smaller flavor houses face 12-18 month compliance timelines to meet buyer qualification requirements.
- Legacy formulation integration:Reformulating established synthetic-based products for natural alternatives without sensory drift demands extensive consumer testing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cheese Flavor Market |
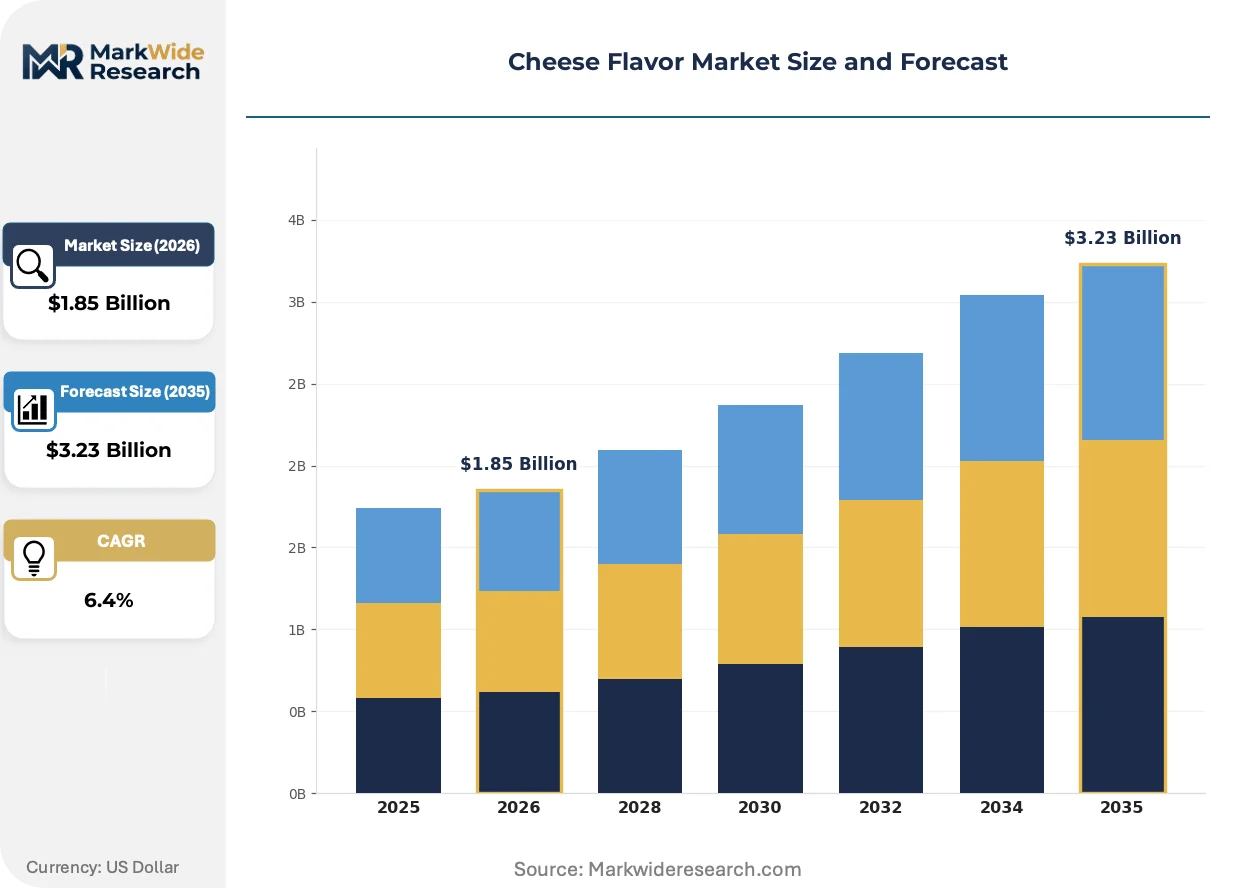
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Flavor Type: Sharp, Creamy, Mild, Blue Application: Snacks, Sauces, Dips, Spreads End User: Food Manufacturers, Restaurants, Retailers, Bakeries Packaging Type: Bottles, Bags, Tubs, Pouches |
| Companies Covered | FrieslandCampina, Lactalis Ingredients, The Kraft Heinz Company, Dairy Farmers of America, Inc., SAVENCIA SA, Fonterra Co-operative Group Limited, Saputo Inc., Groupe Bel, Arla Foods amba, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cheese Flavor Market Strategic Shifts
Bioprocessing advances and regulatory convergence are compressing development timelines while reshaping how flavor houses structure R&D partnerships and scale production.
Precision fermentation platforms are miniaturizing. These systems generate dairy-identical proteins and lipids through microbial hosts, eliminating traditional dairy supply dependencies. Snack manufacturers in the United States and Netherlands pilot these inputs for clean-label claims. The technology is miniaturizing capital requirements for flavor entry, enabling mid-scale biotech firms to challenge established dairy cooperatives.
EFSA flavoring substance evaluations are tightening. The regulator's systematic re-evaluation program removes synthetic molecules from approved lists, forcing reformulation cycles. European flavor houses accelerate enzymatic and fermentation-derived alternatives to maintain portfolio viability. Sauce and dip manufacturers face the steepest transition costs due to mouthfeel-critical creamy profiles.
Buyer concentration is intensifying. Multinational snack conglomerates consolidate supplier rosters to three qualified flavor houses per region, demanding dedicated formulation teams and volume guarantees. This compresses pricing leverage for mid-tier producers. The United States exhibits the most aggressive consolidation, with top four snack manufacturers controlling majority cheese flavor procurement decisions.
Cheese Flavor Market Segmentation
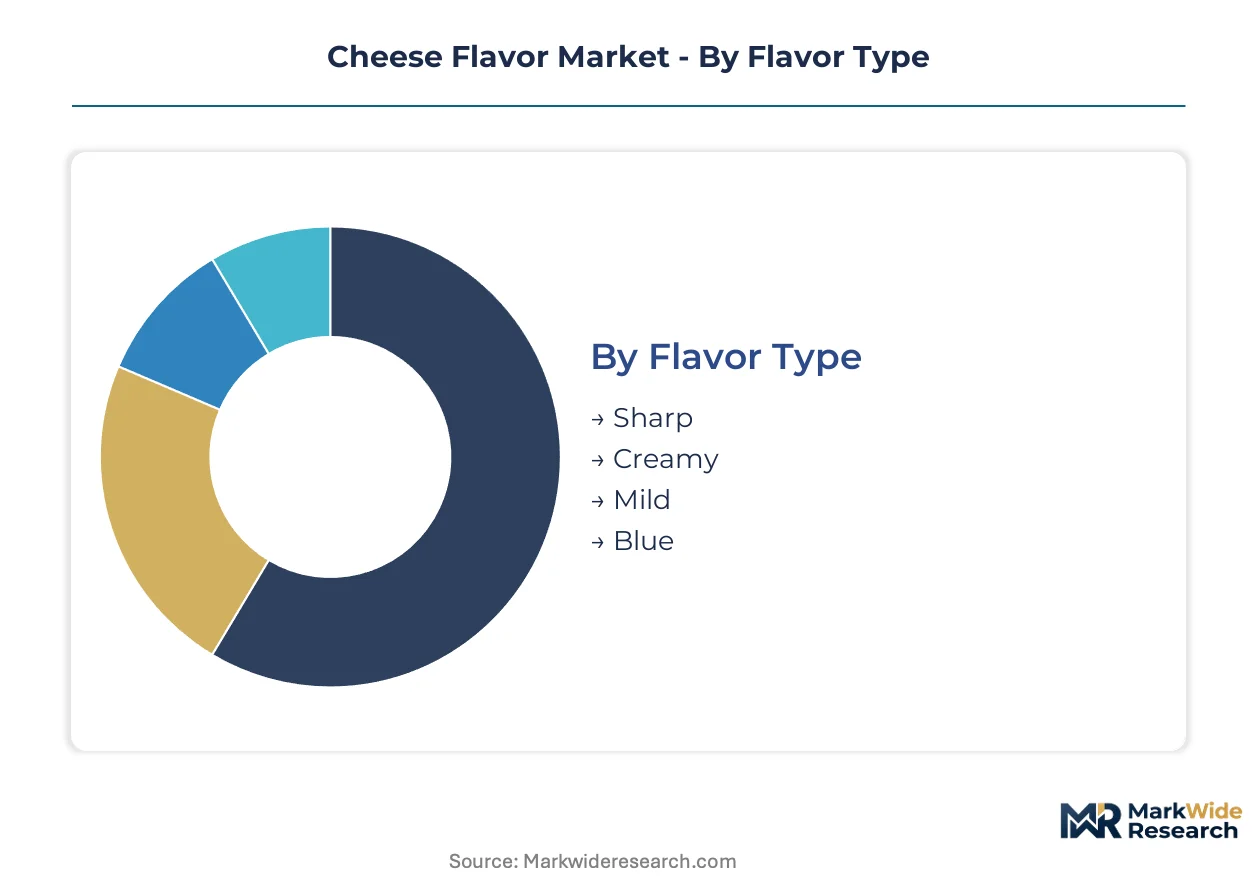
Cheese flavor segmentation reveals where substitution pressures and clean-label mandates reshape procurement priorities. Manufacturers prioritize segments offering formulation flexibility and regulatory compliance across diverse end-use applications.
Flavor Type:
Nutritional yeast and fermented legume extracts exert the strongest displacement threat on flavor profiles with the simplest aromatic signatures.
- Sharp:Extended aging requirements and concentrated intensity reduce usage rates in extruded snack applications. United States snack manufacturers favor sharp profiles for premium positioning in puffed product lines where intensity offsets commodity cost volatility.
- Creamy:Mouthfeel integration proves critical in sauce and dip formulations, creating formulation lock-in with established dairy-derived bases. Netherlands-based sauce manufacturers drive sustained procurement despite plant-based alternatives gaining traction in vegan segments.
- Mild:Neutral flavor carriers suit mass-market applications where cost minimization dominates specification sheets.
- Blue:Pungent mold-derived compounds require specialized handling protocols, limiting adoption to premium positioning strategies.
Sharp retains volume leadership; Creamy holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity bulk applications from premium formulation partnerships with dedicated R&D support.
- Snacks:Extruded and puffed product lines absorb the highest absolute volumes as manufacturers accelerate cheese flavor integration. United States snack conglomerates consolidate supplier rosters to three qualified flavor houses per region, demanding volume guarantees.
- Sauces:Refrigerated pasta and frozen pizza segments seek concentrated essences for clean-label positioning. EFSA systematic re-evaluation programs force reformulation cycles, compressing development timelines for European sauce manufacturers.
- Dips:Mouthfeel-critical formulations face steepest transition costs when shifting from synthetic to enzymatic alternatives.
- Spreads:Retail positioning demands drive premium flavor procurement in developed markets.
Snacks dominate absolute volume; Sauces climb the fastest on clean-label premiumization.
End User:
Customer type determines margin structure, with long-term formulation partnerships offering the deepest margin pools versus spot-market commodity transactions.
- Food Manufacturers:Embedded R&D partnerships with multinational snack conglomerates enable flavor houses to bypass traditional distribution tiers. ISO 22000 certification requirements bifurcate the competitive landscape between qualified suppliers and commodity producers.
- Restaurants:Foodservice channels sustain brand recognition through proprietary flavor formulations with consistent sensory profiles.
- Retailers:Private-label positioning drives cost-sensitive procurement with limited formulation customization.
- Bakeries:Niche applications concentrate in artisanal segments with low absolute volumes but premium pricing tolerance.
Food Manufacturers capture the deepest margin pool; Restaurants expand procurement most quickly on experience-driven menu differentiation.
Packaging Type:
Supply concentration in flexible format production shapes availability and lead time differentials across regional markets.
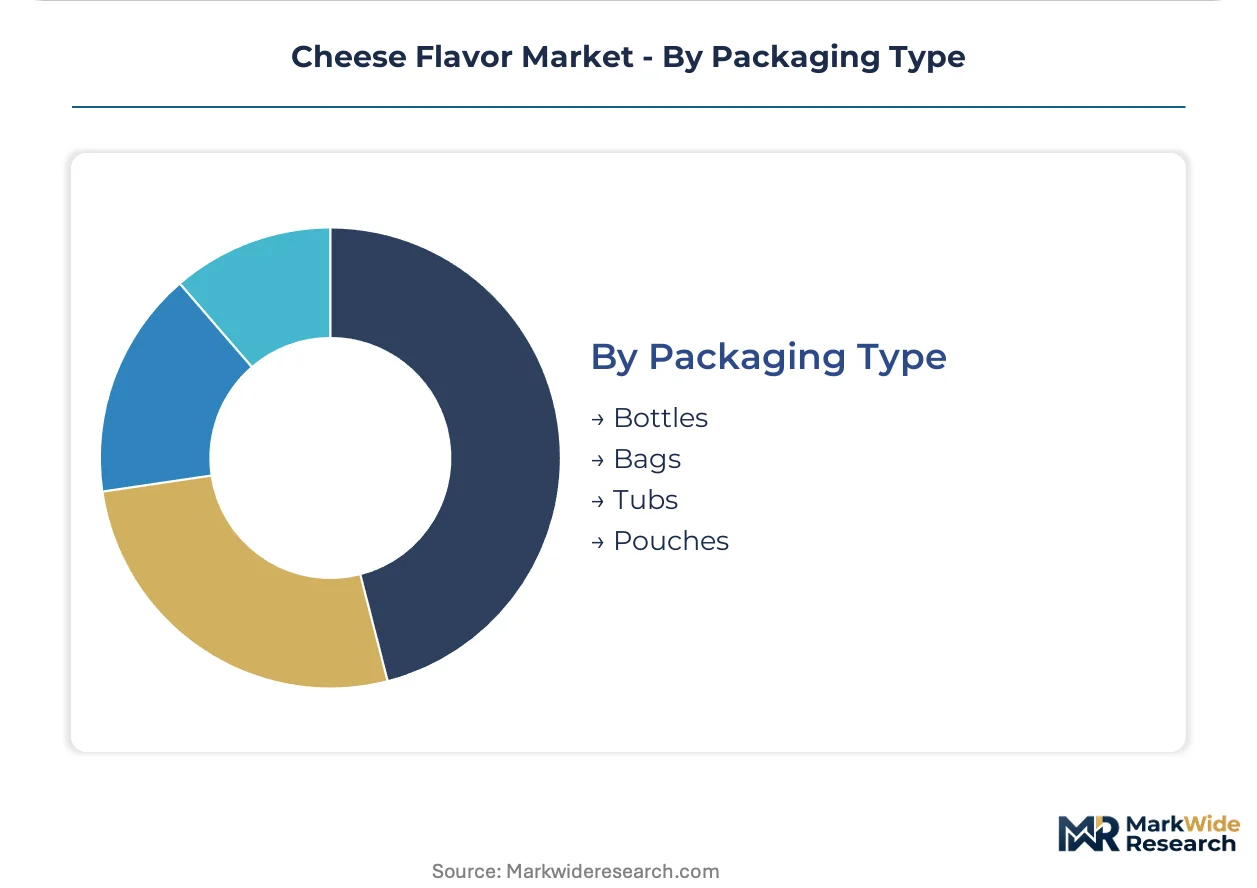
- Bottles:Liquid concentrate formats suit high-volume sauce manufacturing with automated dosing systems.
- Bags:Powdered flavor delivery dominates snack seasoning applications with extended shelf stability requirements.
- Tubs:Paste formats serve artisanal and small-batch food manufacturers requiring manual handling flexibility.
- Pouches:Single-serve and sample formats gain traction in direct-to-manufacturer trial programs and premium positioning strategies.
Bags sustain volume leadership on snack application dominance; Pouches gain share fastest on sampling and premium trial adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Snack food manufacturers in the United States consolidate supplier rosters most aggressively, while enzymatic flavor houses in the Netherlands and Germany scale precision fermentation capacity to meet EU Green Deal synthetic phase-out timelines.
United States
Extruded snack conglomerates drive concentrated procurement volume for sharp cheddar profiles in puffed product lines. FDA modernization initiatives accelerate natural flavor determinations under GRAS pathways. Chicago and Minneapolis-St. Paul anchor Midwest dairy processing clusters where enzymatic flavor houses secure milk solids for aged cheese replications.
Netherlands
Sauce manufacturers seek concentrated cheese essences for clean-label positioning in refrigerated pasta segments. EFSA systematic re-evaluation programs force reformulation cycles on synthetic flavor molecules. Wageningen biotech clusters host precision fermentation pilots generating dairy-identical proteins for flavor applications.
Germany
Food manufacturers demand ISO 22000-certified suppliers for long-term formulation partnerships across frozen pizza applications. EU Green Deal mandates compress synthetic compound phase-out deadlines to 2030. Bavarian dairy cooperatives fractionate milk solids for enzymatic flavor development serving Central European sauce producers.
United Kingdom
Retail private-label positioning drives cost-sensitive procurement of mild flavor carriers in mass-market spreads. FSA alignment with EFSA flavoring substance evaluations constrains molecule approvals post-Brexit. Greater Manchester food tech clusters develop fermented legume extracts displacing dairy-derived flavors in vegan snack segments.
France
Artisanal cheese flavor applications concentrate in premium positioning strategies for bakery and spread segments. ANSM oversees novel food consultations for precision fermentation-derived flavor molecules. Auvergne-Rhône-Alpes dairy processing regions supply concentrated milk fractions to enzymatic flavor houses serving European sauce manufacturers.
Cheese Flavor Market Competitive Environment
Player mix skews toward dairy cooperative-backed flavor houses with captive milk solids supply. The competitive structure concentrates around three qualification tiers: ISO 22000-certified suppliers with embedded R&D partnerships, commodity producers serving spot markets, and emerging biotech firms leveraging precision fermentation. Strategic moves center on backward integration into dairy sourcing and geographic expansion through regional formulation labs.
Within the cooperative-backed tier, FrieslandCampina and Fonterra Co-operative Group Limited exemplify players securing consistent raw material access through member dairy networks. Lactalis Ingredients occupies a position among specialized fractionators yielding concentrated cheese essences for European sauce applications. The Kraft Heinz Company anchors brand recognition across retail and foodservice channels through proprietary formulation relationships. These three represent distinct archetypes: cooperative sourcing, technical fractionation, and brand-anchored distribution.
| Leading Market Players |
|---|
| FrieslandCampina |
| Lactalis Ingredients |
| The Kraft Heinz Company |
| Dairy Farmers of America, Inc. |
| SAVENCIA SA |
| Fonterra Co-operative Group Limited |
| Saputo Inc. |
| Groupe Bel |
| Arla Foods amba |
| Others |
Value Chain & Pricing Dynamics
ISO 22000 certification gates both supplier qualification and price differentiation simultaneously, bifurcating the competitive landscape between certified flavor houses commanding formulation premiums and commodity producers competing on spot-market milk solids arbitrage.
Pricing Analysis
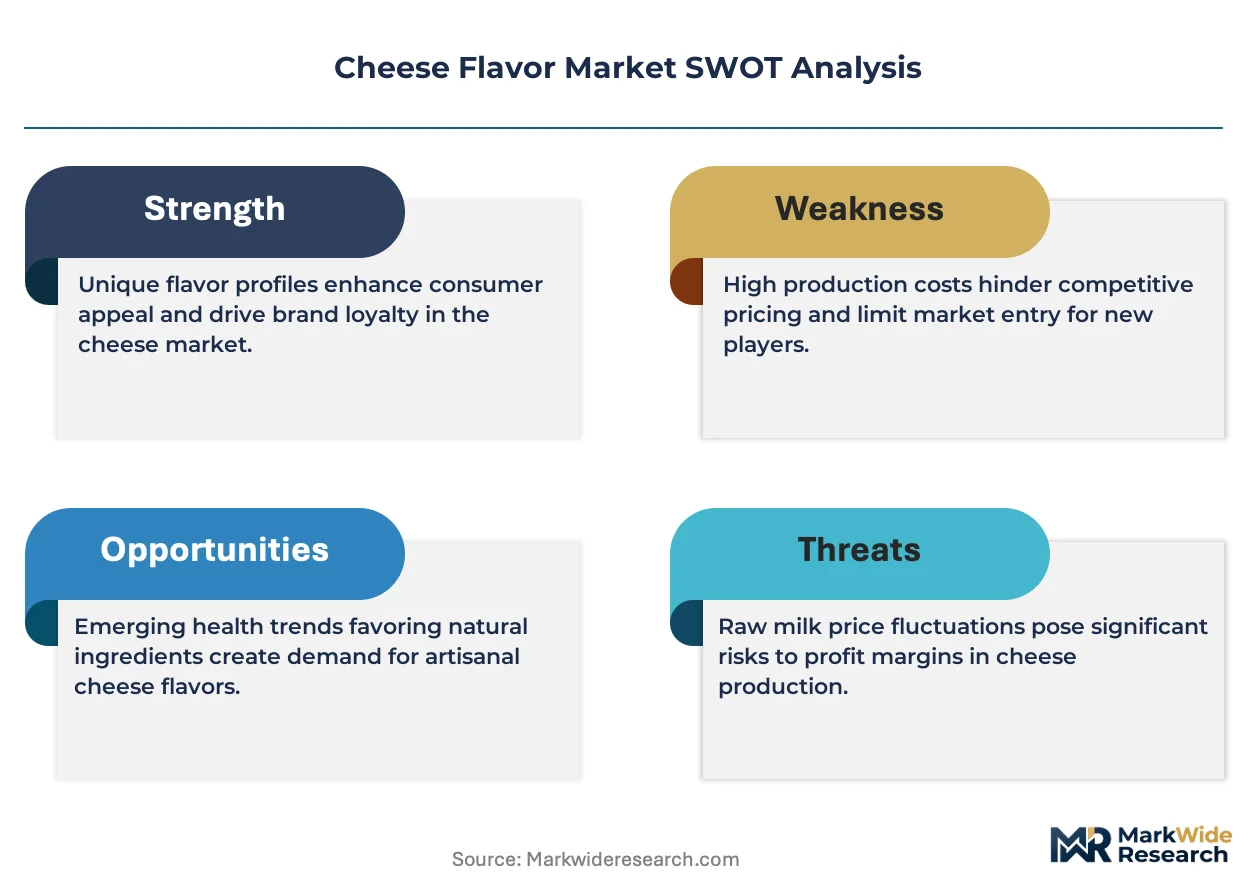
Cost-plus contracts with Global Dairy Trade indexation dominate long-term procurement between enzymatic flavor houses and multinational snack manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 22000-certified suppliers with embedded R&D teams from commodity producers and spot-market traders. Cost compression in the standard tier is intensifying because dairy cooperative-backed players leverage captive milk solids supply to undercut independent flavor houses. Food manufacturers represent the least price-sensitive segment due to formulation lock-in risks, while private-label retailers drive aggressive spot-market sourcing.
Supply Chain Analysis
Port congestion across Rotterdam and Hamburg trade lanes elevates inbound logistics costs for milk solids imports serving Central European enzymatic flavor houses. Supply concentrates in the Netherlands, Germany, and United States, where dairy processing clusters fractionate proteins and lipids for flavor applications. Raw material dependencies center on skim milk powder, butterfat fractions, and specialized enzyme preparations. Single-source vulnerability runs through cooperative dairy networks that control majority milk solids access. Distribution runs through direct-to-manufacturer channels with embedded R&D partnerships replacing traditional distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as clean-label mandates splinter procurement requirements across enzymatic, fermentation-derived, and synthetic-replacement flavor categories, creating specialized niches for qualified mid-tier suppliers.
For Market Incumbents: Consolidate backward integration into dairy cooperative sourcing to secure captive milk solids supply against commodity price volatility. Lock in long-term formulation partnerships with multinational snack conglomerates through dedicated R&D teams and volume guarantees, neutralizing precision fermentation entrants.
For New Entrants and Emerging Players: Anchor in precision fermentation platforms targeting Singapore and Netherlands regulatory sandboxes for novel dairy-identical protein molecules. Vegan sauce and dip applications present the most penetrable white-space segment, with direct-to-manufacturer sampling programs bypassing entrenched distribution tiers.
For Investors and Strategic Acquirers: Carve-out targets emerge from dairy cooperative flavor divisions lacking ISO 22000 certification but holding regional formulation expertise. Five-to-ten year viability hinges on enzymatic technology transition completion. Watch EFSA systematic re-evaluation program announcements as inflection indicators for synthetic flavor obsolescence timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dairy Sourcing | Captive milk solids supply insulates enzymatic flavor houses from Global Dairy Trade volatility. |
| Precision Fermentation Scale-Up | Singapore and Netherlands biotech clusters enable novel protein production outside traditional dairy quotas. |
| ISO 22000 Certification Investment | Regulatory qualification unlocks embedded R&D partnerships with top-four snack manufacturers. |
| Direct-to-Manufacturer Channel Development | Bypassing distributor tiers captures margin and deepens formulation collaboration. |
| Clean-Label Reformulation Partnerships | Sauce and dip manufacturers face steepest EFSA-driven transition costs, creating service revenue pools. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interviews with flavor house R&D directors, snack manufacturer procurement leads, dairy cooperative supply managers, and foodservice channel distributors. Secondary validation drew from EFSA flavoring substance evaluation registers, FDA GRAS determination filings, EU Green Deal implementation documents, and Global Dairy Trade auction data. Bottom-up volume modeling triangulated against top-down value estimates across enzymatic and synthetic flavor production capacity.
Across the analysis window, forecasts modeled flavor type segmentation by sharp, creamy, mild, and blue profiles; application splits across snacks, sauces, dips, and spreads; and end-user differentiation between food manufacturers, restaurants, retailers, and bakeries. CAGRs were derived from historical trajectory analysis adjusted for regulatory phase-out timelines and clean-label adoption curves. Precision fermentation capacity buildouts and EFSA systematic re-evaluation schedules served as industry-specific forecast inputs.
Material uncertainties — dairy commodity price volatility, regulatory approval delays for novel fermentation-derived molecules, and plant-based substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about enzymatic technology cost curves and synthetic compound phase-out adherence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Smoked Condensates Market
Flavorings and Food Additives
Modified Lecithin Market
Flavorings and Food Additives
Global Bitterness Suppressors and Flavor Carriers Market
Flavorings and Food Additives
Orange Terpenes Market
Flavorings and Food Additives
Citrus Oil Market
Flavorings and Food Additives
Carotenoids Pigment Market
Flavorings and Food Additives
Cocoa Extract Market
Flavorings and Food Additives
Feed Flavors and Sweeteners Market
Flavorings and Food Additives
Shelf-Stable Mezze Fermentation Ingredient Systems Market
Flavorings and Food Additives
Food Colorants Market
Flavorings and Food Additives
Annatto Extract Market
Flavorings and Food Additives
US Essential Oil Market
Flavorings and Food Additives
Hops Essential Oil Market
Flavorings and Food Additives
All-Natural Flavors System Market
Flavorings and Food Additives
Tangerine Extract Market
Flavorings and Food Additives
Yeast Based Savory Flavors Market