
 Clean Label Flavors Market | 2026-2036
Clean Label Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
Clean Label Flavors Market Outlook
FDA nutrition labeling modernization is repositioning the cost-of-entry calculus for flavor houses serving North American food manufacturers. Kerry Group plc leverages backward integration into natural dairy flavor extraction to sustain margin control across its beverage and dairy application portfolio. Givaudan specializes in biotechnology-derived flavor molecules, anchoring its position in markets where EU REACH compliance constrains petrochemical-based alternatives. DSM-Firmenich dominates the premium essential oils segment through captive supply of sustainable vanilla and citrus extracts.
Clean label flavors comprise taste-active substances derived from named botanical, animal, or microbial sources without synthetic additives, carriers, or processing aids not declared on ingredient statements, typically manufactured through cold-press extraction, gentle distillation below 80°C, or controlled fermentation to preserve volatile aromatic compounds. Their primary commercial purpose is delivering authentic taste profiles in packaged foods while satisfying retailer clean ingredient policies and regulatory disclosure requirements. Natural extracts and essential oils command the widest formulation flexibility across bakery and beverage applications, where heat stability and solubility constraints drive technical selection. Fruit concentrates represent the fastest-growing product category as CPG companies reformulate with recognizable ingredient declarations that bypass consumer skepticism toward chemical-sounding additives.
The USDA National Organic Program and EU EFSA flavoring substance evaluation program jointly determine which extraction methods and carrier solvents qualify for clean label positioning in their respective jurisdictions. EPA enforcement of residual solvent limits under the Food Quality Protection Act shapes domestic manufacturing process investments, while EU MDR-adjacent disclosure requirements pressure flavor houses to document supply chain provenance down to cultivar level. Stakeholders must monitor pending FDA guidance on the "natural" flavor descriptor, as definitional tightening would force immediate reformulation across thousands of existing SKU portfolios.
Market Dynamics
Label literacy campaigns by major retailers are compressing reformulation timelines for flavor houses, forcing simultaneous compliance with FDA disclosure rules and EU Green Deal extraction standards.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for synthetic refrigerants used in conventional extraction are accelerating capital migration toward cold-press and sub-critical CO2 systems in flavor manufacturing.
- Beverage sector procurement:Carbonated soft drink and functional water producers are expanding long-term contracts for natural citrus and botanical extracts to preempt clean label certification requirements.
- Controlled fermentation:Precision bioprocessing platforms now yield volatile aromatic compounds identical to plant-derived equivalents, bypassing agricultural supply volatility and seasonal harvest constraints.
Market Restraints
- Vanilla bean supply concentration:Madagascar and Uganda account for over four-fifths of global vanilla cultivation, exposing flavor houses to cyclone-driven crop failures and speculative price spikes.
- Cold-press extraction yield limits:Gentle processing below 80°C captures fewer total aromatic compounds than thermal distillation, requiring higher raw material throughput per unit of flavor concentrate.
- USDA National Organic Program compliance costs:Certification audits, buffer zone maintenance, and prohibited substance documentation add 15-25% overhead to organic flavor production versus conventional alternatives.
Strategic Opportunities
- India FSSAI clean label guidelines:Pending notification of natural flavor definitions creates first-mover advantage for suppliers establishing local extraction partnerships ahead of formal mandate implementation.
- Pet food application expansion:Premium companion animal nutrition brands are adopting human-grade flavor declarations, opening formulation contracts previously served by synthetic palatants.
- Blockchain-enabled provenance verification:Immutable cultivar-to-customer tracking satisfies EU MDR-adjacent disclosure requirements while commanding price premiums from transparency-focused CPG buyers.
Industry Challenges
- Flavor chemist talent scarcity:Retirements of specialists trained in pre-digital extraction methods outpace university pipeline output, compressing R&D cycle capacity at mid-tier houses.
- Legacy ERP integration:Batch record systems designed for synthetic flavor manufacturing require costly reconfiguration to track multi-source botanical provenance and variable extraction parameters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clean Label Flavors Market |
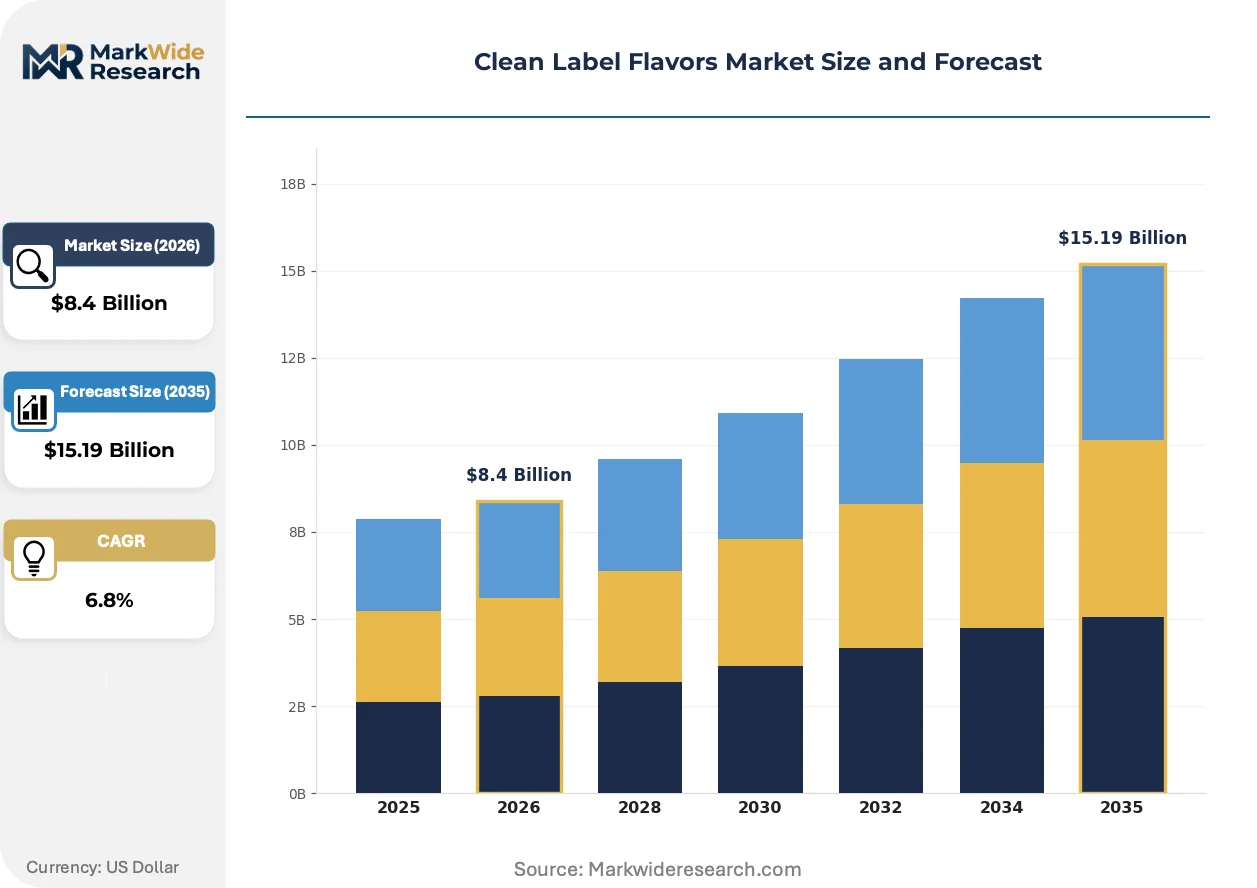
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Extracts, Essential Oils, Flavor Compounds, Fruit Concentrates Application: Bakery Products, Beverages, Dairy, Snacks Form: Liquid, Powder, Paste, Granular End User: Food Manufacturers, Beverage Producers, CPG Companies, Restaurants |
| Companies Covered | International Flavors & Fragrances Inc., DSM-Firmenich, Kerry Group plc, Sensient Technologies Corporation, Givaudan, Symrise, Cargill Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clean Label Flavors Market Strategic Shifts
Biotechnology platforms and precision fermentation systems are displacing conventional agricultural extraction as the primary production modality for high-value aromatic compounds.
Cell-culture-derived flavor molecules are rewriting supply security calculations for vanilla, saffron, and citrus extracts. Givaudan and smaller biotechnology specialists have scaled precision fermentation to commercial volumes. This technology is rewriting the geographic distribution of flavor production, decoupling manufacturing from equatorial growing regions and compressing lead times from harvest cycles to bioreactor batches.
EU REACH substance evaluation is tightening disclosure thresholds for residual processing aids and carrier solvents. Flavor houses must now document complete supply chain provenance down to cultivar level for substances of very high concern. Natural extract suppliers serving European CPG manufacturers are responding by consolidating supplier audits and investing in captive agricultural partnerships.
Retail buyer concentration is compressing supplier negotiation leverage. Walmart, Carrefour, and Aldi now mandate clean label flavor declarations as a condition of shelf placement, effectively transferring compliance investment burden upstream. This shift is most visible in Germany, where discounter private label expansion has forced reformulation across pan-European bakery and beverage portfolios.
Clean Label Flavors Market Segmentation
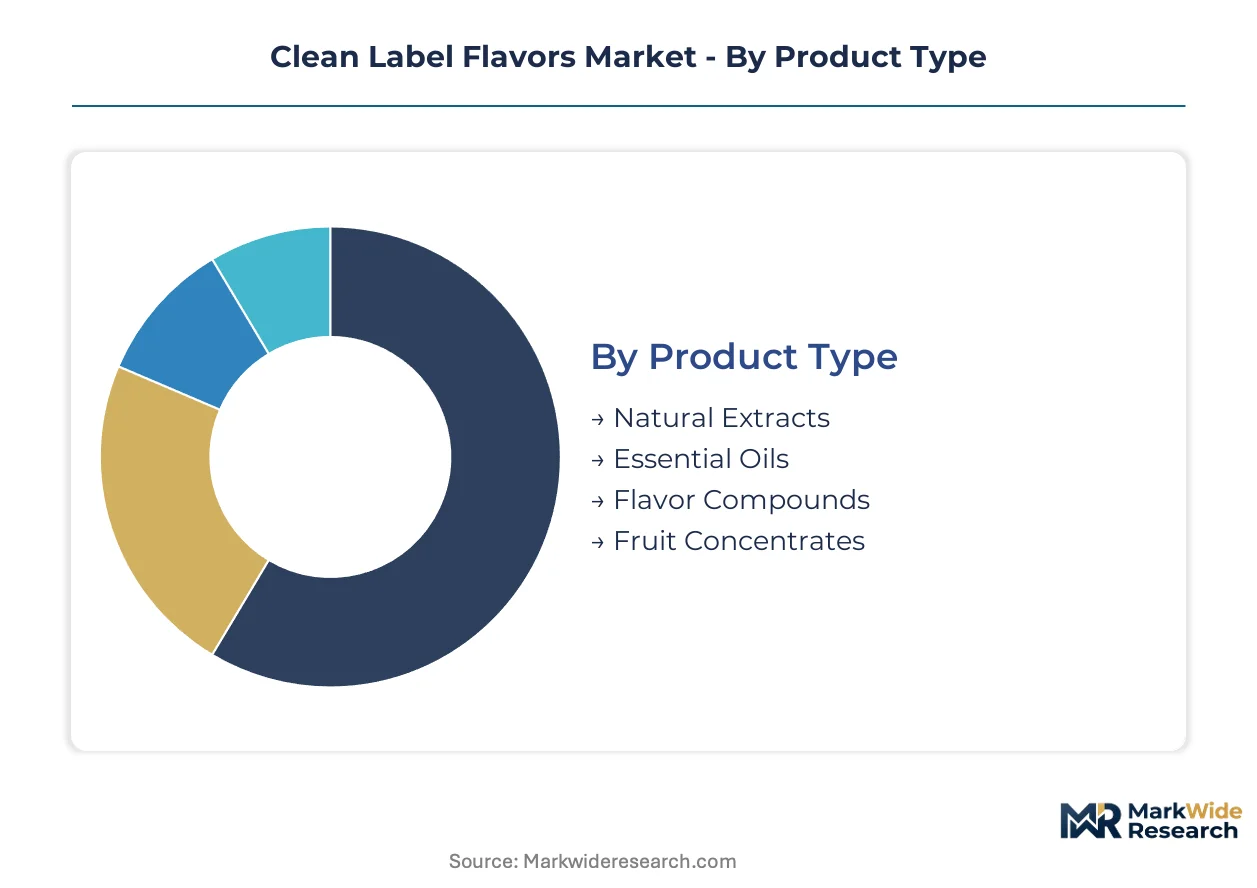
Clean label flavor procurement diverges sharply across product categories and end-use specifications, with extraction method and heat stability requirements determining viable supplier matches. Application-specific formulation constraints—beverage solubility versus bakery heat tolerance—create distinct technical qualification barriers that fragment procurement patterns.
Product Type:
Supply concentration in high-value botanical sourcing channels shapes competitive positioning across extraction-derived categories, with Madagascar vanilla and Kerala cardamom commanding disproportionate procurement attention.
- Natural Extracts:Cold-press and gentle distillation outputs capturing volatile aromatic compounds from named botanical sources. Beverage manufacturers in Germany source heavily from these categories to satisfy Aldi and Carrefour clean label mandates, though yield constraints elevate raw material throughput requirements.
- Essential Oils:Concentrated lipophilic fractions isolated through steam distillation or expression, prized for heat stability in thermal processing. Bakery applications across France and Italy absorb the majority of citrus and spice oil volumes, driven by EU EFSA disclosure requirements for synthetic additive replacement.
- Flavor Compounds:Biotechnology-derived molecules matching plant-derived aromatic profiles.
- Fruit Concentrates:Recognizable ingredient declarations bypassing consumer skepticism toward chemical-sounding additives.
Natural extracts absorb the bulk of installed capacity; fruit concentrates are expanding most quickly.
Application:
End-use thermal processing severity determines formulation selection, with heat-stable oils dominating high-temperature applications while cold-soluble extracts serve ambient mixing protocols.
- Beverages:Carbonated soft drink and functional water producers expanding long-term contracts for natural citrus and botanical extracts. Cold-soluble liquid formats predominate, with solubility constraints driving technical selection toward essential oil emulsions and natural extracts rather than heat-processed alternatives.
- Bakery Products:Heat-stable essential oils and encapsulated natural extracts withstand oven temperatures exceeding 180°C. German and French industrial bakeries represent the largest procurement volume, reformulating to meet discounter private label clean label requirements.
- Dairy:Fermentation-compatible flavor systems for yogurt and cultured products.
- Snacks:Oil-soluble and powder formats for savory seasoning applications.
Beverages absorb the bulk of installed capacity; snacks are expanding most quickly.
Form:
Physical state selection hinges on manufacturing equipment compatibility and shelf stability requirements, with liquid formats dominating high-volume beverage operations.
- Liquid:Ready-to-dose solutions for continuous processing lines, commanding widest formulation flexibility across beverage applications. Cold-press extraction yields predominate in this format, with sub-critical CO2 systems displacing conventional solvent extraction under EU F-Gas Regulation phase-down schedules.
- Powder:Spray-dried and plated variants for dry mix applications. Snack seasoning and bakery premix manufacturers in Italy and Spain source heavily here, driven by powder handling infrastructure and extended ambient shelf stability.
- Paste:High-solids concentrates for industrial-scale dosing.
- Granular:Free-flowing formats for tabletop and small-batch applications.
Liquid absorbs the bulk of installed capacity; powder is expanding most quickly.
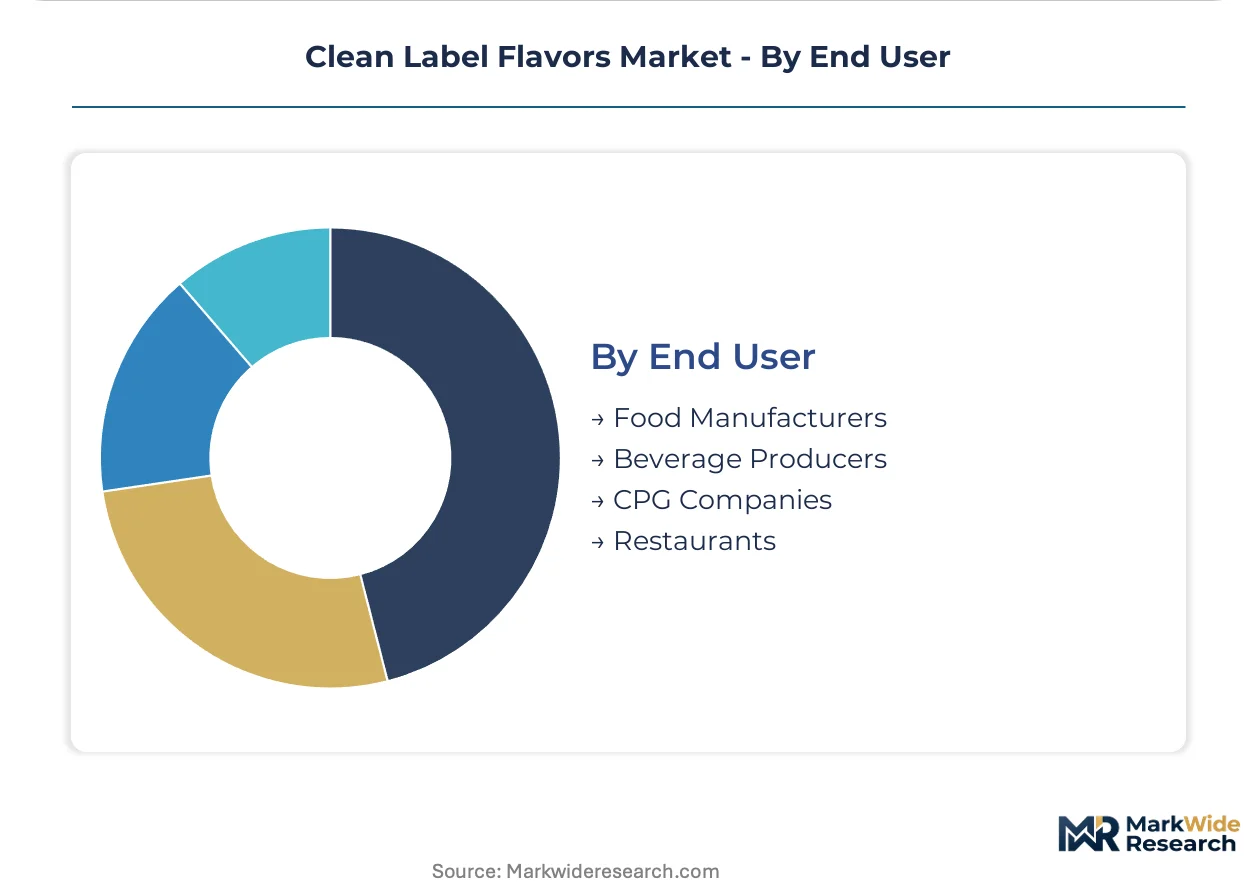
End User:
Procurement scale and technical specification sophistication separate multinational CPG buyers from regional food service operators, with certification requirements tightening fastest at the top of the customer pyramid.
- CPG Companies:Walmart, Carrefour, and Aldi clean label mandates transferred upstream to flavor houses through contractual shelf placement conditions. These buyers command complete supply chain provenance documentation down to cultivar level, with blockchain-enabled verification emerging as a price premium justification.
- Food Manufacturers:Mid-tier industrial bakeries and confectioners reformulating under retailer pressure. German natural flavor formulation clusters serve this segment across pan-European supply chains, with EU REACH compliance constraining petrochemical-based alternative sourcing.
- Beverage Producers:Carbonated and functional water specialists with long-term extract contracts.
- Restaurants:Premium independent and small-chain operators seeking human-grade declarations.
CPG companies absorb the bulk of installed capacity; food manufacturers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, where natural flavor formulation clusters serve pan-European food manufacturers. Procurement patterns diverge sharply across extraction method standards and retailer certification requirements.
Germany
Industrial bakeries and beverage manufacturers drive procurement volume under Aldi and Carrefour clean label mandates. The EU F-Gas Regulation accelerates capital migration toward sub-critical CO2 extraction systems. Cologne and Hamburg harbor formulation clusters supplying reformulated private label portfolios across France, Italy, and Spain.
United States
Carbonated soft drink producers expand long-term contracts for natural citrus extracts to preempt clean label certification requirements. FDA nutrition labeling modernization and EPA residual solvent enforcement reshape manufacturing process investments. Chicago and New Jersey processing hubs absorb the bulk of North American cold-press capacity expansion.
France
Premium bakery applications absorb heat-stable essential oils under EU EFSA disclosure requirements for synthetic additive replacement. REACH substance evaluation tightens documentation thresholds for residual processing aids. Grasse and the surrounding Provence-Alpes-Côte d'Azur region maintain captive agricultural partnerships for lavender, rose, and citrus oil extraction.
India
Spice oil extraction from Kerala cardamom and Karnataka vanilla faces pending FSSAI clean label guideline notification. Domestic CPG companies stockpile natural extracts ahead of formal mandate implementation. Mumbai and Ahmedabad formulation facilities serve both export markets and emerging local demand from reformulating snack and beverage brands.
China
Biotechnology-derived flavor molecule production scales to bypass agricultural supply volatility and seasonal harvest constraints. SAMR natural flavor registration requirements and GB standards for extraction solvents determine import qualification. Shanghai and Zhejiang bioprocessing clusters commercialize precision fermentation platforms for vanilla and citrus aromatic compounds.
Clean Label Flavors Market Competitive Environment
Swiss and Dutch producers anchor the premium tier; German specialists hold mid-market formulation contracts. The vendor base concentrates around integrated flavor houses with captive extraction assets and biotechnology platforms. Three archetypes dominate: backward-integrated agricultural operators, precision fermentation specialists, and regional formulation service providers. Competitive moves center on captive supply partnerships and bioreactor capacity expansion.
Within the biotechnology tier, Givaudan and DSM-Firmenich exemplify the shift toward precision fermentation platforms. Kerry Group plc occupies a position bridging natural extraction and controlled bioprocessing. These three entities represent the dominant competitive anchors as procurement shifts from equatorial agricultural dependence toward bioreactor-based supply security.
| Leading Market Players |
|---|
| International Flavors & Fragrances Inc. |
| DSM-Firmenich |
| Kerry Group plc |
| Sensient Technologies Corporation |
| Givaudan |
| Symrise |
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up mid-tier flavor houses now control significant cold-press extraction capacity across Germany and the United States, concentrating procurement leverage over vanilla and citrus suppliers while enforcing contract discipline that stabilizes input cost volatility for premium extract tiers.
Pricing Analysis
Premium pricing attaches to sub-critical CO2 extracts with sub-90-day lead times, while spot inventory of conventional solvent-derived alternatives trades at meaningful discounts. Three-tier pricing structure across premium, standard, and economy levels stratifies by extraction method certification and cultivar documentation depth. Cost compression in the standard tier is intensifying because EU F-Gas Regulation compliance investments are elevating fixed cost bases. Mid-tier food manufacturers exhibit the highest price sensitivity, whereas multinational CPG buyers prioritize supply security over unit economics.
Supply Chain Analysis
EU REACH substance evaluation and USDA National Organic Program certification now gate supplier qualification, extending onboarding timelines and consolidating approved vendor pools. Raw material sourcing draws from Madagascar and Uganda for vanilla, Kerala for cardamom, and Provence-Alpes-Côte d'Azur for lavender and citrus oils. Single-source vulnerability concentrates in Madagascar vanilla cultivation, where cyclone exposure threatens annual harvest volumes. Distribution runs through formulation clusters in Cologne, Hamburg, and Chicago that serve pan-regional CPG manufacturing networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating rapidly as retailer clean label mandates force simultaneous FDA and EU Green Deal compliance investments that smaller extraction houses cannot absorb.
For Market Incumbents: Cement captive supply partnerships with Kerala cardamom cooperatives and Provence lavender growers to preempt raw material competition from biotechnology entrants. Expand sub-critical CO2 extraction capacity in Hamburg and New Jersey to capture beverage sector procurement migrating from conventional solvent systems. The priority defensive lever is backward integration into high-value botanical sourcing channels.
For New Entrants and Emerging Players: The gap between premium biotechnology-derived flavor molecules and economy-tier conventional extracts creates white-space opportunity at the mid-market intersection. Precision fermentation platforms for vanilla and saffron aromatic compounds offer the most penetrable entry vector, bypassing agricultural supply volatility that constrains incumbent capacity. Target pet food application contracts as a go-to-market angle, where human-grade flavor declarations command pricing tolerance absent in commodity feed palatants.
For Investors and Strategic Acquirers: Pending FDA guidance on the "natural" flavor descriptor is the leading indicator that definitional tightening will force immediate reformulation across thousands of existing SKU portfolios, accelerating distressed asset availability. The acquisition target archetype is mid-tier flavor houses with established retailer relationships but insufficient biotechnology R&D capacity to meet impending disclosure requirements. Watch for FSSAI clean label guideline notification in India as the signal that first-mover extraction partnerships there will lock in regional supply advantages.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Bioreactor capacity expansion in Shanghai and Zhejiang decouples vanilla production from Madagascar cyclone risk. |
| Captive Agricultural Partnership | Exclusive cultivar contracts with Kerala cardamom cooperatives secure heat-stable essential oil supply for EU bakery reformulation. |
| Blockchain Provenance Verification | Immutable cultivar-to-customer tracking satisfies EU MDR-adjacent disclosure requirements and commands CPG price premiums. |
| Cold-Press Capacity Expansion | Sub-critical CO2 system installation in Chicago and Hamburg captures beverage procurement migrating under F-Gas Regulation phase-down. |
| Pet Food Application Entry | Human-grade flavor declarations open formulation contracts previously served by synthetic palatants in premium companion nutrition. |
Study Parameters
Independent corroboration across flavor house procurement directors, CPG category buyers, and extraction equipment manufacturers underwrites the qualitative findings in this study. Primary interviews with beverage reformulation leads, bakery technical directors, and biotechnology platform engineers combined with secondary validation from EU EFSA flavoring substance evaluations, FDA guidance dockets, and FSSAI notification records. Bottom-up capacity assessments across Cologne, Hamburg, Grasse, Chicago, and New Jersey formulation clusters triangulated against top-down procurement flow analysis.
Comparable-period anchoring to pre-COVID baseline years established volume and trajectory reference points across the projection horizon. Segmentation modeling incorporated extraction method, application thermal processing severity, physical form, and end-user procurement scale. CAGRs derived from weighted average of demand elasticity coefficients and supply capacity expansion schedules. Forecast inputs included EU F-Gas Regulation phase-down compliance timelines and pending FDA natural flavor descriptor guidance.
Underlying measurement precision varies by segment; biotechnology-derived flavor compounds and essential oils carry tighter precision than conventional extracts due to concentrated producer transparency. Forecasts reflect documented assumptions regarding regulatory implementation pacing and retailer mandate adoption curves. A model refresh is warranted upon material change in FDA natural flavor guidance publication or FSSAI clean label notification timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Flavor Ingredients Market
Flavorings and Food Additives
Mexico Food Colorants Market
Flavorings and Food Additives
Shelf-Stable Mezze Fermentation Ingredient Systems Market
Flavorings and Food Additives
South America Food Flavor Market
Flavorings and Food Additives
Canola Lecithin Market
Flavorings and Food Additives
Cheese Flavor Market
Flavorings and Food Additives
Beef Flavors Market
Flavorings and Food Additives
Flavored Butter and Oils Market
Flavorings and Food Additives
Global Acerola Extracts Market
Flavorings and Food Additives
Chocolate Flavoring Compounds Market
Flavorings and Food Additives
Mouth Freshener Market
Flavorings and Food Additives
Culinary Essence Market
Flavorings and Food Additives
Water Flavoring Drop Market
Flavorings and Food Additives
Menthol Market
Flavorings and Food Additives
Keto Friendly Flavors Market
Flavorings and Food Additives
Oleoresin Market