
 Africa Medical Cannabis Market | 2026-2036
Africa Medical Cannabis Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Medical Cannabis Market Intelligence
Lesotho's licensed greenhouse operators is recalibrating export quotas toward pharmaceutical-grade output. Medigrow Africa leverages high-altitude cultivation to sustain terpene consistency for European offtake agreements. Bophelo Biosciences and Wellness anchors domestic South African supply through its Bloemfontein extraction facility. Asterion Cannabis competes on GMP certification, differentiating its product for hospital pharmacy channels.
Medical cannabis comprises standardized cannabinoid formulations—primarily THC and CBD extracts processed to pharmaceutical purity grades—for therapeutic administration under clinical supervision. Extraction employs supercritical CO2 or ethanol methods to achieve batch consistency for regulatory submission. Oils dominate current prescription volumes due to physician familiarity with titrated dosing, while inhalation delivery modes capture the fastest expansion among pain management protocols. Neurological disorder applications attract concentrated R&D investment, though cancer therapy segments carry premium pricing power where cytostatic adjunct protocols apply.
South Africa's SAHPRA governs cultivation permits and scheduling amendments, while Lesotho's Medicines Regulatory Authority oversees export certification; both frameworks impose THC potency ceilings and track-and-trace requirements that shape operational scale decisions. WHO cannabis rescheduling recommendations filter into national guideline revisions, compressing product registration timelines in compliant jurisdictions. Stakeholders must monitor scheduling reclassification momentum and cultivation license backlog clearance rates to time capacity commitments.
Market Dynamics
Lesotho's export quota recalibration toward pharmaceutical-grade output is compressing cultivation-to-distribution timelines across Southern Africa. SAHPRA's evolving scheduling amendments are forcing operational scale decisions before license backlogs clear.
Growth Catalysts
- GMP Certification Pathways:Hospital pharmacy channels in South Africa's Gauteng province now mandate pharmaceutical purity grades. Asterion Cannabis and comparable operators are securing European offtake agreements through certification compliance.
- Neurological Disorder Protocols:Concentrated R&D investment into cannabinoid formulations for epilepsy and multiple sclerosis is expanding addressable patient populations. Clinical trial infrastructure in Western Cape accelerates protocol validation.
- Lesotho's High-Altitude Cultivation:Terpene consistency from elevated greenhouse operations supports standardized extract output. Medigrow Africa leverages this geographic advantage for batch-to-batch pharmaceutical uniformity.
Market Restraints
- THC Potency Ceilings:SAHPRA and Lesotho's Medicines Regulatory Authority impose strict cannabinoid concentration limits that constrain formulation flexibility. Product registration timelines extend when potency thresholds require resubmission.
- Supercritical CO2 Equipment Import Dependency:Extraction machinery for pharmaceutical-grade output originates from limited European and North American suppliers. Currency volatility amplifies capex burden for scale-up operators.
- Track-and-Trace System Costs:Seed-to-sale compliance infrastructure demands sustained IT investment. Smaller cultivators face disproportionate overhead relative to output volume.
Strategic Opportunities
- Cancer Therapy Adjunct Protocols:Cytostatic combination therapies command premium pricing where cannabinoid extracts demonstrate antiemetic efficacy. Oncology departments in private South African hospital networks represent concentrated demand.
- Inhalation Delivery Expansion:Pain management protocols are adopting metered-dose inhalation faster than oil-based administration. Device manufacturers are partnering with extractors for co-developed delivery systems.
- WHO Rescheduling Momentum:International guideline revisions are filtering into national framework updates. Jurisdictions aligning with WHO recommendations compress product registration timelines for early movers.
Industry Challenges
- Pharmaceutical-Grade Talent Scarcity:Supercritical extraction technicians and GMP compliance officers command premium compensation. Training pipelines lag behind facility commissioning schedules.
- Batch Consistency Validation:Supercritical CO2 and ethanol methods require continuous analytical testing for regulatory submission. Laboratory capacity constraints create bottlenecks between extraction and release.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Medical Cannabis Market |
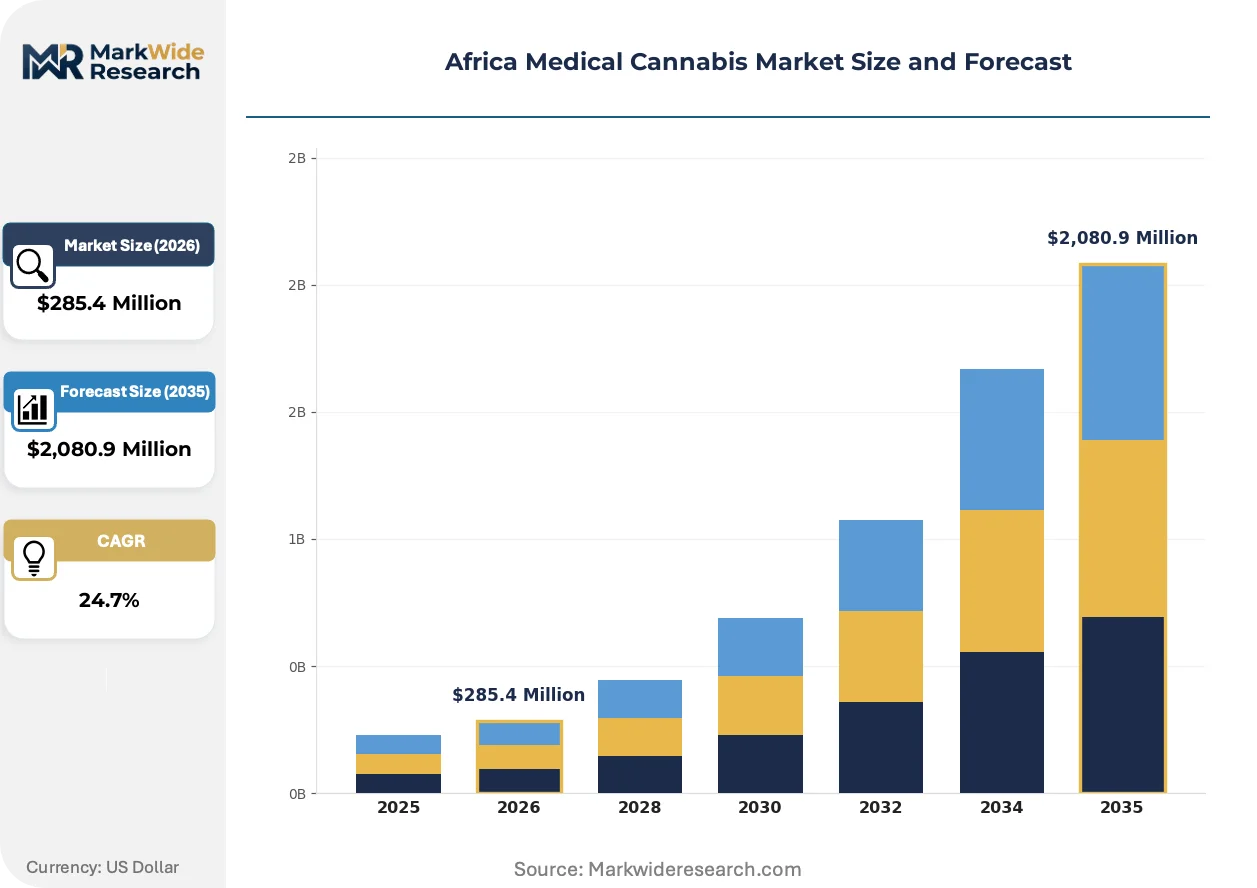
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $2,080.9 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oils, Tinctures, Capsules, Edibles End User: Pharmacies, Hospitals, Dispensaries, Patients Application: Chronic Pain Management, Neurological Disorders, Cancer Therapy, Palliative Care Delivery Mode: Inhalation, Oral, Topical, Vaporization |
| Companies Covered | Medigrow Africa, SANCAP, Halo Collective, Asterion Cannabis, Prohibition Partners, Bophelo Biosciences and Wellness, Wesgrow Potatoes, Louisa Mojela Enterprises, Rascal Medicinal Cannabis, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Medical Cannabis Market Strategic Shifts & Innovations
Supercritical extraction automation and inhalation device co-development are compressing product development cycles. Regulatory harmonization pressures are forcing operators to design for multi-jurisdictional compliance from facility conception.
Automated supercritical CO2 extraction systems with inline chromatography are electrifying throughput capabilities for pharmaceutical-grade cannabinoid isolation. South African hospital pharmacy procurement teams are specifying these systems in supplier qualification criteria. The technology is electrifying competitive differentiation among extraction facility operators bidding for network supply contracts.
SAHPRA's scheduling amendment process for cannabinoid reclassification is compressing product category definitions. Pharmaceutical manufacturers are pre-positioning formulation portfolios for expanded indication approvals. Oncology and neurology therapeutic areas face the most immediate registration pathway revisions.
Hospital network procurement is consolidating supplier lists around vertically integrated cultivator-extractors with captive GMP certification. Private healthcare groups in Western Cape are displacing fragmented distributor relationships with direct manufacturing agreements. This concentration is most visible in Gauteng and Western Cape where clinical trial infrastructure anchors purchasing decisions.
Africa Medical Cannabis Market Segmentation
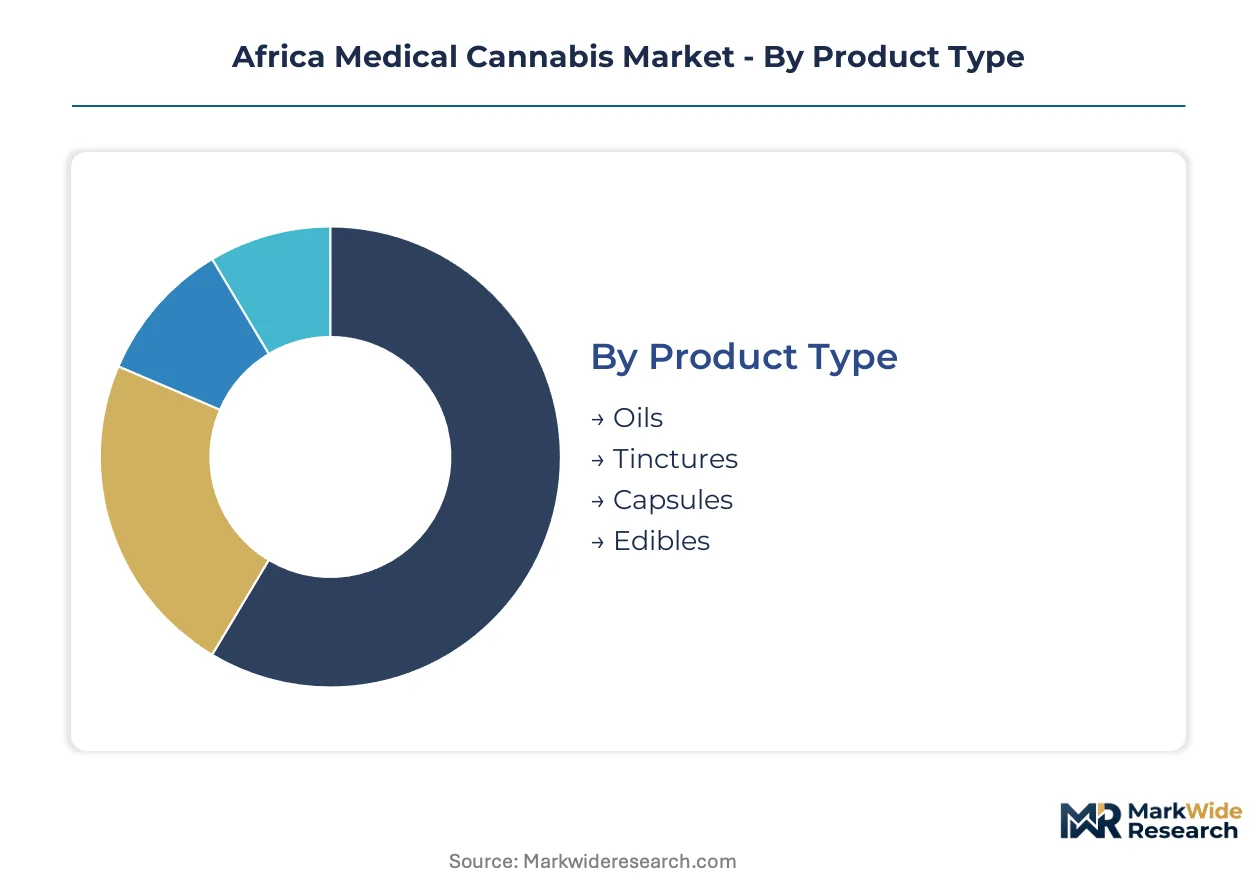
Product form, clinical setting, therapeutic target, and administration route each carry distinct regulatory, reimbursement, and margin profiles across Southern African markets. Understanding these segment boundaries clarifies where capital deployment yields pharmaceutical-grade returns versus commodity exposure.
Product Type:
Oils dominate prescription volumes due to physician familiarity with titrated dosing, while capsules command premium pricing through standardized cannabinoid content.
- Oils:THC and CBD extracts suspended in carrier oils enable precise milligram dosing adjustments. Demand concentrates in South Africa's Gauteng province hospital networks where oncologists and pain specialists prefer liquid formulations for gradual titration protocols.
- Capsules:Gelatin or vegetable-based shells deliver fixed-dose cannabinoid payloads with extended shelf stability. Private healthcare groups in Western Cape specify capsules for outpatient neurological disorder regimens requiring consistent bioavailability.
- Tinctures:Alcohol-based extractions with rapid sublingual absorption serve patients requiring faster onset than oral delivery permits.
- Edibles:Food-matrix cannabinoid infusions face SAHPRA scheduling complexity around palatability and accidental ingestion risk.
Mature deployment sits with Oils. Newer deployment is concentrated in Capsules.
End User:
Procurement authority and reimbursement pathways diverge sharply between institutional buyers and direct patient channels.
- Hospitals:Inpatient and outpatient pharmacy departments within South Africa's private hospital networks mandate GMP-certified supply chains. Gauteng's oncology units drive concentrated demand for antiemetic adjunct protocols.
- Pharmacies:Community and hospital outpatient dispensaries handle the majority of repeat prescription fulfillment. Western Cape's independent pharmacies are consolidating around vertically integrated cultivator-extractors with captive certification.
- Dispensaries:Licensed cannabis-specific retail channels operate under stricter SAHPRA supervision than conventional pharmacies.
- Patients:Direct acquisition remains limited by prescription requirements and insurance reimbursement gaps across Southern Africa.
Volume leadership belongs to Hospitals. Margin expansion is concentrating in Pharmacies.
Application:
Therapeutic area selection determines regulatory pathway complexity and pricing power within hospital procurement frameworks.
- Chronic Pain Management:Long-duration cannabinoid protocols for neuropathic and inflammatory pain conditions represent the largest addressable patient population. South Africa's private hospital networks in Gauteng specify oils and inhalation devices for multimodal pain regimens.
- Cancer Therapy:Cytostatic combination therapies command premium pricing where cannabinoid extracts demonstrate antiemetic and appetite-stimulant efficacy. Oncology departments anchor demand concentration in Western Cape private healthcare facilities.
- Neurological Disorders:Epilepsy and multiple sclerosis applications attract concentrated R&D investment with expanding clinical trial infrastructure.
- Palliative Care:End-of-life symptom management protocols prioritize rapid onset delivery modes and flexible dosing.
Established penetration sits with Chronic Pain Management. Steepest expansion trajectory is visible in Cancer Therapy.
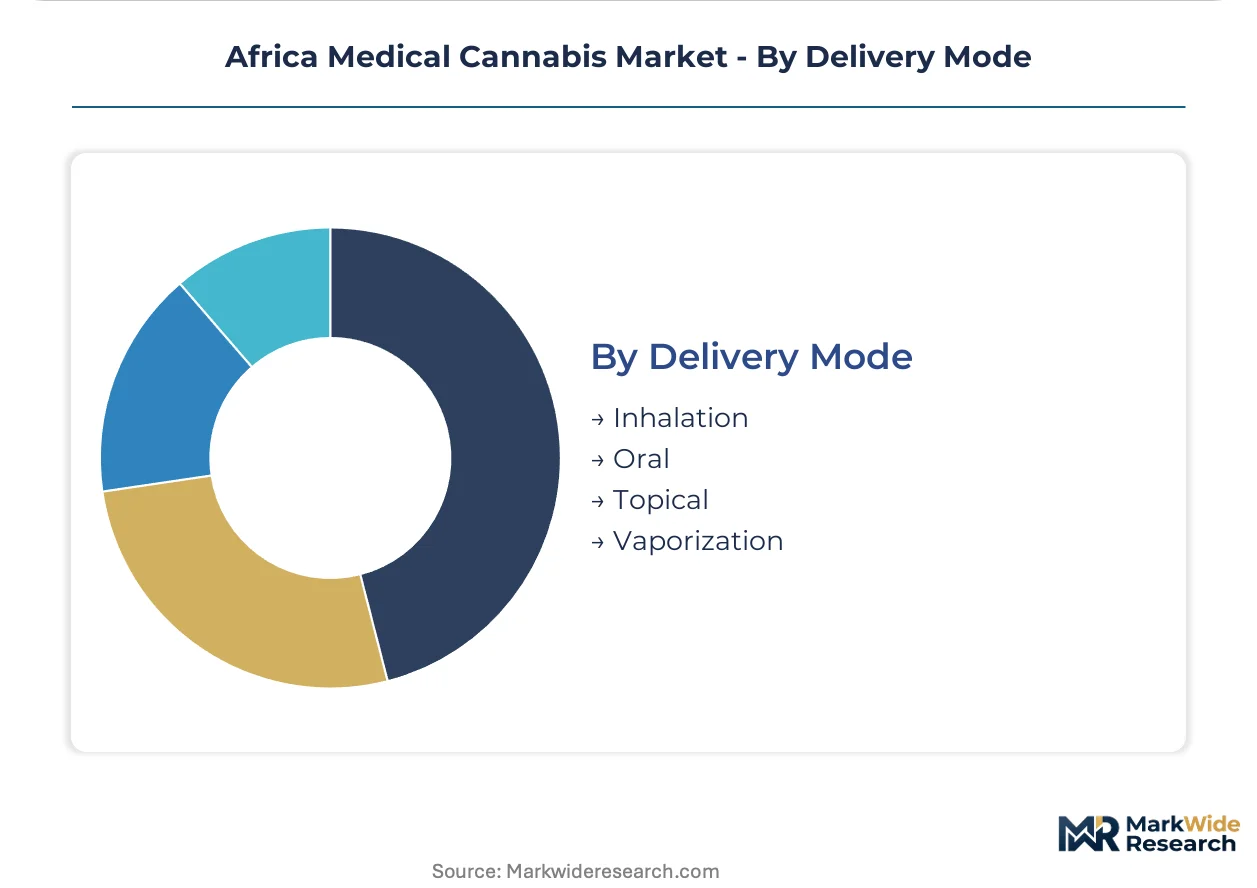
Delivery Mode:
Onset speed, dosing precision, and physician training requirements shape adoption curves across clinical settings.
- Oral:Swallowed oils and capsules provide extended duration with delayed onset, suiting maintenance dosing protocols. South Africa's hospital pharmacies specify oral delivery for discharged patients requiring home-based regimens.
- Inhalation:Metered-dose devices deliver rapid cannabinoid absorption for breakthrough pain episodes. Pain management protocols in Gauteng private hospitals are adopting inhalation faster than oil-based administration.
- Vaporization:Heated cannabinoid aerosol without combustion byproducts occupies a regulatory gray zone under evolving SAHPRA guidelines.
- Topical:Transdermal patches and creams target localized inflammation with minimal systemic absorption, limiting addressable indications.
Dominant utilization rests with Oral delivery. Fastest share gains are occurring in Inhalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-altitude greenhouse zones in Lesotho anchor Southern Africa's pharmaceutical-grade cannabis feedstock output, with cultivation clusters extending into South Africa's Free State and KwaZulu-Natal provinces. Export corridor infrastructure and GMP-certified processing capacity concentrate where altitude, regulatory alignment, and hospital network procurement intersect.
Lesotho
Pharmaceutical-grade export quotas and European offtake agreements drive greenhouse expansion in the country's highland districts. The Medicines Regulatory Authority oversees THC potency ceilings and track-and-trace certification for cross-border shipment. Maseru and surrounding high-altitude cultivation zones sustain terpene consistency for standardized extract production.
South Africa
Gauteng's private hospital networks and Western Cape clinical trial infrastructure concentrate demand for oils and inhalation devices. SAHPRA governs cultivation permits and scheduling amendments that shape operational scale decisions. Bloemfontein extraction facilities and Cape Town pharmaceutical corridors anchor domestic supply chain integration.
Zimbabwe
Industrial hemp licensing reforms and medicinal cannabis export permits attract greenhouse investment from regional operators. The Medicines Control Authority of Zimbabwe imposes GMP compliance timelines that filter investor participation. Harare and Mashonaland cultivation clusters are commissioning extraction capacity for regional distribution.
Malawi
Industrial hemp regulatory frameworks and pilot medicinal programs open cultivation licensing to commercial operators. The country's national pharmaceutical regulator tracks cannabinoid content for export-bound output. Lilongwe and Central Region greenhouse developments target pharmaceutical-grade consistency for Southern African supply.
Morocco
Traditional cannabis cultivation regions pivot toward pharmaceutical export channels under evolving regulatory frameworks. The national medicines agency oversees scheduling amendments and GMP certification pathways for processed extracts. Rif Mountain processing cooperatives and Casablanca pharmaceutical corridors are integrating into Mediterranean export networks.
Africa Medical Cannabis Market Key Industry Players
Global extraction technology suppliers compete with regional cultivator-processors across certification and offtake dimensions. Market structure fragments between high-altitude greenhouse operators, GMP-certified extractors, and hospital network procurement consolidators. Three archetypes dominate: vertically integrated cultivator-extractors with captive certification, specialized extraction facility operators, and pharmaceutical distribution intermediaries. Capacity expansion and GMP certification acquisition represent the dominant competitive moves.
Among Lesotho-based high-altitude cultivators, Medigrow Africa exemplifies geographic advantage exploitation for terpene consistency. Within South Africa's extraction tier, Bophelo Biosciences and Wellness occupies a position anchoring domestic supply through Bloemfontein facility infrastructure. On the certification-driven vector, Asterion Cannabis represents GMP-compliant positioning for hospital pharmacy channel access.
| Leading Market Players |
|---|
| Medigrow Africa |
| SANCAP |
| Halo Collective |
| Asterion Cannabis |
| Prohibition Partners |
| Bophelo Biosciences and Wellness |
| Wesgrow Potatoes |
| Louisa Mojela Enterprises |
| Rascal Medicinal Cannabis |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up greenhouse operators in Lesotho and South Africa are consolidating cultivation assets to enforce pricing discipline across pharmaceutical-grade output tiers. Their concentrated ownership patterns compress margin leakage between high-altitude feedstock production and GMP-certified extraction, while SAHPRA compliance timelines limit rapid capacity expansion that could destabilize contract pricing.
Pricing Analysis
Warranty and batch-certification bundling separate hospital pharmacy procurement tiers from spot-market transactions. Pharmaceutical-grade cannabinoid oils command fixed-contract premiums when GMP documentation and analytical validation accompany each shipment, while unbundled raw extracts trade at compressed margins through distributor channels. Price differentiation hinges on SAHPRA certification status and European offtake agreement backing. Cost compression in standard-grade extracts is intensifying because Medigrow Africa and comparable operators are scaling high-altitude greenhouse throughput. Hospital networks in Gauteng province exhibit lowest price sensitivity due to reimbursement coverage, while independent Western Cape pharmacies face acute margin pressure from vertically integrated supplier consolidation.
Supply Chain Analysis
Direct-to-hospital pharmacy channels handle Gauteng and Western Cape demand concentration, bypassing fragmented wholesale layers that dominated early market development. Geographic supply concentration centers on Lesotho's highland districts, South Africa's Free State greenhouse clusters, and emerging Zimbabwean cultivation zones near Harare. Supercritical CO2 extraction equipment, pharmaceutical-grade ethanol, and GMP-certified packaging materials constitute critical input dependencies. Single-source vulnerability runs through European machinery suppliers for extraction automation. Distribution runs through SAHPRA-licensed cultivator-extractors with captive certification rather than independent logistics intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical-grade extraction capacity scarcity props pricing across Southern African hospital networks, with SAHPRA license backlogs preventing rapid supply response to demand expansion in oncology and neurology protocols.
For Market Incumbents: Hedge against European offtake agreement volatility by diversifying GMP certification across multiple regulatory jurisdictions. Secure backward integration into high-altitude greenhouse operations in Lesotho to control terpene consistency for batch validation. Counter emerging Zimbabwean entrants by accelerating Bloemfontein extraction facility automation before Medicines Control Authority of Zimbabwe compliance timelines mature. For New Entrants and Emerging Players: SAHPRA scheduling amendments for cannabinoid reclassification in South Africa open a window for pre-positioned formulation portfolios targeting expanded neurological disorder indications. White-space concentration sits with inhalation device co-development partnerships for Gauteng pain management protocols. Cancer therapy adjunct protocols in Western Cape private hospitals represent the most penetrable segment due to premium pricing tolerance. A go-to-market angle anchored to clinical trial infrastructure collaboration accelerates physician protocol adoption faster than conventional pharmaceutical detailing. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier extraction facility operators in South Africa with partial GMP certification and stranded capacity from delayed SAHPRA approvals. Long-term viability over a decade horizon rests on positioning for post-harmonization regulatory alignment with WHO rescheduling recommendations. The acquisition target archetype combines Lesotho cultivation licenses with South African extraction infrastructure. License backlog clearance rates at SAHPRA signal inflection timing for capacity deployment decisions.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Acquisition | Hospital pharmacy procurement in Gauteng mandates pharmaceutical purity grades for formulary inclusion. |
| High-Altitude Cultivation Expansion | Lesotho's greenhouse zones sustain terpene consistency required for European offtake agreement compliance. |
| Inhalation Device Co-Development | Metered-dose partnerships with pain specialists in Western Cape accelerate protocol adoption beyond oil-based administration. |
| Clinical Trial Infrastructure Partnership | Neurology and oncology therapeutic validation in South Africa compresses product registration timelines for early movers. |
| Track-and-Trace System Investment | Seed-to-sale compliance infrastructure satisfies SAHPRA and Lesotho Medicines Regulatory Authority cross-border requirements. |
Research Approach
SAHPRA scheduling amendment filings, Lesotho Medicines Regulatory Authority export certification records, and South African private hospital procurement databases formed the secondary backbone for market sizing. Primary interviews with GMP compliance officers at extraction facilities, oncology formulary directors in Gauteng hospital networks, and greenhouse operations managers in Lesotho's highland districts validated supply-side assumptions. Bottom-up cultivation capacity estimates and top-down pharmaceutical procurement expenditure analysis were triangulated against WHO cannabis rescheduling documentation.
Bottom-up modeling anchored volume projections to licensed greenhouse square footage and extraction facility throughput capacity across the analysis window. Segmentation dimensions included product form (oils, capsules, tinctures), clinical setting (hospital inpatient, hospital outpatient, community pharmacy), therapeutic target (chronic pain, cancer therapy, neurological disorders), and administration route (oral, inhalation, topical). CAGRs were derived from capacity expansion timelines and regulatory approval velocity. Industry-specific forecast inputs incorporated SAHPRA license backlog clearance rates and European offtake agreement renewal patterns.
Caveats apply where SAHPRA scheduling reclassification momentum or Lesotho export quota revisions could materially shift the outlook. Forecasts reflect assumptions regarding GMP certification pathway stability and supercritical CO2 equipment import cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
CBD Gummies Market
Cannabis/Marijuana
Cannabis Vaporizers Market
Cannabis/Marijuana
US Medical Marijuana Market
Cannabis/Marijuana
CBD-Infused Products Market
Cannabis/Marijuana
Arizona Legal Cannabis Market
Cannabis/Marijuana
North America Legal Marijuana Market
Cannabis/Marijuana
Veterinary CBD Market
Cannabis/Marijuana
Latin America and Caribbean Hemp-Derived Cannabidiol Market
Cannabis/Marijuana
Europe CBD Oil Market
Cannabis/Marijuana
US Minor Cannabinoids Market
Cannabis/Marijuana
North America Hemp-Derived Cannabidiol Market
Cannabis/Marijuana
Asia-Pacific Medical Cannabis Market
Cannabis/Marijuana
CBD Consumer Health Market
Cannabis/Marijuana
Middle East and Africa CBD Patch Market
Cannabis/Marijuana
Europe CBD Patch Market
Cannabis/Marijuana
North America Legal Cannabis Market