
 Hemp Derivatives Market | 2026-2036
Hemp Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Hemp Derivatives Market Outlook
The hemp derivatives supply base is consolidating around a sharp split between premium, certified-organic CBD isolates and commodity-grade hemp seed outputs. Canopy Growth Corporation leverages its controlled-environment cultivation network to dominate high-purity extraction tiers. Ecofibre Ltd anchors the textile-grade fiber segment with proprietary low-THC cultivars developed for industrial scale. Charlotte's Web Holdings differentiates through vertically integrated seed-to-shelf operations that sustain premium pricing in consumer channels.
Hemp derivatives comprise the refined outputs of Cannabis sativa L. plants containing less than 0.3% THC by dry weight, extracted through supercritical CO2 or cold-press methods to yield oils, isolates, proteins, and fibers for industrial and consumer applications. CBD oil retains the highest margin pool among product types due to pharmaceutical-grade certification requirements and concentrated bioactive content. Hemp protein competes directly with pea and soy alternatives in the food and beverage application, where sports nutrition brands drive formulation demand. The cosmetics application is maturing fastest as European REACH compliance costs filter smaller topical brands from the market.
The FDA, USDA, and EMA collectively govern hemp derivative legality through divergent THC thresholds, novel food approvals, and pharmaceutical pathway designations that fragment cross-border trade. USDA organic certification and EFSA novel food status now function as de facto market access gates for premium-tier suppliers. Stakeholders must monitor regulatory harmonization progress between the FDA's pending CBD enforcement framework and EMA's pharmaceutical-grade extraction standards to anticipate which compliance architecture will govern tomorrow's largest addressable markets.
Market Dynamics
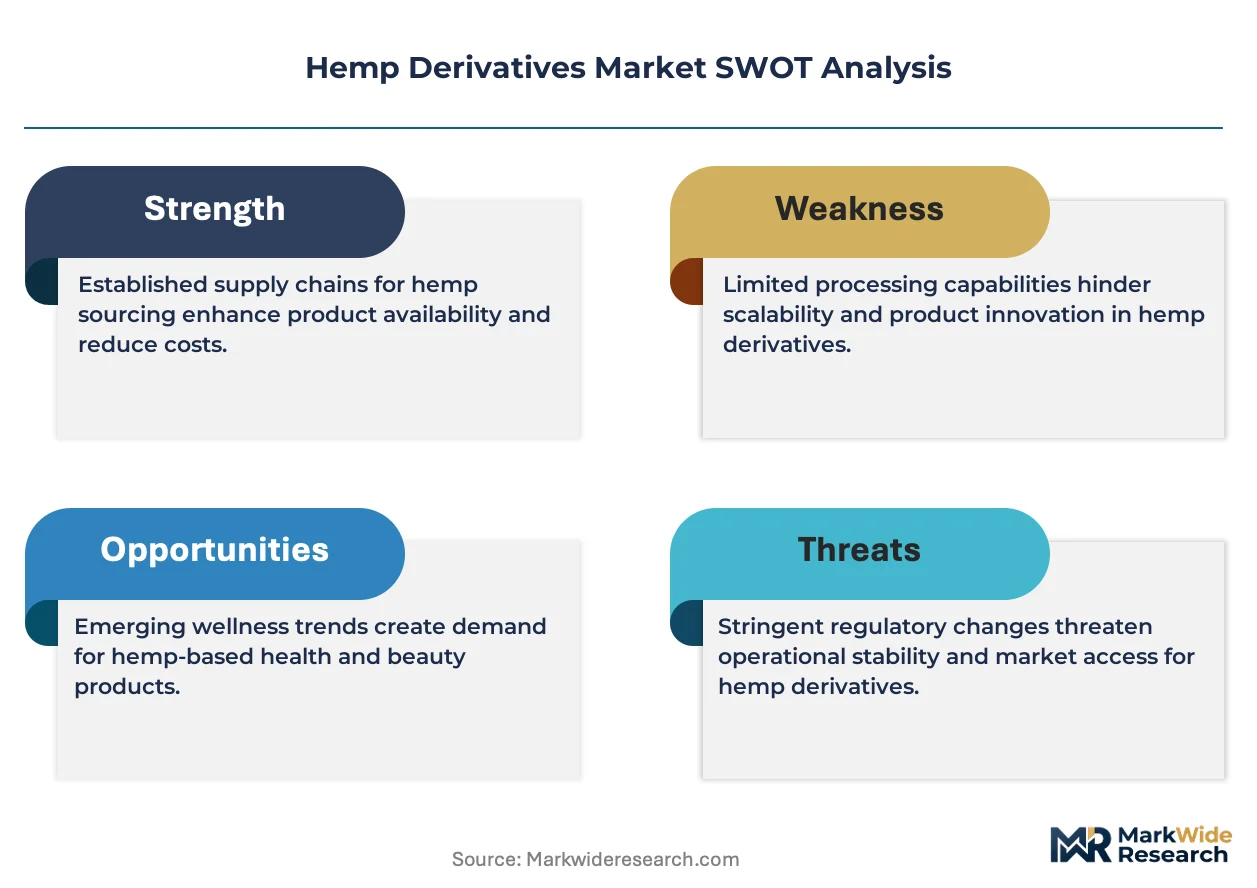
Supercritical CO2 extraction scale-up is compressing batch-to-batch variability, forcing commodity-grade processors to consolidate or exit as pharmaceutical certification costs rise. This technological bifurcation now governs margin distribution across the supply base.
Growth Catalysts
- USDA Organic Certification:Food and beverage manufacturers now require certified-organic CBD isolates for functional product lines, filtering out uncertified suppliers and concentrating procurement among qualified tier-one extractors.
- Sports Nutrition Formulation:Hemp protein displaces pea and soy alternatives in recovery beverages as brands seek complete amino acid profiles and allergen-free positioning for athlete segments.
- Germany:EFSA novel food approvals for hemp-derived ingredients are unlocking shelf space across European retail chains previously blocked by regulatory uncertainty.
Market Restraints
- Input Cost Volatility:Certified-organic hemp biomass commands 40-60% premiums over conventional feedstock, squeezing margin at mid-scale extraction facilities without backward integration into cultivation.
- Regulatory Friction:The FDA's pending CBD enforcement framework creates formulation freeze-outs, forcing CPG brands to delay product launches despite completed R&D cycles.
- Substitution Threat:CBG and CBN isolates from alternative cultivars compete for the same pharmaceutical-grade extraction capacity, fragmenting bioactive demand across minor cannabinoids.
Strategic Opportunities
- Cosmetics Application Expansion:European REACH compliance costs have filtered smaller topical brands, creating white space for certified suppliers with existing toxicology dossiers and safety data packages.
- India:FSSAI novel food consultations for hemp seed derivatives signal impending regulatory opening for protein and oil imports into functional food formulations.
- Textile-Grade Fiber Convergence:Proprietary low-THC cultivars developed for industrial scale enable substitution of cotton and synthetic fibers in automotive and construction composites.
Industry Challenges
- Pharmaceutical-Grade Certification Timeline:EMA extraction standards require 18-24 month validation cycles that outpace product development calendars at mid-cap processors.
- Extraction Talent Scarcity:Supercritical CO2 equipment operation and chromatography purification expertise concentrates among a narrow pool of specialists, inflating compensation at scale-up facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemp Derivatives Market |
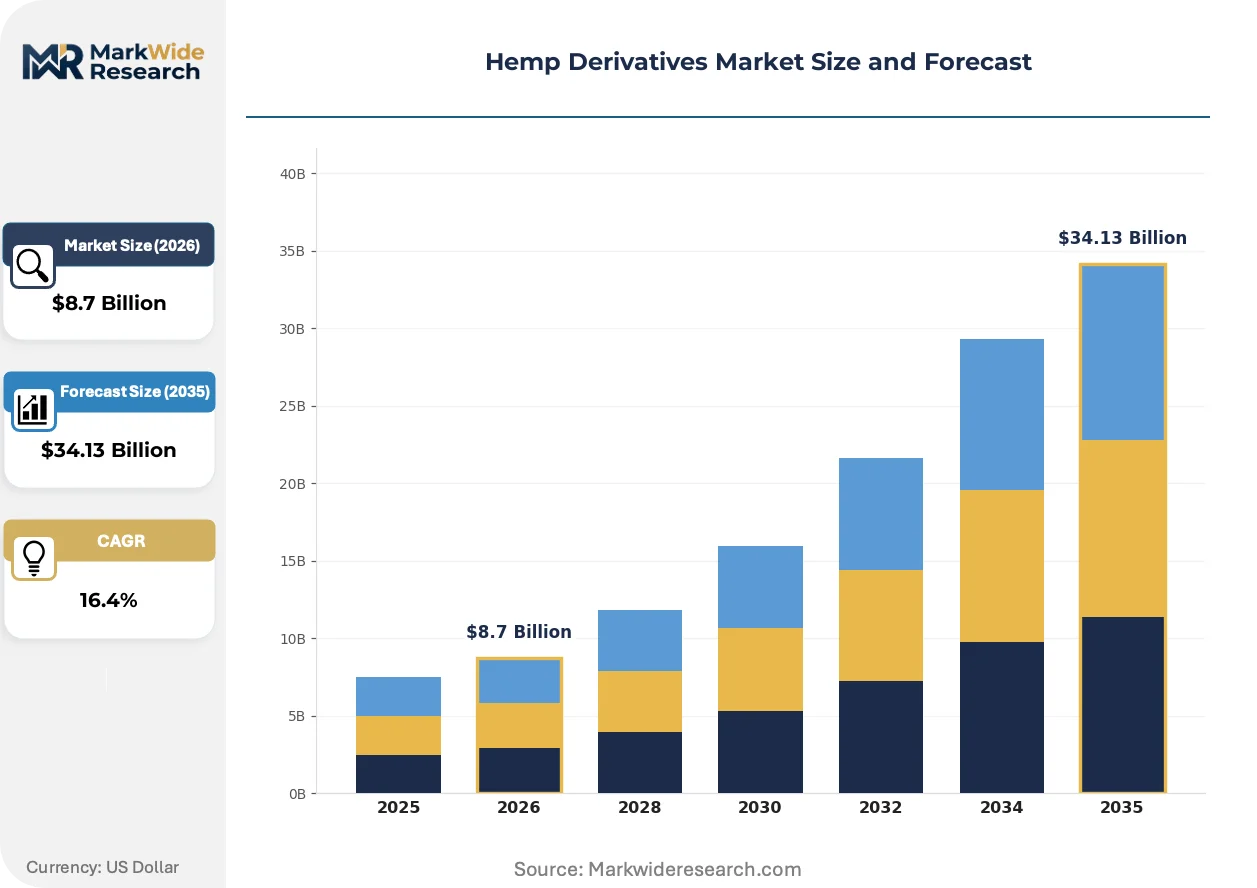
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CBD Oil, CBD Isolate, Hemp Seeds, Hemp Protein Application: Food & Beverage, Cosmetics, Pharmaceuticals, Textiles End User: Consumers, Manufacturers, Retailers, Wholesalers Distribution Channel: Online, Supermarkets, Health Stores, Dispensaries |
| Companies Covered | Canopy Growth Corporation, Aurora Cannabis, Cronos Group, Charlotte's Web Holdings, HempMeds, Green Thumb Industries, Curaleaf Holdings, Ecofibre Ltd, Fresh Hemp Foods Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemp Derivatives Market Strategic Shifts
Decentralized processing infrastructure and automated quality systems are compressing the traditional extractor-brand relationship, enabling direct farm-to-formulator pathways that bypass legacy tolling arrangements.
Supercritical CO2 extraction with inline chromatography refinement is decentralizing high-purity CBD production from centralized pharmaceutical facilities to regional processing hubs. Mid-scale food and beverage manufacturers now source directly from these hubs, bypassing multi-tier distribution. This geographic diffusion is compressing working capital cycles and enabling just-in-time formulation for seasonal product launches.
REACH registration requirements for hemp-derived cosmetics ingredients are forcing toxicology investment decisions before revenue confirmation. European formulators now pre-register active compounds to secure supply continuity, front-loading compliance costs. The cosmetics application segment bears the heaviest burden, with smaller brands exiting rather than funding full substance dossiers.
Certification-driven procurement now governs supplier selection at major CPG houses, replacing price-primary evaluation with organic and pharmaceutical-grade documentation requirements. Third-party audit costs have become table stakes for contract consideration. This shift is most visible in United States sports nutrition channels, where NSF Certified for Sport and Informed Sport logos determine shelf placement.
Hemp Derivatives Market Segmentation
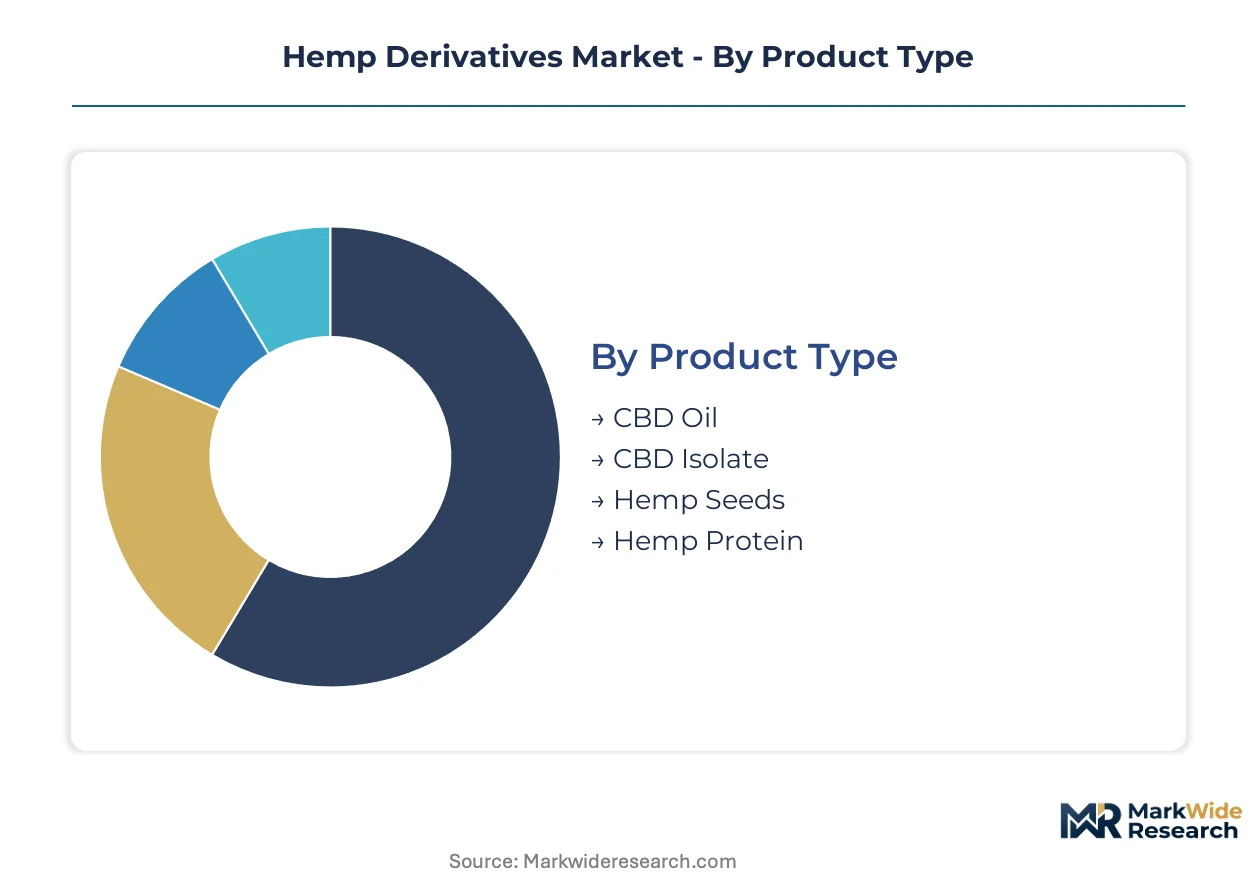
Hemp derivatives fragment across four distinct classification axes, each governing how suppliers configure extraction capacity, certification investments, and channel partnerships. Procurement patterns diverge sharply between pharmaceutical-grade isolates and commodity food inputs, forcing processors to choose margin tiers.
Product Type:
Buyers in this category separate by purity threshold and end-use certification requirements, with pharmaceutical applications demanding COA-documented potency and food applications prioritizing organic credence.
- CBD Oil:Full-spectrum extract retains minor cannabinoids and terpenes through cold-press or CO2 methods, requiring third-party potency verification. Pharmaceutical formulators in the United States concentrate procurement here as FDA enforcement frameworks solidify, though pending regulatory clarity continues to delay formulation commitments.
- CBD Isolate:Crystalline powder achieves 99%+ purity via chromatography refinement, commanding premium positioning in cosmetics and pharmaceutical applications. European REACH pre-registration requirements now filter uncertified suppliers from cosmetics procurement, concentrating contract awards among dossier-ready extractors.
- Hemp Seeds:Hulled or whole seeds deliver omega fatty acid profiles for functional food applications. FSSAI novel food consultations in India signal impending import demand for protein and oil derivatives.
- Hemp Protein:Cold-pressed cake milled into 50% protein concentrate competes with pea and soy in sports nutrition formulations. Allergen-free positioning drives displacement of legacy plant proteins in United States recovery beverage launches.
CBD Oil leads volumes today; CBD Isolate is gaining share fastest.
Application:
Margin concentration tracks regulatory burden intensity, with pharmaceutical pathways requiring 18-24 month validation cycles that commodity food processors bypass entirely.
- Food & Beverage:Functional product lines incorporate hemp protein and CBD isolates for sports nutrition and wellness positioning. NSF Certified for Sport and Informed Sport logos now determine shelf placement at major United States retailers, filtering suppliers without third-party audit documentation.
- Cosmetics:Topical formulations leverage hemp seed oil and CBD for anti-inflammatory positioning. ECHA REACH compliance costs have forced smaller European brands to exit, creating procurement consolidation around dossier-ready suppliers.
- Pharmaceuticals:EMA extraction standards govern pharmaceutical-grade CBD for prescription pathways. Germany anchors European demand as novel food approvals unlock parallel consumer channel access.
- Textiles:Industrial fiber applications substitute hemp for cotton and synthetics in automotive composites and construction materials. Proprietary low-THC cultivars developed for industrial scale enable cost parity with conventional fibers.
Food & Beverage leads volumes today; Cosmetics is expanding most quickly.
End User:
Procurement sophistication separates institutional buyers with technical specification teams from consumer-direct channels where brand narrative dominates purchase decisions.
- Consumers:Direct purchases concentrate in online channels and health stores, with organic certification and third-party testing logos substituting for technical due diligence.
- Manufacturers:Food, beverage, and cosmetics formulators drive bulk procurement of certified-organic isolates and proteins, requiring chain-of-custody documentation from seed to extraction.
- Retailers:United States supermarket and health store chains now mandate USDA organic certification and potency testing for CBD product placement, filtering conventional-grade suppliers.
- Wholesalers:Distribution intermediaries aggregate commodity-grade hemp seed and fiber outputs for industrial buyers, with price-primary evaluation dominating supplier selection.
Manufacturers lead volumes today; Retailers are climbing the fastest.
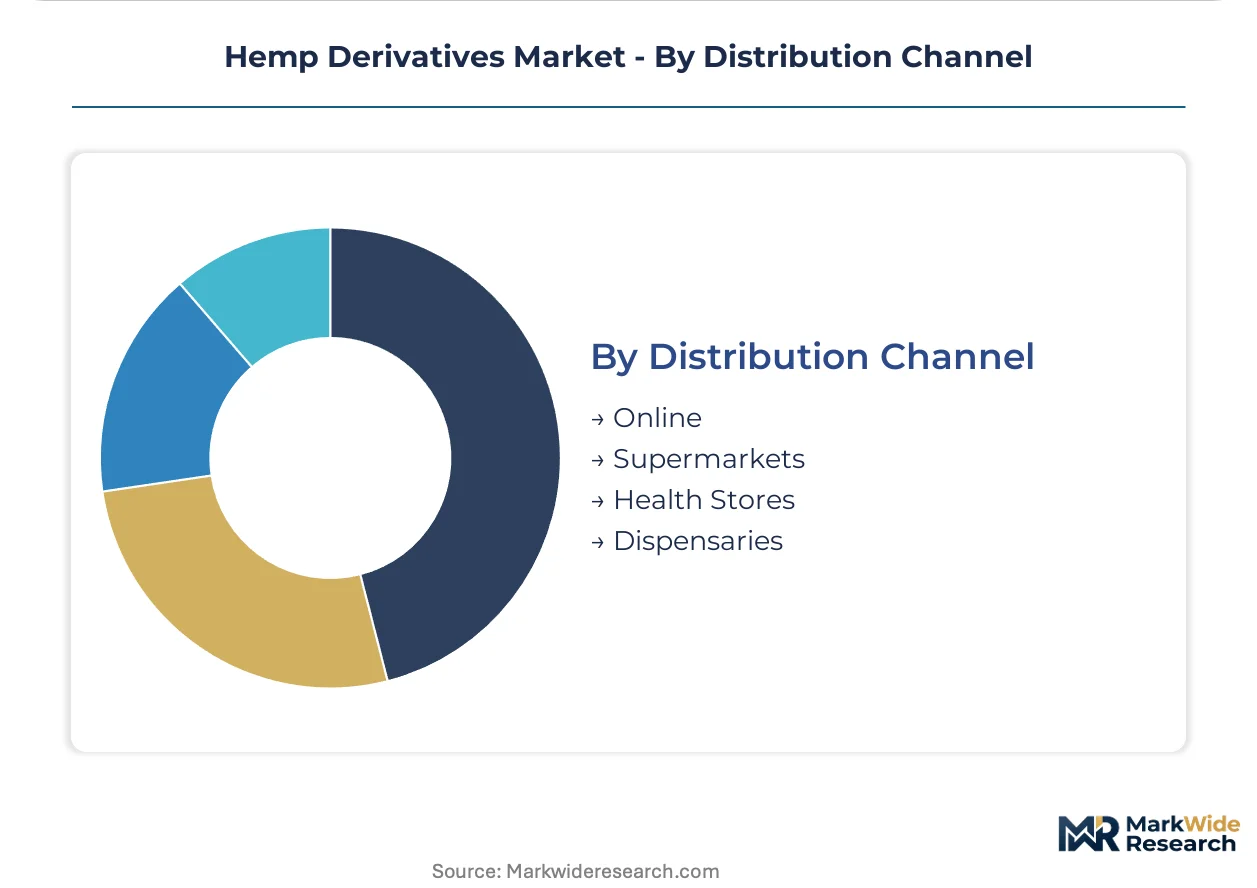
Distribution Channel:
Channel selection reflects buyer urgency and technical confidence, with immediate need favoring physical inspection and specification-heavy procurement favoring direct relationships.
- Online:Direct-to-consumer platforms dominate CBD isolate and oil sales, with third-party lab results and organic certification substituting for physical product evaluation.
- Supermarkets:United States retail chains now stock hemp protein and CBD-infused beverages in functional food aisles, with placement contingent on NSF or Informed Sport certification.
- Health Stores:Specialty retailers concentrate premium CBD oil and isolate SKUs, with staff training on cannabinoid pharmacology differentiating service levels.
- Dispensaries:Licensed cannabis retail channels in United States state markets carry pharmaceutical-grade CBD alongside THC products, with regulatory compliance determining market access.
Online leads volumes today; Supermarkets are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's EFSA novel food approvals are unlocking European retail shelf space faster than the United States can resolve its FDA enforcement uncertainty, creating a transatlantic divergence in formulation timelines.
United States
State-level hemp programs in Colorado, Oregon, and Kentucky are maturing procurement standards for certified-organic CBD isolates. The FDA's pending enforcement framework continues to freeze CPG launch calendars despite completed R&D cycles. Denver and Boulder extraction clusters now supply direct-to-formulator pathways that bypass legacy distribution tiers.
Germany
EFSA novel food approvals for hemp-derived ingredients are concentrating demand among dossier-ready extractors serving pharmaceutical and consumer channels. EMA extraction standards govern prescription-grade CBD validation cycles. The Cologne-Düsseldorf corridor anchors European extraction capacity with REACH-registered suppliers.
India
FSSAI novel food consultations for hemp seed derivatives signal impending import demand for protein and oil formulations. State-level pilot programs in Uttarakhand and Madhya Pradesh are testing controlled cultivation frameworks. Mumbai and Bangalore food manufacturers are pre-qualifying suppliers for functional beverage launches.
Canada
Health Canada licensing frameworks for hemp derivatives are stabilizing export certification pathways to United States and European markets. Prairie province cultivation clusters in Saskatchewan and Manitoba supply organic biomass to extraction facilities. Toronto and Vancouver processing hubs are scaling supercritical CO2 capacity for pharmaceutical-grade output.
United Kingdom
FSA novel food validation requirements are filtering uncertified CBD suppliers from retail channels, concentrating procurement among validated extractors. The Medicines and Healthcare products Regulatory Agency maintains separate pharmaceutical pathways for prescription-grade isolates. London and Manchester formulation labs are driving cosmetics application development with REACH-compliant dossiers.
Hemp Derivatives Market Competitive Environment
Top-tier vendors anchor pharmaceutical-grade extraction tiers, while mid-scale processors compete on organic certification speed and regional distribution reach. The supply base concentrates around three strategic archetypes: vertically integrated seed-to-shelf operators, tolling-focused extraction specialists, and textile-grade fiber cultivators with proprietary genetics. Competitive positioning hardens through backward integration into certified-organic cultivation and pre-emptive toxicology dossier investment for cosmetics channels.
Within the vertically integrated tier, Canopy Growth Corporation and Charlotte's Web Holdings exemplify seed-to-shelf control structures that sustain premium pricing in consumer channels. Ecofibre Ltd occupies a distinct position as an industrial-scale fiber specialist with proprietary low-THC cultivar development. Aurora Cannabis and Cronos Group represent Canadian-licensed operators with export certification infrastructure for multi-jurisdictional supply.
| Leading Market Players |
|---|
| Canopy Growth Corporation |
| Aurora Cannabis |
| Cronos Group |
| Charlotte's Web Holdings |
| HempMeds |
| Green Thumb Industries |
| Curaleaf Holdings |
| Ecofibre Ltd |
| Fresh Hemp Foods Ltd |
| Others |
Value Chain & Pricing Dynamics
Certified-organic versus commodity-grade bifurcation governs both margin capture and supply chain configuration across hemp derivatives. Pharmaceutical-grade CBD isolates command premium positioning through EMA validation and USDA organic certification, while commodity hemp seed outputs compete on volume scale with compressed logistics costs.
Pricing Analysis
Capacity additions in Canada and Germany are reshaping price floors for pharmaceutical-grade CBD isolates as supercritical CO2 extraction scales. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Cost compression in mid-scale extraction tiers intensifies because certified-organic biomass premiums squeeze processors without backward integration into cultivation. Manufacturers with NSF Certified for Sport requirements show least price sensitivity; commodity food processors exhibit highest.
Supply Chain Analysis
Regional distribution centers in Denver, Cologne-Düsseldorf corridor, and Toronto anchor hub-and-spoke patterns for pharmaceutical-grade outputs. Geographic supply concentration centers on the United States, Canada, and Germany for extraction capacity, with India emerging for hemp seed derivatives. Raw material dependencies draw from certified-organic cultivation clusters in Colorado, Saskatchewan, and Uttarakhand. Single-source vulnerability concentrates in supercritical CO2 equipment and chromatography purification expertise. Distribution runs through direct farm-to-formulator pathways that bypass legacy tolling arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in pharmaceutical-grade certification tiers as sports nutrition and cosmetics buyers absorb premium positioning. Supercritical CO2 scale-up and automated quality systems compress cost structures for qualified extractors.
For Market Incumbents: Anticipate regulatory harmonization between FDA and EMA frameworks by pre-positioning toxicology dossiers for cosmetics channels. Secure backward integration into certified-organic cultivation in Colorado and Saskatchewan to defend against input cost volatility. Lock long-term offtake agreements with sports nutrition manufacturers before CBG and CBN isolates fragment bioactive demand.
For New Entrants and Emerging Players: Mid-scale food and beverage manufacturers seeking just-in-time formulation represent underserved buyer archetype with direct sourcing appetite. White space concentrates in regional processing hubs supplying seasonal product launches without multi-tier distribution markup. Target India's FSSAI novel food opening with hemp protein imports for functional beverage launches.
For Investors and Strategic Acquirers: Consolidation pressure builds where pharmaceutical-grade certification timelines outpace capital deployment cycles at mid-cap processors. Long-term viability favors vertically integrated seed-to-shelf operators with captive organic cultivation and REACH-registered cosmetics dossiers. Watch EMA-FDA regulatory harmonization progress as inflection indicator for cross-border premium tier access.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Certification Investment | EMA validation unlocks prescription pathways in Germany and UK markets. |
| Backward Integration into Organic Cultivation | Captive supply of certified-organic biomass insulates margin from feedstock volatility. |
| REACH Pre-Registration for Cosmetics | Toxicology dossiers filter competition from smaller European topical brands. |
| Regional Processing Hub Scale-Up | Supercritical CO2 capacity in Denver and Toronto compresses working capital cycles. |
| Direct Farm-to-Formulator Pathways | Bypassing legacy tolling arrangements captures margin from mid-scale food manufacturers. |
Study Parameters
Coverage spans the United States, Germany, Canada, India, and the United Kingdom, with primary inputs from each jurisdiction combining extraction facility operators, sports nutrition procurement leads, cosmetics formulators, and regulatory affairs specialists. Secondary validation draws from FDA enforcement guidance documents, EFSA novel food approvals, ECHA REACH registrations, and FSSAI consultation papers. Bottom-up capacity modeling and top-down demand triangulation cross-verify volume estimates.
Rate-of-change decomposition isolates product type, application, end user, and distribution channel contributions across the projection horizon. Segmentation dimensions modeled include pharmaceutical versus food-grade certification tiers, supercritical CO2 versus cold-press extraction methods, and regional regulatory cluster variations. CAGRs derive from capacity build-out timelines, certification approval trajectories, and channel penetration curves. Industry-specific inputs include USDA organic certification adoption rates and EMA validation cycle durations.
Underlying measurement precision varies by segment; pharmaceutical-grade isolates with documented COA potency carry tighter precision than emerging cosmetics applications. Forecasts reflect documented assumptions regarding regulatory harmonization progress and certification cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Mexico Hemp CBD Market
Cannabis/Marijuana
Cannabidiol Extract Market
Cannabis/Marijuana
Asia-Pacific Cannabidiol (CBD) Market
Cannabis/Marijuana
US Medical Marijuana Market
Cannabis/Marijuana
North America Cannabidiol (CBD) Market
Cannabis/Marijuana
Cannabis Cultivation Market
Cannabis/Marijuana
CBD Oil Market
Cannabis/Marijuana
North America Medical Cannabis Market
Cannabis/Marijuana
Cannabidiol (CBD) Market
Cannabis/Marijuana
Asia-Pacific Medical Cannabis Market
Cannabis/Marijuana
Germany and Netherlands Medical Marijuana Market
Cannabis/Marijuana
Cannabinoid Therapy Market
Cannabis/Marijuana
Middle East and Africa Cannabidiol (CBD) Market
Cannabis/Marijuana
Latin America and Caribbean Hemp-Derived Cannabidiol Market
Cannabis/Marijuana
Legal Cannabis Market
Cannabis/Marijuana
North America Hemp-Derived Cannabidiol Market