
 North America Legal Cannabis Market | 2026-2036
North America Legal Cannabis Market Size, Share, and Industry Trends Forecast 2026-2036
North America Legal Cannabis Market Intelligence
Dispensary networks across the United States and Canada are reshaping how legal cannabis reaches end consumers, with multi-state operators building vertically integrated footprints from cultivation to retail. Curaleaf Holdings leverages its coast-to-coast dispensary presence to sustain market penetration in high-population states. Green Thumb Industries anchors its position through controlled retail brands that compete on product consistency and consumer education.
Legal cannabis comprises dried flower, concentrated extracts, infused edibles, and topical formulations containing cannabinoids such as THC and CBD, produced through controlled-environment agriculture, hydrocarbon or CO2 extraction, and precision dosing for therapeutic or recreational use. Flower retains the largest revenue share among product types, though concentrates capture expanding margin pools as extraction technology improves yield and purity. Dispensary channels dominate volume, while online sales face structural constraints from interstate shipping prohibitions that limit geographic scaling.
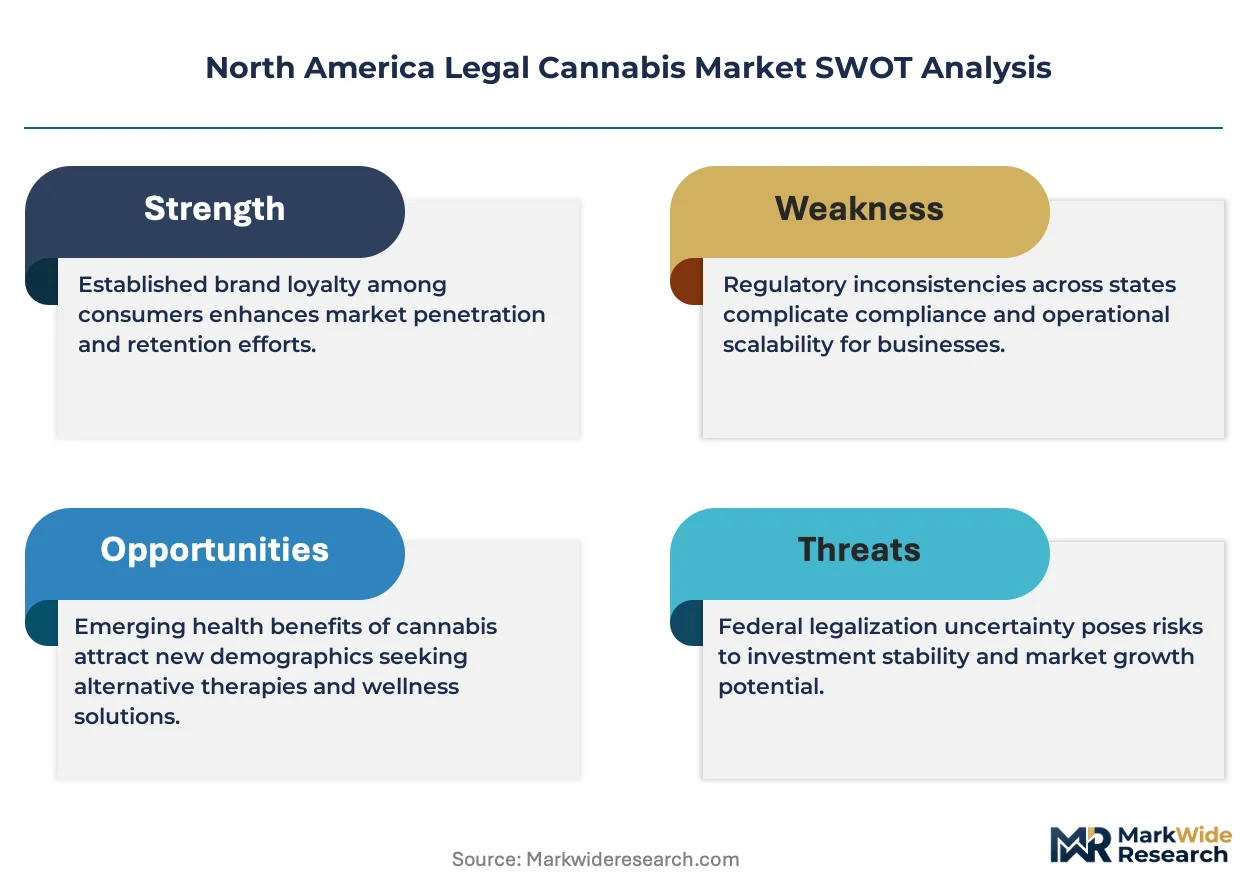
The FDA maintains oversight of cannabis-derived pharmaceuticals and health claims, while individual state regulators including California's Department of Cannabis Control and Canada's Health Canada set operational licensing, testing, and packaging standards that determine market access. Compliance with divergent state-level THC limits, pesticide testing protocols, and track-and-trace systems elevates operational complexity for multi-jurisdiction operators. Stakeholders must monitor pending federal rescheduling decisions and corresponding banking reform legislation that would fundamentally alter capital access and interstate commerce feasibility.
Market Dynamics
Federal rescheduling deliberations are compressing capital timelines for North American operators, forcing balance sheet restructuring before any statutory change materializes. State-level THC testing variance between California and Florida laboratories creates invisible trade barriers that fragment procurement.
Growth Catalysts
- Medical patient enrollment:Chronic pain management protocols in Florida and Colorado are expanding qualifying condition lists faster than recreational frameworks mature.
- Extraction technology yield improvements:CO2 and hydrocarbon systems are capturing cannabinoid fractions previously lost to biomass waste, tightening unit economics for concentrate producers.
- Health Canada's regulatory clarity:Federal licensing pathways for novel cannabinoid formats reduce market access uncertainty compared to the US state-by-state patchwork.
Market Restraints
- 280E tax code exposure:IRS disallowance of ordinary business deductions for plant-touching operators inflates effective tax rates above standard corporate levels.
- Input cost volatility:HVAC and lighting energy inputs for controlled-environment agriculture fluctuate with regional electricity grid pricing, squeezing margin at cultivation stage.
- Interstate commerce prohibition:The US Controlled Substances Act blocks cross-border product flows, trapping inventory within state boundaries and amplifying localized oversupply risk.
Strategic Opportunities
- Canadian derivative formats:Beverage and topical categories remain underdeveloped relative to flower and oil penetration, offering white space for formulation innovation.
- SAFER Banking Act passage:Federal deposit insurance access would normalize lending terms and reduce cash-handling security costs for retail operators.
- Precision dosing technology:Nanotechnology and encapsulation convergence is enabling onset-time compression that rivals inhalation for medical users seeking discretion.
Industry Challenges
- Compliance talent scarcity:Multi-jurisdiction operators struggle to hire professionals fluent in California's METRC track-and-trace system, Health Canada's CTLS portal, and emerging state frameworks simultaneously.
- Legacy ERP integration:Seed-to-sale software mandates clash with established agricultural management systems, forcing expensive middleware development or full platform replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Legal Cannabis Market |
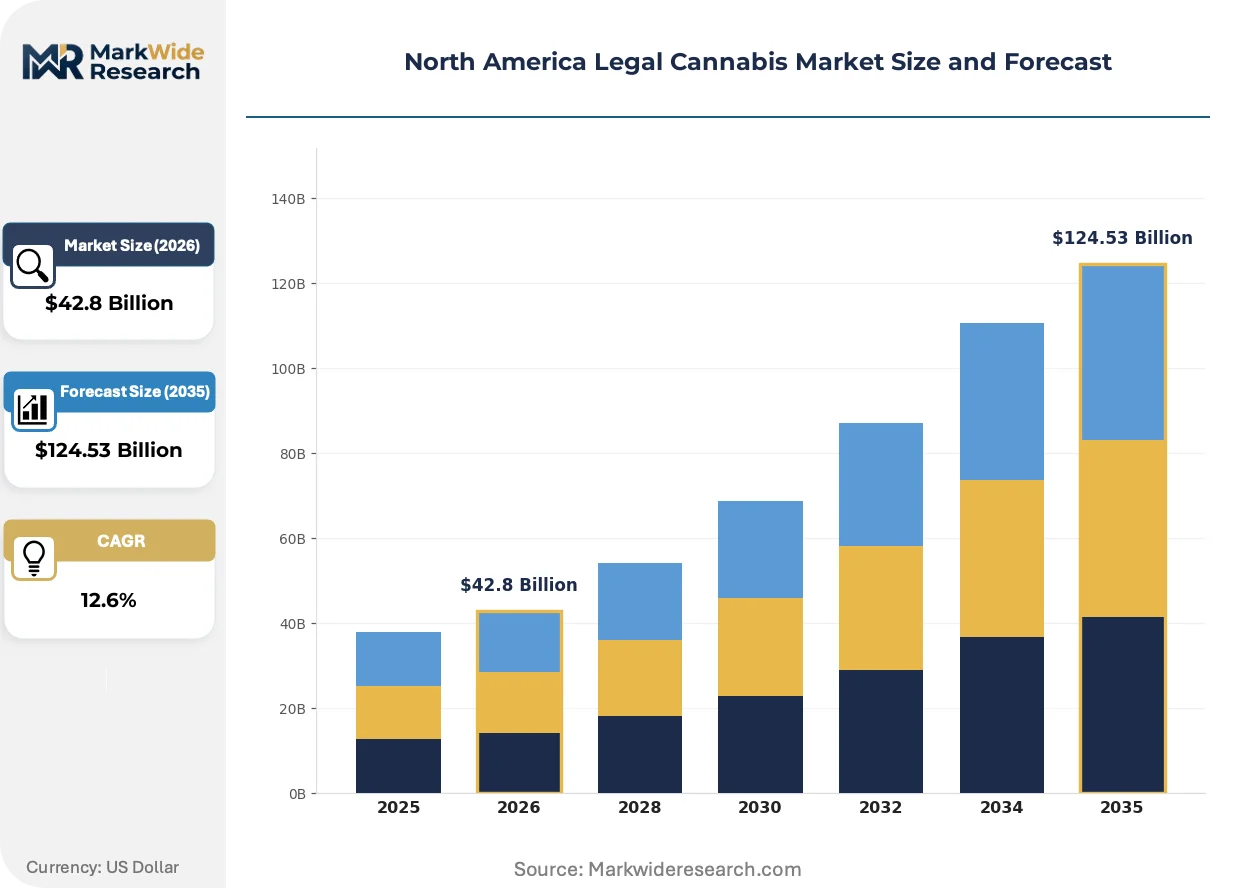
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $124.53 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
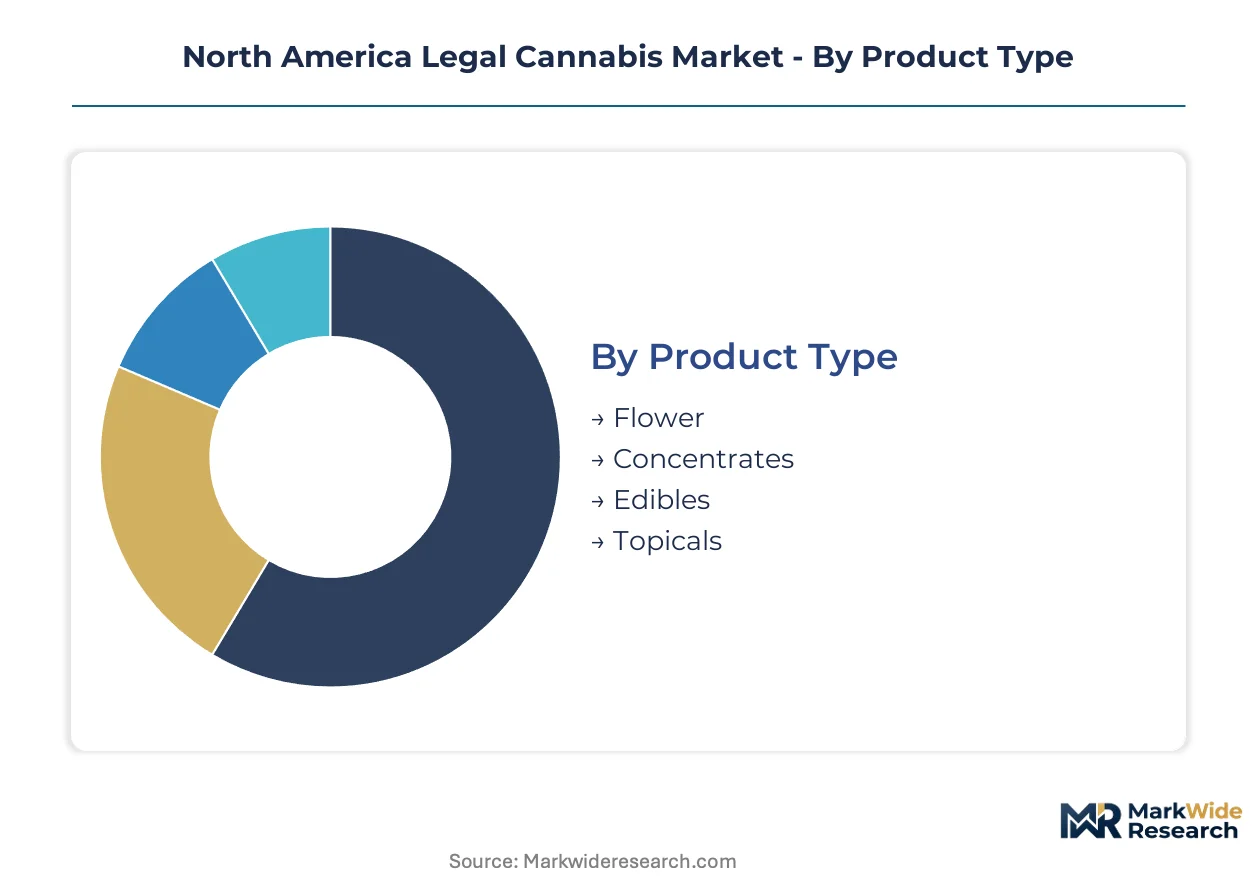
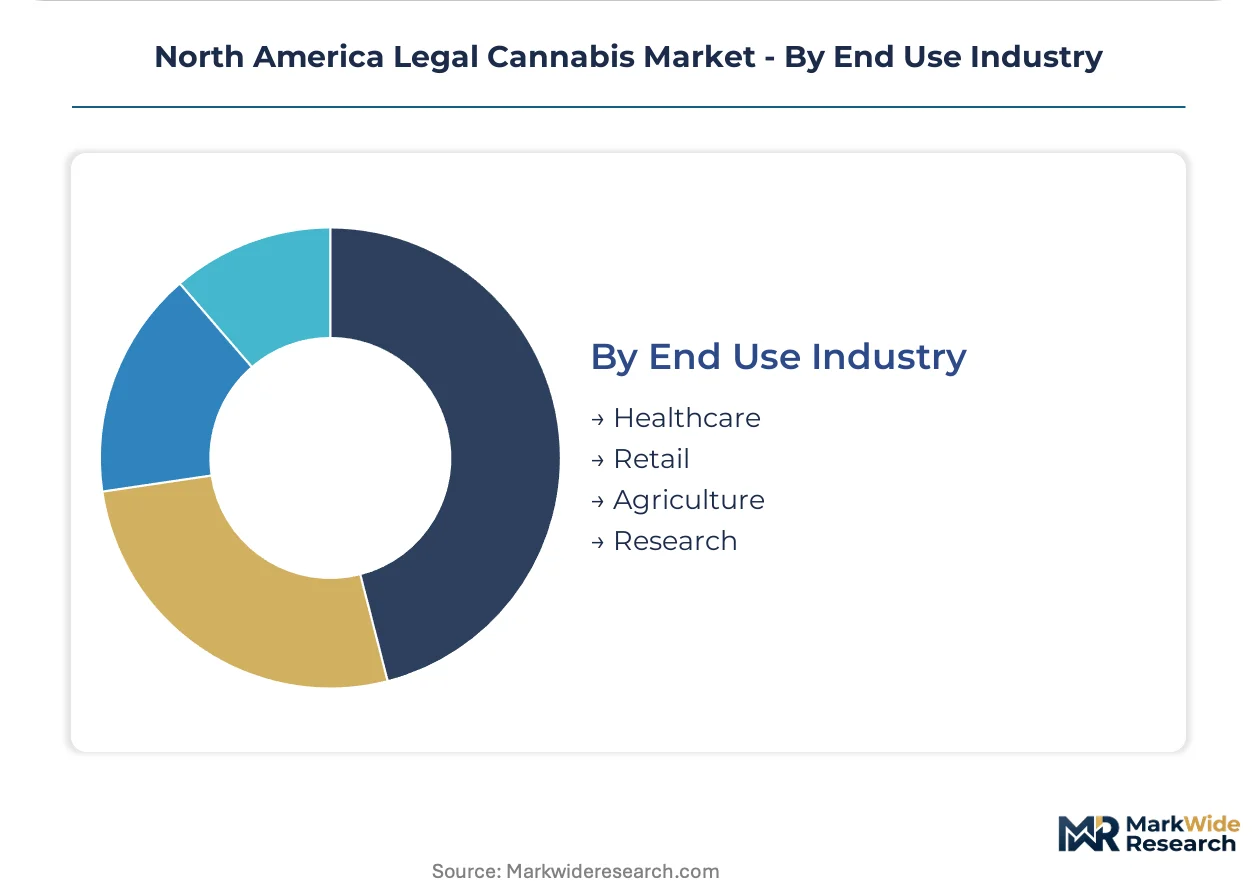
| Segmentation | Product Type: Flower, Concentrates, Edibles, Topicals Distribution Channel: Retail Stores, Online Sales, Dispensaries, Pharmacies Customer Type: Recreational Users, Medical Patients, Caregivers, Wholesale Buyers End Use Industry: Healthcare, Retail, Agriculture, Research |
| Companies Covered | Curaleaf Holdings, Inc., Green Thumb Industries, Trulieve Cannabis Corp., Tilray Brands, Verano Holdings Corp., Cresco Labs, Canopy Growth Corporation, Aurora Cannabis Inc., Charlotte’s Web, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Legal Cannabis Market Strategic Shifts & Innovations
Product format diversification and regulatory technology investment are bifurcating competitive advantage between extraction-science specialists and retail-distribution scale players.
Blockchain-enabled track-and-trace infrastructure is virtualizing compliance documentation across cultivation, processing, and retail tiers. California's Department of Cannabis Control and Health Canada are mandating real-time inventory visibility that paper-based systems cannot satisfy. Multi-state operators adopting distributed ledger architecture are compressing audit response times from weeks to hours while reducing manual reconciliation headcount.
The FDA's stance on CBD as a drug ingredient under the Food, Drug, and Cosmetic Act is forcing product developers toward hemp-derived isomers with ambiguous regulatory status. This policy friction is diverting R&D investment from CBD beverages toward minor cannabinoid exploration including CBN and CBG. Canadian operators with explicit Health Canada authorization for novel cannabinoids are capturing shelf space that US competitors forfeit to enforcement uncertainty.
Medical patients are consolidating purchase volume around licensed producers with consistent cannabinoid certificates of analysis, displacing legacy gray-market relationships. Dispensary loyalty programs in Colorado and Florida are capturing this behavioral shift through subscription-style fulfillment that guarantees strain availability. This pattern concentrates procurement power with vertically integrated operators capable of captive supply chain control across flower and derivative categories.
North America Legal Cannabis Market Segmentation
Segmentation in the North America Legal Cannabis Market exposes how regulatory fragmentation and consumer preference divergence create distinct commercial battlegrounds. Product format, channel access, and patient versus recreational demand each command separate operational capabilities and compliance frameworks.
Product Type:
Use cases span from immediate symptom relief through inhalation to extended-duration therapeutic effects via ingestion or topical application.
- Flower:Dried cannabis bud containing full-spectrum cannabinoid and terpene profiles, typically consumed through combustion or vaporization. Demand concentrates in California and Colorado legacy markets where established consumers prioritize strain-specific effects and ritual familiarity over format innovation.
- Concentrates:Extracted oils, waxes, and shatter produced through hydrocarbon or CO2 processing, delivering elevated THC potency in reduced volume. Medical patients in Florida chronic pain management programs favor concentrates for precise dosing control and rapid onset, though extraction technology capital requirements limit producer participation.
- Edibles:Infused food and beverage products with delayed onset and extended duration effects.
- Topicals:Transdermal creams and balms targeting localized inflammation without psychoactive absorption.
Established volume favors Flower; emerging adoption favors Concentrates.
Distribution Channel:
Channel economics vary sharply by capital intensity, with physical retail demanding real estate investment while digital faces federal shipping prohibitions.
- Dispensaries:Licensed retail storefronts with mandatory seed-to-sale tracking and on-site product verification. California's Department of Cannabis Control and Colorado's Marijuana Enforcement Division maintain divergent operational requirements that fragment multi-state operator systems.
- Retail Stores:General merchandise retailers in Canadian provinces where provincial liquor boards or private operators distribute recreational cannabis.
- Online Sales:E-commerce platforms constrained by US interstate commerce prohibition under the Controlled Substances Act, limiting geographic scaling to within-state fulfillment where permitted.
- Pharmacies:Healthcare-integrated dispensing for medical patients with physician authorization, concentrated in Canadian markets with Health Canada federal licensing clarity.
Dispensaries anchor current revenue; pharmacy integration offers the steepest expansion trajectory pending federal rescheduling.
Customer Type:
Customer economics separate by purchase frequency, basket size, and documentation burden for medical qualification.
- Medical Patients:State-registered consumers with qualifying conditions accessing tax-advantaged or higher-potency products. Florida's expanding chronic pain protocols and Colorado's mature medical framework concentrate enrollment growth.
- Recreational Users:Adult-use consumers in jurisdictions with legalized non-medical access, driving volume in California and Canadian provincial markets.
- Caregivers:Designated purchasers for homebound or minor patients, concentrated in medical-only state frameworks.
- Wholesale Buyers:Dispensary and retail procurement agents purchasing bulk inventory from licensed producers.
Recreational volume dominates transaction counts; medical patients deliver superior per-customer lifetime value through subscription-style fulfillment.
End Use Industry:
Industry application determines regulatory oversight intensity, with healthcare-facing segments subject to FDA pharmaceutical standards.
- Healthcare:Clinical and therapeutic applications spanning pain management, epilepsy, and oncology support. FDA oversight of cannabis-derived pharmaceuticals creates compliance barriers that Health Canada-authorized Canadian operators navigate more predictably.
- Retail:Consumer-facing recreational and wellness product distribution through licensed channels.
- Agriculture:Cultivation inputs, genetics licensing, and controlled-environment technology supply.
- Research:Academic and clinical investigation into cannabinoid pharmacology, constrained by US Schedule I access restrictions that Canadian federal legality bypasses.
Retail commands present revenue concentration; healthcare applications are gaining share fastest as medical enrollment protocols expand qualifying conditions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The I-5 corridor freight network and Port of Vancouver container throughput anchor North American cannabis distribution infrastructure, while cross-border pipeline capacity for ancillary equipment sustains integrated supply chains between cultivation clusters and processing centers.
United States
California's Department of Cannabis Control and Colorado's Marijuana Enforcement Division administer divergent testing protocols that fragment multi-state operator compliance systems. The IRS enforces Section 280E disallowance of ordinary business deductions, inflating effective tax rates for plant-touching enterprises. Los Angeles and Denver anchor cultivation and retail density, with Southern California's Santa Barbara County concentrating greenhouse operations serving both medical and recreational channels.
Canada
Health Canada's Cannabis Tracking and Licensing System provides federal regulatory clarity that reduces market access uncertainty relative to the US state patchwork. The Cannabis Act mandates real-time inventory visibility through the CTLS portal, compressing audit response timelines for licensed producers. Ontario and Alberta concentrate retail distribution through provincially regulated channels, with British Columbia's Okanagan Valley hosting legacy cultivation expertise now transitioning to licensed operations.
Mexico
The Supreme Court's 2021 decriminalization ruling and pending federal regulatory framework are creating preparatory investment corridors for medical cannabis infrastructure. The country's national pharmaceutical regulator oversees pilot programs for cannabinoid-derived therapeutics. Baja California and Jalisco are emerging as preliminary cultivation zones, with Guadalajara's pharmaceutical manufacturing base offering extraction technology transfer potential.
Florida
The state's Office of Medical Marijuana Use administers a vertically integrated licensing structure that limits market entry to 22 approved operators. Chronic pain management protocol expansions are accelerating patient enrollment beyond initial qualifying conditions. Miami-Dade and Orange County concentrate dispensing locations, with the Gulf Coast corridor emerging as greenhouse construction territory serving the state's no-smoke product mandate.
Illinois
The Department of Financial and Professional Regulation oversees a dual medical-adult-use framework with social equity licensing provisions. Tax revenue allocation to community reinvestment funds creates localized political durability for the legal market. Chicago anchors retail density and corporate headquarters concentration, while downstate cultivation zones leverage agricultural land availability for outdoor and greenhouse production.
North America Legal Cannabis Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying extraction technology, cultivation infrastructure, and compliance software to licensed operators. The North American legal cannabis market exhibits tiered consolidation, with multi-state operators capturing retail scale while regional cultivators retain flower supply leverage. Three archetypes dominate: vertically integrated dispensary networks, extraction-science specialists, and brand-focused product houses. Competitive intensity centers on M&A-driven geographic expansion and captive supply chain control over cultivation capacity.
Within the multi-state operator tier, Curaleaf Holdings, Green Thumb Industries, and Trulieve Cannabis Corp. exemplify platform-scale positioning across divergent state regulatory environments. These entities occupy positions that require simultaneous fluency in California's METRC track-and-trace infrastructure, Florida's vertical integration mandates, and Health Canada's CTLS compliance architecture. Their market presence anchors industry commentary on capital access constraints, federal rescheduling preparation, and the operational complexity of serving both medical patient enrollment protocols and recreational consumer demand patterns.
| Leading Market Players |
|---|
| Curaleaf Holdings, Inc. |
| Green Thumb Industries |
| Trulieve Cannabis Corp. |
| Tilray Brands |
| Verano Holdings Corp. |
| Cresco Labs |
| Canopy Growth Corporation |
| Aurora Cannabis Inc. |
| Charlotte's Web, Inc. |
| Others |
Cost & Logistics Intelligence
The I-5 corridor freight network's diesel and labor cost dynamics compress margin for California cultivators supplying Midwest and Northeast dispensaries, amplifying price differentiation between coastal greenhouse operations and inland warehouse conversion facilities while rewarding operators with captive distribution infrastructure.
Pricing Analysis
Volume-discount tiering structures separate medical patient subscription programs from recreational single-unit transactions, with Florida's vertically integrated operators capturing price premiums through guaranteed strain availability. Certification grade under Health Canada's CTLS portal and California's METRC compliance status drive price differentiation between licensed and provisional operators. Pricing pressure stems from 280E tax code exposure inflating effective rates for plant-touching enterprises. Medical patients exhibit lowest price sensitivity due to insurance-adjacent reimbursement frameworks, while recreational consumers in mature markets like Colorado demonstrate acute responsiveness to promotional depth.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for LED grow light and climate control equipment imports essential to controlled-environment agriculture. Cultivation inputs concentrate in Canada, California, and Colorado, with extraction technology fabrication anchored in Germany and the United States. Raw material dependencies include pharmaceutical-grade ethanol, stainless steel bioreactors, and specialized HVAC components. Interstate commerce prohibition under the US Controlled Substances Act fragments distribution into state-siloed fulfillment networks requiring redundant inventory positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where licensing scarcity and compliance architecture create switching costs that protect incumbent position against price-based competition.
For Market Incumbents: Pre-empt margin compression by securing captive supply through backward integration into greenhouse construction in Florida's Gulf Coast corridor and extraction technology licensing in Canada. State-level THC testing variance between California and Florida laboratories threatens operational efficiency; METRC and CTLS system fluency remains the priority capability for multi-jurisdiction defense. For New Entrants and Emerging Players: Build out white-space presence in Canadian beverage and topical categories where Health Canada's derivative format clarity reduces regulatory friction compared to US FDA uncertainty. Mexico's pending federal framework offers the most penetrable geography for medical infrastructure pre-positioning. Physician education partnerships represent the critical go-to-market angle for medical patient enrollment acceleration. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agribusiness conglomerates with underutilized greenhouse assets applicable to cannabis conversion. Long-term viability hinges on federal rescheduling normalization within a decade. The signal to watch is SAFER Banking Act legislative momentum as the inflection indicator for capital access transformation.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Technology Investment | Blockchain-enabled METRC and CTLS integration compresses audit response timelines from weeks to hours for multi-state operators. |
| Extraction Technology Yield Enhancement | CO2 and hydrocarbon system upgrades capture cannabinoid fractions previously lost to biomass waste, tightening unit economics. |
| Medical Patient Enrollment Expansion | Chronic pain protocol advocacy in Florida and Colorado accelerates qualifying condition list growth faster than recreational frameworks mature. |
| Precision Dosing Formulation Development | Nanotechnology and encapsulation convergence enables onset-time compression rivaling inhalation for medical users seeking discretion. |
| Cross-Border Equipment Supply Agreement | Canadian ancillary equipment manufacturers leverage Health Canada regulatory clarity to serve US operators facing FDA uncertainty. |
Research Approach
The analysis maps cultivation operations, extraction processing, dispensary retail, and pharmaceutical distribution channels, each validated through interviews with licensed producer compliance officers, state regulator track-and-trace administrators, dispensary procurement managers, and medical patient advocacy organization directors. Secondary validation draws from Health Canada CTLS disclosure filings, California Department of Cannabis Control enforcement reports, FDA cannabis-derived pharmaceutical guidance documents, and state-level tax revenue allocation disclosures. Bottom-up facility capacity modeling and top-down consumer expenditure estimates were triangulated against operating data.
Assumptions held fixed include state-level legalization trajectories and federal Schedule I classification status, while variables tested encompass federal rescheduling timing, SAFER Banking Act passage probability, and medical patient enrollment elasticity. Segmentation dimensions modeled span product format, distribution channel, customer type, and end-use industry across the projection horizon. CAGRs were derived from historical volume trajectories and regulatory event probability weighting. Industry-specific inputs include electricity grid pricing volatility for cultivation cost modeling and state-by-state testing protocol divergence for compliance burden estimation.
Stress conditions across federal rescheduling acceleration, interstate commerce prohibition repeal, and 280E tax code reform were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and acknowledge that FDA pharmaceutical pathway clarity or Health Canada regulatory revision could materially revise projections. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
CBD Infused Cosmetics Market
Cannabis/Marijuana
Legal Marijuana Market
Cannabis/Marijuana
Cannabinoid CB2 Products Market
Cannabis/Marijuana
North America Legal Marijuana Market
Cannabis/Marijuana
Cannabinoid Therapy Market
Cannabis/Marijuana
Trichome Separator/Extractor Market
Cannabis/Marijuana
Biometric Cannabis Storage Boxes Market
Cannabis/Marijuana
Electric Cannabis Grinders Market
Cannabis/Marijuana
Flavored CBD Powder Market
Cannabis/Marijuana
Cannabis Edibles Market
Cannabis/Marijuana
Middle East and Africa CBD Patch Market
Cannabis/Marijuana
Europe Cannabidiol (CBD) Market
Cannabis/Marijuana
Australia Medicinal Cannabis Testing Market
Cannabis/Marijuana
Mexico Medical Cannabis Market
Cannabis/Marijuana
Medical Marijuana Market
Cannabis/Marijuana
Arizona Legal Cannabis Market