
 Handheld Marijuana Vaporizer Market | 2026-2036
Handheld Marijuana Vaporizer Market Size, Share, and Industry Trends Forecast 2026-2036
Handheld Marijuana Vaporizer Market Analysis
Multi-source component procurement is shifting toward vertically integrated supply chains as manufacturers seek tighter quality control over heating elements and battery systems. PAX Labs leverages its in-house firmware development to sustain premium positioning across licensed dispensary channels. Storz & Bickel anchors European market presence through precision-engineered convection systems manufactured at its German facility. DaVinci Vaporizer differentiates via advanced temperature control algorithms that compete on consistency metrics.
A handheld marijuana vaporizer is a portable, battery-powered thermal extraction device engineered to heat cannabis flower or concentrate to precise temperatures—typically between 350°F and 430°F—without combustion, producing an inhalable aerosol rich in cannabinoids and terpenes while minimizing pyrolytic byproducts. The device serves both medical patients requiring dose-standardized therapy and recreational consumers prioritizing respiratory harm reduction over traditional smoking methods. Dry herb vaporizers command established margin pools among wellness enthusiasts seeking whole-plant formulations, while concentrate vaporizers and cartridge vape pens capture accelerating demand from recreational users valuing potency precision and operational discretion. Convection heating technology leads in premium positioning due to superior flavor preservation, though hybrid heating systems gain traction by balancing efficiency with thermal response speed.
The FDA maintains oversight of cannabis-adjacent device marketing claims under the Federal Food, Drug, and Cosmetic Act, while individual state cannabis regulatory frameworks—such as California's Bureau of Cannabis Control licensing requirements—dictate distribution legality and product testing mandates that directly determine market access geography. The EPA's evolving battery disposal regulations and OSHA workplace safety standards for lithium-ion handling add compliance layers affecting manufacturing location decisions and end-of-life program design. Stakeholders must monitor the interplay between federal scheduling reconsideration and state-level social equity licensing programs, as this tension will determine whether emerging manufacturers gain distribution footholds or incumbent channel control tightens further.
Market Dynamics
California's Bureau of Cannabis Control licensing requirements and the FDA's evolving stance on cannabis-derived products are compressing distribution timelines while fragmenting compliance obligations across state borders. Manufacturers now face divergent testing mandates that reshape production location decisions and channel access strategies.
Growth Catalysts
- Medical patient protocols:Clinical cannabis therapies gain legitimacy across jurisdictions, expanding device demand from dose-standardized therapy requirements. Hospital procurement channels in Germany and Israel now include vaporizer specifications.
- REACH compliance alignment:European manufacturers adapting heating element materials to meet chemical safety standards gain preferential access to EU dispensary networks. RoHS-compliant battery systems unlock cross-border distribution.
- Convection technology maturation:Precision temperature control algorithms reduce thermal degradation of cannabinoids, attracting wellness enthusiasts seeking whole-plant formulations without combustion byproducts.
Market Restraints
- Lithium-ion supply concentration:Battery cell production clusters in East Asia create single-source vulnerability for portable device manufacturers. EPA disposal regulations add end-of-life compliance costs.
- Federal-state scheduling misalignment:US cannabis classification restricts interstate banking services for device distributors. Financial institutions avoid accounts tied to plant-touching commerce.
- Combustion substitution persistence:Traditional smoking methods retain cost and cultural advantages in price-sensitive recreational segments. Pre-roll products capture convenience-oriented buyers.
Strategic Opportunities
- Social equity licensing windows:California and New York reserve dispensary licenses for historically impacted communities, creating first-mover access for emerging manufacturers without incumbent channel relationships.
- Cartridge standardization convergence:510-thread battery interfaces and CCELL ceramic heating cores enable interoperability across oil formulations, reducing consumer switching costs and brand lock-in.
- OSHA workplace safety integration:Corporate wellness programs in Canada and Uruguay explore vaporizer allowances as smoking cessation tools, opening B2B procurement channels outside traditional retail.
Industry Challenges
- Firmware validation timelines:FDA software-as-medical-device scrutiny extends product launch cycles for temperature control algorithms. Validation documentation requirements strain engineering resources.
- Heating element material sourcing:Ceramic and zirconia supply chains lack qualified secondary suppliers, forcing manufacturers to hold excess inventory against disruption risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handheld Marijuana Vaporizer Market |
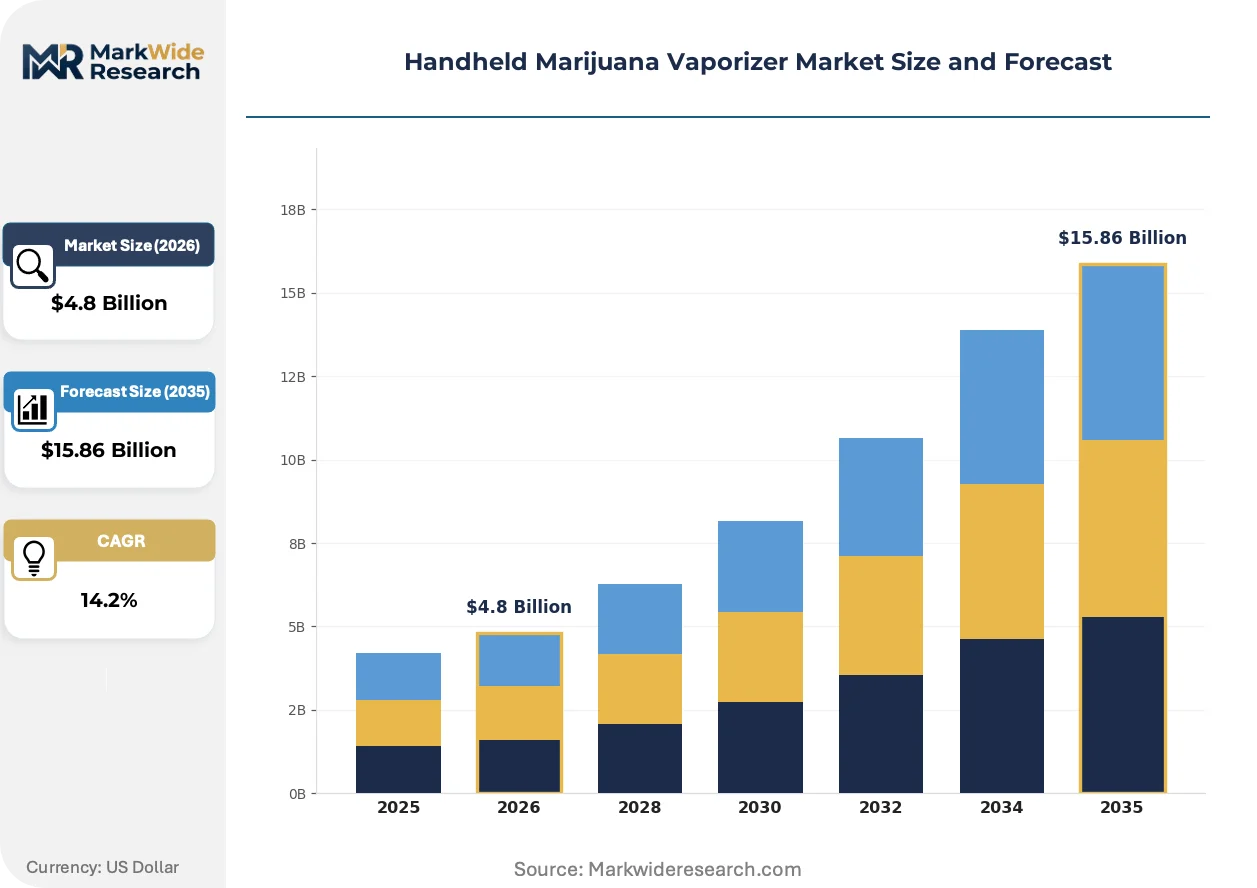
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Herb Vaporizer, Concentrate Vaporizer, Cartridge Vape Pen, Disposable Vape, Refillable Vape Technology: Conduction Heating, Convection Heating, Hybrid Heating, Induction Heating, Vapor Path Material End User: Medical Patients, Recreational Users, Wellness Enthusiasts, Specialty Dispensaries, Vape Lounges Distribution Channel: Online Retailers, Specialty Stores, Licensed Dispensaries, Vape Shops, Direct Manufacturer Sales |
| Companies Covered | PAX Labs, Storz & Bickel, DaVinci Vaporizer, Arizer, Boundless Technology, Grenco Science, KandyPens, Firefly Vapor, Dr. Dabber, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handheld Marijuana Vaporizer Market Emerging Trajectories
Device architecture is bifurcating between medical-grade precision systems and recreational-oriented convenience formats. This divergence compresses development cycles while fragmenting R&D investment priorities across incompatible technical roadmaps.
Hybrid heating systems combining conductive base plates with convection airflow channels are expanding into premium device tiers previously dominated by pure convection designs. Medical patients in Germany and wellness consumers in Colorado adopt these configurations for their balance of thermal efficiency and flavor preservation. The technology is expanding into mid-market price bands as manufacturing scale reduces component costs.
EMA guidance on cannabis-derived medicinal products is harmonizing quality standards across EU member states, forcing manufacturers to adopt GMP-aligned production documentation. Device makers serving pharmaceutical channels must now validate cleaning protocols and material biocompatibility. German and Dutch medical distributors require batch-level traceability that recreational channels ignore.
Wellness-oriented buyers now demand third-party lab results for heavy metals and residual solvents, treating vaporizer hardware as an extension of product safety. Dispensary buyers in California and Colorado prioritize devices with published materials certifications over unverified competitors. This certification-driven preference shift favors established manufacturers with documented supply chain controls over new market entrants.
Handheld Marijuana Vaporizer Market Segmentation
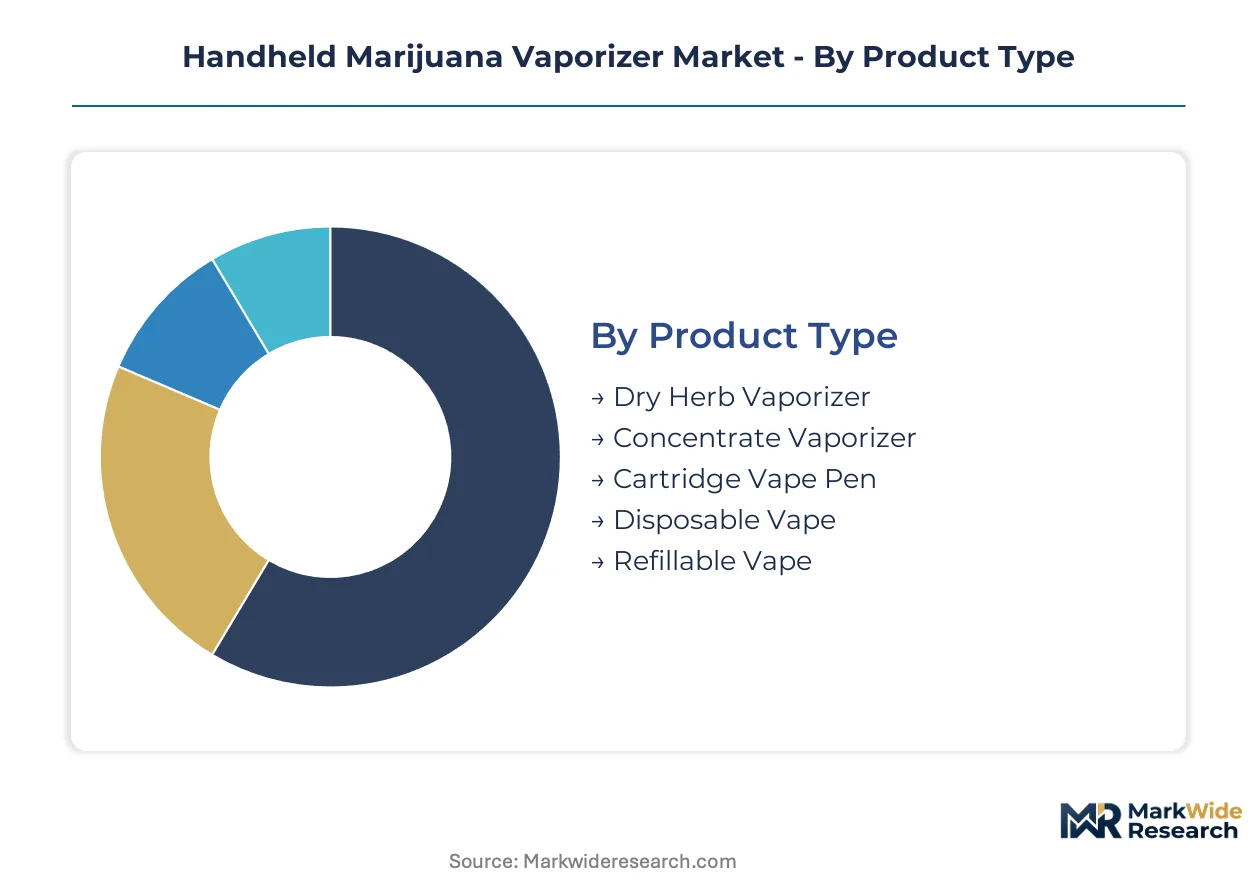
Segmentation in the handheld marijuana vaporizer market determines regulatory pathway complexity and margin architecture. Device categories face divergent compliance burdens from FDA marketing scrutiny to state-level testing mandates, while technology choices dictate manufacturing location and certification requirements.
Product Type:
Dry herb vaporizers require ISO 13485 alignment for medical channel access, while concentrate devices trigger stricter residual solvent testing protocols under state cannabis frameworks.
- Dry Herb Vaporizer:These devices heat whole cannabis flower through precision thermal chambers, preserving full-spectrum cannabinoid profiles. Demand concentrates among wellness enthusiasts in Colorado and California seeking whole-plant formulations without combustion byproducts, constrained by longer heat-up times that frustrate convenience-oriented buyers.
- Concentrate Vaporizer:Engineered for wax, shatter, and rosin consumption through specialized atomizers or bucket-style chambers. German medical distributors and Israeli hospital procurement channels favor these for dose-standardized therapy, though ceramic heating element supply scarcity elevates production costs.
- Cartridge Vape Pen:510-thread battery systems paired with pre-filled oil cartridges dominate recreational channels.
- Disposable Vape:Single-use integrated units capture price-sensitive trial purchases.
- Refillable Vape:Tank-based systems with replaceable coils appeal to cost-conscious heavy users.
Cartridge vape pens sit at the top of the volume ranking, with concentrate vaporizers climbing the fastest.
Technology:
Heating technology selection determines thermal efficiency, flavor preservation, and the regulatory documentation burden for firmware-controlled precision systems.
- Conduction Heating:Direct surface-to-material contact through heated chambers or plates enables rapid temperature achievement and compact device footprints. Budget-conscious recreational users in mature markets like California favor conduction systems for their manufacturing simplicity and lower retail price points.
- Convection Heating:Forced hot air passes through cannabis material without direct contact, eliminating hot spots and preserving volatile terpenes. Premium positioning in German and Dutch medical channels relies on convection's superior flavor metrics, though battery drain rates challenge portable form factor design.
- Hybrid Heating:Combines conductive base plates with convection airflow channels.
- Induction Heating:Electromagnetic field generation enables rapid, precise temperature modulation.
- Vapor Path Material:Ceramic, zirconia, or medical-grade stainless steel construction affects thermal retention and taste purity.
Conduction heating maintains the widest installed base, with hybrid systems gaining share fastest among wellness-oriented upgraders.
End User:
Customer archetype dictates purchasing channel, price sensitivity, and the depth of clinical documentation required for device validation.
- Medical Patients:Dose-standardized therapy requirements drive demand for precision temperature control and session logging capabilities. Hospital procurement in Germany and Israel now includes vaporizer specifications, though FDA software-as-medical-device scrutiny extends validation timelines.
- Recreational Users:Potency precision and operational discretion prioritize compact form factors and rapid onset. California's mature dispensary infrastructure serves this cohort with broad product selection, while social equity licensing windows in New York create emerging access points.
- Wellness Enthusiasts:Third-party lab demands for heavy metals and residual solvents elevate certification requirements.
- Specialty Dispensaries:Curated device selection for informed consumer guidance.
- Vape Lounges:Social consumption venues requiring durable, high-throughput equipment.
Recreational users command the largest addressable population, with medical patients expanding most quickly as clinical protocols gain jurisdiction-by-jurisdiction legitimacy.
Distribution Channel:
Channel selection determines geographic reach, margin retention, and exposure to state-level licensing compliance complexity.
- Online Retailers:Direct-to-consumer platforms bypass physical storefront overhead while navigating patchwork state shipping restrictions. California and Colorado operators leverage established logistics networks, though federal-state scheduling misalignment complicates payment processing infrastructure.
- Licensed Dispensaries:State-regulated cannabis retail requires Bureau of Cannabis Control compliance in California and equivalent frameworks elsewhere. These channels capture premium pricing through tactile product demonstration and trained staff consultation.
- Specialty Stores:Generalist retailers with vaporizer category focus.
- Vape Shops:Dedicated inhalation device retailers with technical expertise.
- Direct Manufacturer Sales:B2B relationships with institutional buyers.
Licensed dispensaries generate the highest revenue concentration, with online retailers scaling fastest where interstate shipping frameworks permit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers relocate production to exploit compliance-cost differentials between jurisdictions. Germany's EMA-aligned medical channel demands GMP documentation that adds cost but unlocks hospital procurement. California's Bureau of Cannabis Control imposes testing mandates that favor established players with captive laboratory relationships.
United States
California's mature dispensary infrastructure concentrates demand from wellness enthusiasts and recreational users alike. The FDA's Federal Food, Drug, and Cosmetic Act oversight shapes marketing claims for temperature-controlled devices. Oakland and Los Angeles host manufacturing clusters where social equity licensing programs create entry points for emerging producers without incumbent channel ties.
Germany
Hospital procurement channels in Berlin and Cologne now specify vaporizer requirements for dose-standardized cannabis therapy. EMA guidance on cannabis-derived medicinal products forces GMP-aligned production documentation upon device makers serving pharmaceutical distributors. Storz & Bickel's Tuttlingen facility anchors European precision-engineered convection manufacturing.
Israel
Medical patient protocols drive institutional procurement from hospital networks in Tel Aviv and Jerusalem. The national medical cannabis program mandates device specifications for clinical cannabis administration. Local distributors require batch-level traceability systems that recreational markets ignore.
Canada
Corporate wellness programs in Toronto and Vancouver explore vaporizer allowances as smoking cessation instruments. Health Canada's cannabis regulations create distinct medical and recreational distribution pathways. British Columbia's manufacturing base supplies both domestic demand and cross-border medical exports.
Netherlands
Medical distributors in Amsterdam and Rotterdam require precision temperature control for standardized cannabinoid delivery. Dutch tolerance policies created early commercial infrastructure that now transitions toward pharmaceutical-grade compliance. Eindhoven's electronics cluster supplies ceramic heating element components to device manufacturers.
Handheld Marijuana Vaporizer Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue social equity licensing windows in newly regulated states. The vendor base stratifies across medical-grade precision specialists, recreational convenience-format manufacturers, and component suppliers capturing margin from heating element scarcity. Three archetypes dominate: firmware-controlled precision device makers, ceramic heating element specialists, and 510-thread battery system integrators. Competitive moves concentrate on backward integration into heating element supply and geographic expansion through dispensary license partnerships.
Within the firmware-development tier, PAX Labs represents premium positioning through in-house software capabilities. Storz & Bickel exemplifies European medical-grade engineering with its German manufacturing heritage. DaVinci Vaporizer occupies a position emphasizing algorithmic temperature control among wellness-oriented upgraders. These three anchors illustrate how competitive differentiation flows from technical specialization rather than scale alone.
| Leading Market Players |
|---|
| PAX Labs |
| Storz & Bickel |
| DaVinci Vaporizer |
| Arizer |
| Boundless Technology |
| Grenco Science |
| KandyPens |
| Firefly Vapor |
| Dr. Dabber |
| Others |
Supply Flow & Price Mechanics
Firmware engineering talent clusters in California's Bay Area and Shenzhen's electronics corridor, with labor-cost differentials between these hubs driving spreads between premium algorithm-controlled devices and economy-tier conduction units. This geographic concentration of specialized workforce pools enables tiered pricing architectures that align manufacturing location with target buyer archetypes.
Pricing Analysis
Distributor margins at licensed California dispensaries compress manufacturer net pricing by 40-50 points compared with direct-to-consumer online channels. Three-tier pricing structure across premium, standard, and economy levels separates firmware-validated medical-grade devices from recreational conduction systems and disposable cartridge pens. Price differentiation centers on certification burden—FDA software-as-medical-device scrutiny adds validation costs that premium tiers recover through hospital procurement channels. Pricing pressure stems from ceramic heating element supply scarcity forcing inventory carry costs. Wellness enthusiasts in Colorado and Germany show least price sensitivity; recreational trial buyers in emerging state markets exhibit highest elasticity.
Supply Chain Analysis
Ceramic and zirconia heating element supply rests on Japanese specialty ceramic producers and German precision machining houses, with secondary qualified sources scarce across both material categories. Lithium-ion cell production concentrates in China, South Korea, and Japan, creating geographic dependency for portable device power systems. Raw material vulnerabilities span battery cathode chemistry, medical-grade stainless steel for vapor paths, and RoHS-compliant circuit board substrates. Single-source vulnerability in ceramic heating cores poses the dominant structural risk, with qualified supplier audits taking 18-24 months. Distribution runs through state-licensed dispensary networks in mature markets, supplemented by direct-to-consumer platforms where interstate shipping frameworks permit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The handheld marijuana vaporizer market functions as a stable compounder, with medical patient protocol expansion across Germany, Israel, and Canada jurisdictions providing steady demand foundation regardless of recreational regulatory volatility.
For Market Incumbents: Anchor market position through backward integration into ceramic heating element supply chains, eliminating single-source vulnerability that disrupts production scheduling. Pursue GMP-aligned production documentation investment to secure hospital procurement channel access in EMA-regulated markets, defending against emerging entrants lacking validation infrastructure. Firmware-controlled precision device makers face substitution threat from hybrid heating system commoditization; prioritize temperature algorithm patent filings and clinical outcome data generation to sustain premium positioning. For New Entrants and Emerging Players: The price-point gap between Storz & Bickel's medical-grade convection systems and budget conduction devices offers white-space targeting for mid-market hybrid configurations. California social equity licensing windows provide dispensary channel access without incumbent relationship requirements. Target wellness enthusiasts in Colorado and British Columbia through third-party heavy metals certification and published materials transparency. Pursue go-to-market partnerships with established cartridge oil producers to leverage 510-thread standardization and reduce consumer switching costs. For Investors and Strategic Acquirers: Cannabis-adjacent consumer electronics manufacturers represent the most active acquirer category in this space, seeking temperature control firmware capabilities and dispensary channel relationships. Long-term viability framing centers on medical channel diversification reducing recreational regulatory dependency. Acquisition target archetype: mid-scale manufacturers with validated ceramic supply agreements and pending FDA software documentation. Watch FDA scheduling reconsideration and state-level social equity program expansion as inflection indicators for distribution access democratization versus incumbent consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Heating Element Supply Integration | Captive ceramic and zirconia sourcing eliminates production disruption risk from qualified supplier scarcity. |
| GMP Production Documentation | EMA-aligned validation unlocks hospital procurement channels in Germany, Israel, and Netherlands markets. |
| Firmware Patent Portfolio Expansion | Temperature algorithm IP protects against hybrid heating system commoditization in mid-market tiers. |
| Social Equity License Partnerships | California and New York reserved dispensary access creates distribution footholds without incumbent channel ties. |
| Corporate Wellness B2B Pilot Programs | OSHA-compliant workplace vaporizer allowances in Canada and Uruguay open institutional procurement channels. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with device manufacturers, dispensary procurement managers, and regulatory affairs specialists with secondary validation. Primary sources included firmware engineering leads at precision device makers, California Bureau of Cannabis Control licensing officers, German medical distributor category managers, and ceramic heating element supply chain directors. Secondary data drew from FDA 510(k) device filings, EMA cannabis-derived medicinal product guidance documents, state-level cannabis regulatory frameworks, and ISO 13485 quality management system audits. Bottom-up unit shipment modeling triangulated against top-down market value estimates across the analysis window.
Historical reference periods anchored the projection framework through 2020-2025 demand trajectory analysis, with forward modeling calibrated to jurisdiction-by-jurisdiction medical protocol expansion timelines. Segmentation dimensions spanned product type (dry herb, concentrate, cartridge, disposable, refillable), heating technology (conduction, convection, hybrid, induction), end user archetype (medical patient, recreational user, wellness enthusiast), and distribution channel (licensed dispensary, online retail, specialty store). CAGRs derived from fitted growth curves applied to medical patient population expansion rates and recreational market maturity indicators, incorporating battery chemistry cost curves and ceramic component pricing trends as industry-specific forecast inputs.
Caveats apply where federal scheduling reconsideration, ceramic heating element supply disruption, or lithium-ion battery regulatory restriction could materially shift the outlook. Forecasts reflect assumptions around state-level social equity program implementation pace and EMA guidance harmonization timing. A small set of named triggers—FDA software-as-medical-device enforcement intensity, REACH compliance alignment deadlines, and OSHA workplace vaporizer policy evolution—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Hemp Derivatives Market
Cannabis/Marijuana
Cannabis Infused Edible Products Market
Cannabis/Marijuana
Marijuana Sensors Market
Cannabis/Marijuana
CBD Oil Market
Cannabis/Marijuana
Electric Cannabis Grinders Market
Cannabis/Marijuana
Arizona Legal Cannabis Market
Cannabis/Marijuana
Cannabidiol Extract Market
Cannabis/Marijuana
Medical Cannabis Market
Cannabis/Marijuana
CBD Market
Cannabis/Marijuana
Middle East and Africa CBD Patch Market
Cannabis/Marijuana
Cannabis Capsules Market
Cannabis/Marijuana
Butane Hash Oil Market
Cannabis/Marijuana
Global Cannabis ERP Software Market
Cannabis/Marijuana
CBD-Infused Products Market
Cannabis/Marijuana
Global Cannabidiol (CBD) Vape Juice Market
Cannabis/Marijuana
Australia Medicinal Cannabis Testing Market