
 Cannabis Technology Market | 2026-2036
Cannabis Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Cannabis Technology Market Analytics
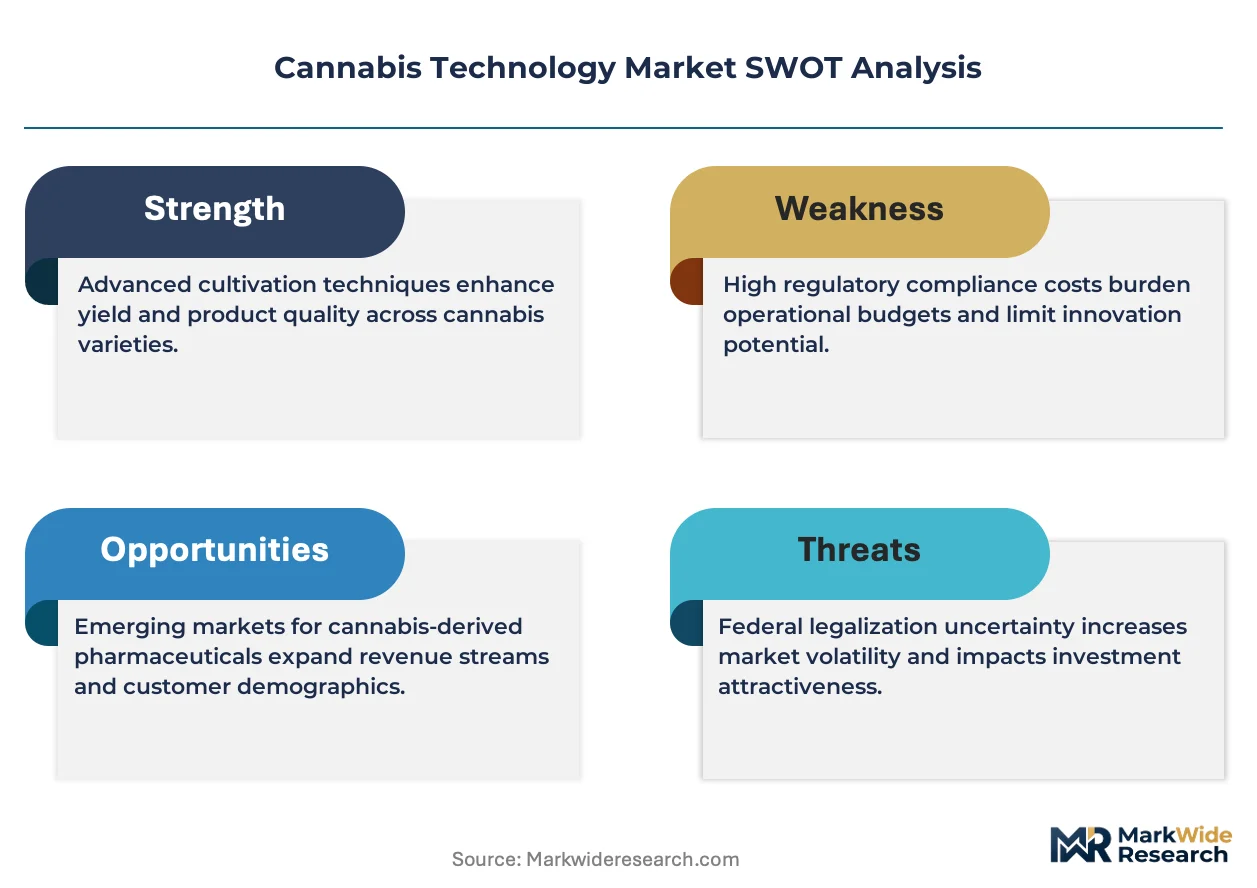
A shortage of qualified cannabis cultivation technicians is collapsing operational capacity at licensed facilities across mature markets. Dutchie leverages its point-of-sale infrastructure to anchor dispensary software penetration in the United States. LeafLink sustains wholesale marketplace dominance by connecting multi-state operators with compliant inventory tracking. Green Thumb Industries competes through vertically controlled retail and production assets in Illinois and Pennsylvania.
Cannabis technology encompasses hardware, software, and biotechnical systems engineered to cultivate, process, test, and distribute cannabis with validated potency and purity metrics, operating within temperature ranges of 18–26°C and photoperiod controls of 12–18 hours. Its primary commercial purpose is to standardize output quality while satisfying jurisdictional compliance requirements for THC and CBD concentration reporting. Extraction systems command premium margin pools due to capital intensity and solvent recovery specifications. Smart farming platforms are expanding fastest as sensor networks and AI-driven climate control reduce labor dependency in greenhouse operations. Testing tools remain structurally constrained by ISO 17025 accreditation bottlenecks and variable state laboratory capacity.
The FDA maintains oversight of cannabis-derived pharmaceutical ingredients through IND and NDA pathways, while state cannabis control boards in California, Colorado, and Illinois enforce batch-level testing and seed-to-sale tracking through METRC and comparable platforms. The USDA regulates industrial hemp cultivation under the Farm Bill, creating a bifurcated compliance landscape for technology vendors serving THC and CBD supply chains. Stakeholders must monitor evolving state reciprocity agreements and federal rescheduling deliberations to calibrate platform investments against jurisdictional expansion timelines.
Market Dynamics
State-level track-and-trace mandates are compressing operational margins for unautomated cultivators while concentrating procurement power among integrated technology vendors serving licensed producers.
Growth Catalysts
- METRC Compliance Mandates:California, Colorado, and Illinois require seed-to-sale tracking through METRC and comparable platforms, forcing facility upgrades and sustaining demand for integrated compliance software.
- AI-Driven Climate Control:Smart farming platforms deploy sensor networks and machine learning to reduce labor dependency in greenhouse operations, cutting per-unit cultivation costs.
- Extraction Automation:Solvent recovery specifications and capital-intensive processing requirements pull investment toward automated extraction systems that standardize THC and CBD potency metrics.
Market Restraints
- ISO 17025 Accreditation Bottlenecks:Testing laboratories face structural capacity constraints as variable state requirements create backlogs for batch-level certification.
- Qualified Technician Scarcity:Licensed facilities in mature markets report collapsing operational capacity due to insufficient trained cultivation staff.
- Federal-State Regulatory Bifurcation:The USDA regulates industrial hemp under the Farm Bill while the FDA maintains IND and NDA oversight of pharmaceutical ingredients, fragmenting vendor platform investments.
Strategic Opportunities
- Canadian Provincial Expansion:Licensed producers in Ontario and British Columbia are expanding automation investments as federal frameworks stabilize, creating demand for smart farming integration.
- Pharmaceutical Pathway Convergence:FDA IND and NDA pathways for cannabis-derived ingredients enable technology vendors to serve dual THC and CBD supply chains with validated purity systems.
- Retail Software Penetration:Point-of-sale infrastructure anchors dispensary technology adoption, with wholesale marketplace platforms connecting multi-state operators to compliant inventory tracking.
Industry Challenges
- Cultivation Technician Skill Gaps:Facilities struggle to staff climate-controlled environments requiring photoperiod management and temperature regulation expertise.
- Legacy System Integration:Automated extraction and testing platforms face compatibility friction with existing seed-to-sale tracking infrastructure.
- Capex Recovery Timelines:Greenhouse sensor networks and AI-driven control systems require extended depreciation periods amid shifting state reciprocity agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cannabis Technology Market |
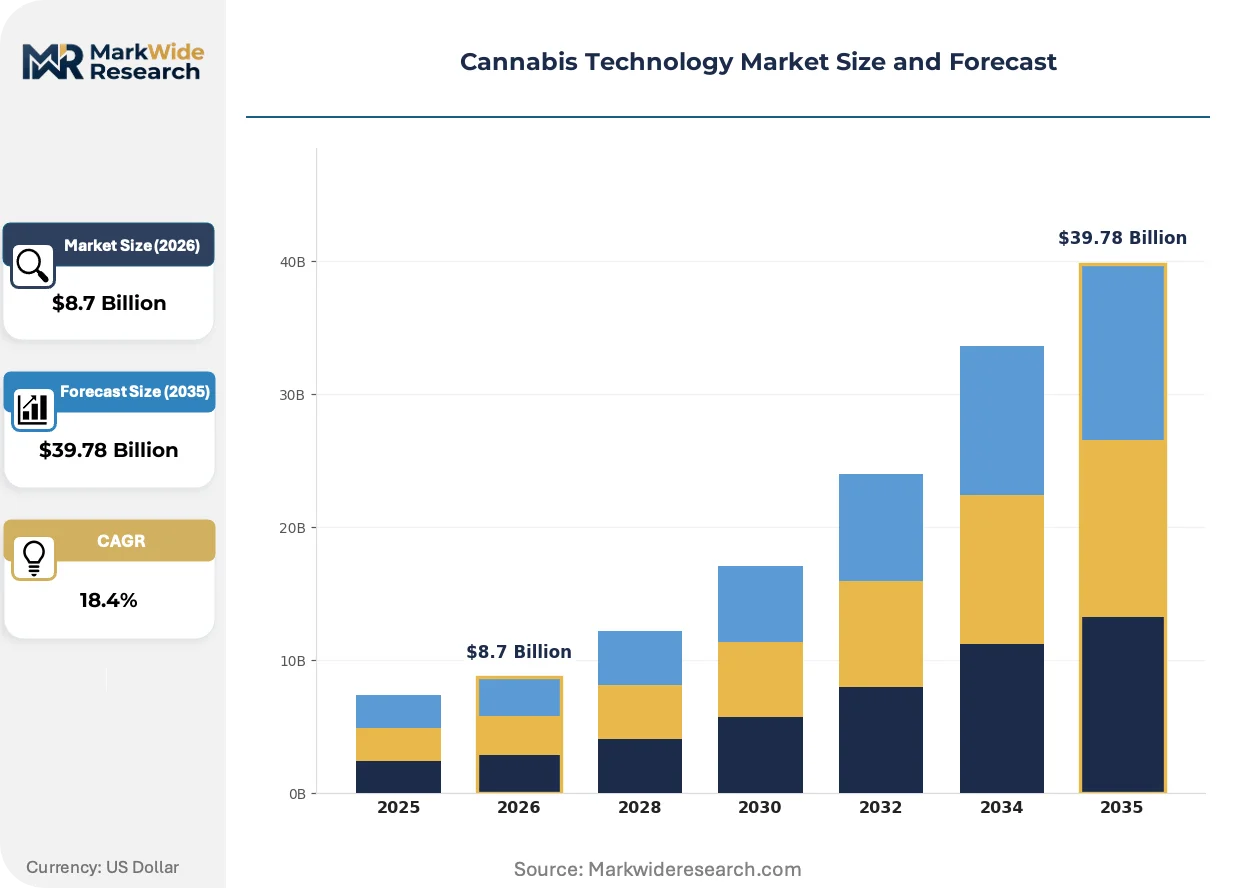
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grow Equipment, Extraction Systems, Testing Tools, Lighting Solutions End User: Licensed Producers, Research Institutions, Dispensaries, Investors Technology: Hydroponics, Aeroponics, Soil-Based, Smart Farming Application: Medical Cannabis, Recreational Use, Industrial Hemp, Product Development |
| Companies Covered | Dutchie, LeafLink, Treez, Green Thumb Industries, Flowhub, Jane Technologies, The Valens Company, PAX, WM Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cannabis Technology Market Evolving Landscape
Automation architectures are splitting between high-throughput extraction systems and precision cultivation platforms, with regulatory compliance layers binding both strands into unified vendor ecosystems.
Smart farming technology is bifurcating the cultivator base. Sensor networks and AI-driven climate control systems enable large greenhouse operators to compress labor costs while maintaining 18–26°C temperature bands and 12–18 hour photoperiod precision. Mid-scale facilities without automation face margin compression as labor-dependent operations lose pricing power against standardized output.
REACH and RoHS compliance requirements in Europe are reshaping hardware specifications for cultivation and extraction equipment exported from North American vendors. Component material restrictions and chemical safety documentation now gate market access for climate control systems and solvent recovery units. German and Dutch licensed producers prioritize CE-marked equipment to preempt regulatory friction during facility licensing.
Buyer consolidation among multi-state operators is compressing procurement cycles for enterprise-grade compliance platforms. Dispensary software and wholesale marketplace systems face vendor consolidation pressure as integrated retail-production assets in Illinois and Pennsylvania demand unified seed-to-sale tracking. This concentration is most visible in mature state markets where operational scale determines licensing survival.
Cannabis Technology Market Segmentation
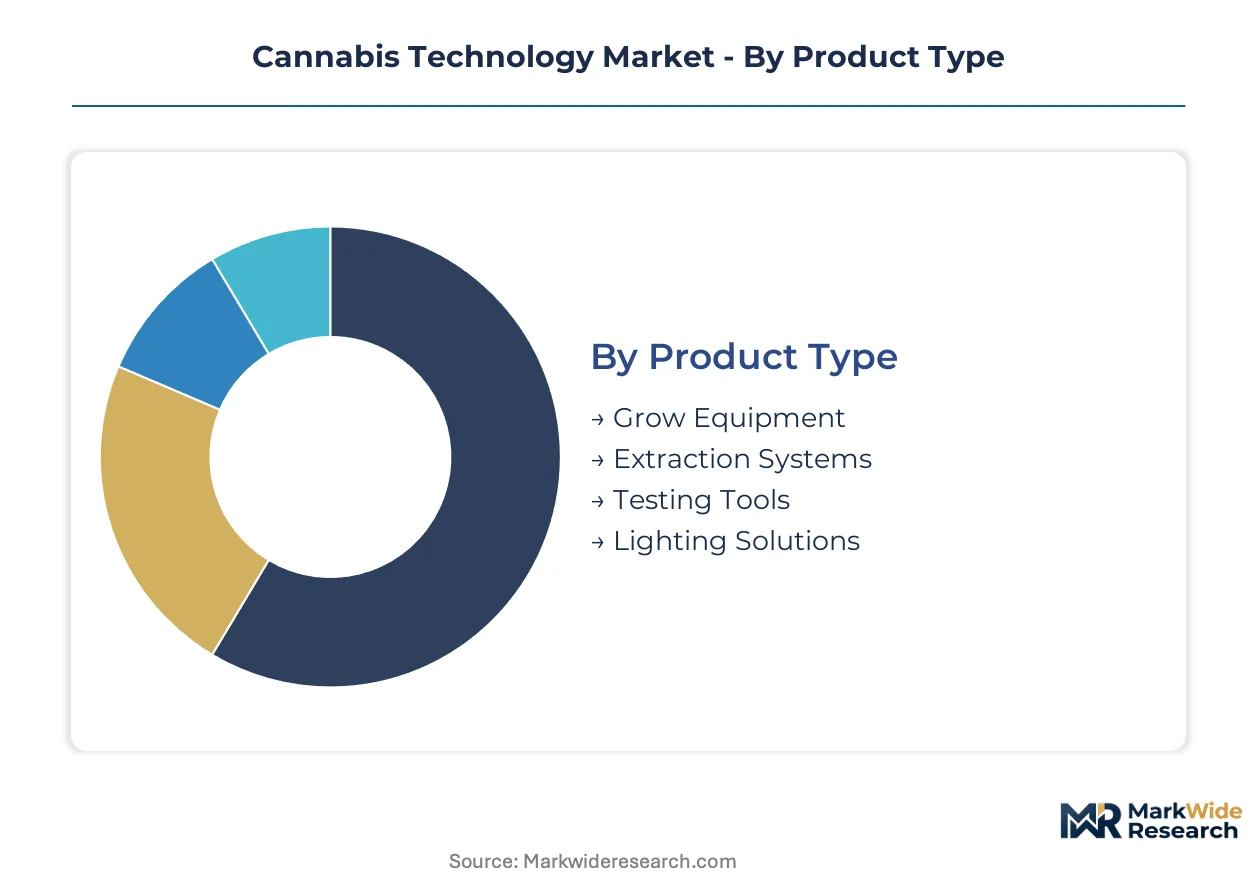
Cannabis technology vendors must align platform investments with distinct operational requirements across cultivation, processing, and distribution. Each segment category carries unique compliance burdens and capital intensity profiles that determine procurement timelines and vendor selection criteria.
Product Type:
Grow equipment and extraction systems face intensifying substitution pressure as integrated smart farming platforms absorb standalone hardware functions into unified control architectures.
- Grow Equipment:Climate control systems, irrigation infrastructure, and environmental sensors engineered for 18–26°C temperature maintenance and 12–18 hour photoperiod precision. Demand concentrates in California and Colorado greenhouse operations as METRC compliance mandates force facility upgrades.
- Extraction Systems:Solvent-based and solventless processing equipment with automated solvent recovery capabilities that standardize THC and CBD potency metrics. Capital-intensive specifications pull investment from Illinois and Pennsylvania multi-state operators seeking pharmaceutical-grade output consistency.
- Testing Tools:Chromatography and spectrometry systems for batch-level potency and purity verification. ISO 17025 accreditation bottlenecks constrain laboratory capacity across state markets.
- Lighting Solutions:LED and high-pressure sodium fixtures optimized for photosynthetic photon flux density in controlled environments. Energy efficiency regulations in Canada drive retrofit demand.
Grow equipment anchors the volume base while extraction systems gain share at the steepest rate.
End User:
Procurement authority splits between production assets seeking operational scale and retail infrastructure requiring compliance integration, with research institutions representing an emerging specification influencer.
- Licensed Producers:Vertically integrated cultivation and processing facilities subject to seed-to-sale tracking mandates. Automation investments accelerate in Ontario and British Columbia as federal frameworks stabilize.
- Research Institutions:Academic and pharmaceutical laboratories conducting FDA IND and NDA pathway studies for cannabis-derived ingredients. Purity validation requirements drive demand for analytical instrumentation.
- Dispensaries:Retail operations requiring point-of-sale integration with state track-and-trace platforms. Software procurement concentrates among multi-state operators in Illinois and Pennsylvania.
- Investors:Capital allocators funding facility expansion and technology upgrades. Due diligence processes prioritize platforms with proven compliance integration.
Licensed producers dominate current procurement volume while research institutions expand their specification influence fastest.
Technology:
Cost tier differentiation separates capital-intensive precision platforms from established growing methodologies, with sensor network deployment determining margin outcomes.
- Hydroponics:Soilless cultivation using nutrient-rich water solutions in controlled reservoirs. Mature adoption across Colorado and California facilities seeking water use efficiency.
- Aeroponics:Root misting systems delivering nutrients via pressurized spray. High capital requirements limit deployment to premium pharmaceutical-grade operations.
- Soil-Based:Traditional substrate cultivation with organic amendment protocols. Labor dependency creates margin pressure against automated alternatives.
- Smart Farming:AI-driven climate control with sensor networks and machine learning optimization. Expanding most quickly in Canadian provincial markets as federal regulation standardizes.
Soil-based methods retain the largest installed base while smart farming climbs the fastest.
Application:
Regulatory maturity separates medical and recreational pathways from industrial hemp, with pharmaceutical convergence creating cross-segment technology demand.
- Medical Cannabis:Therapeutic products requiring FDA oversight through IND and NDA pathways. Purity validation systems command premium pricing from pharmaceutical-grade producers.
- Recreational Use:Adult-use products subject to state-level potency labeling and packaging requirements. California and Colorado anchor procurement volume for compliance software.
- Industrial Hemp:Fiber and CBD feedstock regulated under USDA Farm Bill provisions. Bifurcated compliance landscape fragments vendor platform investments.
- Product Development:Formulation R&D for novel delivery mechanisms and cannabinoid profiles. Emerging demand from research institutions and licensed producer innovation divisions.
Recreational use anchors current technology deployment while medical cannabis applications expand at the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA and state cannabis control boards anchor technology demand in the United States, while Health Canada stabilizes federal frameworks for provincial automation investments. Germany and the Netherlands drive European equipment specifications through REACH and RoHS compliance gates. Australia and Israel expand research-grade cultivation infrastructure under pharmaceutical pathway convergence.
United States
California, Colorado, and Illinois multi-state operators compress procurement cycles for enterprise compliance platforms. METRC mandates force facility upgrades across mature recreational markets. Los Angeles and Denver anchor smart farming deployment as sensor networks reduce labor dependency in greenhouse operations.
Canada
Ontario and British Columbia licensed producers accelerate automation investments as federal seed-to-sale frameworks stabilize. Health Canada oversight of THC and CBD reporting sustains demand for validated potency systems. Toronto and Vancouver metropolitan areas concentrate extraction system procurement from capital-intensive operators.
Germany
Medical cannabis expansion under BfArM licensing creates demand for pharmaceutical-grade cultivation technology. REACH and RoHS compliance requirements reshape hardware specifications for imported climate control and solvent recovery equipment. Berlin and Cologne industrial clusters prioritize CE-marked systems to preempt regulatory friction during facility licensing.
Netherlands
Government-controlled cannabis supply chain experiments drive precision cultivation technology trials. Dutch greenhouse engineering expertise exports sensor network architectures to North American operators. Amsterdam and Rotterdam logistics hubs facilitate equipment distribution across European medical markets.
Australia
TGA pharmaceutical-grade cannabis approvals expand research institution demand for analytical instrumentation. State-level cultivation licenses in Victoria and Queensland attract smart farming platform investment. Melbourne biomedical precincts anchor FDA IND pathway studies requiring validated purity systems.
Cannabis Technology Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with compliance-integrated platforms commanding premium positioning against standalone hardware vendors. The vendor base splits between point-of-sale software specialists, wholesale marketplace operators, and vertically controlled retail-production assets. Three archetypes dominate: seed-to-sale compliance platforms, smart farming system integrators, and extraction automation specialists. Competitive moves concentrate on strategic partnerships between software layers and hardware OEMs, plus geographic expansion into provincial Canadian markets.
Within the software infrastructure tier, Dutchie and LeafLink occupy positions anchoring dispensary and wholesale marketplace penetration respectively. Green Thumb Industries exemplifies the vertically integrated archetype controlling retail and production assets across Illinois and Pennsylvania. These three entities represent distinct competitive vectors: POS-dominated software stacks, B2B marketplace aggregation, and captive retail-production technology deployment.
| Leading Market Players |
|---|
| Dutchie |
| LeafLink |
| Treez |
| Green Thumb Industries |
| Flowhub |
| Jane Technologies |
| The Valens Company |
| PAX |
| WM Technology |
| Others |
Value Network & Pricing Analysis
Greenhouse scale economies in Ontario and British Columbia compress per-unit cultivation costs below labor-dependent competitors, concentrating supply among automated licensed producers while establishing price floors for smart farming platforms and extraction systems. METRC compliance mandates in California, Colorado, and Illinois force facility upgrades that sustain premium pricing for integrated seed-to-sale software, with multi-state operators leveraging procurement volume to negotiate service bundling.
Pricing Analysis
California commands 15-20% premiums over Colorado for equivalent extraction system configurations due to stricter solvent recovery specifications and higher facility licensing costs. Three-tier pricing structure across pharmaceutical-grade, premium recreational, and standard economy levels separates buyers by ISO 17025 certification requirements and batch validation depth. Pricing pressure stems from mid-scale cultivator margin compression as AI-driven climate control systems displace labor-dependent operations. Dispensary software buyers exhibit highest price sensitivity, while pharmaceutical pathway producers prioritize purity validation over unit cost.
Supply Chain Analysis
Canada and the United States anchor climate control system manufacturing, with German and Dutch engineering clusters supplying precision sensor networks and solvent recovery equipment. Hardware production draws from semiconductor components, aluminum extrusion framing, and specialized LED chipsets. Single-source vulnerability concentrates in AI-driven control software licensed from narrow vendor pools. Distribution runs through direct OEM sales for large greenhouse operators and regional distributor networks serving mid-scale facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cannabis technology demand cycles track state-level licensing waves, with current recovery driven by Canadian provincial automation investments following federal framework stabilization. Procurement authority concentrates among multi-state operators seeking unified compliance platforms.
For Market Incumbents: Consolidate seed-to-sale software stacks through API integration with smart farming hardware OEMs to preempt displacement by full-stack competitors. Deepen backward integration into sensor manufacturing to secure component supply against semiconductor allocation constraints. Priority leverage rests on METRC certification maintenance as state mandates tighten. For New Entrants and Emerging Players: Cultivation technician training and certification services represent underserved white space as licensed facilities report collapsing operational capacity from qualified staff scarcity. Target mid-scale greenhouse operators in emerging state markets lacking automation expertise. Go-to-market angle: compliance-integrated training platforms bundled with equipment procurement. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among point-of-sale software vendors with dispensary lock-in through state track-and-trace integration. Five-to-ten-year viability favors platforms with proven multi-jurisdictional deployment. Acquisition target archetype: smart farming system integrators with Health Canada validation. Signal to watch: FDA rescheduling deliberations triggering pharmaceutical pathway convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-layer unification of seed-to-sale compliance with AI-driven climate control reduces vendor fragmentation for multi-state operators. |
| Geographic Expansion | Ontario and British Columbia automation investments create demand pull for vendors with Health Canada-validated potency systems. |
| Strategic Partnership | Software-hardware OEM alliances compress procurement cycles as integrated retail-production assets demand unified tracking. |
| Product Launch | FDA IND pathway-aligned testing tools capture pharmaceutical-grade producer demand for validated purity metrics. |
| Acquisition of Specialist Firm | Extraction automation specialists with solvent recovery IP address capital-intensive processing requirements in Illinois and Pennsylvania. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with licensed producer facility managers, dispensary operations directors, seed-to-sale software engineers, METRC compliance officers, and extraction system technicians. Secondary validation drew from Health Canada licensing databases, FDA IND submission records, state cannabis control board enforcement reports, and SEC filings of publicly traded multi-state operators. Bottom-up equipment procurement estimates triangulated against top-down market sizing from federal framework expenditure disclosures.
Across the projection horizon, analytical frameworks modeled segmentation by cultivation technology, end-user procurement authority, application pathway, and regulatory jurisdiction cluster. CAGRs were derived from equipment shipment tracking and facility licensing velocity. Industry-specific inputs included METRC mandate implementation timelines and ISO 17025 laboratory capacity expansion rates.
Forecasts assume regulatory continuity in Health Canada oversight and state cannabis control board frameworks; material policy shifts including FDA rescheduling or federal legalization would require re-modeling. Recalibration cycles align with material shifts in licensing velocity and compliance mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Veterinary CBD Market
Cannabis/Marijuana
Cannabis Edibles Market
Cannabis/Marijuana
Global CBD Vape Juice Market
Cannabis/Marijuana
Cannabis Capsules Market
Cannabis/Marijuana
Global Cannabis Industry Software Market
Cannabis/Marijuana
CBD Infused Cosmetics Market
Cannabis/Marijuana
Automated Cannabis Testing Market
Cannabis/Marijuana
Arizona Legal Cannabis Market
Cannabis/Marijuana
Handheld Marijuana Vaporizer Market
Cannabis/Marijuana
Thailand Medical Cannabis Market
Cannabis/Marijuana
Flavored CBD Powder Market
Cannabis/Marijuana
Latin America and Caribbean Hemp-Derived Cannabidiol Market
Cannabis/Marijuana
CBD Consumer Health Market
Cannabis/Marijuana
Middle East and Africa Cannabidiol (CBD) Market
Cannabis/Marijuana
CBD-Infused Products Market
Cannabis/Marijuana
Middle East and Africa CBD Patch Market