
 Veterinary CBD Market | 2026-2036
Veterinary CBD Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary CBD Market Outlook
The veterinary CBD category is consolidating around a sharp split between premium full-spectrum formulations backed by third-party testing and commodity-grade products with minimal traceability. Charlotte's Web leverages its seed-to-shelf control over hemp cultivation to command premium shelf positioning in specialty pet retail. Honest Paws differentiates through subscription-based direct-to-consumer distribution that sustains recurring revenue without intermediary markups. Pet Releaf anchors the clinical channel by securing shelf space in independent veterinary practices that prioritize Certificate of Analysis documentation.
Veterinary CBD comprises hemp-derived cannabinoid formulations refined to contain less than 0.3% delta-9 tetrahydrocannabinol by dry weight, typically extracted via supercritical CO2 or ethanol methods and standardized to declared cannabidiol potency for oral or transdermal administration in companion animals. Oils retain the dominant revenue position due to dosing flexibility and faster systemic absorption compared to treat-based alternatives. Anxiety Relief applications command premium pricing relative to inflammation management, reflecting pet owner willingness to pay for behavioral outcomes in dogs with noise phobia or separation distress. The oral delivery mode occupies the largest volume share, though sublingual tincture formats are gaining traction among veterinary clinics seeking more predictable pharmacokinetic profiles.
The FDA Center for Veterinary Medicine maintains enforcement discretion while declining to approve CBD as an animal food additive, creating compliance ambiguity that shapes formulation and labeling strategies. State agriculture departments and the USDA hemp production program collectively determine testing thresholds and interstate shipment legality for hemp-derived ingredients. Stakeholders must monitor pending federal rulemaking on cannabinoid safety data requirements while building veterinary clinical trial partnerships that preempt stricter efficacy standards.
Market Dynamics
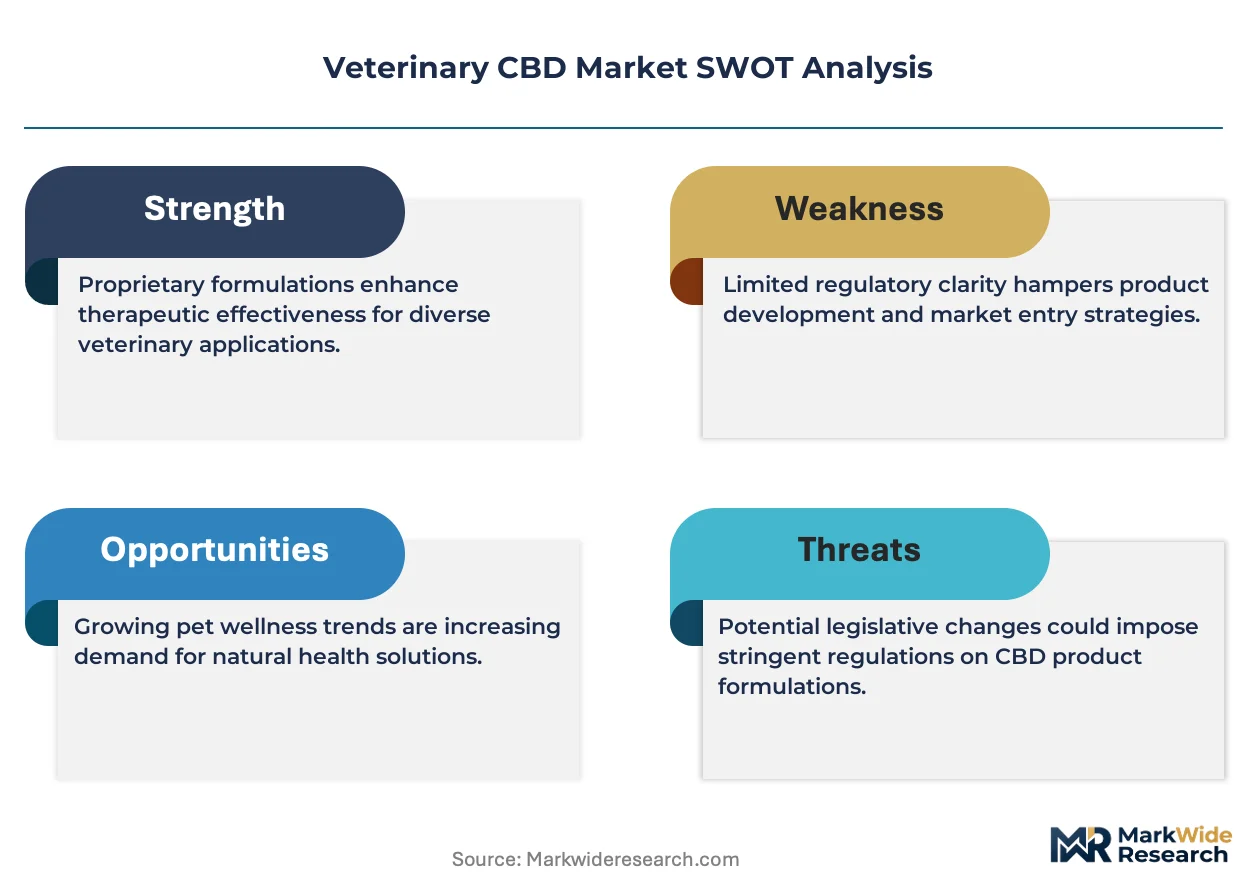
The veterinary CBD sector is bifurcating around regulatory ambiguity at the FDA Center for Veterinary Medicine, which maintains enforcement discretion without formal approval pathways for cannabinoid animal food additives. This structural uncertainty forces manufacturers to navigate state-level hemp statutes and USDA hemp production program requirements while building clinical evidence portfolios that anticipate future federal rulemaking.
Growth Catalysts
- The 2018 Farm Bill:This federal legislation removed hemp from Schedule I controlled substance classification, enabling interstate commerce in hemp-derived ingredients containing less than 0.3% delta-9 tetrahydrocannabinol and creating legal foundation for product development.
- Anxiety relief applications:Pet owner demand for behavioral interventions in dogs with noise phobia and separation distress is generating premium pricing power and expanding the addressable companion animal population beyond traditional pain management use cases.
- Supercritical CO2 extraction:This refinement technology preserves full-spectrum cannabinoid profiles while eliminating residual solvents, enabling third-party Certificate of Analysis documentation that satisfies independent veterinary practice procurement standards.
Market Restraints
- FDA regulatory friction:The agency's refusal to approve CBD as an animal food additive creates compliance ambiguity that restricts marketing claims and limits distribution through conventional pet food retail channels.
- Input cost volatility:Organic hemp biomass prices fluctuate with weather-dependent cultivation yields in Kentucky and Oregon, compressing margin stability for brands without captive agricultural supply.
- Certificate of Analysis standardization gaps:Inconsistent state agriculture department testing thresholds for heavy metals, pesticides, and residual solvents create interstate shipment barriers and product reformulation costs.
Strategic Opportunities
- Independent veterinary practice channel:Clinical settings that prioritize pharmacokinetic documentation and dosing protocols represent underpenetrated distribution with higher margin capture than mass retail.
- Sublingual tincture formats:Transdermal and sublingual delivery modes enabling more predictable absorption profiles are displacing oil-based administration in professional settings.
- Subscription direct-to-consumer models:Recurring revenue structures bypass intermediary markups and build proprietary customer data assets for personalized formulation development.
Industry Challenges
- Veterinary pharmacology expertise scarcity:Cannabinoid therapeutics training remains absent from most veterinary school curricula, limiting prescriptive confidence and dosing standardization.
- Clinical trial infrastructure gaps:Multi-site efficacy studies require capital deployment that exceeds mid-tier manufacturer R&D budgets, delaying peer-reviewed evidence generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary CBD Market |
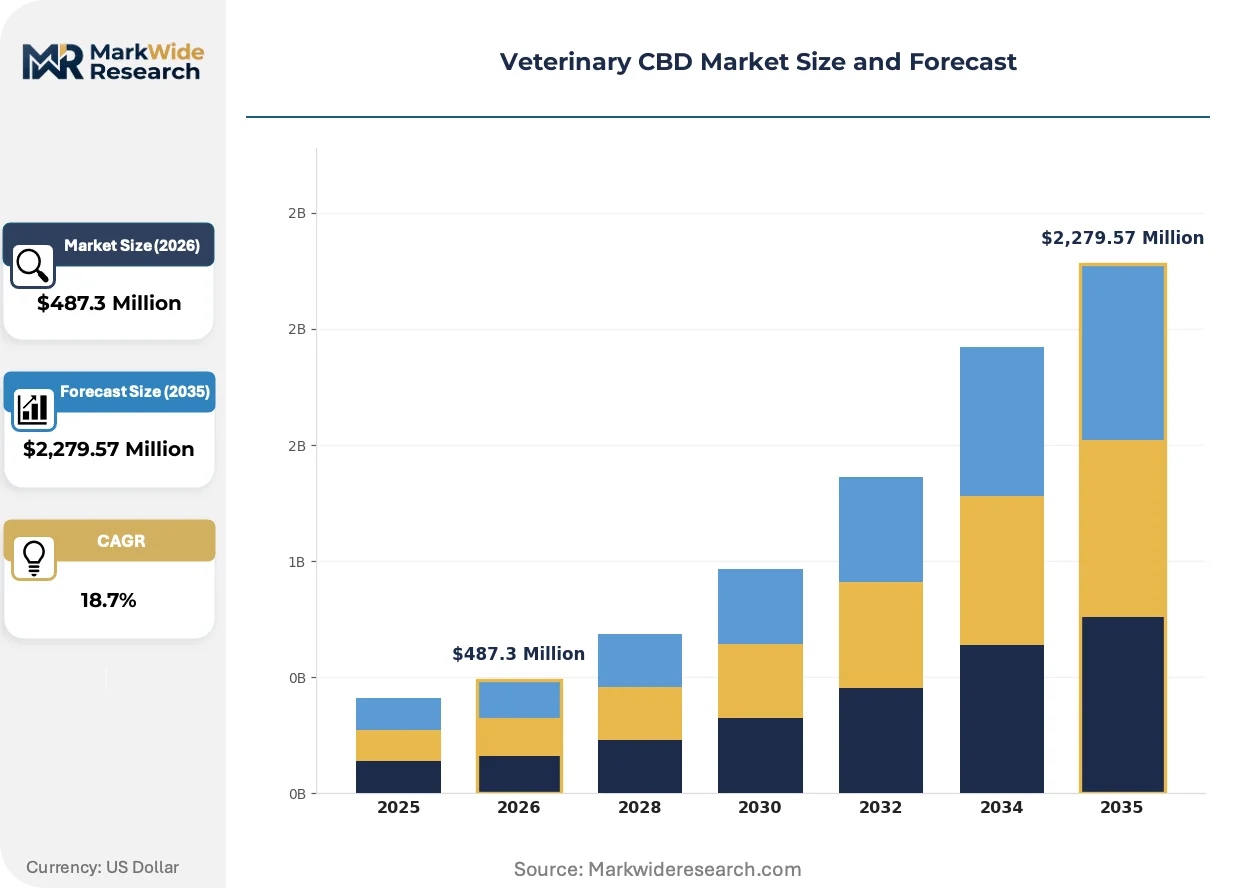
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $2,279.57 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oils, Treats, Capsules, Topicals End User: Pet Owners, Veterinary Clinics, Animal Shelters, Pet Stores Delivery Mode: Oral, Transdermal, Inhalation, Sublingual Application: Anxiety Relief, Pain Management, Inflammation, Seizure Control |
| Companies Covered | Pet Releaf, Canna-Pet, HolistaPet, King Kanine, Honest Paws, Charlotte’s Web, HempMy Pet, cbdMD, Joy Organics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary CBD Market Strategic Shifts
Formulation science and distribution architecture are converging to reshape competitive positioning in veterinary cannabinoid therapeutics. Product differentiation now hinges on pharmacokinetic validation and channel-specific compliance rather than commodity ingredient sourcing.
Nanoemulsion technology is automating bioavailability enhancement in liquid formulations, reducing particle size to below 100 nanometers for improved systemic absorption. Specialty pet retailers and veterinary clinics in California and Colorado are adopting these advanced delivery systems at accelerated pace. This technological shift is automating margin compression for conventional oil-based competitors lacking refinement capabilities.
USDA hemp production program requirements for THC testing and interstate shipment documentation are tightening traceability standards across the supply chain. State agriculture departments in Oregon, Kentucky, and Colorado now mandate lot-specific testing protocols that increase compliance overhead. Small-batch manufacturers without in-house quality infrastructure face exclusion from multi-state distribution networks.
Pet owner purchasing behavior is rotating toward subscription-based replenishment models that prioritize convenience and dosing consistency over episodic retail purchase. Direct-to-consumer platforms are displacing brick-and-mortar specialty retail in urban markets with established pet wellness infrastructure. This channel migration concentrates most acutely in metropolitan areas with high veterinary clinic density and premium pet product consumption patterns.
Veterinary CBD Market Segmentation
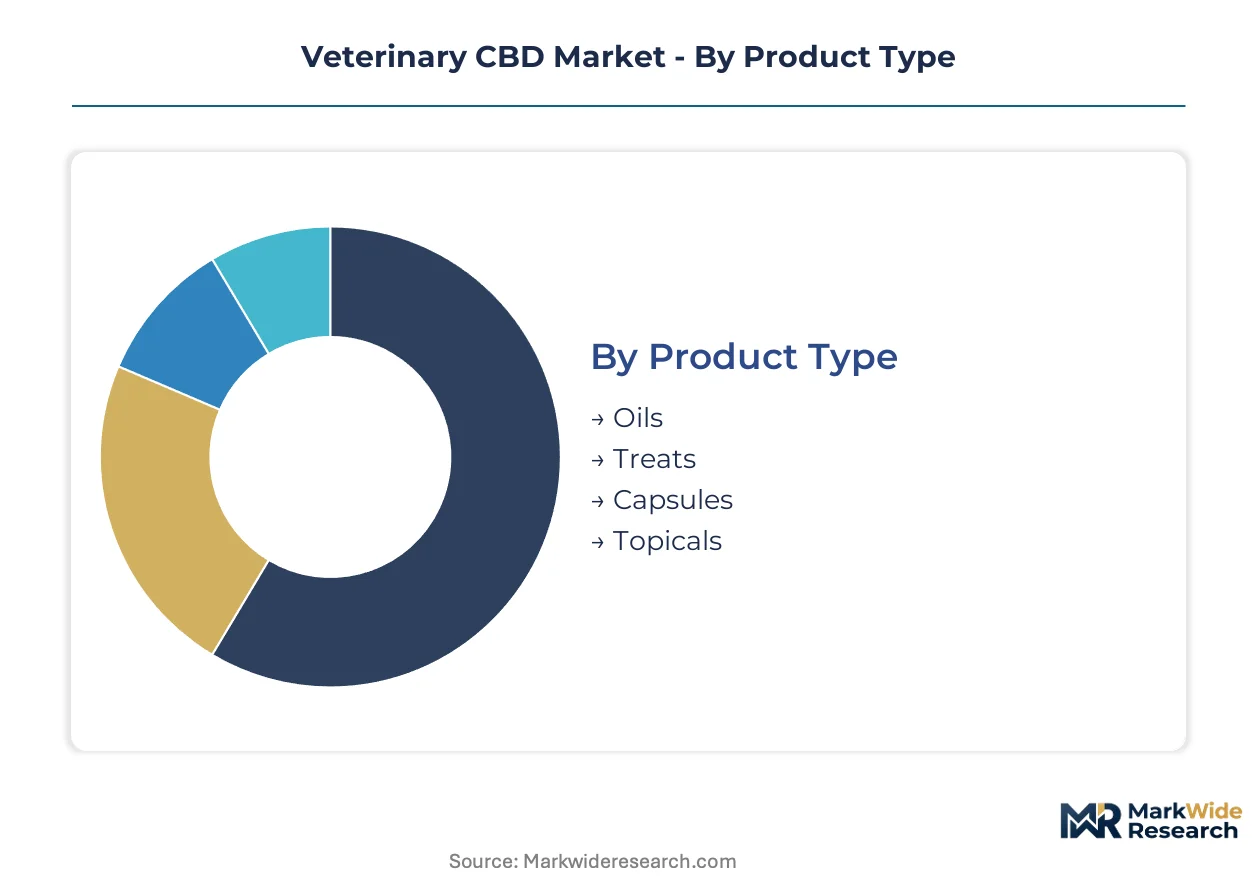
Veterinary CBD manufacturers configure product portfolios around regulatory compliance burdens and channel-specific procurement standards. Each segment carries distinct testing documentation requirements that shape formulation investment and distribution strategy.
Product Type:
USDA hemp production program compliance and FDA enforcement discretion create tiered certification obligations across formats, with third-party Certificate of Analysis documentation mandatory for veterinary clinic procurement.
- Oils:Liquid formulations extracted via supercritical CO2 or ethanol methods, standardized to declared cannabidiol potency with less than 0.3% delta-9 tetrahydrocannabinol. Demand concentrates in North American urban markets with established pet wellness retail infrastructure, driven by dosing flexibility and faster systemic absorption profiles that veterinary clinics prioritize for behavioral interventions.
- Treats:Palatable delivery vehicles incorporating hemp-derived cannabinoids into chewable matrices, requiring additional stability testing for moisture content and shelf-life validation. Pet owners seeking anxiety relief solutions for companion animals favor this format for home administration convenience, though bioavailability variability limits clinical channel penetration.
- Capsules:Pre-measured gelatin or vegetable-based shells containing standardized cannabinoid powder, appealing to precision-focused consumers.
- Topicals:Transdermal creams and balms targeting localized inflammation, constrained by limited pharmacokinetic data for dermal absorption in companion animals.
Leading the category by volume: Oils. Growing fastest: Treats.
End User:
Customer type determines margin structure and recurring revenue potential, with direct-to-consumer models bypassing intermediary markups that compress specialty retail economics.
- Pet Owners:Individual consumers purchasing through subscription-based platforms or brick-and-mortar specialty retailers, representing the largest addressable population. This segment concentrates in metropolitan areas with high veterinary clinic density and premium pet product consumption patterns, with anxiety relief applications generating premium pricing power for behavioral outcomes.
- Veterinary Clinics:Independent practices prioritizing Certificate of Analysis documentation and pharmacokinetic validation for prescriptive confidence. Clinical settings command higher margin capture than mass retail but require manufacturer investment in dosing protocol development and cannabinoid therapeutics education.
- Animal Shelters:Institutional buyers managing population-level behavioral stress, constrained by procurement budget limitations.
- Pet Stores:Specialty retail intermediaries demanding slotting fees and promotional support that erode manufacturer profitability.
Pet owners dominate absolute volume. Veterinary clinics are climbing the fastest as prescriptive confidence builds.
Delivery Mode:
Absorption kinetics and administration feasibility create technical differentiation that separates professional-grade from consumer-grade positioning.
- Oral:Standard ingestion through food or direct administration, occupying the largest volume share due to familiarity and formulation simplicity. State agriculture department testing thresholds for heavy metals and residual solvents create interstate shipment barriers that oral-format manufacturers must navigate for multi-state distribution.
- Sublingual:Tincture formats enabling mucosal absorption with more predictable pharmacokinetic profiles, gaining traction among veterinary clinics seeking standardized onset timing. Nanoemulsion technology is automating bioavailability enhancement in these liquid formulations, reducing particle size to below 100 nanometers.
- Transdermal:Patch-based or cream-based dermal delivery, limited by species-specific skin permeability variability.
- Inhalation:Aerosolized delivery systems, minimally developed due to respiratory safety concerns and dosing precision challenges in companion animals.
Oral administration leads current volume. Sublingual formats show steepest expansion trajectory in professional settings.
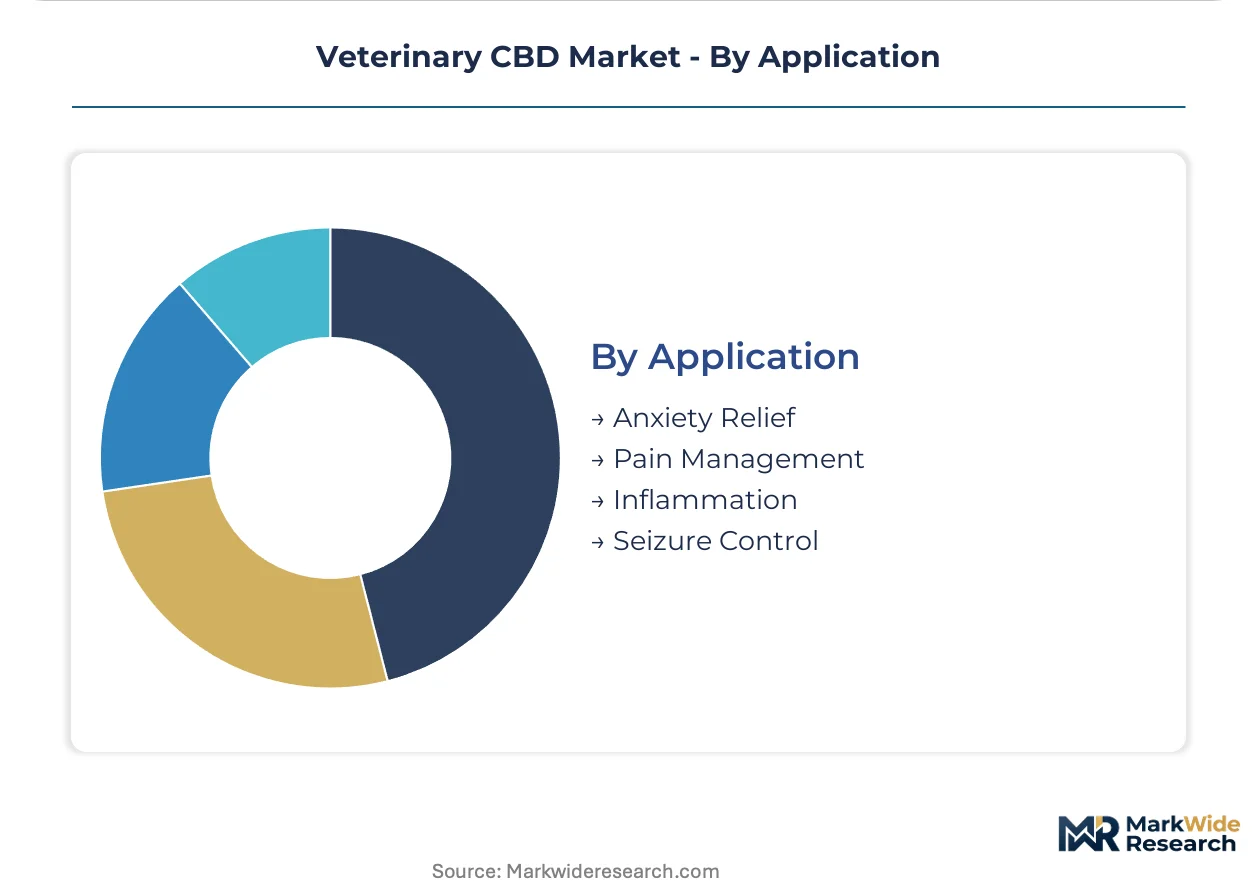
Application:
Therapeutic indication determines pricing power and clinical evidence requirements, with behavioral applications commanding premium positioning over physiological symptom management.
- Anxiety Relief:Formulations targeting noise phobia and separation distress in dogs, representing the fastest-expanding buyer segment. Pet owner willingness to pay for behavioral outcomes sustains premium pricing, though FDA regulatory friction restricts marketing claims and limits distribution through conventional pet food retail channels.
- Pain Management:Traditional cannabinoid application for osteoarthritis and post-surgical discomfort, established but facing competition from conventional analgesics with clearer regulatory pathways.
- Inflammation:Anti-inflammatory applications for joint health and immune modulation, requiring longer duration studies to demonstrate efficacy.
- Seizure Control:Epilepsy management in companion animals, constrained by veterinary pharmacology expertise scarcity and limited cannabinoid therapeutics training in veterinary school curricula.
Anxiety relief leads revenue contribution. Seizure control is expanding most quickly as clinical trial infrastructure develops.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denver anchors veterinary CBD commercial activity through its concentration of hemp processing facilities and specialty pet wellness retail chains that serve the Rocky Mountain corridor.
United States
Urban pet owners in California and Colorado drive anxiety-relief product demand through subscription platforms and veterinary clinic networks. The 2018 Farm Bill and evolving state-level hemp statutes reshape interstate commerce legality for hemp-derived ingredients. Denver and Boulder clusters host vertically integrated processors that control cultivation through retail distribution.
Canada
Health Canada maintains strict cannabinoid oversight for veterinary products while allowing hemp-derived CBD under industrial hemp regulations. Cannabis Act frameworks create parallel compliance pathways that manufacturers navigate for companion animal formulations. Ontario's Greater Toronto Area concentrates distribution infrastructure serving cross-border veterinary clinic networks.
Germany
BfArM guidelines for novel food ingredients extend to pet supplement categories, requiring toxicological documentation for CBD product registration. German pet owners demonstrate willingness-to-pay premiums for third-party certified formulations. Bavaria's pharmaceutical manufacturing corridor supplies analytical testing services that support Certificate of Analysis standardization.
United Kingdom
VMD regulatory ambiguity restricts veterinary cannabinoid prescribing while FSA novel food authorizations create compliance templates for pet supplement manufacturers. London's specialty pet retail density supports premium product positioning for anxiety-relief applications. The M25 corridor hosts import distribution centers managing EU-origin hemp ingredient logistics.
Australia
APVMA scheduling controls limit veterinary cannabinoid availability to prescription pathways, compressing retail market development relative to North American benchmarks. Sydney and Melbourne metropolitan areas concentrate companion animal veterinary expenditure that could support future category expansion. TGA guidance on human CBD products creates precedent frameworks that industry stakeholders monitor for veterinary application.
Veterinary CBD Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification and channel access dimensions. The sector structures around three tiers: seed-to-shelf vertically integrated operators, direct-to-consumer subscription specialists, and white-label commodity suppliers. Strategic moves concentrate on veterinary clinic channel penetration and pharmacokinetic validation partnerships that preempt regulatory standardization.
Within the clinical-channel tier, Pet Releaf and Charlotte's Web occupy positions that exemplify compliance-forward positioning through Certificate of Analysis documentation and veterinary practice procurement standards. Honest Paws represents the direct-to-consumer archetype with subscription-based distribution that bypasses intermediary markups. These three companies collectively illustrate how channel selection determines margin architecture and customer data asset accumulation in a category shaped by FDA enforcement discretion.
| Leading Market Players |
|---|
| Pet Releaf |
| Canna-Pet |
| HolistaPet |
| King Kanine |
| Honest Paws |
| Charlotte's Web |
| HempMy Pet |
| cbdMD |
| Joy Organics |
| Others |
Value Chain & Pricing Dynamics
Family-owned hemp cultivation operations in Kentucky and Oregon anchor upstream supply, translating weather-dependent biomass yields into volatile input costs that compress margin stability for brands lacking captive agricultural supply. This ownership pattern forces pricing discipline through backward integration premiums while exposing non-integrated competitors to commodity spot pressure.
Pricing Analysis
Outcome-based pricing tied to anxiety relief efficacy anchors premium positioning in the veterinary CBD sector. Three-tier pricing structure across premium, standard, and economy levels separates full-spectrum formulations with third-party Certificate of Analysis documentation from commodity-grade alternatives with minimal traceability. Pricing pressure stems from organic hemp biomass volatility as weather-dependent cultivation yields in Kentucky and Oregon fluctuate seasonally. Veterinary clinics demonstrate lowest price sensitivity due to prescriptive confidence requirements, while mass-market pet owners exhibit highest elasticity.
Supply Chain Analysis
Regional distribution centers in Denver and Boulder coordinate hub-and-spoke patterns serving North American urban markets with established pet wellness retail infrastructure. Hemp biomass concentrates in Kentucky, Oregon, and Colorado under USDA hemp production program oversight. Supercritical CO2 extraction equipment and third-party testing laboratory capacity constitute critical input dependencies. Single-source vulnerability runs through limited FDA-approved analytical testing facilities for veterinary cannabinoid documentation. Distribution runs through specialty pet retail chains and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The veterinary CBD market operates as a supply-constrained environment where certified organic hemp acreage and third-party testing laboratory capacity prop pricing power for compliant manufacturers.
For Market Incumbents: Lock in veterinary clinic channel access through pharmacokinetic validation partnerships and dosing protocol development that preempts FDA rulemaking on efficacy standards. Secure captive hemp supply through agricultural partnerships in Kentucky and Oregon to defend against input cost volatility from weather-dependent cultivation yields. Certification investment in USDA organic and third-party Certificate of Analysis documentation represents the critical lever against white-label commodity competitors. For New Entrants and Emerging Players: Nanoemulsion technology for sublingual tincture bioavailability enhancement offers a technology-first wedge into underpenetrated independent veterinary practice channels. Target metropolitan areas with high veterinary clinic density and premium pet product consumption patterns in California and Colorado. Subscription-based direct-to-consumer distribution bypasses intermediary markups while building proprietary customer data assets for personalized formulation development. For Investors and Strategic Acquirers: Distressed-cycle entries favor seed-to-shelf vertically integrated operators with in-house quality infrastructure in Oregon and Colorado. Long-term viability hinges on regulatory clarity from FDA Center for Veterinary Medicine rulemaking on cannabinoid safety data requirements. The signal to watch is multi-site clinical trial publication in peer-reviewed veterinary journals indicating prescriptive confidence inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Clinical Trial Partnership | Pet Releaf's pharmacokinetic validation secures shelf space in independent practices prioritizing Certificate of Analysis documentation. |
| Seed-to-Shelf Vertical Integration | Charlotte's Web's hemp cultivation control commands premium positioning in specialty pet retail through traceability assurance. |
| Subscription Direct-to-Consumer Launch | Honest Paws' recurring revenue model builds proprietary customer data assets while bypassing intermediary markups. |
| Nanoemulsion Technology Licensing | Bioavailability enhancement below 100 nanometers displaces conventional oil-based competitors in California and Colorado clinics. |
| Regulatory Pre-Compliance Investment | Early FDA safety data portfolio development anticipates stricter efficacy standards before formal rulemaking publication. |
Study Parameters
USDA hemp production program filings, state agriculture department testing protocols, and FDA Center for Veterinary Medicine enforcement discretion records formed the secondary backbone of this analysis. Primary interviews with veterinary pharmacology researchers, independent practice procurement managers, specialty pet retail category buyers, and hemp cultivation operators in Kentucky and Oregon combined with secondary validation. Bottom-up product-level volume estimation and top-down category value triangulation anchored market sizing across the analysis window.
Historical trendline analysis of hemp-derived ingredient pricing and veterinary cannabinoid product adoption patterns informed projection modeling. Segmentation dimensions included product type, delivery mode, application indication, and end-user channel. CAGRs derived from regression analysis of volume trajectories adjusted for regulatory scenario weighting. Forecast inputs incorporated USDA hemp acreage expansion data and veterinary school curriculum evolution on cannabinoid therapeutics training.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA formal approval pathway announcements or state-level hemp statute restrictions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cannabis/Marijuana
Middle East and Africa CBD Patch Market
Cannabis/Marijuana
Arizona Legal Cannabis Market
Cannabis/Marijuana
Cannabidiol Extract Market
Cannabis/Marijuana
US Cannabinoids Market
Cannabis/Marijuana
Medical Cannabis Market
Cannabis/Marijuana
Butane Hash Oil Market
Cannabis/Marijuana
US Minor Cannabinoids Market
Cannabis/Marijuana
Handheld Marijuana Vaporizer Market
Cannabis/Marijuana
North America Medical Cannabis Market
Cannabis/Marijuana
Asia-Pacific Medical Cannabis Market
Cannabis/Marijuana
North America Cannabidiol (CBD) Market
Cannabis/Marijuana
Global Cannabis ERP Software Market
Cannabis/Marijuana
Medical Marijuana Market
Cannabis/Marijuana
CBD Hemp Oil Market
Cannabis/Marijuana
Global Cannabidiol (CBD) Vape Juice Market
Cannabis/Marijuana
Asia-Pacific Cannabidiol (CBD) Vape Juice Market