
 Candy Wrapping Machine Market | 2026-2036
Candy Wrapping Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Candy Wrapping Machine Market Outlook
Biodegradable film substrates is consolidating around candy wrapping equipment as brand owners abandon conventional multilayer plastics. Bosch Packaging Technology leverages its Swiss-German engineering heritage to anchor premium flow-wrapping lines for artisan confectioners. SACMI competes through ceramic-to-packaging diversification, while Theegarten-Pactec specializes in ultra-high-speed twist-wrapping systems for hard candies.
A candy wrapping machine is an automated packaging system that forms, seals, and cuts flexible film around individual or grouped confectionery units at speeds typically ranging from 100 to 1,200 pieces per minute, designed to preserve product freshness, enable portion control, and deliver shelf-ready presentation. Horizontal wrapping machines occupy the largest installed base across European and North American facilities due to proven reliability with chocolate bars and tablet candies. Servo-driven technology leads growth trajectories as electronic motion control replaces mechanical cam systems, enabling format changeovers without tool swaps and reducing film waste by enabling precise registration of printed webs.
Food contact compliance under FDA regulations in the United States and EU Framework Regulation 1935/2004 governs all materials contacting confectionery surfaces, directly influencing machine design for cleanability and material traceability. CE marking requirements under the EU Machinery Directive mandate interlocked guarding and emergency stop architectures that add engineering cost but create market access barriers for non-compliant imports. Stakeholders must monitor how extended producer responsibility legislation across multiple jurisdictions reshapes total cost of ownership calculations for wrapping equipment.
Market Dynamics
Servo-driven electric architectures are displacing pneumatic systems across confectionery packaging lines as the EU's F-Gas Regulation and REACH directives phase out fluorinated greenhouse gas components in industrial equipment.
Growth Catalysts
- Biodegradable film mandates:Extended producer responsibility legislation across Germany, France, and Italy compels confectioners to source machines compatible with compostable substrates. Equipment retrofits accelerate to maintain shelf-ready compliance.
- CE marking under Machinery Directive:Interlocked guarding and emergency stop architectures create technical barriers for non-compliant imports, protecting established European equipment manufacturers from low-cost competition.
- Stuttgart-Cologne engineering cluster:Precision automation suppliers concentrate in southwestern Germany, enabling rapid prototyping and reducing lead times for format changeover tooling.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316 price fluctuations compress margins for machine builders sourcing food-contact frames and contact parts from Asian mills.
- High-voltage servo motor supply concentration:Permanent magnet synchronous motor production clusters in China, creating single-source dependency risks for European OEMs.
- Multilayer film legacy infrastructure:Existing thermoforming and laminating assets at contract packers delay capital redeployment toward mono-material-compatible wrapping lines.
Strategic Opportunities
- Artisan confectionery automation:Small-batch chocolate producers in Belgium and Switzerland seek mid-speed flow-wrappers with quick format change capability, a segment underserved by high-volume specialists.
- EU Green Deal capital subsidies:National recovery funds in Spain and Poland finance energy-efficient equipment upgrades, creating tender pipelines for servo-electric system vendors.
- Pharma-confectionery convergence:Nutraceutical gummy manufacturers require hygienic design standards borrowed from pharmaceutical packaging, opening specification gaps for compliant machine builders.
Industry Challenges
- Motion control programming deficit:Confectionery plants lack technicians trained in servo drive parameterization and electronic cam profiling, forcing OEMs to embed commissioning support into equipment pricing.
- FDA-EU dual certification timelines:Export-oriented builders face 14-18 month validation cycles to satisfy both FDA food contact requirements and EU Framework Regulation 1935/2004 material traceability protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Candy Wrapping Machine Market |
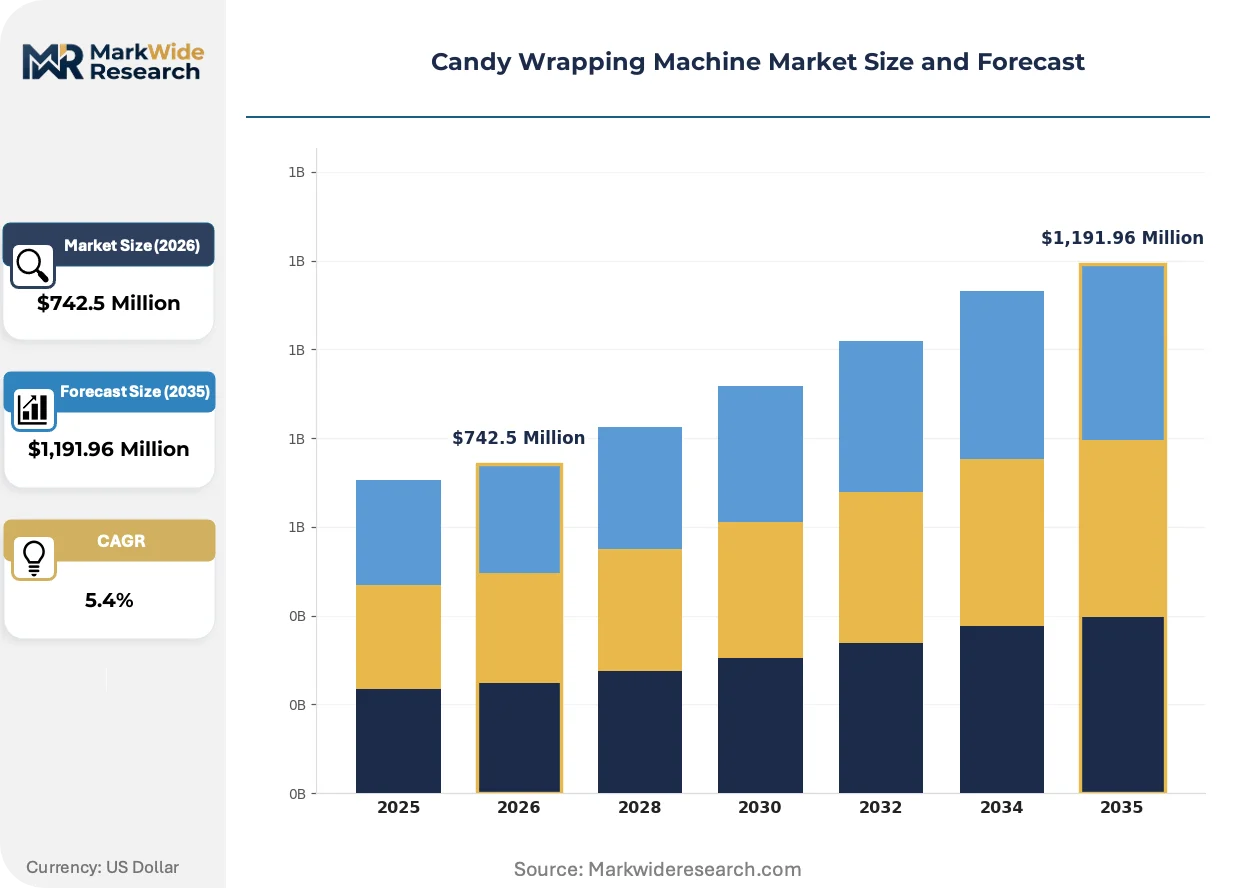
| Market Size in 2026 | $742.5 Million |
| Market Size in 2035 | $1,191.96 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Wrapping Machine, Vertical Wrapping Machine, Flow Wrapping Machine, Automatic Wrapping Machine Technology: Mechanical, Servo-driven, Pneumatic, Electronic End User: Candy Manufacturers, Confectionery Businesses, Snack Producers, Food Packaging Companies Deployment: In-house Production, Contract Packaging, Custom Packaging Solutions, OEM Services |
| Companies Covered | Bosch Packaging Technology, IMA Group, SACMI, Denny Bros, Fuji Machinery, Syntegon Technology, Theegarten-Pactec, Gerhard Schubert, PFM Packaging Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Candy Wrapping Machine Market Strategic Shifts
Digital twin technology and predictive maintenance algorithms are compressing downtime windows across high-speed wrapping operations, while regulatory pressure on refrigerants and films forces simultaneous hardware and materials evolution.
Ultrasonic sealing heads are unifying previously separate thermal and mechanical sealing stations into single-axis motion systems. Mid-tier chocolate manufacturers in the Netherlands and Austria adopt these heads to reduce film waste through precise energy delivery. The technology is unifying machine footprints and enabling cleanroom-compatible designs previously reserved for pharmaceutical lines.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating fluoropolymer coatings from sealing jaws and forming collars. German equipment builders reformulate surface treatments using ceramic plasma deposition to maintain release properties. Hard candy specialists dependent on high-temperature wrapping face the steepest retrofit requirements.
Confectionery brands now bundle wrapping equipment procurement with decade-long service contracts covering predictive parts replacement and remote diagnostics. Regional cooperatives in northern Italy and Bavaria aggregate demand to secure fleet-level pricing and guaranteed uptime clauses. This contracting shift concentrates vendor relationships among integrators with established field service networks.
Candy Wrapping Machine Market Segmentation
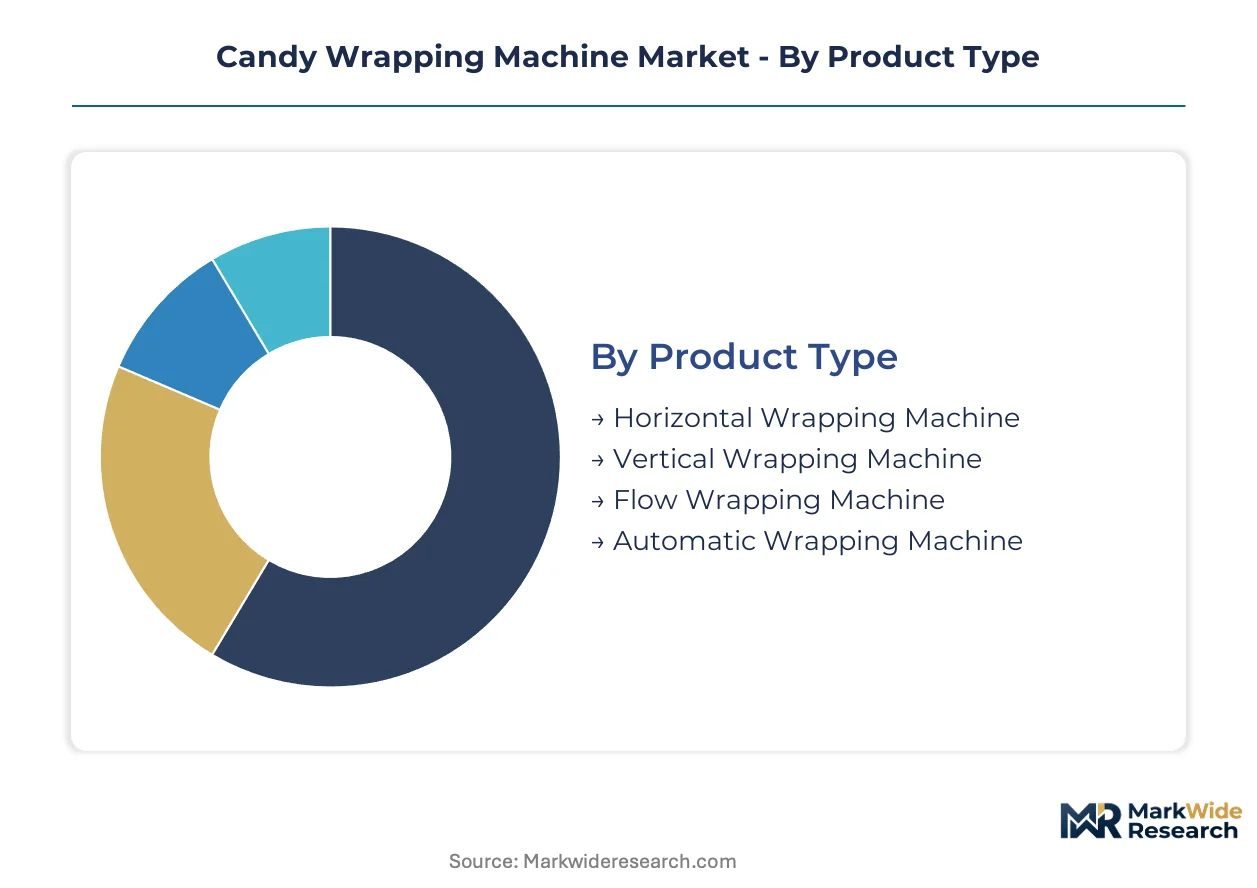
Candy wrapping equipment segments by motion architecture, film handling geometry, and buyer integration strategy. Each axis determines capital intensity, regulatory exposure, and aftermarket service attach rates differently.
Product Type:
Buyers differentiate by throughput ceiling and footprint constraints, with speed requirements and factory floor geometry driving selection trade-offs.
- Horizontal Wrapping Machine:These systems feed product through a forming collar while film travels horizontally, achieving tight seals on chocolate bars and tablet candies. German and Swiss confectioners anchor demand here, prioritizing servo-driven registration for printed film webs that must align with seasonal branding.
- Flow Wrapping Machine:Continuous motion systems draw film from a roll around products on a conveyor, sealing via longitudinal fin wheels and end crimpers. Belgian artisan chocolate producers specify mid-speed variants with 15-minute changeover capability to accommodate small-batch SKUs.
- Vertical Wrapping Machine:Film forms a tube around vertically dropped products, suited to irregular shapes like pralines. Limited adoption outside hard candy applications.
- Automatic Wrapping Machine:Fully integrated lines with infeed collation and discharge stacking. Large North American contract packers favor these for labor cost reduction.
Volume sits with horizontal configurations; growth tilts toward flow wrapping as artisan automation accelerates.
Technology:
Capital deployment patterns split between legacy mechanical reliability and electronic precision, with regulatory pressure now forcing migration timelines.
- Servo-driven:Electronic motion control replaces mechanical cams with programmable virtual equivalents, enabling format changeovers without physical tooling swaps. REACH and F-Gas Regulation compliance in the EU accelerates displacement of pneumatic alternatives, particularly at Stuttgart-area engineering clusters serving premium confectioners.
- Mechanical:Cam-driven systems with fixed motion profiles offer lower first cost and proven uptime in high-volume, stable-SKU environments. Eastern European sugar confectioners maintain installed bases here due to technician familiarity and spare parts availability.
- Pneumatic:Compressed air actuation for sealing jaws and film transport faces phase-out pressure from fluorinated gas restrictions.
- Electronic:Hybrid architectures combining servo axes with centralized PLC control, gaining traction in retrofit applications.
Servo-driven platforms command the steepest expansion trajectory; mechanical retains share in cost-sensitive sugar candy segments.
End User:
Buyer sophistication varies by regulatory exposure and product margin structure, with pharma-adjacent requirements emerging as a segmentation force.
- Candy Manufacturers:Integrated producers with captive wrapping operations, typically running 24/7 schedules. These buyers specify predictive maintenance contracts and remote diagnostics, with northern Italian cooperatives aggregating fleet-level service agreements.
- Confectionery Businesses:Mid-tier chocolate and sugar specialists balancing automation with craft positioning. Swiss and Belgian operators in this tier seek quick-change format capability to preserve small-batch flexibility.
- Snack Producers:Diversified food manufacturers with wrapping needs secondary to core savory operations. Price sensitivity concentrates procurement decisions.
- Food Packaging Companies:Contract packers serving multiple confectionery brands, prioritizing throughput over changeover speed. Extended producer responsibility legislation complicates their equipment sourcing as brand owners push compliance downstream.
Volume concentrates with integrated candy manufacturers; expansion tilts toward nutraceutical gummy producers requiring pharma-grade hygienic design.
Deployment:
Make-versus-buy decisions reflect asset specificity, with service integration emerging as the decisive procurement criterion.
- In-house Production:Captive wrapping lines owned and operated by confectionery brands, typical at scale manufacturers with stable demand profiles. These buyers negotiate decade-long service contracts bundling equipment, parts replacement, and uptime guarantees.
- Contract Packaging:Third-party wrapping services at dedicated facilities, prevalent among emerging brands testing market traction before capital commitment. EU Green Deal capital subsidies in Spain and Poland finance energy-efficient line upgrades at these operators.
- Custom Packaging Solutions:Engineered-to-order systems for unique product geometries or film substrates. Hard candy specialists requiring high-temperature sealing specifications drive demand here.
- OEM Services:Original equipment manufacturer arrangements where machinery builders supply private-label wrapping lines to integrated food companies. German precision engineering clusters dominate this tier.
Contract packaging carries the largest installed base; in-house production gains share as extended producer responsibility tightens supply chain control requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart's precision engineering cluster anchors European equipment sourcing through Germany's Industrie 4.0 tax incentives, while extended producer responsibility laws across multiple jurisdictions reshape capital deployment patterns.
Germany
Baden-Württemberg's automation suppliers concentrate around Stuttgart, serving premium confectioners with servo-driven systems. The F-Gas Regulation accelerates displacement of pneumatic components in wrapping lines. Cologne-Düsseldorf engineering networks reduce format changeover tooling lead times through rapid prototyping capabilities.
United States
Midwest contract packers drive demand for automatic wrapping lines with integrated discharge stacking. FDA food contact compliance requirements govern machine design for cleanability and material traceability. Chicago-area facilities prioritize predictive maintenance contracts bundling equipment with decade-long service agreements.
Italy
Northern Italian cooperatives aggregate fleet-level demand for wrapping equipment with guaranteed uptime clauses. Extended producer responsibility legislation compels equipment retrofits for compostable substrate compatibility. Emilia-Romagna's packaging machinery builders specialize in mid-speed flow-wrappers for artisan chocolate producers.
Switzerland
Swiss chocolate manufacturers seek quick-change format capability to preserve small-batch flexibility. REACH Annex XVII restrictions on fluoropolymer coatings force reformulation of sealing jaw surface treatments. Zurich-Basel engineering corridors anchor hygienic design standards borrowed from pharmaceutical packaging.
China
Permanent magnet synchronous motor production clusters create supply concentration for European OEMs sourcing servo systems. The country's dual carbon goals pressure equipment imports toward energy-efficient architectures. Yangtze River Delta fabricators compete on cost-sensitive sugar candy segments with mechanical cam-driven systems.
Candy Wrapping Machine Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated OEMs commanding premium pricing through embedded service networks while regional fabricators compete on first cost. The vendor base organizes around three archetypes: precision engineering clusters serving artisan confectioners, scale-oriented builders targeting high-volume contract packers, and diversified industrial groups leveraging cross-sector packaging expertise. Strategic moves concentrate on portfolio diversification into adjacent pharma-confectionery applications and backward integration into motion control components to reduce supply dependency.
Within the precision-engineering tier, Bosch Packaging Technology and Theegarten-Pactec occupy positions anchored by Swiss-German heritage, while SACMI exemplifies diversified industrial-group expansion from ceramic processing into packaging machinery. These named entities represent archetypal competitive positioning rather than exhaustive market coverage, with geographic origin and corporate structure derivable from nomenclature.
| Leading Market Players |
|---|
| Bosch Packaging Technology |
| IMA Group |
| SACMI |
| Denny Bros |
| Fuji Machinery |
| Syntegon Technology |
| Theegarten-Pactec |
| Gerhard Schubert |
| PFM Packaging Machinery |
| Others |
Value Chain & Pricing Dynamics
Servo-electric versus mechanical cam divergence splits the candy wrapping machine market into premium precision tiers and commodity volume segments, with Stuttgart engineering clusters commanding pricing power through embedded motion control expertise while Asian fabricators compete on stainless steel frame economics.
Pricing Analysis
Volume versus margin splits sharply across buyer archetypes. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with CE-marked servo systems from German engineering clusters commanding substantial premiums over mechanical alternatives from Eastern European suppliers. Pricing pressure stems from stainless steel input volatility compressing builder margins, particularly for food-contact Grade 304 and 316 components sourced from Asian mills. Contract packers exhibit highest price sensitivity due to extended producer responsibility compliance costs pushed downstream, while integrated candy manufacturers prioritize uptime guarantees over first-cost minimization.
Supply Chain Analysis
Reverse logistics flows for servo motor refurbishment and sealing jaw recoating create secondary supply channels that extend equipment lifecycle and dampen replacement demand. Permanent magnet synchronous motor production clusters in China, Germany, and Japan anchor upstream supply, with European OEMs drawing from Chinese sources for cost-sensitive configurations. Food-grade stainless steel, ceramic plasma deposition materials, and biodegradable film substrate compatibility kits constitute critical input dependencies. Single-source vulnerability concentrates in high-voltage servo motor supply. Distribution runs through regional engineering clusters with embedded field service networks, particularly the Stuttgart-Cologne corridor and northern Italian packaging machinery districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The candy wrapping machine market is becoming a vertical-integration race as builders pursue backward control over motion control components to reduce dependency on Chinese permanent magnet motor suppliers.
For Market Incumbents: Deploy predictive maintenance service bundling to lock in decade-long contracts with northern Italian cooperatives and Bavarian fleet operators. Incumbents should deepen backward integration into servo drive programming tools to offset technician scarcity forcing embedded commissioning support costs. The threat of nutraceutical gummy producers demanding pharma-grade hygienic design standards creates specification gaps that compliant builders can capture.
For New Entrants and Emerging Players: Capture artisan confectionery automation white space in Belgian and Swiss mid-speed flow-wrapper segments underserved by high-volume specialists. New entrants should target Poland and Spain where EU Green Deal capital subsidies finance energy-efficient equipment tenders. A go-to-market angle emphasizing 15-minute format changeover capability for small-batch SKU producers offers differentiation against established high-speed specialists.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial groups seeking pharma-confectionery convergence exposure. Long-term viability hinges on servo-electric architecture dominance as F-Gas Regulation phase-outs eliminate pneumatic alternatives. Acquisition targets should display embedded field service networks in Stuttgart-area engineering clusters. The signal to watch is REACH Annex XVII fluoropolymer restriction enforcement tightening retrofit demand from hard candy specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Motors | Reduces single-source dependency on Chinese permanent magnet suppliers for European OEMs. |
| Pharma-Grade Hygienic Design Certification | Opens nutraceutical gummy specification gaps requiring FDA-EU dual compliance capabilities. |
| Biodegradable Film Compatibility Retrofit | Captures extended producer responsibility-driven demand from German and Italian confectioners. |
| Predictive Maintenance Service Bundling | Locks in fleet-level pricing with northern Italian cooperatives aggregating regional demand. |
| Ultrasonic Sealing Head Platform Launch | Enables cleanroom-compatible designs for Dutch and Austrian mid-tier chocolate manufacturers. |
Study Parameters
Multi-period observation of servo-electric adoption rates, biodegradable film mandate enforcement, and engineering cluster output volumes anchored the trend analysis, supplemented by interviews with plant engineers at integrated candy manufacturers, procurement leads at contract packers, aftermarket service heads at German OEMs, and regulatory affairs specialists tracking REACH implementation. Secondary validation drew from EU F-Gas Regulation filings, CE marking certification databases, customs records of stainless steel machinery imports, and SEC disclosures from diversified industrial groups with packaging machinery segments. Bottom-up equipment shipment tracking triangulated against top-down confectionery production capacity estimates.
Input-output matrix modeling connected motion architecture segmentation to end-user buyer archetypes across the projection horizon. Segmentation dimensions included technology tier, film handling geometry, deployment strategy, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and greenfield capacity expansion pipelines. Industry-specific forecast inputs incorporated EU Green Deal capital subsidy allocation patterns and F-Gas Regulation phase-out timelines for pneumatic components.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to permanent magnet motor supply chain reconfiguration and biodegradable film substrate performance validation. Practitioners should monitor REACH Annex XVII enforcement intensity and stainless steel price volatility for early signals of margin compression or retrofit demand acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Plastic Vacuum Forming Machinery Market
Packaging Machinery
Blind Box Machine Market
Packaging Machinery
Carton Erecting Machinery Market
Packaging Machinery
Tissue Paper Unwinding Machine Market
Packaging Machinery
Extrusion Press Market
Packaging Machinery
Volumetric Boom Filling Machine Market
Packaging Machinery
Toilet Roll Converting Lines Market
Packaging Machinery
Die Cutting Machine Market
Packaging Machinery
Case Packing Machines Market
Packaging Machinery
Global Hand Wrapping Machine Market
Packaging Machinery
Vacuum Sealing Machine Market
Packaging Machinery
Global Paper Napkin Making Machine Market
Packaging Machinery
Tubular Form Fill and Seal Machines Market
Packaging Machinery
Bottle Blowing Machine Market
Packaging Machinery
Piston Fillers Market
Packaging Machinery
Lamination Systems Market