
 Tubular Form Fill and Seal Machines Market | 2026-2036
Tubular Form Fill and Seal Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Tubular Form Fill and Seal Machines Market Analytics
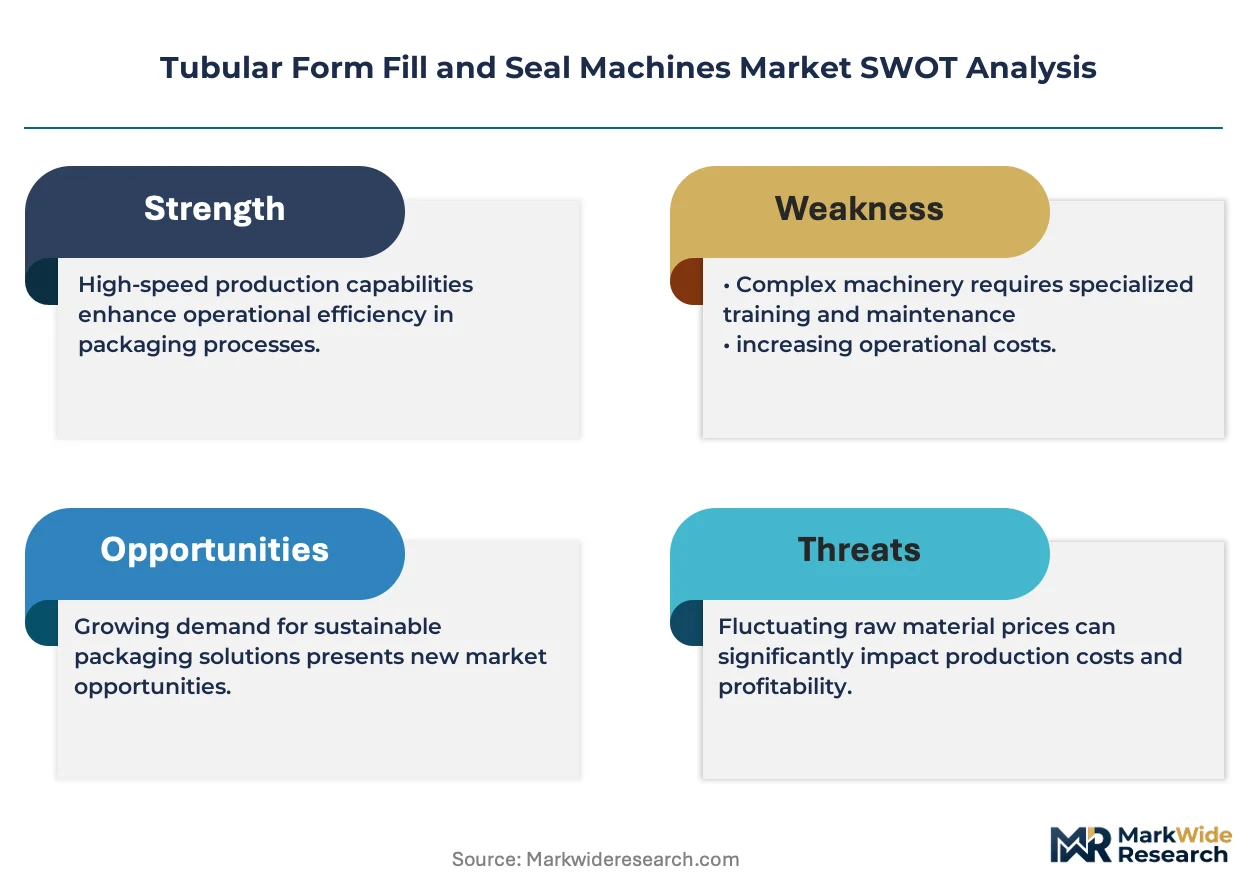
The gap between premium and commodity tiers in tubular form fill and seal equipment is broadening as high-speed aseptic systems command widening price premiums over basic vertical baggers. Concetti S.p.A. leverages Italian engineering heritage to dominate precision weighing and dosing integrations for agricultural bulk products. Syntegon sustains technology leadership in continuous-motion horizontal platforms for pharmaceutical sachet formats. ProMach anchors North American market presence through diversified brand portfolio coverage across food and consumer goods installations.
Tubular form fill and seal machines form, fill, and seal flexible packaging from continuous tubular film stock at speeds reaching 200+ cycles per minute, with sealing temperatures typically spanning 120°C to 220°C depending on film laminate composition; these systems serve primary packaging functions for free-flowing powders, granules, and small-piece solids across automated production lines. Vertical machines retain volume dominance in commodity food packaging where gravity-fed product flow minimizes mechanical complexity, while aseptic technology commands concentrated margin pools in dairy and ready-to-eat segments requiring validated sterile boundaries. Modified atmosphere packaging is displacing standard gas-flush configurations in premium meat and seafood applications as shelf-life extension becomes a decisive purchasing criterion.
FDA validation requirements for pharmaceutical contact surfaces and USDA sanitation standards for dairy-grade equipment create dual compliance burdens for manufacturers serving cross-industry clients, while CE marking under the EU Machinery Directive mandates documented risk assessments for all systems deployed in Europe. The EU F-Gas Regulation progressively restricts hydrofluorocarbon-based sealing technologies, redirecting R&D investment toward induction and impulse heat-seal alternatives. Stakeholders must weigh regulatory trajectory against capital replacement cycles when configuring regional product portfolios and service networks.
Market Dynamics
Sealing technology electrification is compressing thermal cycle times and eliminating refrigerant-dependent systems, forcing incumbents to reconfigure R&D roadmaps around induction heat-seal architectures. This transition is reshaping competitive positioning between European precision engineering houses and Asian cost-optimized suppliers.
Growth Catalysts
- EU F-Gas Regulation:Progressive hydrofluorocarbon phase-down mandates are redirecting capital toward impulse and induction sealing platforms, creating replacement demand across dairy and pharmaceutical packaging lines.
- Modified atmosphere packaging:Premium meat and seafood processors are specifying gas-barrier tubular films with validated residual oxygen control, pulling high-performance machine configurations into protein processing facilities.
- India:Domestic packaging machinery clusters in Pune and Ahmedabad are scaling capacity to serve regional processed food brands, reducing import dependence for mid-speed vertical baggers.
Market Restraints
- Laminate film cost volatility:Multi-layer coextruded structures with ethylene-vinyl alcohol barriers face input price swings from petrochemical feedstock markets, compressing OEM margins on fixed-price contracts.
- Precision servo component concentration:High-resolution motion control systems for continuous-motion horizontal platforms rely on Japanese and German suppliers, exposing lead time risks during supply disruptions.
- USDA dairy-grade validation:Sanitation standards requiring 3-A SSI-compliant contact surfaces add engineering burden and extend commercialization timelines for cross-industry equipment vendors.
Strategic Opportunities
- Vietnam and Indonesia:Underpenetrated processed seafood export sectors present whitespace for aseptic tubular baggers with integrated metal detection and checkweighing modules.
- Induction-ultrasonic hybrid sealing:Convergent heat-seal technologies are enabling hermetic closure of recyclable mono-material films without thermal degradation of seal integrity.
- India PLI scheme:Production-linked incentives for machinery manufacturing are attracting component suppliers to establish captive machining and assembly operations near Ahmedabad industrial corridors.
Industry Challenges
- Mechatronics integration expertise:Shortage of engineers capable of synchronizing servo-driven film transport with precision dosing systems is extending commissioning timelines for complex multi-lane installations.
- FDA pharmaceutical validation cycles:IQ/OQ/PQ documentation requirements for contact surface compliance are stretching project durations by 6-12 months for vendors serving cross-industry clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tubular Form Fill and Seal Machines Market |
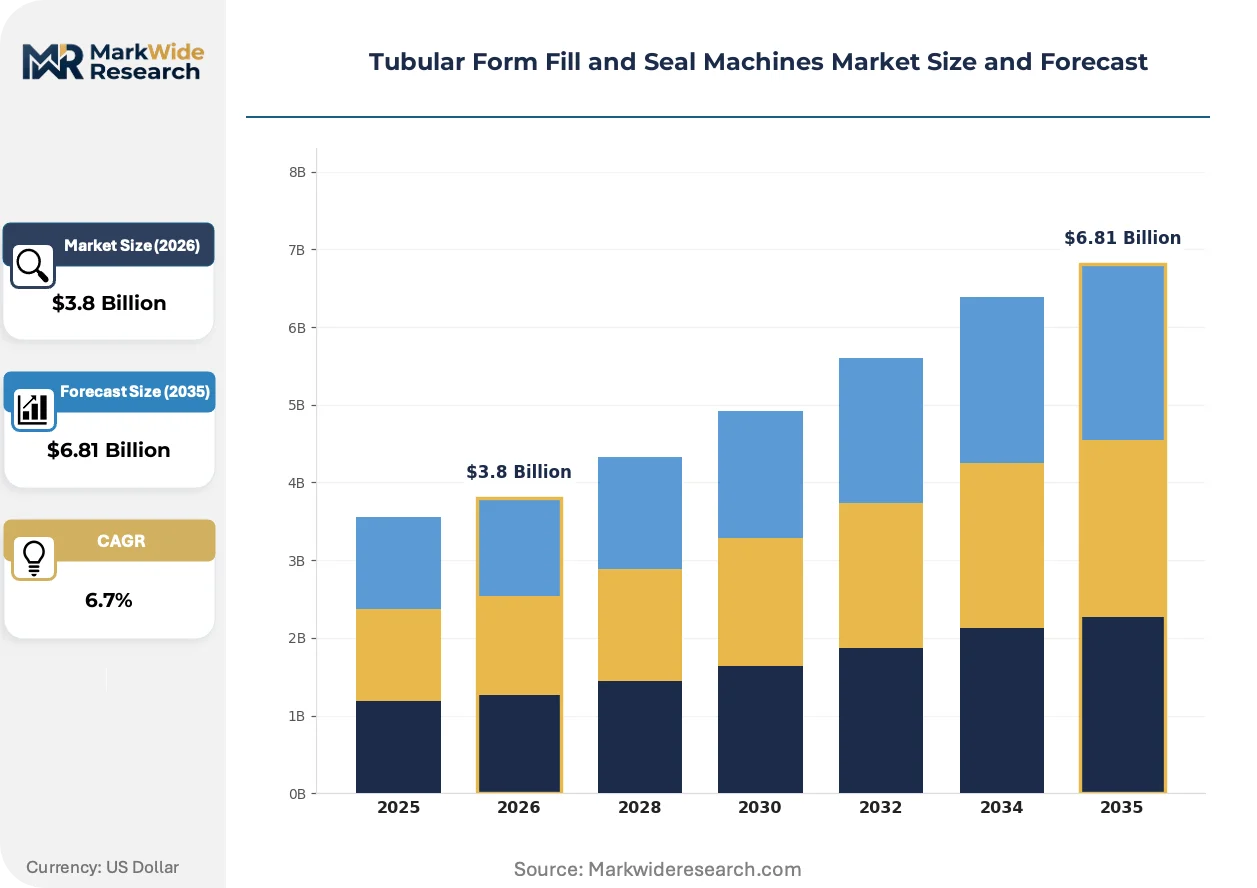
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
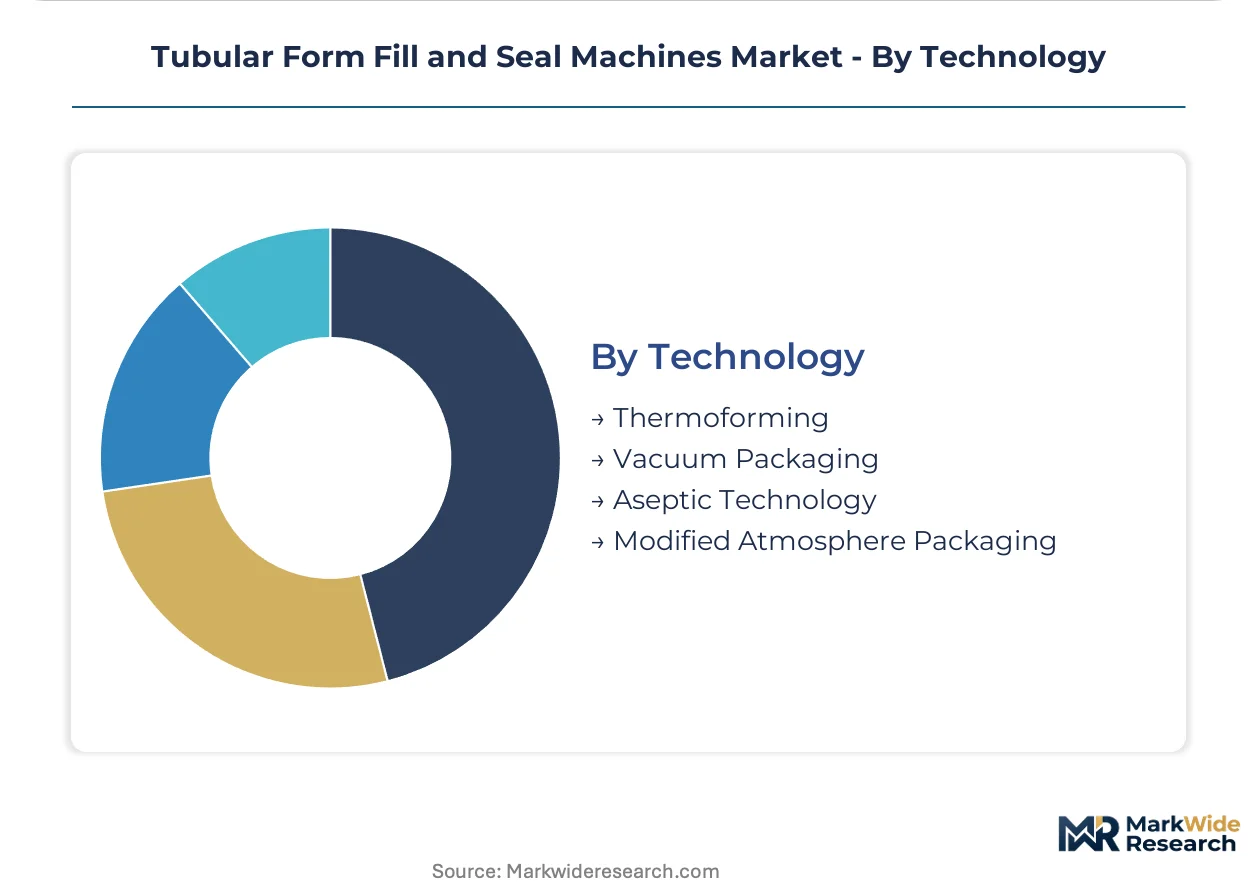
| Segmentation | Product Type: Vertical Machines, Horizontal Machines, Automatic Machines, Semi-Automatic Machines Application: Food Packaging, Pharmaceutical Packaging, Consumer Goods, Industrial Products End User: Food Processing, Healthcare, Personal Care, Chemical Industry Technology: Thermoforming, Vacuum Packaging, Aseptic Technology, Modified Atmosphere Packaging |
| Companies Covered | Concetti S.p.A., Premier Tech Chronos, Cordano Packaging Engineers, Hastamat Verpackungstechnik GmbH, Webster Griffin, Weber Waagenbau und Wägeelektronik GmbH, Ehcolo A/S, ProMach, Syntegon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tubular Form Fill and Seal Machines Market Evolving Landscape
Active materials and control architectures are compressing machine footprints while elevating seal integrity validation. These developments are concentrating investment in three domains: thermal system electrification, regulatory-driven material transitions, and service model restructuring.
Induction heat-seal technology is electrifying the replacement of conventional resistance-barrier sealing in dairy and pharmaceutical applications. European OEMs are retrofitting existing horizontal platforms with solid-state RF generators to eliminate F-Gas-dependent cooling circuits. This transition is compressing maintenance intervals and enabling validated sterile boundaries without refrigerant infrastructure.
EU F-Gas Regulation restrictions on hydrofluorocarbon-based sealing technologies are forcing laminate suppliers to qualify impulse-seal-compatible barrier structures. Machinery OEMs must now validate temperature-pressure dwell profiles across wider film gauge ranges. Dairy and ready-to-eat segments are responding by specifying equipment with programmable seal recipe libraries covering 80-250 micron film spans.
Service contract unbundling is fragmenting traditional full-service agreements into modular performance guarantees. Food processors are purchasing base hardware with separately negotiated uptime commitments and remote diagnostics subscriptions. This pattern is most visible in German and Benelux installations where operating lease structures are displacing outright equipment purchases.
Tubular Form Fill and Seal Machines Market Segmentation
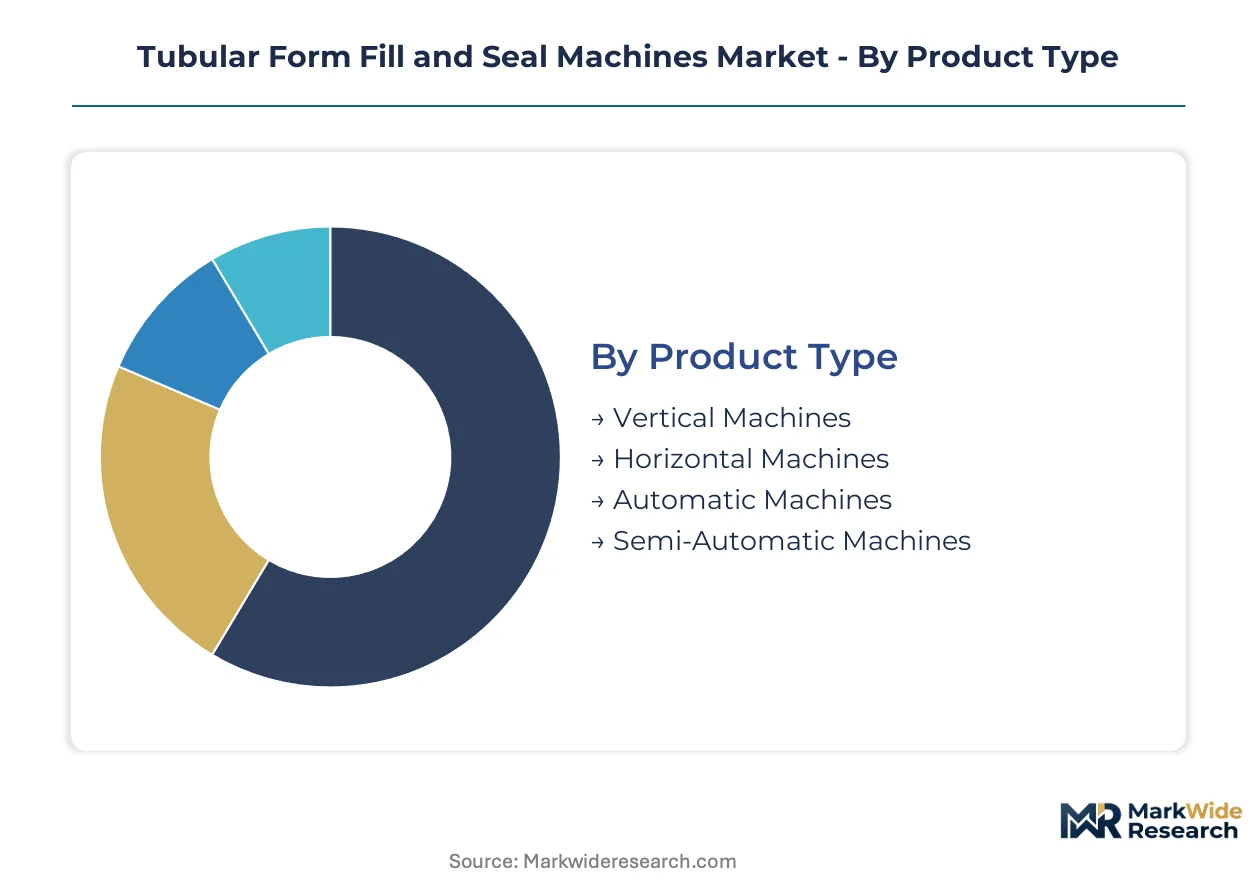
Segmentation in tubular form fill and seal equipment reveals how regulatory compliance burdens and production scale requirements fragment purchasing behavior across installation types. Certification thresholds for pharmaceutical and dairy applications create distinct specification tiers that reshape vendor positioning and service model design.
Product Type:
FDA validation for pharmaceutical contact surfaces and USDA 3-A SSI compliance for dairy-grade equipment impose divergent engineering burdens across machine configurations, with automatic platforms facing dual-certification complexity.
- Vertical Machines:Gravity-fed film transport with forming collars creating pillow, gusseted, or quad-seal bags from 50-500mm width stock. Demand concentrates in Indian processed food clusters around Pune and Ahmedabad where domestic OEMs scale mid-speed platforms for regional spice and snack brands. CE marking under EU Machinery Directive adds documentation overhead for European-bound exports from these facilities.
- Horizontal Machines:Continuous-motion servo-driven platforms achieving 200+ cycles per minute with precision film registration. Pharmaceutical sachet production in Germany and Switzerland specifies these configurations for validated sterile boundary maintenance, with IQ/OQ/PQ documentation extending commissioning timelines by 6-12 months.
- Automatic Machines:Integrated weighing, dosing, and metal detection modules with recipe-driven changeover. Food processors in Vietnam's seafood export corridor specify these for HACCP-compliant automated lines.
- Semi-Automatic Machines:Operator-assisted film loading and seal initiation for batch-scale operations. Small-batch protein processors in Indonesia deploy these for MAP trials prior to full automation.
Leading the category by volume: Vertical Machines. Growing fastest: Horizontal Machines.
Application:
End-use requirements dictate laminate specification complexity and sealing temperature windows, with protein applications demanding gas-barrier structures that narrow compatible machine configurations.
- Food Packaging:Powder, granule, and small-piece solid containment across 80-250 micron film gauges with seal temperatures from 120°C to 220°C. Modified atmosphere specifications for premium meat and seafood are displacing standard gas-flush configurations as shelf-life extension becomes decisive in German retail procurement.
- Pharmaceutical Packaging:Unit-dose sachets and strip packs with FDA-validated contact surfaces and documented sterile boundaries. European installations face EU F-Gas Regulation mandates driving induction seal retrofits on existing horizontal platforms.
- Consumer Goods:Detergent pods and cosmetic samples requiring fragrance-barrier laminates. Japanese household chemical brands specify compact vertical units for high-density urban production facilities.
- Industrial Products:Hardware and chemical granule containment with puncture-resistant structures. Brazilian agricultural input suppliers favor semi-automatic configurations for seasonal demand fluctuation.
Dominant by installed base: Food Packaging. Steepest expansion trajectory: Pharmaceutical Packaging.
End User:
Customer scale and compliance maturity determine service contract structure, with large processors unbundling traditional full-service agreements into modular uptime guarantees.
- Food Processing:Dairy, ready-to-eat, and processed protein operations requiring 3-A SSI-compliant contact surfaces. Benelux operating lease structures are displacing outright purchases in this segment.
- Healthcare:Hospital nutrition and clinical trial material packaging with batch traceability requirements. Swissmedic validation protocols govern equipment selection for Swiss pharmaceutical manufacturing.
- Personal Care:Wipe sachets and sample pouches with moisture-barrier specifications. South Korean cosmetic OEMs specify compact vertical platforms for flexible production scheduling.
- Chemical Industry:Fertilizer and agricultural chemical containment with static-dissipative film options. Indian domestic machinery clusters serve this segment with cost-optimized mid-speed alternatives.
Highest equipment throughput: Food Processing. Gaining share fastest: Healthcare.
Technology:
Sealing architecture electrification is compressing thermal cycle times and eliminating refrigerant-dependent systems, forcing laminate suppliers to qualify new barrier structures.
- Thermoforming:Heated die forming of rigid or semi-rigid trays with lidding film sealing. European dairy operations specify these for portion-controlled cheese and yogurt formats under EFSA hygiene standards.
- Vacuum Packaging:Air evacuation prior to hermetic sealing for oxygen-sensitive products. Italian cured meat processors deploy these configurations for DOP-protected regional specialties.
- Aseptic Technology:Validated sterile boundaries with hydrogen peroxide or UV-C decontamination for extended-shelf-life dairy. Syntegon maintains technology leadership in continuous-motion platforms for this segment.
- Modified Atmosphere Packaging:Gas-flush or gas-barrier systems with residual oxygen control below 1%. Premium Australian meat exporters specify these for extended cold-chain distribution to Asian markets.
Widest installed base: Thermoforming. Climbing the fastest: Modified Atmosphere Packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pune and Ahmedabad industrial corridors anchor machinery production capacity expansion for regional processed food brands across India. Domestic OEM clusters scale mid-speed vertical baggers to reduce import dependence. CE marking documentation adds overhead for European-bound exports from these facilities.
Germany
Benelux operating lease structures displace outright equipment purchases among dairy and ready-to-eat processors. EU F-Gas Regulation mandates accelerate induction seal retrofits on existing horizontal platforms. Pharmaceutical sachet manufacturers in Baden-Württemberg specify continuous-motion servo-driven configurations with IQ/OQ/PQ validation.
United States
USDA 3-A SSI sanitation standards for dairy-grade equipment extend commercialization timelines for cross-industry vendors. FDA validation requirements for pharmaceutical contact surfaces create dual compliance burdens. Midwest food processing facilities expand automated bagging lines for powder and granule containment.
Switzerland
Swissmedic validation protocols govern equipment selection for pharmaceutical manufacturing of hospital nutrition and clinical trial materials. Precision engineering houses leverage heritage positioning for sterile boundary maintenance systems. Basel-area installations concentrate validated aseptic technology deployments.
Vietnam
Underpenetrated processed seafood export sectors present whitespace for aseptic tubular baggers with integrated metal detection modules. HACCP-compliant automated lines attract specification from regional protein processors. Ho Chi Minh City corridor facilities upgrade packaging infrastructure for cold-chain distribution to Asian markets.
India
Production-linked incentives under the PLI scheme attract component suppliers to establish captive machining operations near Ahmedabad industrial corridors. FSSAI compliance requirements shape domestic equipment specifications for spice and snack brands. Pune machinery clusters scale capacity to serve regional processed food demand.
Tubular Form Fill and Seal Machines Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across precision engineering and cost-optimized fabrication tiers. Market structure fragments between European precision houses, North American diversified portfolios, and Asian domestic clusters. Three archetypes dominate: heritage engineering specialists, diversified multi-brand holding companies, and regional cost-optimized fabricators. Competitive moves concentrate on portfolio diversification through brand acquisition and geographic expansion via regional assembly partnerships.
Within the heritage engineering tier, Concetti S.p.A. and Syntegon occupy positions anchored by geographic origin and organizational structure. Among diversified holding companies, ProMach exemplifies multi-brand portfolio coverage. German fabricators including Hastamat Verpackungstechnik GmbH and Weber Waagenbau und Wägeelektronik GmbH represent precision-focused archetypes with GmbH structures indicating limited liability frameworks. Danish and UK-based entities including Ehcolo A/S and Webster Griffin sit within specialized regional positioning. Premier Tech Chronos and Cordano Packaging Engineers complete the named set, with suffix structures suggesting corporate and engineering-specialist formations respectively.
| Leading Market Players |
|---|
| Concetti S.p.A. |
| Premier Tech Chronos |
| Cordano Packaging Engineers |
| Hastamat Verpackungstechnik GmbH |
| Webster Griffin |
| Weber Waagenbau und Wägeelektronik GmbH |
| Ehcolo A/S |
| ProMach |
| Syntegon |
| Others |
Value Network & Pricing Analysis
Petrochemical feedstock volatility in multi-layer coextruded films with ethylene-vinyl alcohol barriers cascades through fixed-price OEM contracts into tiered equipment pricing, compressing margins on mid-speed vertical baggers while elevating premium positioning for validated aseptic systems.
Pricing Analysis
Throughput-guaranteed uptime contracts anchor value-based pricing for continuous-motion horizontal platforms serving pharmaceutical sachet manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated aseptic systems from CE-marked dairy-grade equipment and basic vertical baggers. Cost compression in commodity tiers intensifies because Indian domestic clusters scale mid-speed alternatives, while precision servo component shortages elevate pricing power for European engineering houses. Small-batch protein processors in Indonesia exhibit highest price sensitivity; Swiss pharmaceutical manufacturers demonstrate lowest.
Supply Chain Analysis
High-resolution motion control systems for continuous-motion platforms rest on Japanese and German precision servo suppliers, exposing lead time vulnerabilities during disruption. Specialized laminate films draw from Italian and German barrier technology specialists; solid-state RF generators for induction sealing feed from Swiss and German electronics fabricators. Single-source vulnerability concentrates in precision dosing module suppliers serving pharmaceutical validation requirements. Distribution runs through regional OEM assembly partnerships near Pune and Ahmedabad industrial corridors, with CE-marked exports requiring separate documentation channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Induction heat-seal electrification is displacing refrigerant-dependent resistance-barrier sealing, forcing incumbent R&D reconfiguration and creating acquisition targets among RF generator specialists.
For Market Incumbents: Lock in servo-driven film transport expertise through captive engineering retention or targeted hiring in Baden-Württemberg and Basel precision clusters. Secure backward integration into solid-state RF generator supply to defend margin position against Asian cost-optimized entrants exploiting F-Gas retrofit demand. For New Entrants and Emerging Players: Launch via operating lease structures targeting Benelux dairy processors seeking to displace outright equipment purchases with modular uptime guarantees. Vietnam's underpenetrated processed seafood export corridor offers whitespace for aseptic tubular baggers with integrated metal detection; specify HACCP-compliant automated lines as the entry wedge. For Investors and Strategic Acquirers: Induction seal retrofit order acceleration from European dairy and pharmaceutical processors is the leading indicator that electrification transition is reaching critical adoption velocity. Target precision engineering houses with validated sterile boundary maintenance capabilities and existing IQ/OQ/PQ documentation infrastructure. Watch for PLI scheme component supplier clustering near Ahmedabad as the signal for Indian manufacturing cost structure inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Induction Heat-Seal Retrofit Program | Eliminates F-Gas-dependent cooling circuits while compressing maintenance intervals for dairy processors. |
| Precision Servo Supply Agreement | Secures motion control component allocation from Japanese and German specialists amid lead time risks. |
| Regional Assembly Partnership | Establishes captive machining operations near Ahmedabad to exploit PLI scheme incentives. |
| Operating Lease Structure Launch | Captures Benelux demand shift from outright purchase toward modular uptime guarantees. |
| IQ/OQ/PQ Documentation Investment | Extends pharmaceutical validation service capabilities for FDA and Swissmedic compliance requirements. |
Research Methodology
Independent corroboration across maintenance directors at food processing facilities, plant engineers specifying automated bagging lines, OEM procurement teams evaluating validation requirements, and aftermarket service heads managing uptime contracts underwrites the qualitative findings. SEC filings from diversified packaging machinery holding companies, EU F-Gas Regulation implementation reports, FSSAI compliance documentation, and customs data on machinery imports into India provide secondary validation. Bottom-up equipment shipment tallies triangulate against top-down processed food production capacity expansion estimates.
Rate-of-change decomposition separates volume growth in automated bagging line installations from value expansion in aseptic and modified atmosphere technology tiers across the analysis window. Segmentation dimensions include machine orientation, compliance certification level, end-use application, and sealing technology architecture. CAGRs derive from installed base replacement cycles, regulatory mandate timelines, and regional production capacity buildouts. Forecast inputs incorporate F-Gas phase-down schedules and PLI scheme incentive disbursement patterns.
The model assumes a particular technology adoption path; alternative pathways for ultrasonic-induction hybrid sealing would alter the outlook. Forecasts reflect assumptions about laminate film barrier qualification timelines and precision component supply normalization. A small set of named triggers—F-Gas enforcement acceleration, PLI scheme expansion, and servo supplier capacity additions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Auger Powder Filling Machines Market
Packaging Machinery
Wraparound Case Packers Market
Packaging Machinery
Bakery Packaging Machine Market
Packaging Machinery
Form-Fill-Seal (FFS) Packaging Machine Market
Packaging Machinery
Global Hand Wrapping Machine Market
Packaging Machinery
Sanitizer Filling Machine Market
Packaging Machinery
Molded Pulp Packaging Machines Market
Packaging Machinery
Tube Filling Machine Market
Packaging Machinery
Box Sealing Machines Market
Packaging Machinery
Kitchen/ Toilet Roll Converting Machines Market
Packaging Machinery
Twist Tie Machines Market
Packaging Machinery
Banding Machine Market
Packaging Machinery
Cutter-Box Packaging Market
Packaging Machinery
Flow Wrapper Market
Packaging Machinery
Vial Filling and Capping Machines Market
Packaging Machinery
Stick Pack Packaging Machine Market