
 Global Wrapping Machine Market | 2026-2036
Global Wrapping Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wrapping Machine Market Intelligence
The divergence between premium servo-controlled systems and commodity semi-automatic units is hardening as end users prioritize throughput consistency over upfront cost savings. Lantech leverages its North American installed base to sustain aftermarket service revenue. Robopac anchors European demand through stretch-hood specialization for beverage pallets. Syntegon Technology GmbH differentiates via pharmaceutical-grade containment validation.
Wrapping machines mechanically encase products or palletized loads in stretch film, shrink film, or paper-based materials using tension-controlled dispensers, rotary arms, or ring-style applicators operating at speeds from 20 to 150 pallets per hour. Automatic pallet wrappers with PLC control and remote diagnostics now command the dominant margin pool as labor scarcity intensifies across logistics networks. Semi-automatic units retain volume leadership in emerging manufacturing clusters where capital constraints limit full automation. Flow wrapping for food processing applications generates the fastest replacement cycle due to sanitation mandates and film compatibility requirements.
The EPA regulates volatile organic compound emissions from solvent-based shrink films used in US packaging operations, while the EU F-Gas Directive restricts fluorinated greenhouse gases in certain sealing technologies. China's SAMR enforces GB standards for electrical safety and electromagnetic compatibility on imported wrapping equipment. Stakeholders must monitor how divergent energy-efficiency certifications across these jurisdictions affect platform standardization and regional product variants.
Market Dynamics
Labor scarcity across logistics networks is compressing the payback period for automated pallet wrapping systems, while REACH and EPA regulations on film chemistry are forcing simultaneous equipment and material upgrades.
Growth Catalysts
- E-commerce fulfillment density:Third-party logistics operators in Germany and the United States are installing continuous-motion rotary arm wrappers to match throughput targets set by major retail platforms.
- EU F-Gas Regulation:The phase-down of fluorinated greenhouse gases is accelerating replacement of sealing technologies in stretch-hood systems, creating equipment refresh demand.
- Food safety mandates:Sanitation-validated flow wrappers are capturing replacement cycles in dairy and ready-meal processing as FDA enforcement intensifies.
Market Restraints
- Steel and servo motor cost volatility:Input price swings for precision mechanical components compress margins on mid-range automatic systems manufactured in China.
- Film supply concentration:European stretch film production clusters in Germany and Italy create geographic dependency risk for just-in-time wrapping operations.
- Technical limitation of paper-based alternatives:Moisture resistance and load containment specifications currently exclude paper wrapping from beverage and chemical pallet applications.
Strategic Opportunities
- Pharmaceutical containment validation:GMP-compliant isolator-integrated wrapping systems for sterile drug distribution represent an underserved premium segment.
- India manufacturing expansion:The country's PLI scheme for food processing and logistics infrastructure is opening capital equipment procurement windows for semi-automatic pallet systems.
- Remote diagnostics convergence:Integration of PLC-based machine monitoring with warehouse management software enables predictive maintenance contracts.
Industry Challenges
- Electromechanical technician scarcity:Maintenance of servo-controlled tension systems requires skills that outpace vocational training output in Midwestern US logistics hubs.
- Multi-jurisdiction certification timelines:Simultaneous CE marking, UL listing, and China GB compliance extend product launch cycles by 8-14 months.
- Legacy equipment integration:Retrofitting remote diagnostic modules onto 1990s-era mechanical wrappers creates data protocol incompatibilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wrapping Machine Market |
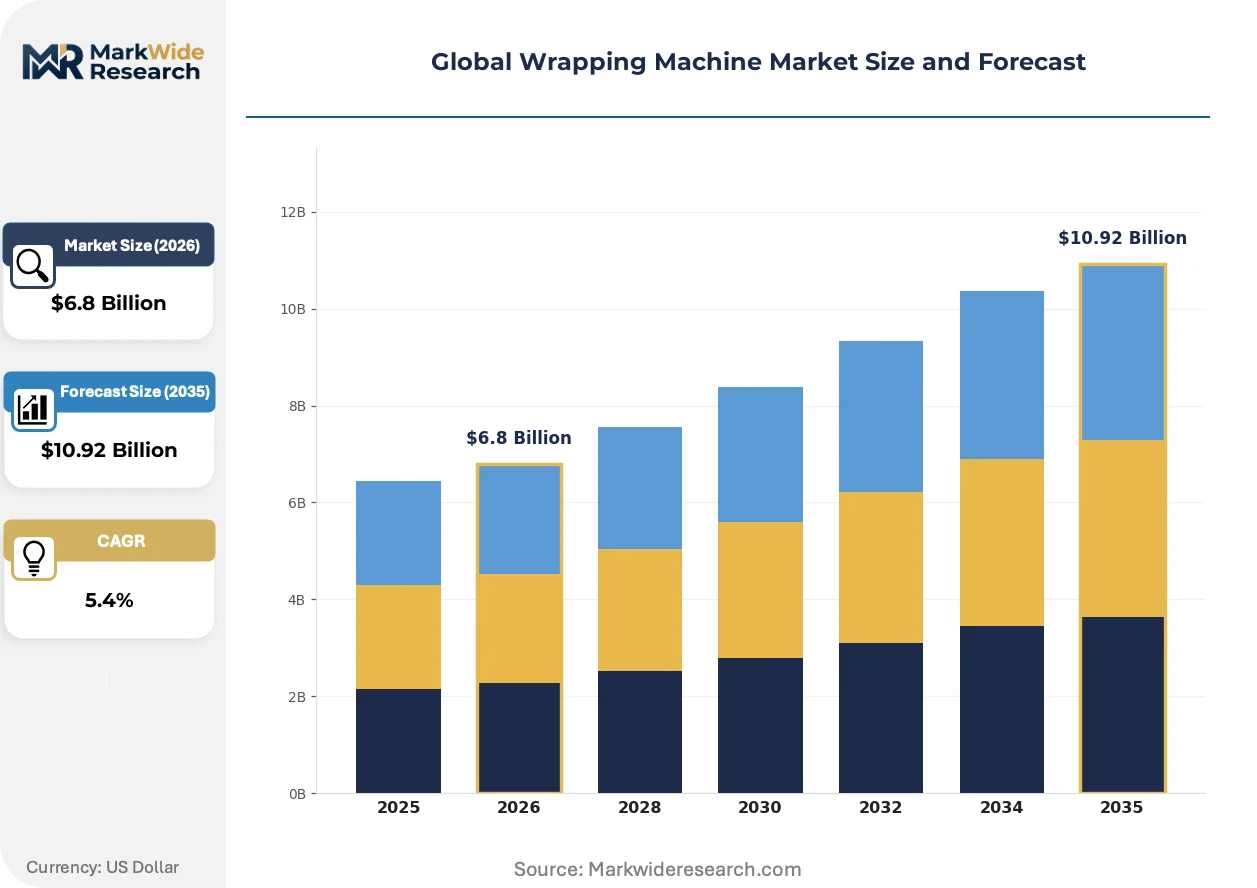
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal, Vertical, Rotary, Overwrapping, Flow, Pallet Wrappers Technology: Automatic, Semi-Automatic, Fully Automatic, Manual Adjustment, Servo Control, PLC Control Application: Food Processing, Pharmaceuticals, Cosmetics, Electronics, Home Goods, Industrial Supplies End User: Manufacturers, Packaging Companies, Distributors, Third-Party Logistics, Wholesalers, Retail Chains |
| Companies Covered | Robopac, Lantech, Phoenix Wrappers, Orion Packaging Systems LLC, Durapak, ProMach Inc., Coesia S.p.A, Matco International, Syntegon Technology GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wrapping Machine Market Strategic Shifts & Innovations
Intelligent tension control and sustainable film handling are converging to redefine equipment specifications, with regulatory pressure on material chemistry forcing simultaneous hardware and consumable innovation cycles.
Ring-style orbital wrapping technology is consolidating market position in high-volume beverage distribution. Rotary ring designs applying pre-stretched film at 120+ pallets per hour are displacing conventional turntable systems at Coca-Cola and PepsiCo bottling facilities. The technology is consolidating throughput advantages while reducing film consumption by 30-40% through precise tension algorithms.
REACH restrictions on phthalate plasticizers and the EU F-Gas Directive are reshaping film specifications and sealing hardware. Manufacturers must validate alternative stretch film chemistries that maintain load containment without restricted additives. German automotive suppliers and French food exporters face the tightest compliance deadlines, accelerating equipment replacement ahead of material phase-outs.
Service unbundling is fragmenting traditional equipment-plus-consumables procurement. Large third-party logistics operators in the Netherlands and California are separating wrapper hardware purchases from film supply contracts, pitting Lantech and Robopac service networks against independent film distributors. The shift pressures OEMs to defend attachment rates through proprietary pre-stretch head designs and locked calibration protocols.
Global Wrapping Machine Market Segmentation
Wrapping machine segmentation reveals a market split between high-throughput automation for logistics networks and specialized containment systems for regulated industries. Equipment specifications diverge sharply across end-use requirements, with pharmaceutical validation and food sanitation mandates driving premium configurations.
Product Type:
Volume leaders dominate pallet logistics while precision systems command premium margins in regulated processing environments.
- Pallet Wrappers:Rotary arm and turntable configurations mechanically secure palletized loads with stretch film tensioned between 150-300 percent pre-stretch ratios. Third-party logistics operators in Germany and the United States are scaling automated rotary systems to match e-commerce fulfillment throughput targets set by major retail platforms.
- Flow Wrappers:Continuous-motion horizontal form-fill-seal systems encase individual products in heat-sealed film at speeds exceeding 200 packages per minute. Dairy and ready-meal processors face the fastest replacement cycles here as FDA sanitation enforcement intensifies and film compatibility requirements evolve.
- Horizontal:Side-sealing configurations accommodate wide product formats for home goods and electronics distribution.
- Vertical:Top-down film application suits bagged products and bulk items in agricultural supply chains.
- Rotary:Ring-style orbital designs apply pre-stretched film at 120+ pallets per hour, consolidating position in beverage bottling facilities.
- Overwrapping:Tuck-and-fold cellophane or paper systems serve cosmetics and premium confectionery presentation requirements.
Today's leader: Pallet Wrappers. Tomorrow's challenger: Flow Wrappers.
Technology:
Control sophistication separates capital-intensive automation from labor-dependent semi-automatic installations.
- Automatic:PLC-controlled systems with HMI interfaces execute wrapping cycles without operator intervention, integrating with warehouse management software for throughput synchronization. Labor scarcity across Midwestern US logistics hubs compresses payback periods for these configurations.
- Servo Control:Closed-loop motor systems maintain film tension within ±2 percent variance, reducing material consumption by 30-40 percent through precise algorithms. German automotive suppliers specify these systems for load containment consistency in just-in-time component distribution.
- Semi-Automatic:Operator-initiated cycles with manual load positioning retain volume leadership in emerging manufacturing clusters where capital constraints limit full automation.
- Fully Automatic:Conveyor-integrated lines with automatic film splicing achieve 24/7 operation in high-volume distribution centers.
- Manual Adjustment:Mechanical tension knobs and hand-cranked turntables persist in small-batch operations with irregular load formats.
- PLC Control:Programmable logic controllers enable remote diagnostics integration, supporting predictive maintenance contracts.
Automatic systems anchor current revenue; Servo Control configurations are climbing the fastest as film cost pressures intensify.
Application:
Regulatory stringency varies dramatically across end-use categories, with validation requirements reshaping equipment specifications.
- Food Processing:Sanitation-validated flow wrappers with IP65 washdown ratings and quick-change film paths dominate dairy, meat, and ready-meal operations. FDA enforcement patterns and EU hygiene directives drive replacement demand here.
- Pharmaceuticals:GMP-compliant isolator-integrated systems with containment validation for sterile drug distribution represent an underserved premium segment. Syntegon Technology GmbH differentiates via this pharmaceutical-grade certification.
- Cosmetics:Overwrapping and shrink systems emphasize shelf presentation with registered film graphics and tamper-evident seals.
- Electronics:Anti-static film handling and precision tension control protect sensitive components during distribution.
- Home Goods:General-purpose pallet wrapping secures furniture and appliance shipments through diverse retail channels.
- Industrial Supplies:Heavy-duty stretch containment addresses chemical drums, metal coils, and construction materials.
Food Processing commands installed base volume; Pharmaceuticals offers the steepest expansion trajectory for validated containment systems.
End User:
Procurement authority concentrates with logistics operators while manufacturers retain specification control for integrated packaging lines.
- Third-Party Logistics:3PL operators in the Netherlands and California are unbundling equipment purchases from film supply contracts, separating wrapper hardware procurement from consumable agreements. This shift pressures OEMs to defend attachment rates through proprietary pre-stretch head designs.
- Manufacturers:Automotive and food processing clusters in Germany, China, and the United States drive capital expenditure for in-line wrapping integration with production scheduling systems.
- Packaging Companies:Contract packagers balance flexibility requirements across diverse client specifications with quick-changeover equipment platforms.
- Distributors:Regional distribution centers prioritize throughput consistency over upfront cost savings in equipment selection.
- Wholesalers:Mixed-load operations favor semi-automatic systems accommodating irregular pallet configurations.
- Retail Chains:Private-label fulfillment centers specify equipment matching upstream supplier packaging standards.
Third-Party Logistics sets current procurement volume; Manufacturers are gaining specification authority fastest through vertical integration of packaging operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled electromechanical technicians concentrate in Germany's industrial belt, China's manufacturing hubs, and the American Midwest, anchoring regional equipment deployment capacity.
United States
Third-party logistics operators across California and Illinois are scaling automated rotary arm wrappers to match e-commerce fulfillment targets set by major retail platforms. EPA regulations on volatile organic compound emissions from solvent-based shrink films mandate equipment upgrades. Chicago-area distribution centers compress payback periods for PLC-controlled systems as labor scarcity intensifies.
Germany
Automotive suppliers in Baden-Württemberg specify servo-controlled tension systems for just-in-time component distribution consistency. The EU F-Gas Regulation accelerates replacement of sealing technologies in stretch-hood systems ahead of fluorinated greenhouse gas phase-down deadlines. Bavarian beverage bottling facilities consolidate ring-style orbital wrapping technology at 120+ pallets per hour.
China
SAMR enforcement of GB standards for electrical safety and electromagnetic compatibility shapes imported equipment specifications. Yangtze River Delta manufacturing clusters drive capital expenditure for semi-automatic pallet systems where capital constraints limit full automation. Shanghai-area logistics operators balance throughput requirements with technician training pipeline limitations.
India
The PLI scheme for food processing and logistics infrastructure opens capital equipment procurement windows for semi-automatic pallet systems. Maharashtra and Gujarat manufacturing clusters prioritize quick-payback wrapping solutions amid skilled operator scarcity. Mumbai-based third-party logistics operators test unbundled procurement separating hardware from film supply contracts.
Netherlands
Rotterdam-port adjacent distribution centers pioneer service unbundling, separating wrapper hardware purchases from film supply agreements. REACH compliance deadlines on phthalate plasticizers accelerate validation of alternative stretch film chemistries. Dutch 3PL networks pressure OEM attachment rates through independent film distributor relationships.
Global Wrapping Machine Market Key Industry Players
Top-tier vendors anchor premium servo-controlled automation, while mid-range fabricators compete on semi-automatic volume and regional service density. The vendor base stratifies across three archetypes: precision engineering specialists with pharmaceutical validation capabilities, logistics-focused throughput maximizers, and emerging-market cost optimizers. Competitive moves concentrate on proprietary pre-stretch head designs that lock calibration protocols, and predictive maintenance contract structures that monetize remote diagnostics integration.
Within the precision-tier, Syntegon Technology GmbH exemplifies pharmaceutical-grade containment validation specialization. Lantech occupies a position among North American-installed-base service network anchors. Robopac sits within the European stretch-hood specialization cluster for beverage pallet applications. These three represent distinct competitive vectors—regulatory compliance depth, aftermarket service density, and application-specific engineering—rather than direct product overlap.
| Leading Market Players |
|---|
| Robopac |
| Lantech |
| Phoenix Wrappers |
| Orion Packaging Systems LLC |
| Durapak |
| ProMach Inc. |
| Coesia S.p.A |
| Matco International |
| Syntegon Technology GmbH |
| Others |
Cost & Logistics Intelligence
Steel and servo motor price indices cascade through wrapping machine manufacturing tiers, compressing margins on mid-range automatic systems assembled in China while amplifying pricing power for German-engineered servo-controlled units with captive component sourcing.
Pricing Analysis
The bundled-vs-unbundled service split separates OEM attachment strategies from independent distributor competition. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—CE-marked servo systems command premium positioning against semi-automatic units lacking PLC integration. Pricing pressure stems from steel and servo motor cost volatility squeezing mid-range fabricators. Third-party logistics operators exhibit highest price sensitivity through unbundled procurement separating hardware from film supply contracts, while pharmaceutical manufacturers show lowest sensitivity due to GMP validation requirements.
Supply Chain Analysis
Dual-sourcing requirements from German automotive suppliers and Dutch beverage distributors mandate multi-supplier qualification for critical servo motors and precision tension heads. Component manufacturing concentrates in Germany, China, and Japan for servo systems, with stretch film resin production clustering in Germany and Italy. Raw material dependencies rest on specialty steel alloys, rare-earth servo magnets, and LLDPE resin grades. Single-source vulnerability runs through European stretch film production clusters serving just-in-time wrapping operations. Distribution runs through OEM-direct channels for large 3PL accounts and regional equipment distributors for emerging market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU F-Gas Regulation compliance costs in Germany and France exceed India's PLI scheme subsidy offsets, creating divergent equipment replacement timelines and capital deployment efficiency gaps.
For Market Incumbents: Lock in aftermarket service revenue through proprietary pre-stretch head designs and locked calibration protocols that defend attachment rates against independent film distributors. Deepen backward integration into servo motor assembly to buffer steel and magnet cost volatility threatening mid-range automatic system margins. Prioritize pharmaceutical-grade containment validation investment as Syntegon Technology GmbH's specialized positioning faces limited direct replication. For New Entrants and Emerging Players: Launch via regional equipment distributor partnerships targeting India's PLI scheme procurement windows for semi-automatic pallet systems in Maharashtra and Gujarat manufacturing clusters. White-space concentrates in GMP-compliant isolator-integrated wrapping for sterile drug distribution, where validation timelines deter established logistics-focused vendors. Service unbundling trends in Dutch and California 3PL networks create entry points through independent film distributor alliances. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-range automatic system fabricators face simultaneous input cost volatility and unbundled procurement erosion. Five-to-ten year viability favors precision-tier specialists with pharmaceutical validation depth or logistics-scale throughput maximizers with dense installed-base service networks. Acquisition target archetype: servo-control engineering specialists with CE-marked platforms and underpenetrated aftermarket service contracts. Signal to watch: REACH alternative film chemistry validation timelines accelerating equipment replacement ahead of material phase-outs.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Pre-Stretch Head Development | Locked calibration protocols defend OEM film attachment rates against unbundled procurement. |
| Pharmaceutical Containment Validation | GMP-compliant isolator integration captures underserved premium segment in sterile drug distribution. |
| Remote Diagnostics Platform Integration | PLC-based machine monitoring enables predictive maintenance contracts with warehouse management software. |
| Regional Service Network Expansion | Dense technician coverage in Midwestern US logistics hubs addresses electromechanical maintenance scarcity. |
| Alternative Film Chemistry Qualification | REACH-compliant stretch film validation ahead of phthalate plasticizer phase-outs accelerates replacement demand. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers, OEM procurement teams, aftermarket service heads, and 3PL operations directors with secondary validation from SEC filings, customs trade records, machinery registration databases, and EU regulatory filings. Bottom-up equipment shipment data triangulated against top-down end-use capital expenditure surveys across food processing, pharmaceutical, and logistics verticals.
Comparable-period anchoring tied projection assumptions to historical replacement cycle patterns and regulatory compliance deadline clustering. Segmentation modeling spanned product type, technology tier, application regulatory stringency, and end-user procurement authority across the analysis window. CAGRs derived from equipment unit economics, film consumption intensity, and labor cost arbitrage sensitivity. Forecast inputs incorporated REACH chemical phase-out schedules, EU F-Gas Directive enforcement timelines, and India's PLI scheme disbursement patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt steel or servo motor price spikes and accelerated REACH alternative material validation failures. Deviation in EU F-Gas Regulation enforcement intensity or India's PLI scheme expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Food Packaging Machinery Market
Packaging Machinery
Folding Gluing Machines Market
Packaging Machinery
Packaging Machinery Market
Packaging Machinery
Tray and Sleeve Packing Machines Market
Packaging Machinery
Powder Auger Fillers Market
Packaging Machinery
Multi-Head Filling Machines Market
Packaging Machinery
Blown Film Extrusion Machine Market
Packaging Machinery
Carton Folding and Gluing Machine Market
Packaging Machinery
Vacuum Sealing Machine Market
Packaging Machinery
Blow Fill Seal (BFS) Technology Market
Packaging Machinery
Granule Filling Machine Market
Packaging Machinery
Stick Pack Packaging Machine Market
Packaging Machinery
Tissue Paper Unwinding Machine Market
Packaging Machinery
Pouch Packaging Machine Market
Packaging Machinery
Box Filling Machine Market
Packaging Machinery
Vial Filling and Capping Machines Market