
 Tissue Paper Unwinding Machine Market | 2026-2036
Tissue Paper Unwinding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Tissue Paper Unwinding Machine Market Analytics
China is reconfiguring regional supply dynamics through aggressive domestic machinery capacity expansion. Fujian Xinyun Machinery Development Co.,Ltd leverages coastal manufacturing clusters to dominate automatic unwinding system output. Fabio Perini S.p.A. anchors European demand through precision servo-control specialization. Wangda Group Co Ltd competes on cost-optimized semi-automatic lines for emerging market converters.
A tissue paper unwinding machine mechanically decelerates and tensions parent rolls for downstream converting, typically operating at web speeds between 800 and 2,000 meters per minute with automated splice cycles. The equipment ensures continuous feed to embossing, perforating, and folding stations across hygiene and food-service supply chains. Automatic systems capture the widest installed base, though servo control technology commands premium pricing due to precision tension management and reduced substrate waste. Roll-to-roll configurations lead in throughput volume, while pneumatic actuation retains share in cost-sensitive installations across developing markets.
EU machinery safety directives and CE marking requirements shape product design standards for equipment sold into European converting operations. China's GB standards and SAMR oversight govern domestic manufacturing quality and export certification pathways. India's BIS registration and PLI scheme incentives for paper product manufacturing indirectly stimulate machinery procurement. Stakeholders must weigh servo upgrade cycles against semi-automatic cost floors as energy efficiency regulations tighten across major installation geographies.
Market Dynamics
EU Green Deal mandates and China's dual carbon goals are forcing hygiene converters to retire pneumatic systems in favor of servo-controlled unwinding architectures that cut energy intensity and substrate waste.
Growth Catalysts
- REACH chemical compliance:European converters face mandatory substitution of solvent-based adhesives in splice tapes, accelerating demand for thermal bonding systems that integrate with modern unwinding lines.
- Food-service supply chains:Quick-service restaurants in North America are specifying certified compostable napkin substrates, requiring tension-calibrated unwinding equipment that handles lower-basis-weight recycled fibers without web breaks.
- Fujian manufacturing clusters:China's coastal machinery corridors achieve 40% shorter lead times on automatic unwinding systems through concentrated component sourcing and in-house casting capabilities.
Market Restraints
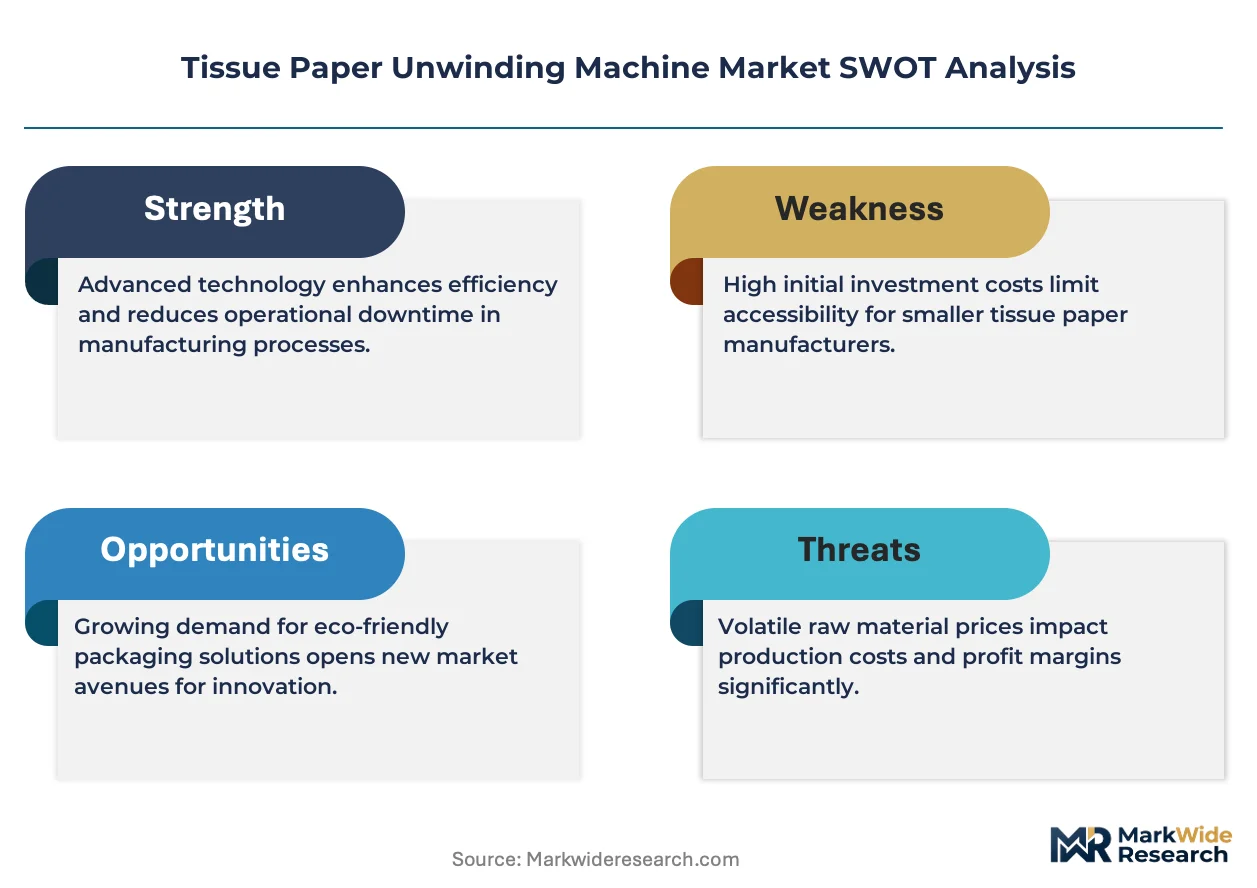
- Aluminum alloy pricing volatility:Frame castings and pneumatic cylinder housings absorb significant aluminum cost exposure, compressing margins for European and North American fabricators unable to hedge commodity positions.
- Control system supplier concentration:Precision servo drives for tension management rely on a narrow German and Japanese vendor base, creating single-source vulnerability for mid-tier unwinding equipment builders.
- CE marking timeline friction:Machinery safety directive compliance documentation extends European market entry by 8-14 months for Chinese manufacturers unfamiliar with Notified Body pathways.
Strategic Opportunities
- India PLI scheme spillover:Paper product manufacturing incentives under India's production-linked incentive framework stimulate greenfield converting capacity, creating first-mover advantage for unwinding system suppliers establishing local service networks.
- Machine vision integration:Convergence of edge-computing cameras with servo control loops enables real-time web defect detection and automatic splice rejection, opening premium pricing tiers for quality-critical pharmaceutical wipe applications.
- Remanufactured equipment channels:Secondary markets for refurbished automatic unwinding systems address Southeast Asian converters with constrained capex budgets, extending asset life cycles through certified rebuild programs.
Industry Challenges
- Mechatronics technician scarcity:Servo-controlled unwinding systems require cross-trained maintenance staff fluent in both mechanical web handling and programmable logic controller diagnostics, a skill combination scarce in emerging market installation bases.
- Legacy pneumatic integration:Converters with installed semi-automatic lines face disruptive retrofit timelines when upgrading to servo architectures, as frame geometries and control architectures lack backward compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tissue Paper Unwinding Machine Market |
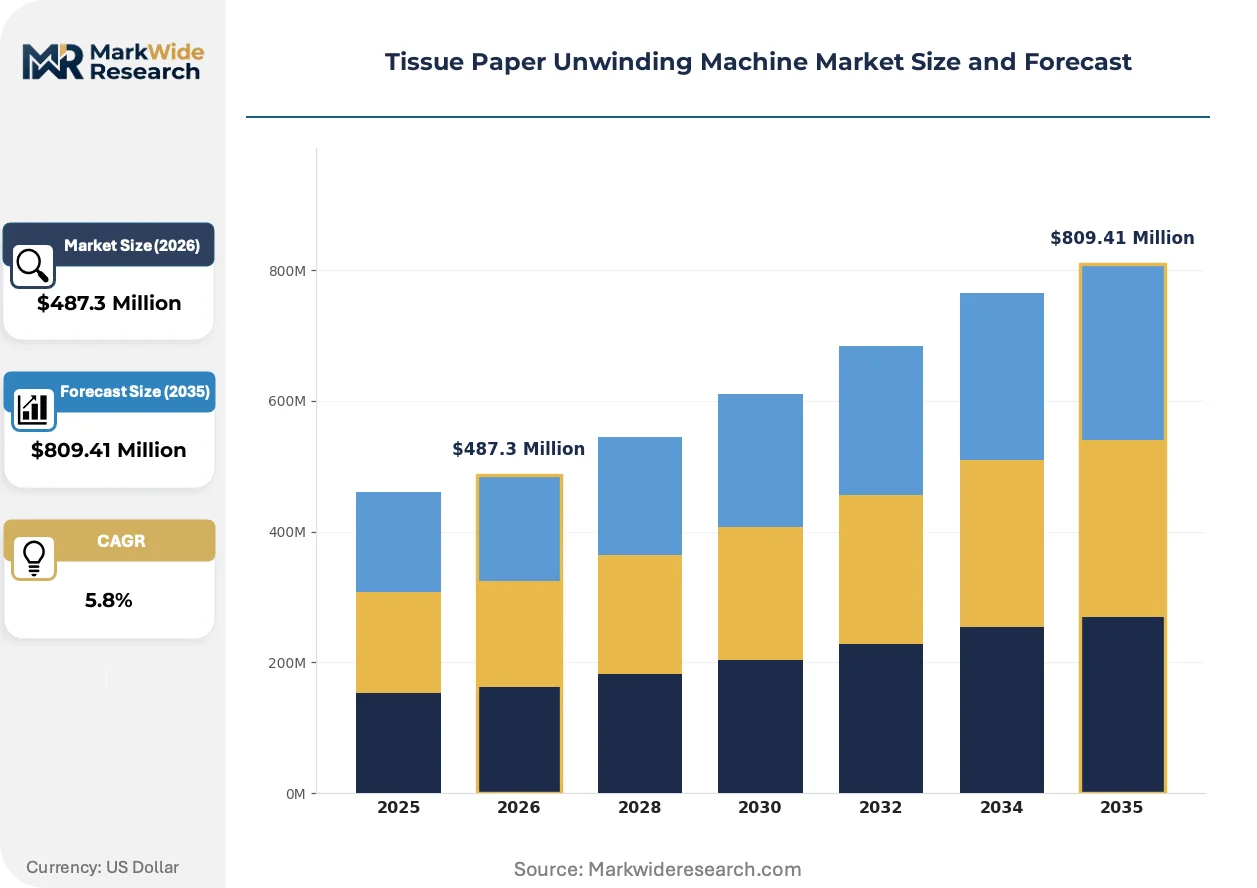
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Custom End User: Manufacturers, Packaging Companies, Wholesalers, Retailers Technology: Roll-to-Roll, Servo Control, Pneumatic, Hydraulic Application: Food Packaging, Hygiene Products, Industrial Cleaning, Tissue Converting |
| Companies Covered | Fujian Xinyun Machinery Development Co.,Ltd, Finetech Tissue Machines, Fabio Perini S.p.A., Baosuo Paper Machinery Manufacture Co. Ltd., Fidan Makina, A Celli Paper SpA, Wangda Group Co Ltd, Toscotec S.p.A., Dalian Mach Co.,Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tissue Paper Unwinding Machine Market Evolving Landscape
Active magnetic braking technology and predictive maintenance algorithms are compressing the performance gap between premium European systems and cost-optimized Asian alternatives, reshaping competitive tier boundaries.
Active magnetic powder brakes are replacing pneumatic disc brakes in tension control subsystems, delivering ±0.5% tension accuracy across parent roll diameter decay. Premium hygiene converters in Germany and Switzerland are specifying these systems for facial tissue lines running above 1,500 meters per minute. Pneumatic brake architectures are rendering obsolete for new capacity installations above mid-tier performance thresholds.
EU F-Gas Regulation phase-down schedules are prohibiting hydrofluorocarbon refrigerants in climate-controlled converting halls, indirectly pressuring unwinding equipment to operate reliably at elevated ambient temperatures without conditioned air envelopes. Southern European tissue converters face accelerated capital cycles as machinery thermal specifications tighten. Italian and Spanish installation sites are responding with enhanced bearing cooling circuits and heat-resistant web path materials.
Converter procurement committees are unbundling after-sales service contracts from equipment purchase agreements, negotiating separate multi-year maintenance subscriptions with third-party technical service providers. This disintermediation compresses OEM service margins while creating independent certification pathways for regional maintenance specialists. The pattern is most visible among North American private-label tissue converters seeking operational flexibility across multi-site machine fleets.
Tissue Paper Unwinding Machine Market Segmentation
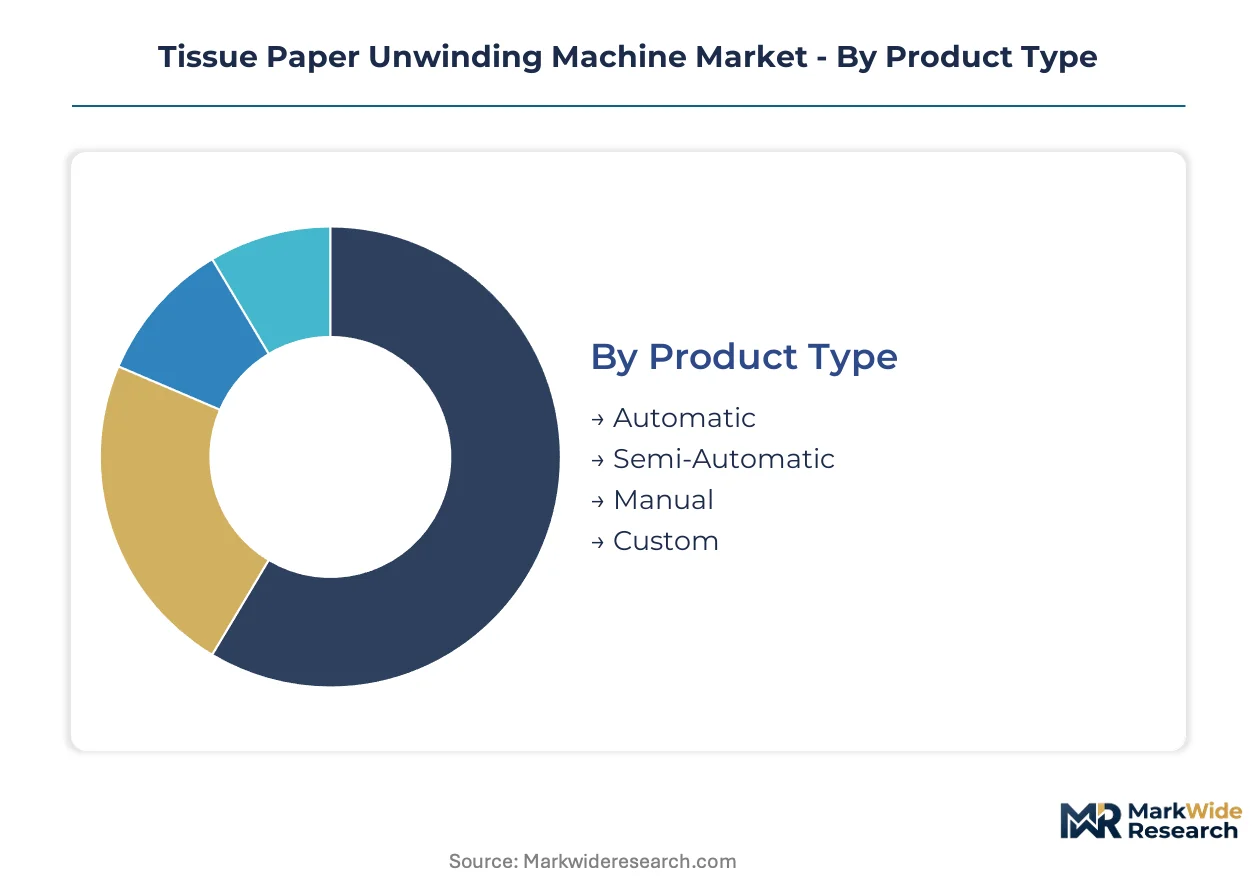
Tissue paper unwinding machine procurement patterns diverge sharply across automation tiers, end-user scale, and control architectures. Converters align capital deployment with substrate complexity, regulatory exposure, and line speed requirements rather than pursuing uniform technology adoption.
Product Type:
Cost tier stratification separates high-throughput hygiene producers from budget-constrained emerging market converters.
- Automatic:Servo-driven tension control and automated splice cycles handle parent rolls at 1,500+ meters per minute. German and Swiss facial tissue lines specify these systems to minimize web waste under REACH chemical compliance mandates.
- Semi-Automatic:Hybrid architectures blend pneumatic braking with limited programmable logic control. Indian paper converters under the PLI scheme favor this tier for greenfield capacity with constrained capex budgets.
- Manual:Operator-dependent unwinding for low-volume specialty tissue grades and pilot production lines.
- Custom:Purpose-built configurations for non-standard parent roll diameters or integrated converting lines.
Automatic systems command the established base. The steepest expansion runs through semi-automatic lines serving India's production-linked incentive spillover.
End User:
Customer type determines service intensity, spare parts contracting, and upgrade cycle frequency.
- Manufacturers:Integrated hygiene producers operating multi-line converting halls. These buyers negotiate unbundled maintenance subscriptions with third-party technical service providers rather than OEM service packages.
- Packaging Companies:Food-service napkin and towel converters requiring tension-calibrated equipment for certified compostable substrates. Quick-service restaurant supply chains in North America drive specification tightening.
- Wholesalers:Trading intermediaries procuring refurbished automatic systems for Southeast Asian resale channels.
- Retailers:Private-label tissue converters with multi-site fleets seeking operational flexibility across distributed machine bases.
Manufacturers command the established base. The steepest expansion runs through packaging companies responding to food-service compostable certification requirements.
Technology:
Control architecture maturity separates legacy pneumatic installations from magnetic braking adoption curves.
- Roll-to-Roll:Continuous web path configurations maximizing throughput volume for high-speed facial tissue and toilet paper lines. Fujian manufacturing clusters achieve 40% shorter lead times on these systems.
- Servo Control:Precision tension management through digital drive loops. Active magnetic powder brakes deliver ±0.5% accuracy, displacing pneumatic disc brakes in premium German and Swiss installations.
- Pneumatic:Compressed-air braking architectures retaining share in cost-sensitive developing markets. EU Green Deal mandates and China's dual carbon goals are forcing accelerated retirement of these systems.
- Hydraulic:High-torque braking for industrial cleaning substrate lines with extreme parent roll weights.
Roll-to-Roll configurations command the established base. The steepest expansion runs through servo control systems displacing pneumatic architectures under tightening energy efficiency regulations.
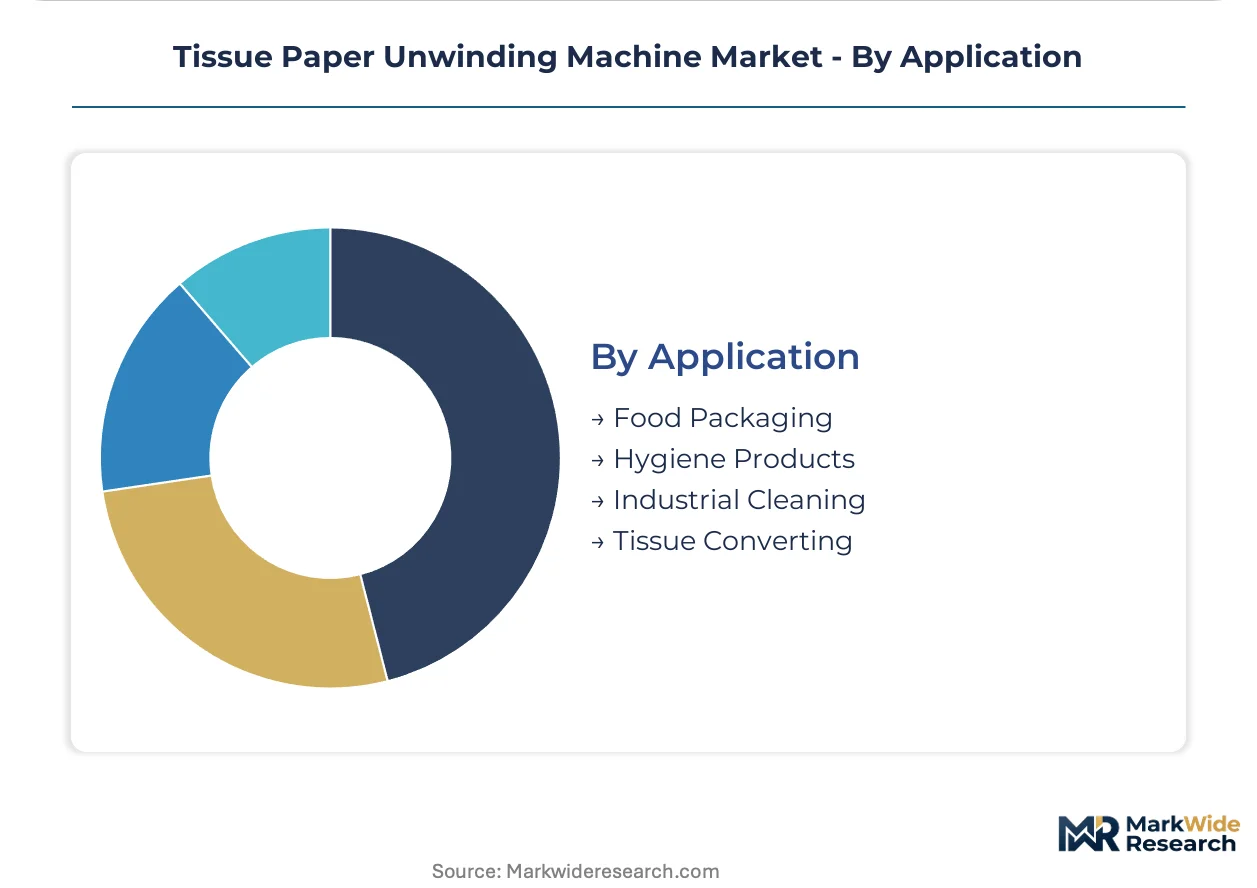
Application:
End-use substrate characteristics dictate web speed, tension precision, and contamination control specifications.
- Hygiene Products:Facial tissue, toilet paper, and napkin converting requiring pharmaceutical-grade tension stability. Machine vision integration enables real-time defect detection for quality-critical pharmaceutical wipe applications.
- Food Packaging:Quick-service restaurant napkin specifications demand handling of lower-basis-weight recycled fibers without web breaks. Certified compostable substrates require recalibrated tension profiles.
- Industrial Cleaning:Heavy-duty wipers and shop towels tolerating wider tension variance and lower line speeds.
- Tissue Converting:General-purpose parent roll preparation for downstream embossing, perforating, and folding stations.
Hygiene products command the established base. The steepest expansion runs through food packaging applications as quick-service chains mandate compostable substrate transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR oversight and GB standards anchor procurement patterns in China, the dominant geography for new capacity installations. Tightening EU Green Deal mandates and REACH chemical compliance reshape European converter equipment specifications. India's PLI scheme for paper products stimulates machinery demand across South Asia.
China
Coastal manufacturing clusters in Fujian Province absorb the largest share of automatic unwinding system output. Dual carbon goals from MEE accelerate retirement of pneumatic braking architectures in favor of servo-controlled alternatives. Fujian Xinyun Machinery Development Co.,Ltd leverages concentrated component sourcing and in-house casting capabilities to achieve 40% shorter lead times than European competitors.
Germany
Precision servo-control specialization anchors European demand for facial tissue lines operating above 1,500 meters per minute. EU F-Gas Regulation phase-down schedules pressure converting halls to operate at elevated ambient temperatures without conditioned air envelopes. Stuttgart and Munich industrial corridors specify active magnetic powder brakes delivering ±0.5% tension accuracy under REACH-mandated thermal bonding system integrations.
United States
Quick-service restaurant supply chains drive specification tightening for certified compostable napkin substrates. FDA food-contact regulations and EPA sustainability guidelines indirectly shape tension-calibration requirements for lower-basis-weight recycled fiber handling. Wisconsin and Georgia converting clusters negotiate unbundled maintenance subscriptions with third-party technical service providers rather than OEM service packages.
India
Paper product manufacturing incentives under the PLI scheme stimulate greenfield converting capacity across Maharashtra and Gujarat. BIS registration requirements govern domestic machinery quality standards and create certification friction for imported equipment. Mumbai and Ahmedabad industrial zones favor semi-automatic hybrid architectures blending pneumatic braking with limited programmable logic control for constrained capex budgets.
Italy
Pharmaceutical-grade tension stability requirements from EMA regulations drive machine vision integration for quality-critical wipe applications. CE marking timelines extend market entry documentation by 8-14 months for unfamiliar Notified Body pathways. Lucca tissue valley converters respond to southern European thermal specification tightening with enhanced bearing cooling circuits and heat-resistant web path materials.
Tissue Paper Unwinding Machine Market Competitive Landscape
Precision specialists and cost-optimized fabricators split the market along automation tier and geographic origin lines. European vendors anchor premium positioning through servo-control intellectual property and precision engineering heritage. Chinese manufacturers occupy mid-tier and economy segments through concentrated coastal production clusters and shortened supply chain loops. Competitive moves center on technology licensing partnerships for magnetic braking subsystems and geographic expansion into India's PLI-stimulated greenfield capacity.
Within the precision-specialist tier, Fabio Perini S.p.A. and A Celli Paper SpA exemplify Italian engineering heritage in servo-control unwinding architectures. Among Chinese fabricators, Fujian Xinyun Machinery Development Co.,Ltd and Wangda Group Co Ltd occupy positions spanning automatic and semi-automatic system output. These named entities represent geographic concentration patterns rather than exhaustive market enumeration, with European precision vendors commanding premium pricing and Chinese scale manufacturers competing on lead-time compression and component integration depth.
| Leading Market Players |
|---|
| Fujian Xinyun Machinery Development Co.,Ltd |
| Finetech Tissue Machines |
| Fabio Perini S.p.A. |
| Baosuo Paper Machinery Manufacture Co. Ltd. |
| Fidan Makina |
| A Celli Paper SpA |
| Wangda Group Co Ltd |
| Toscotec S.p.A. |
| Dalian Mach Co.,Ltd |
| Others |
Value Network & Pricing Analysis
Aluminum alloy pricing volatility compresses margin structures across European and North American fabricators while simultaneously widening the premium-to-economy equipment spread and forcing supply chain reconfiguration toward in-house casting capabilities in coastal Chinese manufacturing clusters.
Pricing Analysis
Geographic price spreads separate German servo-control systems from Fujian automatic lines by a factor reflecting precision engineering premiums against lead-time advantages. Three-tier pricing structure across premium, standard, and economy levels stratifies by automation tier and after-sales service bundling, with unbundled maintenance subscriptions gaining traction among North American private-label converters. Pricing pressure stems from commodity cost exposure in aluminum frame castings and pneumatic cylinder housings. Packaging companies facing compostable substrate mandates exhibit highest price sensitivity, while integrated hygiene producers in Germany and Switzerland demonstrate lowest sensitivity due to waste-reduction ROI from magnetic braking precision.
Supply Chain Analysis
Tariff exposure between Chinese component suppliers and European assembly operations dominates supply chain risk profiles for mid-tier unwinding equipment builders. Precision servo drives draw from concentrated German and Japanese vendor bases, while aluminum castings and pneumatic subsystems source from Chinese coastal manufacturing corridors. Single-source vulnerability in control system supplier concentration creates chokepoint exposure for tension management architectures. Distribution runs through OEM direct sales for premium installations and third-party technical service providers for aftermarket refurbishment channels in Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Servo-control adoption curves in hygiene converting represent early-cycle expansion, with EU Green Deal mandates and China's dual carbon goals accelerating the displacement of legacy pneumatic architectures before regulatory deadlines tighten.
For Market Incumbents: Entrench precision servo-control intellectual property through active magnetic braking subsystem patents and CE marking documentation expertise that extends Chinese competitor market entry timelines. Deepen backward integration into aluminum casting capabilities to hedge commodity volatility exposure. Prioritize unbundled service contract alternatives that retain converter relationships against third-party technical service disintermediation.
For New Entrants and Emerging Players: Build out certified rebuild programs for refurbished automatic unwinding systems targeting Southeast Asian converters with constrained capex budgets. India's PLI scheme spillover offers the most penetrable geography for semi-automatic hybrid architectures. Lead with local service network establishment rather than equipment price competition to secure first-mover positioning in greenfield Maharashtra and Gujarat converting capacity.
For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down schedules reshape the acquisition landscape toward equipment suppliers with thermal specification engineering for elevated ambient temperature operation. Long-term viability centers on servo-control technology ownership and geographic diversification beyond single-region manufacturing concentration. Monitor CE marking timeline friction as an inflection indicator for Chinese manufacturer competitive pressure intensity in European markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Control Technology Licensing | Magnetic braking IP partnerships enable mid-tier European fabricators to close precision gaps with Italian engineering heritage leaders. |
| Local Service Network Expansion | India PLI scheme greenfield capacity creates captive maintenance revenue streams independent of OEM equipment margins. |
| Remanufactured Equipment Certification | Secondary market channel control extends asset life cycles while addressing Southeast Asian converter budget constraints. |
| Machine Vision Integration Development | Edge-computing camera convergence opens pharmaceutical wipe application premiums through real-time defect detection. |
| Thermal Specification Engineering Investment | EU F-Gas Regulation compliance enables southern European converting hall operation without conditioned air envelopes. |
Research Methodology
Desk research of machinery trade databases, customs import records, and regulatory filing repositories preceded structured interviews with plant engineers at hygiene converting operations, OEM procurement teams, aftermarket service heads, and technical R&D directors at control system suppliers. Primary fieldwork combined with secondary validation against SEC filings, SAMR certification registries, and BIS registration databases. Bottom-up equipment shipment tracking and top-down converting capacity expansion analysis were triangulated to establish market sizing.
Assumptions held fixed include REACH chemical compliance timelines, EU F-Gas Regulation phase-down schedules, and India's PLI scheme incentive structures, while aluminum alloy pricing trajectories and servo drive supplier concentration were modeled as variable sensitivities. Segmentation dimensions spanned automation tier, end-user scale, control architecture maturity, and substrate application type across the projection horizon. CAGRs were derived from equipment procurement cycle analysis and parent roll throughput expansion rates in key installation geographies.
Sensitivities concentrate around regulatory deadline acceleration, commodity cost spike persistence, and single-source control system supply disruptions. Forecasts reflect documented assumptions regarding converter capex commitment patterns and sustainability mandate enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Autofill Drums & Totes Machines Market
Packaging Machinery
Kitchen/ Toilet Roll Converting Machines Market
Packaging Machinery
Liquid Filling Machines Market
Packaging Machinery
Carton Folding and Gluing Machine Market
Packaging Machinery
Cutter-Box Packaging Market
Packaging Machinery
Asia-Pacific Pharmaceutical Packaging Machinery Market
Packaging Machinery
Paper Napkins Converting Machines Market
Packaging Machinery
Banding Machine Market
Packaging Machinery
Pallet Strapping Machines Market
Packaging Machinery
Palletizing Machines Market
Packaging Machinery
Bagging Machine Market
Packaging Machinery
Global Hand Wrapping Machine Market
Packaging Machinery
Auger Powder Filling Machines Market
Packaging Machinery
Induction Sealing Machine Market
Packaging Machinery
Shrink - Sleeve Wrapping Machinery Market
Packaging Machinery
Case Packaging Machinery Market