
 Blind Box Machine Market | 2026-2036
Blind Box Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Blind Box Machine Market Insights
A capital-intensity divergence between players is collapsing as mid-tier manufacturers gain access to off-the-shelf mechatronics and cloud payment modules. Pop Mart International Group leverages its captive IP library and retail footprint to sustain premium placement in high-traffic Chinese malls. Funko anchors North American demand through licensed character portfolios and big-box retail partnerships. Bandai Namco dominates Japan's dense urban vending corridors with compact, high-reliability units engineered for 24-hour operation.
A blind box machine is an electromechanical dispensing system that randomizes product delivery through sealed compartments, typically incorporating RFID inventory tracking, touchscreen interfaces, and cashless payment terminals rated for commercial-duty cycles. Automated units command the largest installed base, though customized configurations for brand activations capture disproportionate margin pools. Plastic and cardboard material types split along price-tier lines, with metal-reinforced chassis penetrating warehouse and distribution center environments where throughput demands exceed retail-grade durability thresholds.
China's SAMR mandates probability disclosure and age-rating labels on mystery-box machines, while Japan's METI enforces electrical safety certifications under JIS standards for public-access vending equipment. The EU's CE marking and RoHS compliance create non-tariff barriers for Asian OEMs seeking European retail placement. Stakeholders must monitor evolving youth-protection frameworks and payment-security mandates as regulatory fragmentation intensifies across target geographies.
Market Dynamics
Capital-intensity divergence between manufacturers is collapsing as standardized mechatronics and cloud payment modules democratize machine production, eroding the historical advantage of vertically integrated incumbents.
Growth Catalysts
- China SAMR probability disclosure mandates:Regulatory clarity around mystery-box mechanics is legitimizing the format for mainstream retail expansion, reducing consumer trust barriers that previously constrained placement in family-oriented venues.
- RFID inventory tracking integration:Real-time stock monitoring is reducing out-of-stock incidents and enabling dynamic pricing algorithms that maximize throughput during peak traffic windows.
- Tokyo commercial corridor density:Japan's 24-hour urban retail culture sustains machine utilization rates that justify premium hardware investments unavailable in lower-density markets.
Market Restraints
- Semiconductor component volatility:Touchscreen controllers and payment terminal chipsets face supply concentration risks concentrated in Taiwanese foundry capacity, creating machine delivery timeline uncertainty.
- RoHS compliance friction:Asian OEMs targeting EU retail placement encounter material certification costs that compress margins on compact units engineered for Asian electrical standards.
- Digital collectible substitution:NFT-based randomized reward platforms are capturing youth entertainment expenditure that previously flowed to physical blind box formats.
Strategic Opportunities
- India tier-2 mall expansion:Entertainment retail infrastructure in cities like Pune and Ahmedabad remains undersupplied relative to disposable income growth among 18-34 demographics.
- Brand activation channel development:Limited-edition pop-up machine deployments for film and gaming IP launches command per-unit margins substantially above permanent retail installations.
- Japan METI energy efficiency incentives:Subsidies for low-power vending equipment are accelerating LED display and standby-mode retrofits that reduce operational expenditure.
Industry Challenges
- Mechatronics technician scarcity:Maintenance networks capable of servicing cashless payment terminal integration remain thin outside Shanghai, Tokyo, and Seoul metropolitan clusters.
- JIS electrical certification timelines:Japan's safety validation protocols for public-access vending equipment extend product launch cycles by 4-7 months relative to domestic Chinese market entry.
- Cross-border IP licensing complexity:Character portfolio agreements for multinational machine networks require territory-by-territory negotiation that fragments operational scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blind Box Machine Market |
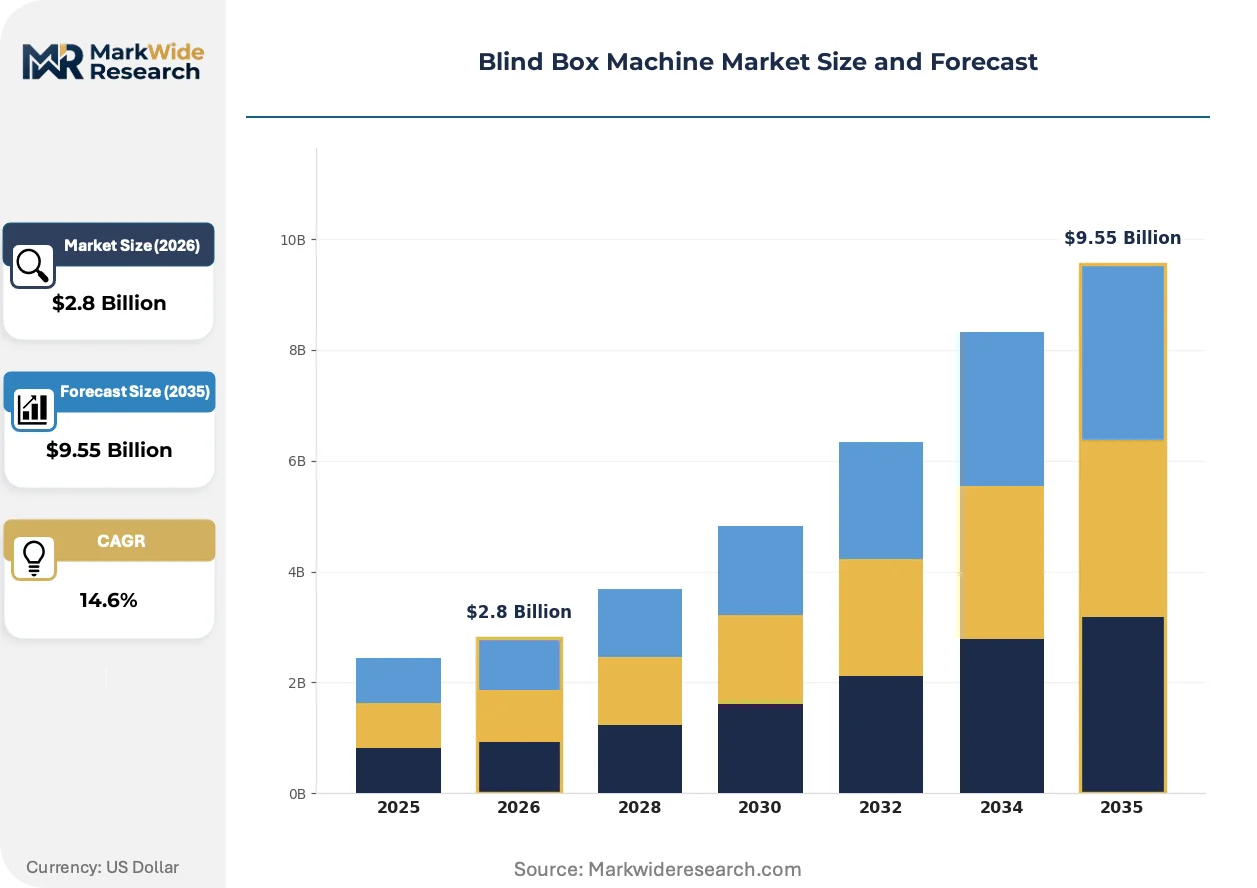
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated, Semi-Automated, Manual, Customized End User: Manufacturers, Retailers, E-commerce Platforms, Distributors Material Type: Plastic, Cardboard, Paper, Metal Operating Environment: Warehouse, Retail Store, Online Platform, Distribution Center |
| Companies Covered | Fun Industries, Triple Shop Vending, Pop Mart International Group, Funko, LEGO Group, U-Tech, Eureka Vending, Bandai Namco, Seaga Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blind Box Machine Market Trends and Innovations
Hardware differentiation is compressing as cloud-native software layers become the primary vector for competitive distinction, shifting value capture toward data analytics and consumer engagement platforms.
Computer vision-enabled inventory verification is fragmenting quality assurance workflows across the installed base. Cameras mounted inside dispensing compartments verify product condition before release, reducing refund incidents. Boutique operators in Seoul's Hongdae district deploy this capability to justify premium pricing against unverified competitors.
EU CSRD sustainability disclosure requirements are mandating lifecycle documentation for vending equipment placed in European retail environments. Machine OEMs must now provide carbon footprint data spanning component sourcing through end-of-life recycling. This regulatory load favors larger manufacturers with established supply chain audit capabilities over mid-tier Asian exporters.
Collector community digital integration is reshaping repeat purchase behavior. Mobile apps that track collection completion rates and enable peer-to-peer trading are becoming standard companions to physical machine networks. Pop Mart's domestic China ecosystem demonstrates how software engagement extends customer lifetime value beyond the initial transaction frequency typical of standalone vending.
Blind Box Machine Market Segmentation
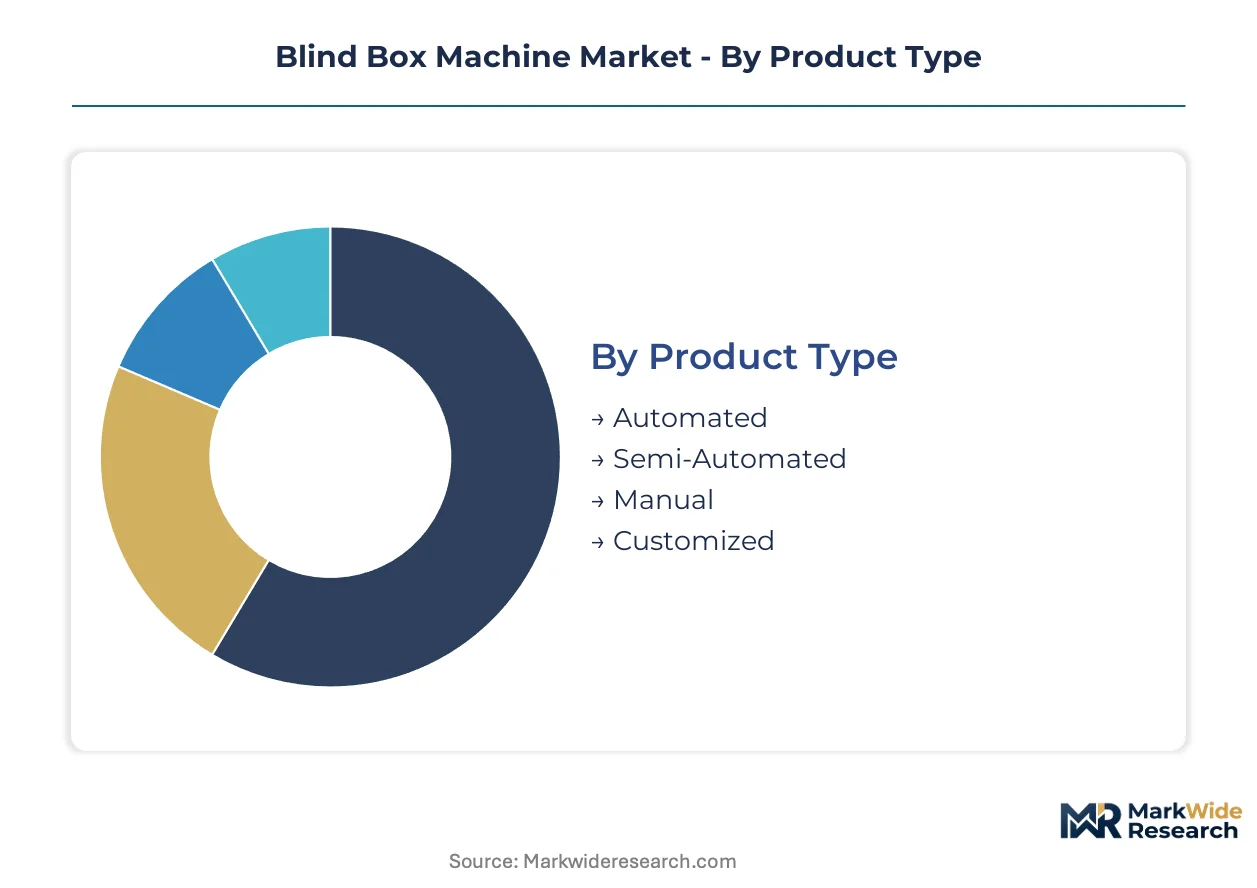
Segmentation in the blind box machine market determines hardware durability requirements, payment integration complexity, and maintenance network density. Machine specifications diverge sharply between high-traffic urban retail and industrial logistics environments.
Product Type:
Regulatory differentiation shapes product type selection, with Japan's METI JIS certification and China's SAMR probability disclosure rules imposing distinct electrical safety and transparency standards on automated versus manual formats.
- Automated:These units integrate RFID inventory tracking, touchscreen interfaces, and cashless payment terminals rated for commercial-duty cycles. Demand concentrates in Tokyo's 24-hour commercial corridors and Shanghai's Tier-1 malls, where high throughput justifies premium hardware investments and continuous operation mandates METI-compliant electrical certifications.
- Customized:Purpose-built configurations for film and gaming IP activations command per-unit margins substantially above permanent retail installations. Brand activation deployments in Seoul's Hongdae district and Beijing's Sanlitun cluster prioritize computer vision verification and limited-edition dispensing mechanics to justify premium positioning against standard automated units.
- Semi-Automated:Hybrid units blending manual selection with automated payment processing, common in India's tier-2 mall expansions where technician scarcity constrains full automation deployment.
- Manual:Mechanical dispensing without electronic payment integration, persisting in lower-density Southeast Asian markets with limited cloud infrastructure penetration.
Automated machines handle the majority of throughput; customized configurations are climbing the fastest on share.
End User:
Cost tier differentiation separates captive IP owners from third-party operators, with vertical integration economics favoring manufacturers who internalize machine deployment.
- Retailers:Entertainment retail chains in Japan and South Korea are expanding automated dispensing fleets across high-traffic commercial corridors. These operators prioritize METI-certified reliability and 24-hour operational uptime to match urban consumer behavior patterns.
- Manufacturers:Captive IP owners like Pop Mart International Group leverage machine networks as proprietary distribution channels, capturing margin pools unavailable to licensed third-party operators. In-house deployment enables direct consumer data collection and dynamic pricing algorithm implementation.
- E-commerce Platforms:Online retailers deploying physical touchpoints for customer acquisition, particularly in China's Tier-1 cities where mystery-box vending legitimizes brand extension into experiential retail.
- Distributors:Third-party logistics providers placing machines on consignment, dominant in India's emerging tier-2 markets where capital constraints limit direct retailer ownership.
Retailers dominate installed base volume; manufacturers are expanding most quickly through captive network buildout.
Material Type:
Application context drives material selection, with warehouse and distribution center environments demanding metal-reinforced chassis that exceed retail-grade durability thresholds.
- Metal:Reinforced chassis penetrating warehouse and distribution center environments where throughput demands exceed retail-grade durability. These units withstand continuous loading cycles and resist tampering in unmanned logistics facilities.
- Plastic:Lightweight enclosures standard in retail-grade automated units, optimized for aesthetic customization and rapid deployment in climate-controlled mall environments.
- Cardboard:Temporary structures for brand activations and pop-up deployments, minimizing capital commitment for limited-duration IP launches.
- Paper:Sustainable material trials responding to EU CSRD lifecycle documentation requirements, currently niche due to moisture sensitivity constraints.
Plastic captures the largest production volume; metal is gaining share fastest in logistics applications.
Operating Environment:
Geography determines environmental specifications, with humidity-controlled retail stores and climate-exposed distribution centers imposing divergent thermal management and sealing requirements.
- Retail Store:Climate-controlled mall placements in Tokyo, Seoul, and Shanghai's commercial corridors sustain the highest utilization rates. These environments prioritize aesthetic integration and touchscreen accessibility over industrial durability.
- Warehouse:High-throughput logistics facilities requiring metal-reinforced chassis and extended-duty payment terminals. Demand concentrates in China's e-commerce fulfillment networks where blind box machines serve as last-mile customer engagement nodes.
- Distribution Center:Intermediate facilities balancing throughput demands with space constraints, common in Japan's dense urban logistics corridors where floor space efficiency dictates compact unit design.
- Online Platform:Virtual dispensing interfaces paired with physical fulfillment, emerging as a hybrid category bridging digital collectible substitution risks.
Retail store placements handle the majority of consumer transactions; warehouse deployments are expanding most quickly in e-commerce integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Blind box machine utilization patterns diverge sharply across geographies. Japan and South Korea prioritize 24-hour automated corridors in dense urban commercial zones. China's regulatory environment favors probability-transparent formats in Tier-1 mall placements. Western markets emphasize licensed character portfolios and temporary brand activations over permanent vending infrastructure.
China
Shanghai and Beijing's Tier-1 mall clusters sustain the highest machine density globally. SAMR probability disclosure mandates legitimize mystery-box formats for family-oriented venues previously resistant to unregulated dispensing. The Yangtze River Delta corridor anchors domestic manufacturing capacity for automated units with integrated RFID tracking.
Japan
Tokyo's 24-hour commercial culture generates utilization rates unmatched elsewhere. METI enforces JIS electrical safety certifications that extend product launch cycles but ensure public-access reliability. Osaka's Kansai corridor hosts dense vending corridors where compact, high-duty machines dominate 24-hour operation.
South Korea
Seoul's Hongdae district exemplifies premium brand activation deployments with computer vision verification. MFDS consumer protection frameworks regulate probability mechanics alongside youth-access restrictions. The Seoul Capital Area sustains automated fleet expansion across entertainment retail chains.
United States
Licensed character portfolios anchor North American demand through big-box retail partnerships rather than dense urban corridors. State-level consumer protection laws create regulatory fragmentation absent federal vending equipment standards. California and Texas metros concentrate pop-up brand activation deployments for film and gaming IP launches.
Germany
CE marking and RoHS compliance create non-tariff barriers for Asian OEMs seeking European retail placement. The country's national consumer protection regulator enforces strict youth-access frameworks for randomized reward mechanics. Bavaria and North Rhine-Westphalia concentrate sustainability-focused pilot programs responding to EU CSRD lifecycle documentation requirements.
Blind Box Machine Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive IP owners commanding margin pools unavailable to licensed third-party operators. The vendor base stratifies across three archetypes: vertically integrated entertainment conglomerates with proprietary machine networks, specialized vending equipment fabricators serving third-party operators, and brand activation specialists deploying temporary customized configurations. Competitive moves concentrate on geographic licensing expansion and cloud-native software layer differentiation as hardware commoditization accelerates.
Within the integrated entertainment tier, Pop Mart International Group exemplifies captive IP deployment through proprietary machine networks, while Funko anchors licensed character portfolio strategies in Western markets. Bandai Namco occupies a position representing Japanese engineering reliability for dense urban 24-hour corridors. These three entities collectively illustrate how vertical control over character portfolios and machine deployment creates defensive positioning against hardware commoditization pressures.
| Leading Market Players |
|---|
| Fun Industries |
| Triple Shop Vending |
| Pop Mart International Group |
| Funko |
| LEGO Group |
| U-Tech |
| Eureka Vending |
| Bandai Namco |
| Seaga Manufacturing |
| Others |
Pricing and Supply Chain Analysis
Japan's METI JIS certification gates both supplier qualification and price differentiation in blind box machine procurement, as only certified fabricators can access Tokyo's premium 24-hour corridor placements while commanding hardware premiums unavailable to uncertified competitors. This regulatory filter compresses margins for Asian OEMs targeting European markets where CE marking and RoHS compliance add parallel certification burdens.
Pricing Analysis
Long-term offtake contracts dominate procurement between entertainment retail chains and established fabricators, insulating Japanese and South Korean operators from spot-market component volatility while locking in volume discounts. Price differentiation separates METI-certified units with 24-hour duty cycles from standard retail-grade machines, with customization for brand activations capturing the highest per-unit returns. Cost compression in mid-tier automated units is intensifying because off-the-shelf mechatronics democratize production. Third-party distributors in India's tier-2 markets exhibit the highest price sensitivity, whereas captive IP owners like Pop Mart prioritize total cost of ownership over upfront hardware expenditure.
Supply Chain Analysis
Port congestion on the Shanghai-Yokohama trade lane elevates inbound logistics costs for Taiwanese touchscreen controllers and payment terminal chipsets, creating delivery timeline uncertainty for machine OEMs. Component sourcing draws from China for plastic enclosures and mechatronics, Taiwan for semiconductor modules, and Japan for high-reliability electrical assemblies. Single-source vulnerability concentrates in Taiwanese foundry capacity for payment processing chipsets. Distribution runs through entertainment retail chain procurement offices in Tokyo and Seoul, with direct manufacturer deployment growing fastest among captive IP owners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native software layers and data analytics subscriptions are expanding faster than hardware sales, positioning machine networks as recurring-revenue platforms rather than one-time capital expenditures. This service-attach dynamic favors stakeholders who internalize consumer engagement capabilities.
For Market Incumbents: Secure exclusive territory rights for high-traffic mall placements before regulatory clarity in additional markets invites competitive entry. Consolidate maintenance technician networks in Shanghai, Tokyo, and Seoul to defend against mechatronics scarcity that fragments service quality. Invest in backward integration of RFID inventory modules to capture margin pools currently flowing to specialized component suppliers.
For New Entrants and Emerging Players: After-sales software integration represents the most penetrable white-space where vertically integrated incumbents under-serve third-party operators lacking captive development resources. Target India's tier-2 mall expansions in Pune and Ahmedabad where entertainment retail infrastructure lags disposable income growth among 18-34 demographics. Pursue white-label deployment partnerships with e-commerce platforms seeking physical customer acquisition touchpoints without proprietary machine development.
For Investors and Strategic Acquirers: China's SAMR probability disclosure mandates reshape the acquisition landscape by legitimizing mystery-box formats for mainstream retail expansion, reducing regulatory overhang risk for platform investments. Focus on captive IP owners with established software ecosystems and direct consumer data collection capabilities as the most defensible long-term positioning against hardware commoditization. Monitor Japan's METI energy efficiency subsidy programs as an inflection signal for low-power retrofit demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Development | Software engagement layers extend customer lifetime value beyond transaction frequency for Pop Mart's domestic ecosystem. |
| Certification Investment in JIS Standards | METI compliance unlocks Tokyo's 24-hour commercial corridors where utilization rates justify premium hardware investments. |
| Brand Activation Channel Expansion | Limited-edition pop-up deployments in Seoul's Hongdae district command margins substantially above permanent retail installations. |
| Technician Network Consolidation | Maintenance capability scarcity outside Shanghai, Tokyo, and Seoul clusters creates defensive moats for established service organizations. |
| RFID Inventory Integration | Real-time stock monitoring enables dynamic pricing algorithms that maximize throughput during peak traffic windows in Tier-1 Chinese malls. |
Research Methodology
A spread of perspectives from entertainment retail procurement directors, vending equipment fabricators, IP licensing executives, and cloud payment platform engineers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with machine network operators in Tokyo, Shanghai, and Seoul alongside secondary validation through SAMR regulatory filings, METI certification databases, Japan Vending Machine Manufacturers Association reports, and customs trade data for mechatronics component flows. Bottom-up unit economics triangulated against top-down market sizing across product type, end user, material, and operating environment dimensions.
Segmentation dimensions modeled include automated versus customized versus semi-automated formats, captive IP owners versus third-party retailers versus distributor networks, and retail store versus warehouse versus distribution center placements. CAGRs were derived from installed base expansion trajectories, replacement cycle analysis, and penetration rate assumptions across the projection horizon. Industry-specific forecast inputs incorporated METI energy efficiency incentive uptake rates and SAMR compliance transition timelines for probability disclosure mandates.
Forecasts assume regulatory continuity in China's SAMR disclosure frameworks and Japan's METI certification protocols; material policy shifts would require re-modeling. Semiconductor supply concentration risks and youth-protection framework evolution in additional geographies represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Plastic Extruding Equipment Market
Packaging Machinery
Stretch Blow Molding Machines Market
Packaging Machinery
Granule Filling Machine Market
Packaging Machinery
Clamshell Labeling Machines Market
Packaging Machinery
Tray Sealing Machines Market
Packaging Machinery
Palletizing Machines Market
Packaging Machinery
Package Closing Machines Market
Packaging Machinery
Bundling Machine Market
Packaging Machinery
Carton Folding and Gluing Machine Market
Packaging Machinery
Tea Packing Machine Market
Packaging Machinery
Automatic Auger Fillers Market
Packaging Machinery
Die Cutting Machine Market
Packaging Machinery
North America Automatic Carton Erector Market
Packaging Machinery
Tray and Sleeve Packing Machines Market
Packaging Machinery
Global Paper Napkin Making Machine Market
Packaging Machinery
Kitchen/ Toilet Roll Converting Machines Market