
 Piston Fillers Market | 2026-2036
Piston Fillers Market Size, Share, and Industry Trends Forecast 2026-2036
Piston Fillers Market Outlook
Stainless steel is realigning equipment economics across the piston fillers sector as manufacturers substitute 316L grades for legacy 304 formulations to satisfy pharmaceutical clean-in-place protocols. Krones AG leverages its German engineering base to dominate high-speed aseptic filling lines for dairy and beverage producers. All-Fill Inc. specializes in semi-automatic tabletop configurations that occupy the mid-volume contract packaging niche in North America. GEA Group extends its position through backward integration into pump and valve subsystems, reducing lead times for custom sanitary installations.
A piston filler is a positive-displacement packaging machine that draws product into a precision-machined cylinder before mechanically driving a piston to discharge a preset volume through a nozzle, achieving fill accuracies within ±0.5% for viscous liquids and pastes. Fully automatic fillers command the largest installed base due to throughput requirements in high-volume food and pharmaceutical operations, while pneumatic technology leads technology adoption for its reliability in explosive atmospheres governed by ATEX directives. Electric technology represents the fastest-expanding segment as brushless servo motors displace air-driven actuators in cleanroom environments demanding precise speed control and reduced contamination risk.
FDA 21 CFR Part 11 electronic records requirements and EU MDR Annex I general safety standards compel pharmaceutical and medical device manufacturers to validate every filling parameter traceability, directly shaping equipment specification sheets and procurement criteria. ISO 9001 quality management certification has become a baseline market access requirement rather than a differentiator for equipment vendors serving regulated industries. Stakeholders must monitor how FDA draft guidance on continuous manufacturing may redefine batch-size flexibility requirements for piston filler configurations in oral solid dose and parenteral applications.
Market Dynamics
The migration from pneumatic to electric servo actuation is compressing equipment replacement cycles as pharmaceutical manufacturers pursue ATEX-compliant cleanroom configurations that eliminate compressed air contamination pathways.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates force pharmaceutical manufacturers to validate every filling parameter, directly expanding demand for traceable automatic piston filler systems with integrated data logging.
- Biologics manufacturing:Vaccine and cell therapy producers require aseptic filling lines capable of handling shear-sensitive viscous formulations, driving precision-engineered piston filler procurement.
- German precision engineering clusters:Concentrated supplier networks around Stuttgart and Munich reduce lead times for custom sanitary installations serving global vaccine producers.
Market Restraints
- 316L stainless steel input costs:Nickel price volatility and alloy sourcing constraints inflate equipment bill-of-materials by 15-25% for pharmaceutical-grade configurations.
- Supply concentration risk:German and Italian pump subsystem suppliers control critical valve and seal technologies, creating single-source dependencies for high-accuracy dosing modules.
- ATEX directive compliance friction:Explosion-proof pneumatic certifications for chemical and solvent filling applications impose extended validation timelines that delay equipment deployment.
Strategic Opportunities
- India contract manufacturing expansion:CDSCO regulatory alignment with ICH Q7 guidelines positions Indian CMOs to absorb piston filler demand from Western cost-pressured sponsors.
- Continuous manufacturing FDA draft guidance:Batch-size flexibility requirements for oral solid dose applications favor modular piston filler configurations with rapid changeover capabilities.
- Servo-electric and vision system convergence:Integrated in-line checkweighing and machine vision enable real-time fill verification, opening premium pricing tiers for integrated line suppliers.
Industry Challenges
- Mechatronics skill scarcity:Servo motor programming and brushless drive calibration expertise concentrates in German and Japanese automation hubs, constraining field service capacity elsewhere.
- EU MDR Annex I validation timelines:General safety and performance requirements for medical device filling equipment extend certification cycles to 18-24 months, compressing vendor cash conversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Piston Fillers Market |
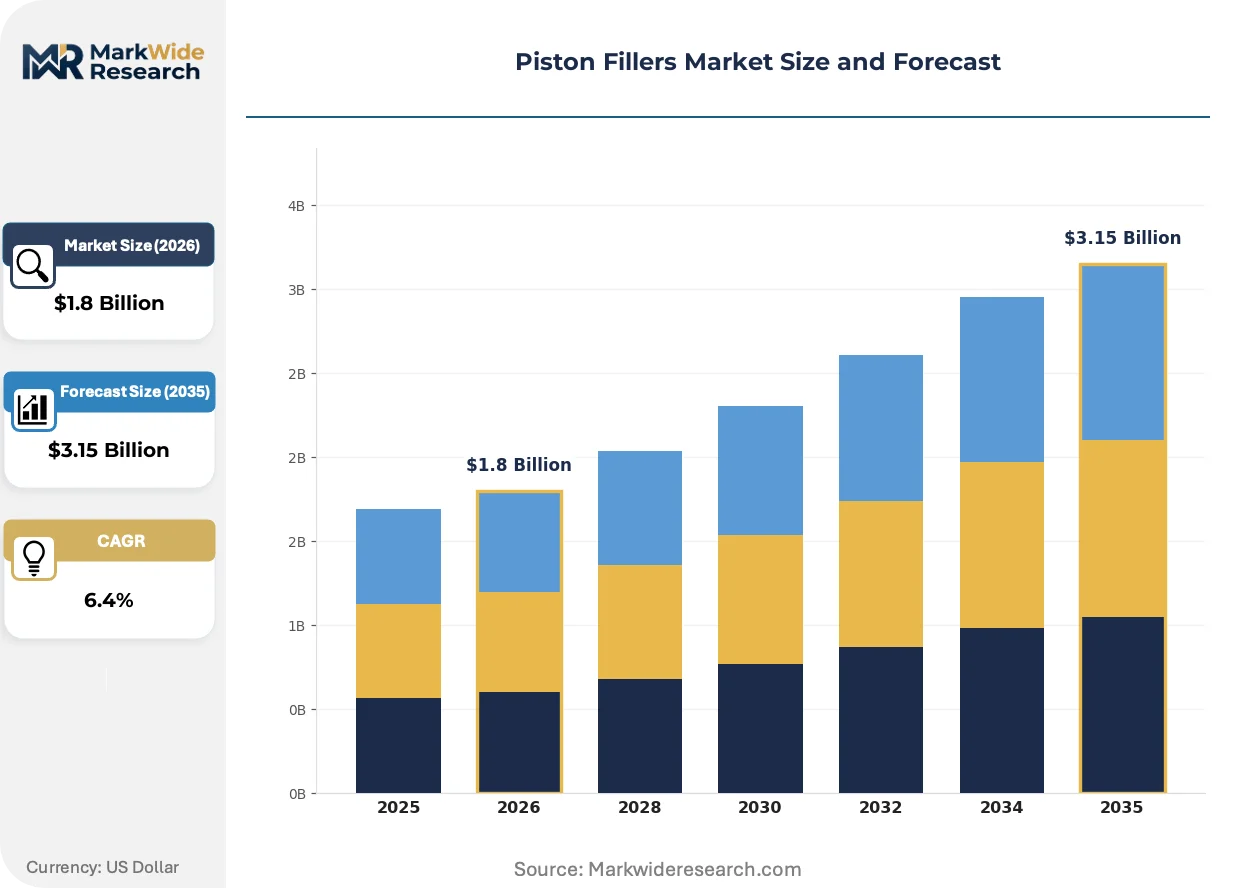
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Fillers, Semi-Automatic Fillers, Fully Automatic Fillers, Tabletop Fillers End User: Food Industry, Pharmaceutical Companies, Cosmetics Manufacturers, Chemical Producers Application: Liquid Filling, Paste Filling, Cream Filling, Gel Filling Technology: Pneumatic Technology, Electric Technology, Mechanical Technology, Vacuum Technology |
| Companies Covered | Accutek Packaging Equipment, All-Fill Inc., Krones AG, GEA Group, IMA Group, Busch Machinery, Cleveland Equipment & Machinery, Raque Food Systems, E-PAK Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Piston Fillers Market Strategic Shifts
Servo-electric actuation is rewriting equipment architecture across pharmaceutical cleanrooms, displacing legacy pneumatic systems that introduce oil vapor and particulate contamination risks into aseptic processing environments.
Brushless servo motors with integrated absolute encoders deliver positional accuracy within ±0.1 millimeters, enabling pharmaceutical manufacturers to tighten fill weight variation bands for high-value biologics. Vaccine producers in Germany and Switzerland are specifying all-electric filling lines for new mRNA manufacturing facilities. This precision is rewriting competitive requirements for equipment vendors, forcing pneumatic specialists to develop hybrid electric-pneumatic architectures or cede premium market tiers.
EU MDR Annex I general safety standards and FDA 21 CFR Part 11 electronic records requirements are converging to mandate machine-level data integrity architectures. Equipment must now embed audit trails, electronic signatures, and tamper-evident logging at the PLC layer rather than through external MES integration. Pharmaceutical and medical device manufacturers are responding by rewriting procurement specifications to require native compliance modules, disqualifying legacy platforms that depend on third-party software overlays.
Buying committees are consolidating vendor relationships around single-source line integration responsibility, displacing the historical practice of sourcing fillers, cappers, and labelers from separate specialists. Large pharmaceutical manufacturers now demand turnkey validation packages spanning IQ/OQ/PQ documentation from one accountable supplier. This pattern concentrates procurement authority in Germany, where integrated line builders dominate high-value vaccine and biologics contracts, compressing opportunities for standalone equipment vendors.
Piston Fillers Market Segmentation
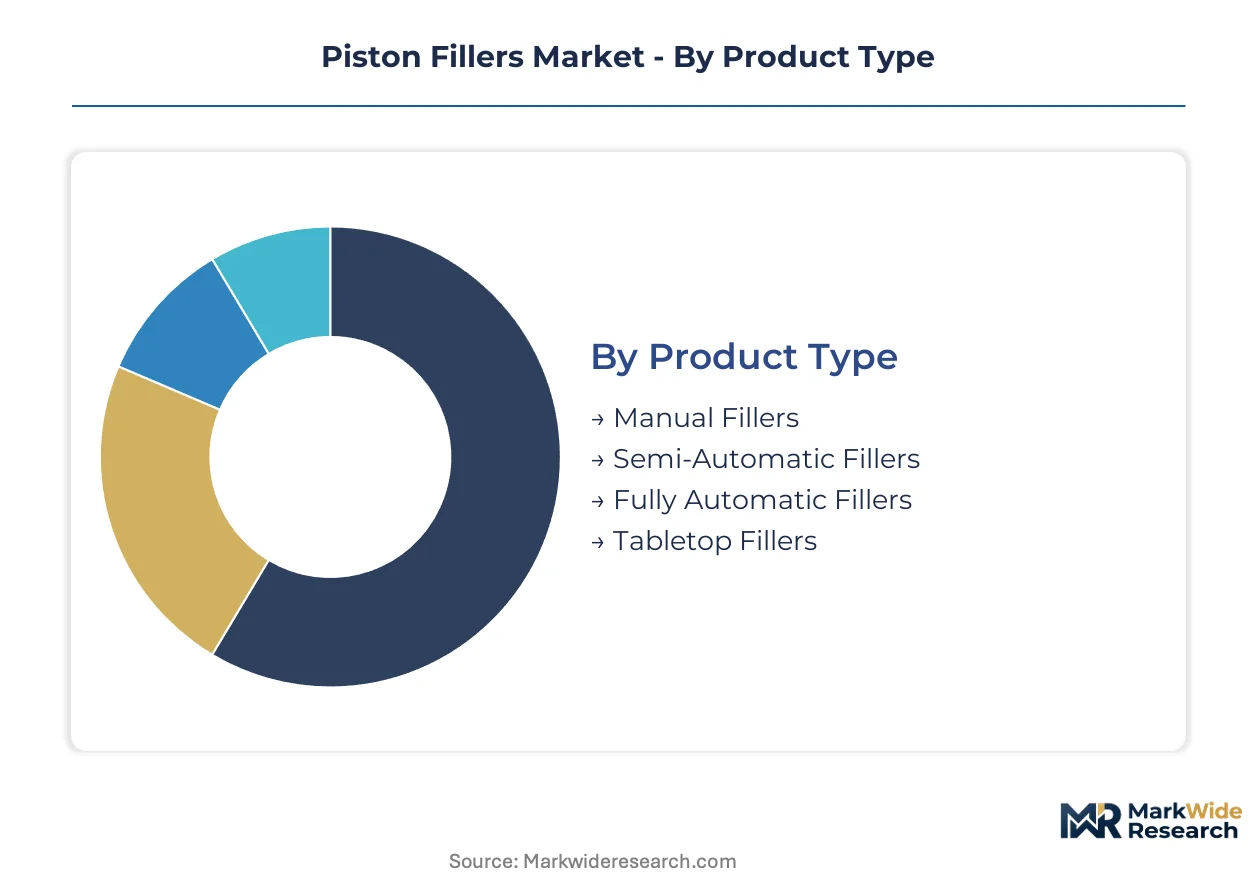
Piston filler procurement patterns diver sharply across automation tiers and regulatory exposure, with pharmaceutical-grade configurations demanding validation documentation that manual systems never require. Segmentation reveals where equipment margins concentrate and which technology transitions are compressing replacement cycles.
Product Type:
FDA 21 CFR Part 11 and EU MDR Annex I impose electronic records mandates on automatic configurations while exempting manual equipment, creating a two-tier compliance burden that shapes vendor R&D allocation and pricing architecture.
- Fully Automatic Fillers:These systems integrate servo-electric actuation with machine-level data integrity architectures, embedding audit trails and tamper-evident logging at the PLC layer. German vaccine producers and Swiss biologics manufacturers specify all-electric lines for mRNA facilities, driven by ATEX-compliant cleanroom requirements that eliminate compressed air contamination pathways.
- Semi-Automatic Fillers:Tabletop configurations with pneumatic or hybrid actuation occupy mid-volume contract packaging niches, particularly among North American CMOs serving cost-pressured sponsors. FDA validation protocols for pharmaceutical applications still apply, though reduced throughput demands lower capital outlays than fully automatic alternatives.
- Manual Fillers:Hand-operated piston mechanisms serve small-batch artisanal producers and early-stage formulation labs where precision requirements remain below ±1% tolerance bands.
- Tabletop Fillers:Compact semi-automatic units designed for laboratory-scale production and pilot manufacturing lines, prioritizing rapid changeover over throughput maximization.
Fully automatic fillers sit at the top of the volume ranking, with electric-actuation configurations climbing the fastest as brushless servo motors displace legacy pneumatic systems.
End User:
Margin structures vary dramatically across end-use verticals, with pharmaceutical and biologics applications commanding premium pricing for 316L stainless steel construction and native compliance modules.
- Pharmaceutical Companies:Vaccine, cell therapy, and parenteral drug producers require aseptic filling lines capable of handling shear-sensitive viscous formulations with fill accuracies within ±0.5%. FDA and EMA validation timelines extend procurement cycles to 18-24 months, compressing vendor cash conversion but locking in long-term service contracts.
- Food Industry:Dairy and beverage producers prioritize throughput maximization and clean-in-place protocols, with German engineering clusters supplying high-speed aseptic lines that dominate global dairy packaging contracts.
- Cosmetics Manufacturers:Cream and gel filling operations demand sanitary pump subsystems with rapid changeover capabilities for SKU proliferation, though regulatory burdens remain lighter than pharmaceutical applications.
- Chemical Producers:Solvent and hazardous material filling requires ATEX-certified pneumatic configurations for explosive atmospheres, imposing extended validation timelines that delay equipment deployment.
Pharmaceutical companies anchor the premium tier by revenue, with food industry volume expanding most quickly in emerging contract manufacturing geographies.
Application:
Viscosity handling requirements dictate pump subsystem selection and nozzle geometry, with high-value biologics driving precision-engineered configurations that command substantial price premiums over standard liquid filling platforms.
- Liquid Filling:Standard aqueous and solvent-based formulations dominate installed base volume, with pneumatic technology leading adoption for chemical and beverage applications governed by ATEX and sanitary standards respectively.
- Paste Filling:High-viscosity products including pharmaceutical ointments and food condiments require precision-machined cylinders with hardened piston surfaces to maintain dosing accuracy across temperature variations.
- Cream Filling:Shear-sensitive cosmetic and dermatological formulations demand low-pulsation pump architectures that preserve emulsion stability during displacement.
- Gel Filling:Thixotropic and non-Newtonian fluid handling challenges equipment vendors to customize piston geometries and drive profiles for consistent discharge through narrow-gauge nozzles.
Liquid filling maintains the largest installed base, with paste filling applications gaining share fastest as topical drug delivery formats proliferate.
Technology:
Actuation technology selection determines contamination risk profiles, maintenance intervals, and energy consumption patterns, with electric servo systems rewriting competitive requirements for pharmaceutical cleanroom deployments.
- Electric Technology:Brushless servo motors with integrated absolute encoders deliver positional accuracy within ±0.1 millimeters, enabling tightened fill weight variation bands for high-value biologics. German and Swiss vaccine producers are specifying all-electric architectures for new manufacturing facilities.
- Pneumatic Technology:Compressed air-driven actuators retain dominance in explosive atmospheres governed by ATEX directives, though oil vapor and particulate contamination risks exclude them from aseptic pharmaceutical processing.
- Mechanical Technology:Cam-driven and linkage-based actuation persists in legacy food and chemical installations where precision requirements tolerate ±1% variation bands and capital constraints favor proven simplicity over upgrade investment.
- Vacuum Technology:Suction-assisted filling mechanisms handle foam-prone and degassing-sensitive formulations in cosmetic and specialty chemical applications, complementing rather than replacing positive-displacement piston architectures.
Pneumatic technology retains the broadest installed base, with electric technology showing the steepest expansion trajectory as pharmaceutical cleanroom specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering clusters around Stuttgart and Munich anchor equipment supply for global vaccine and biologics producers, with concentrated supplier networks reducing lead times for custom sanitary installations.
United States
FDA 21 CFR Part 11 electronic records mandates drive pharmaceutical manufacturers to validate every filling parameter, expanding procurement of traceable automatic piston filler systems with integrated data logging. The FDA's draft guidance on continuous manufacturing is reshaping batch-size flexibility requirements for oral solid dose applications. Greater Boston and Research Triangle Park host contract manufacturing organizations absorbing demand from cost-pressured sponsors seeking domestic production capacity.
Germany
EMA validation protocols and EU MDR Annex I general safety standards compel equipment upgrades across pharmaceutical operations, with 18-24 month certification cycles compressing vendor cash conversion. ATEX-compliant cleanroom specifications are eliminating compressed air contamination pathways in aseptic processing environments. Stuttgart and Munich precision engineering clusters supply filling lines to global vaccine producers, with backward integration into pump and valve subsystems reducing lead times for custom installations.
Switzerland
Swissmedic regulations for medical device and pharmaceutical manufacturing enforce stringent dosing accuracy requirements that favor all-electric filling architectures. mRNA vaccine producers are specifying brushless servo motor configurations for new manufacturing facilities to achieve positional accuracy within tight variation bands. Basel and Zurich host biologics manufacturing operations driving premium-tier equipment procurement.
India
CDSCO regulatory alignment with ICH Q7 guidelines positions Indian contract manufacturing organizations to absorb piston filler demand from Western cost-pressured sponsors. The country's national pharmaceutical regulator is tightening validation requirements for export-oriented facilities serving regulated markets. Maharashtra and Gujarat pharmaceutical clusters are expanding aseptic filling capacity for generic injectables and biosimilars.
China
NMPA standards for pharmaceutical equipment manufacturing are converging with international GMP requirements, driving domestic producers toward 316L stainless steel construction and native compliance modules. The national medical products administration is strengthening traceability mandates for critical drug manufacturing equipment. Yangtze River Delta pharmaceutical manufacturing bases are upgrading filling lines to serve both domestic and export markets.
Piston Fillers Market Competitive Environment
Global majors compete with regional champions across validation documentation and turnkey integration capabilities, with procurement authority concentrating around single-source line integration responsibility. The vendor base separates into three tiers: integrated line builders dominating high-value vaccine contracts, standalone equipment specialists serving mid-volume niches, and regional fabricators competing on capital cost. Strategic moves center on M&A for pump subsystem control and geographic expansion into contract manufacturing growth markets.
Among German engineering conglomerates, Krones AG and GEA Group exemplify the integrated line builder archetype, with Krones leveraging its engineering base and GEA extending position through upstream control over pump and valve subsystems. All-Fill Inc. represents the North American mid-volume specialist, occupying tabletop configuration niches in contract packaging. These three anchors illustrate how competitive positioning stratifies across premium validation-heavy, mid-tier flexible, and economy capital-sensitive tiers.
| Leading Market Players |
|---|
| Accutek Packaging Equipment |
| All-Fill Inc. |
| Krones AG |
| GEA Group |
| IMA Group |
| Busch Machinery |
| Cleveland Equipment & Machinery |
| Raque Food Systems |
| E-PAK Machinery |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical OEM procurement committees concentrate buying authority for high-accuracy dosing modules, enforcing three-tier pricing stratification across premium validation-heavy, mid-tier flexible, and economy capital-sensitive equipment categories. This buyer concentration amplifies cost pass-through leverage for German and Italian pump subsystem suppliers controlling critical valve and seal technologies.
Pricing Analysis
Input-cost pass-through from 316L stainless steel alloy sourcing constrains margin flexibility for pharmaceutical-grade configurations, with nickel price volatility inflating equipment bill-of-materials substantially. Price differentiation hinges on FDA 21 CFR Part 11 certification tier and native compliance module integration, with fully automatic electric-actuation lines commanding substantial premiums over pneumatic alternatives. Pricing pressure stems from Western sponsor cost pressures redirecting procurement toward Indian and Chinese contract manufacturing organizations. Mid-volume North American CMOs exhibit highest price sensitivity, while German vaccine producers demonstrate lowest elasticity due to ATEX-compliant cleanroom specifications.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Munich, and Northern Italy anchor hub-and-spoke patterns for precision-engineered pump and valve subsystems serving global biologics producers. Manufacturing concentration in Germany, Italy, and Switzerland draws from specialized 316L stainless steel foundries and brushless servo motor suppliers concentrated in Japanese and German automation hubs. Single-source dependencies for high-accuracy dosing modules create structural vulnerability to alloy sourcing constraints and mechatronics skill scarcity. Distribution runs through integrated line builders offering turnkey validation packages rather than standalone equipment vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with FDA draft guidance on continuous manufacturing and EU MDR Annex I validation timelines perpetually refreshing equipment replacement cycles across pharmaceutical and biologics manufacturing operations.
For Market Incumbents: Deepen backward integration into pump and valve subsystems to defend against emerging Asian equipment fabricators competing on capital cost. Captive supply of sanitary-grade 316L components and in-house brushless servo motor programming capacity insulates margin position from German and Italian supplier concentration risk. Prioritize modular piston filler configurations enabling rapid changeover capabilities for batch-size flexibility requirements. For New Entrants and Emerging Players: Mid-volume Indian contract manufacturing organizations represent the most penetrable buyer archetype, with CDSCO regulatory alignment creating qualification pathways for export-oriented facilities. Target tabletop semi-automatic configurations with hybrid electric-pneumatic architectures serving cost-pressured Western sponsors seeking geographic diversification. Establish validation documentation partnerships with established European engineering consultants to overcome 18-24 month certification cycle barriers. For Investors and Strategic Acquirers: German diversified industrial conglomerates are the most active acquirer in this space, consolidating pump subsystem specialists to secure single-source line integration responsibility. Long-term viability rests on exposure to mRNA and cell therapy manufacturing expansion rather than legacy small-molecule pharmaceutical volume. Monitor FDA finalization of continuous manufacturing guidance as the critical inflection signal for modular equipment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pump Subsystems | GEA Group's upstream control over valve technologies reduces lead times for custom sanitary installations serving vaccine producers. |
| Servo-Electric Architecture Transition | Brushless motor configurations displace pneumatic systems in Swiss mRNA facilities demanding ATEX-compliant cleanroom specifications. |
| Modular Batch-Size Flexibility Development | Rapid changeover capabilities align with FDA draft guidance on continuous manufacturing for oral solid dose applications. |
| Indian CMO Validation Partnership | CDSCO-aligned documentation packages unlock Maharashtra and Gujarat pharmaceutical clusters for Western sponsor cost redirection. |
| Native Compliance Module Integration | Machine-level data integrity architectures embed audit trails at the PLC layer, satisfying converging FDA and EU MDR mandates. |
Study Parameters
Bottom-up pharmaceutical and biologics manufacturing modeling reconciled against top-down precision engineering equipment tracking forms the analytical core of this study. Primary interviews with plant engineers, OEM procurement teams, regulatory affairs leads, and aftermarket service heads combine with secondary validation from FDA 510(k) filings, EMA submission databases, SEC equipment supplier disclosures, and German engineering association production statistics. This dual-structure approach enables triangulation between end-use demand signals and supply-side capacity constraints.
Historical trendline analysis across installed base replacement cycles, technology transition velocities, and regulatory compliance expenditure patterns informs the projection framework. Segmentation dimensions include automation tier, actuation technology, end-use vertical, viscosity handling requirement, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to validated baseline estimates, with industry-specific inputs incorporating ATEX directive adoption timelines and servo-electric penetration trajectories in aseptic processing environments.
Underlying measurement precision varies by segment; fully automatic pharmaceutical-grade configurations carry tighter precision than manual artisanal equipment due to documented procurement transaction visibility. Forecasts reflect stated assumptions regarding regulatory timeline stability, alloy price trajectory, and technology substitution elasticity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Hardgel Liquid Capsule Filling Machines Market
Packaging Machinery
Tube Sealing Machines Market
Packaging Machinery
Poly Bagging Machines Market
Packaging Machinery
Candy Wrapping Machine Market
Packaging Machinery
Bakery Packaging Machine Market
Packaging Machinery
Oral Dosage Powder Packaging Machines Market
Packaging Machinery
Vacuum Sealing Machine Market
Packaging Machinery
Packaging Machine Heaters Market
Packaging Machinery
Hand-Held Capping Machines Market
Packaging Machinery
Corrugated Box Making Machine Market
Packaging Machinery
Thermoform Fill Sealing Machine Market
Packaging Machinery
Powder Auger Fillers Market
Packaging Machinery
Oil Packing Machine Market
Packaging Machinery
Plastic Blow Molding Machine Market
Packaging Machinery
Bundling Machine Market
Packaging Machinery
Sleeve Wrapping Machine Market