
 Plastic Vacuum Forming Machinery Market | 2026-2036
Plastic Vacuum Forming Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Vacuum Forming Machinery Market Outlook
China is tilting toward domestic vacuum forming machinery capacity to reduce reliance on European and Japanese imports. Brown Machine Group leverages its North American installed base to sustain aftermarket parts revenue. MAAC Machinery anchors heavy-gauge thermoforming demand across automotive and aerospace supply chains. ILLIG Maschinenbau dominates high-speed packaging applications with integrated tool and machine offerings.
Plastic vacuum forming machinery heats thermoplastic sheets until pliable, then draws them over a mold via vacuum to create shaped components with wall thicknesses typically ranging from 0.25 mm to 12.7 mm depending on gauge class. The process serves primary industrial purposes in packaging tray production, automotive interior panels, and electronic device housings where cost-efficient medium-volume output outweighs injection molding capital requirements. Automated multi-station systems capture expanding margin pools as labor costs rise and cycle-time compression becomes a competitive priority across packaging end users. Manual and single-station categories retain stable positions in prototyping shops and low-volume custom fabrication where capital constraints limit automation uptake. Bioplastic forming technology remains nascent but draws strategic R&D allocation as brand owners specify renewable-content packaging commitments.
The EPA regulates volatile organic compound emissions from heating and forming operations under Clean Air Act provisions, while OSHA sets permissible exposure limits for heated plastic fumes in manufacturing environments. The EU Machinery Directive and CE marking requirements shape product safety standards and market access conditions for equipment sold into European end-user facilities. Stakeholders must monitor evolving extended producer responsibility frameworks and polymer-specific recycling mandates that will determine which material-forming technology combinations retain long-term viability.
Market Dynamics
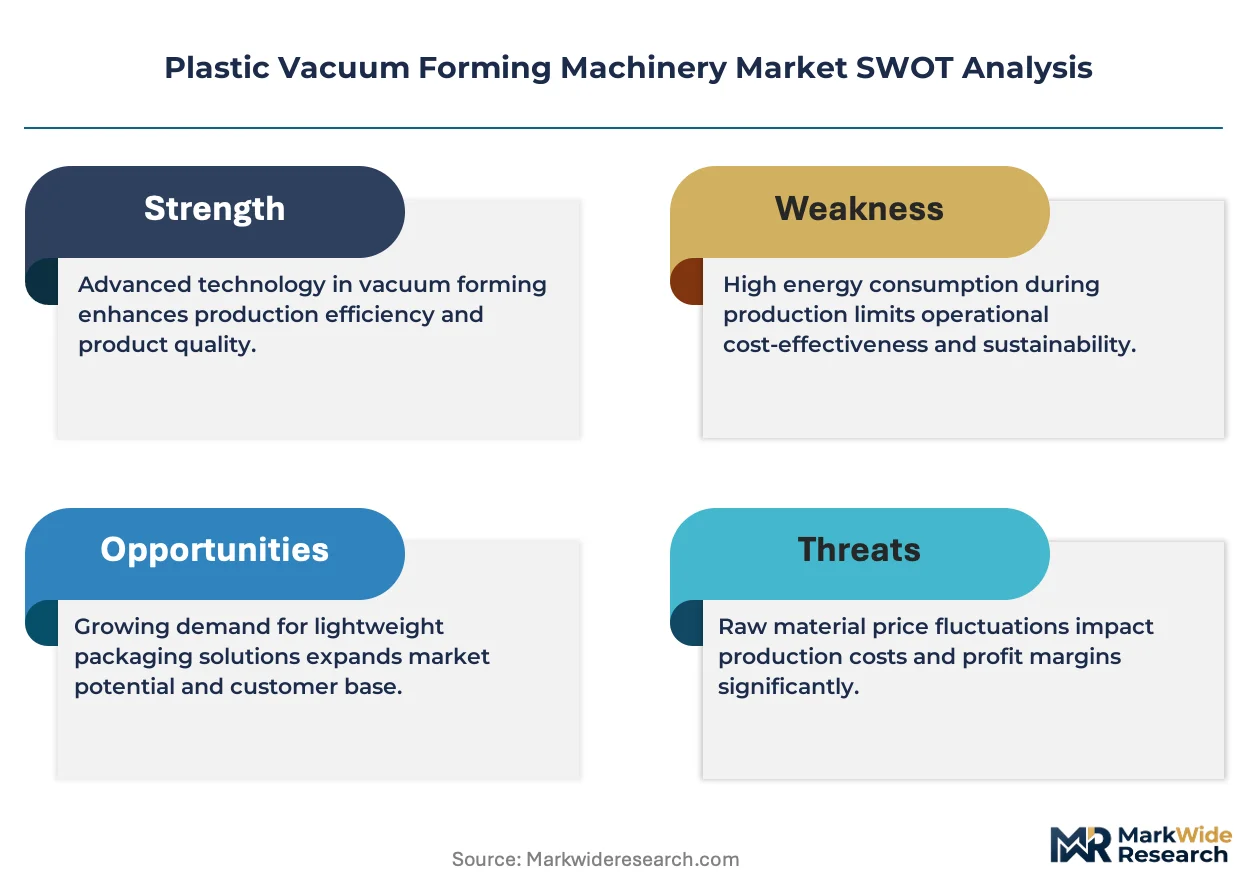
The EU F-Gas Regulation and REACH compliance are compressing demand toward electric and low-emission forming systems, while automotive lightweighting mandates pull machinery orders toward high-speed, multi-station configurations capable of thin-gauge precision output.
Growth Catalysts
- Automotive lightweighting mandates:OEMs specify vacuum-formed interior panels to replace heavier injection-molded components, driving machinery upgrades across tier-one suppliers in Germany and Japan.
- REACH polymer restrictions:The EU chemical framework accelerates converter investment in machinery compatible with bio-based and recycled-content thermoplastics.
- Packaging automation:Labor cost escalation across food processing end-users is virtualizing manual forming lines with robotic stacking and trim-in-place systems.
Market Restraints
- Steel and aluminum price volatility:Frame and platen construction costs fluctuate with commodity markets, compressing margin predictability for machinery builders.
- Heater element supply concentration:Ceramic infrared emitters and quartz tube suppliers cluster in East Asian manufacturing hubs, exposing European and North American OEMs to logistics disruption.
- Injection molding substitution:Thin-wall precision applications below 0.5 mm thickness increasingly migrate to high-speed injection systems with faster cycle economics.
Strategic Opportunities
- India packaging conversion:Food service and pharmaceutical tray demand outpaces domestic machinery supply, creating import substitution potential for European and Japanese equipment vendors.
- Bioplastic forming R&D:PLA and PHA sheet processing requires modified heating profiles and vacuum control, opening premium machinery tiers for early technical leaders.
- CE marking convergence:The EU Machinery Directive and impending CSRD reporting obligations favor integrated machine-tool suppliers capable of delivering certified, traceable production lines.
Industry Challenges
- Thermoforming process engineering expertise:The workforce gap in sheet rheology and mold design constrains converter adoption of advanced multi-zone heating controls.
- Legacy PLC integration:Brownfield facilities face protocol incompatibility when retrofitting Industry 4.0 data acquisition to 1990s-vintage forming lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Vacuum Forming Machinery Market |
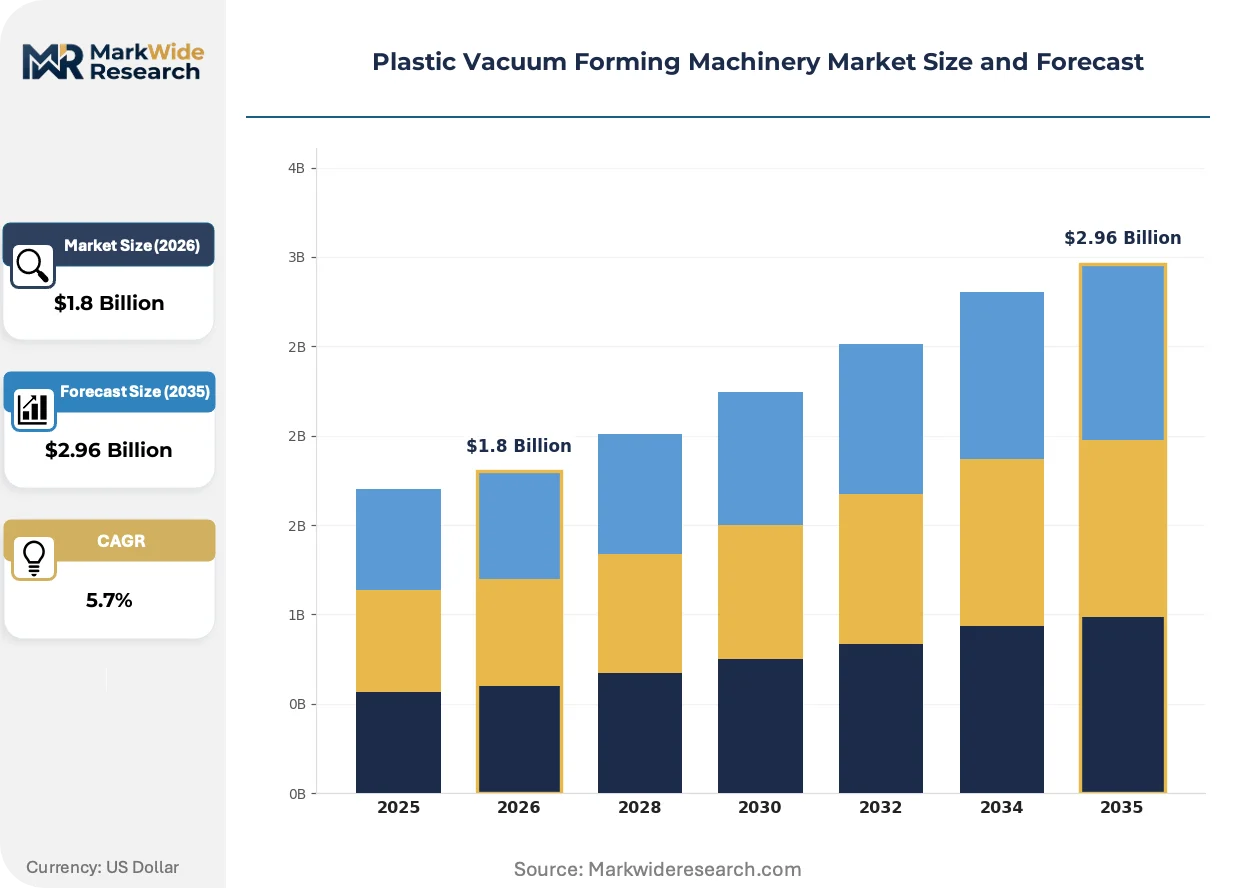
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Station, Multi Station, Automated, Manual End User: Packaging, Automotive, Electronics, Consumer Goods Material Type: ABS, PVC, PET, Polypropylene Technology: Thermoforming, Pressure Forming, Bioplastic Forming, Vacuum Forming |
| Companies Covered | Brown Machine Group, MAAC Machinery, ILLIG Maschinenbau, COMI SpA, Asano Laboratories, GABLER Thermoform, TZ Machinery, Formech Inc., Kiefel GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Vacuum Forming Machinery Market Strategic Shifts
Digital twin technology and predictive maintenance architectures are virtualizing traditional machinery sales models, while regulatory pressure on fluorinated gases and polymer traceability forces hardware redesign across the supplier base.
Multi-zone ceramic infrared heating systems are virtualizing conventional quartz tube arrays in high-volume packaging applications. Major food tray converters in Germany and the Netherlands specify these units for 40% faster heat-up and precise zonal temperature mapping. The technology is virtualizing energy consumption benchmarks and enabling real-time process adjustment through integrated thermocouple feedback loops.
REACH Annex XVII restrictions on persistent organic pollutants are forcing heater element redesigns and alternative bonding adhesives in machinery bound for EU end-user facilities. Manufacturers must now certify full material disclosure across supply chains to maintain CE marking validity. Packaging machinery vendors serving export markets are dual-certifying systems to preempt regulatory divergence between European and North American requirements.
Converter procurement teams increasingly unbundle aftermarket service contracts from initial machinery purchases, pressuring OEMs to compete on transparent parts pricing and remote diagnostic capabilities. This unbundling is most pronounced among mid-volume automotive interior suppliers in the US Midwest and Mexico's Bajío region, where maintenance cost visibility now dominates vendor selection criteria ahead of capital expenditure terms.
Plastic Vacuum Forming Machinery Market Segmentation
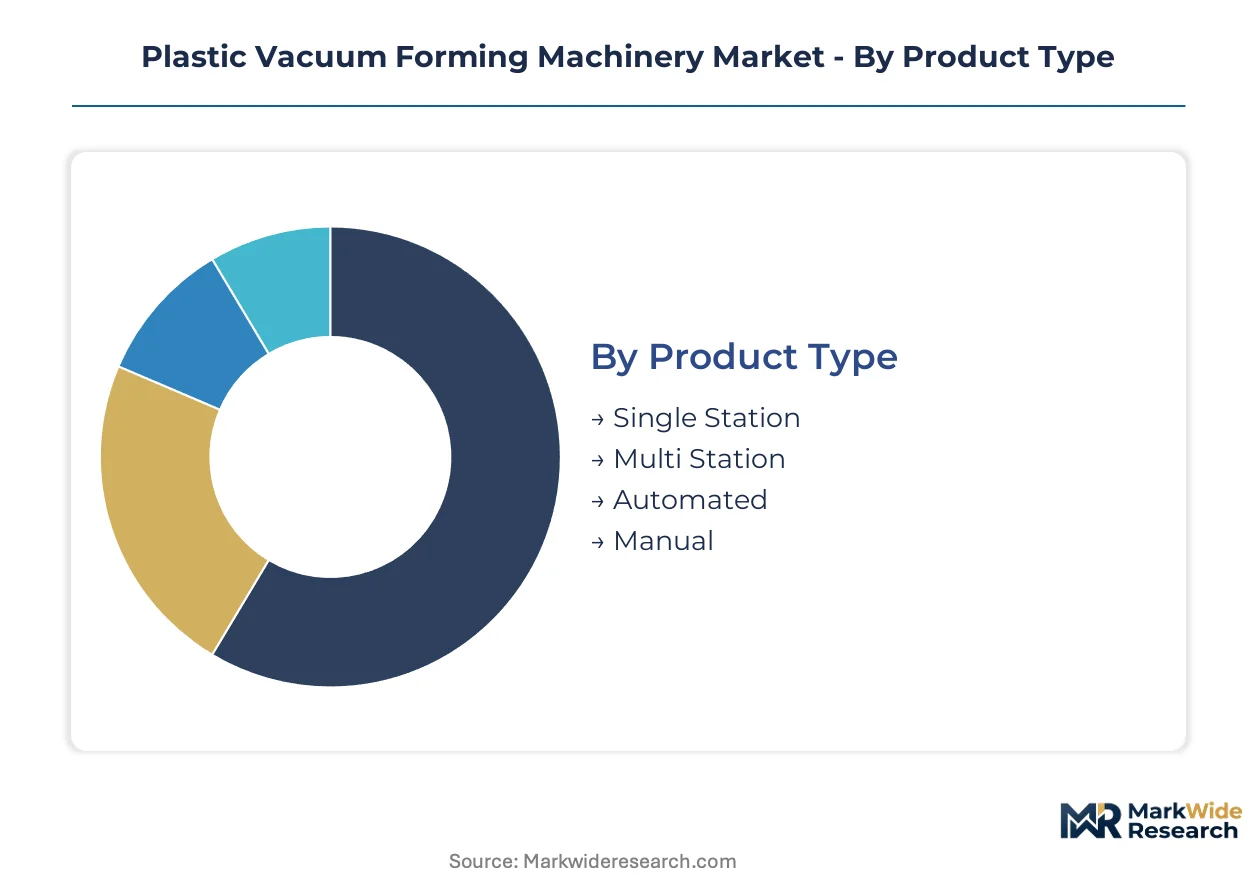
Segmentation in plastic vacuum forming machinery reveals how automation intensity, material compatibility, and end-use precision requirements reshape procurement patterns across converter tiers. Distinct technical specifications govern equipment selection for thin-gauge packaging versus heavy-gauge automotive panels.
Product Type:
Mature single-station architectures coexist with emerging robotic multi-station configurations as labor economics shift across manufacturing geographies.
- Single Station:Compact footprint units with manual mold loading serve prototyping shops and custom fabricators where batch sizes fall below 500 units. German tool-and-die specialists in Stuttgart retain these systems for automotive interior mock-ups despite longer cycle times.
- Multi Station:Rotary and inline configurations synchronize heating, forming, and trimming across indexed stations to compress cycle economics. Japanese packaging converters in Osaka specify these for food tray volumes exceeding 10 million units annually, driven by convenience store chain consolidation.
- Automated:Robotic sheet loading and part stacking reduce direct labor content by 60% in high-wage manufacturing environments.
- Manual:Low-capital entry points dominate emerging market small enterprises and educational training facilities.
Multi Station retains volume leadership; Automated holds the steepest expansion curve.
End User:
Application-specific tooling investments separate high-margin precision segments from commodity volume categories.
- Packaging:Food service, pharmaceutical blister, and industrial tray applications demand sanitary-grade stainless steel contact surfaces and rapid mold changeover systems. Dutch dairy packaging clusters specify equipment with 15-minute tool swap capabilities to manage SKU proliferation.
- Automotive:Door panels, instrument clusters, and HVAC ducting require heavy-gauge pressure forming with robotic trim integration. Tier-one suppliers in Michigan and Mexico's Guanajuato state upgrade machinery to meet OEM lightweighting targets and interior acoustic specifications.
- Electronics:ESD-safe housings and equipment enclosures prioritize dimensional stability and surface finish consistency.
- Consumer Goods:Appliance panels and recreational equipment components balance aesthetic requirements with cost constraints.
Packaging retains volume leadership; Automotive holds the steepest expansion curve.
Material Type:
Polymer rheology and forming temperature windows dictate heater element specification and vacuum system sizing across machinery tiers.
- ABS:Amorphous terpolymer with broad processing window serves automotive interior panels and luggage shells where impact resistance and surface aesthetics converge. German OEMs specify ABS-compatible systems with multi-zone ceramic infrared arrays for dashboard component production.
- PVC:Chlorinated polymer requires corrosion-resistant vacuum plumbing and fume extraction systems to manage hydrogen chloride release during heating. REACH Annex XVII restrictions on plasticizer content are compressing converter investment in PVC-capable machinery across EU facilities.
- PET:Crystalline polyester demands precise temperature control to prevent hazing in transparent packaging applications.
- Polypropylene:High melt strength grades enable deep-draw forming for industrial pails and automotive underbody shields.
ABS retains volume leadership; PET holds the steepest expansion curve.
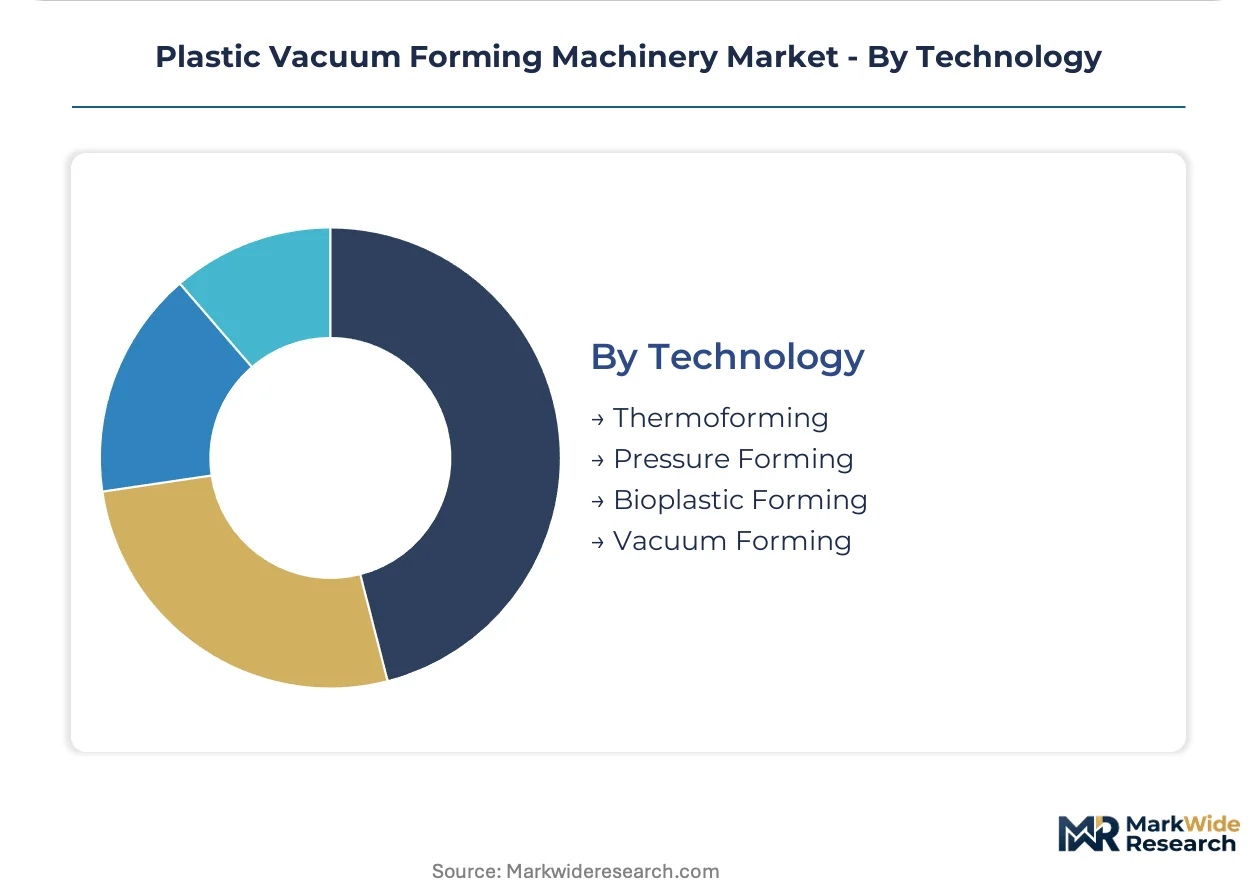
Technology:
Process physics and pressure differential capabilities separate precision-forming architectures from conventional vacuum-only systems.
- Thermoforming:Convective and radiant heating of thermoplastic sheets with vacuum or pressure assist represents the foundational process architecture. Italian packaging machinery builders in Bologna dominate high-speed roll-fed configurations for disposable cup and lid production.
- Pressure Forming:Positive air pressure up to 6 bar forces material against mold surfaces to capture fine detail and textured finishes. Aerospace interior suppliers in Toulouse specify pressure forming for aircraft seat shells and overhead bin components where cosmetic standards exceed vacuum-only capabilities.
- Bioplastic Forming:Modified heating profiles and controlled cooling rates accommodate PLA and PHA sheet structures with narrow processing windows.
- Vacuum Forming:Atmospheric pressure differential remains the baseline technology for shallow-draw applications with modest detail requirements.
Thermoforming retains volume leadership; Bioplastic Forming holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites European machinery import flows, while China's high-speed rail network connects Yangtze River Delta manufacturing clusters to interior conversion facilities.
Germany
Automotive interior panel demand from Stuttgart OEMs drives multi-station machinery procurement. The EU F-Gas Regulation compresses converter timelines for electric heating retrofits. The Swabian machinery belt around Stuttgart anchors ILLIG Maschinenbau and Kiefel GmbH operations serving export markets.
United States
Tier-one automotive suppliers in Michigan and Mexico's Bajío region upgrade forming lines for lightweighting compliance. EPA Clean Air Act provisions regulate volatile organic compound emissions from heating operations. Brown Machine Group leverages its North American installed base across the Midwest manufacturing corridor.
China
Domestic food tray and electronics housing production outpaces import capacity. MIIT industrial upgrading guidelines favor automated forming systems with Industry 4.0 integration. The Yangtze River Delta cluster around Shanghai concentrates TZ Machinery and local fabricator capacity.
Japan
Convenience store chain consolidation in Osaka drives high-volume packaging machinery demand. METI energy efficiency standards push ceramic infrared heater adoption. Asano Laboratories occupies a position within the Kansai precision machinery ecosystem.
India
Pharmaceutical blister and food service tray demand exceeds domestic machinery supply. BIS certification requirements shape import specifications for European and Japanese equipment. Maharashtra's Pune-Aurangabad industrial corridor attracts packaging converter investment.
Plastic Vacuum Forming Machinery Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying heater elements, vacuum pumps, and control systems. The vendor base concentrates around three strategic archetypes: integrated machine-tool suppliers delivering certified production lines, regional fabricators serving price-sensitive emerging markets, and aftermarket service providers monetizing installed base longevity. Competitive moves center on CE marking convergence for EU market access and unbundled service contracts with transparent parts pricing.
Among German-based integrated suppliers, ILLIG Maschinenbau GmbH and Kiefel GmbH exemplify the machine-tool archetype with combined system and tooling offerings. Brown Machine Group represents the North American installed-base specialist position. MAAC Machinery occupies a role within heavy-gauge thermoforming for automotive and aerospace supply chains.
| Leading Market Players |
|---|
| Brown Machine Group |
| MAAC Machinery |
| ILLIG Maschinenbau |
| COMI SpA |
| Asano Laboratories |
| GABLER Thermoform |
| TZ Machinery |
| Formech Inc. |
| Kiefel GmbH |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese forming machinery capacity is compressing export pricing while elevating margin pressure on European and Japanese OEMs serving premium segments. This utilization imbalance shapes procurement negotiations across automotive and packaging converter tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by CE marking certification and ceramic infrared heater specification. Price differentiation centers on automation intensity and after-sales service bundling, with unbundled maintenance contracts gaining traction among Midwest automotive suppliers. Cost compression in the economy tier is intensifying because Chinese fabricators are absorbing steel price volatility to maintain volume. Small-batch prototyping shops exhibit highest price sensitivity; aerospace interior suppliers demonstrate lowest sensitivity due to qualification timelines.
Supply Chain Analysis
Export-control restrictions on advanced ceramic heater technology and precision vacuum pump components limit flows from Japanese and German suppliers to certain end-user jurisdictions. Manufacturing concentrates in Germany, China, and Japan, with frame fabrication drawing from domestic steel mills and ceramic emitters sourcing from specialized East Asian foundries. Single-source vulnerability runs through quartz tube suppliers clustered in the Yangtze River Delta. Distribution runs through integrated machine-tool vendors and regional fabricator networks serving price-sensitive emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: CE marking and EPA compliance create switching costs that lock converters into qualified supplier relationships across multi-year depreciation cycles.
For Market Incumbents: Harden aftermarket revenue streams by unbundling service contracts with transparent parts pricing and remote diagnostic capabilities. Expand ceramic infrared heater in-house production to reduce East Asian supply exposure. Defend against injection molding substitution by embedding predictive maintenance architectures that compress converter downtime. For New Entrants and Emerging Players: India's pharmaceutical blister and food service tray demand offers the most penetrable white-space opportunity given domestic machinery supply deficits. Target Maharashtra's Pune-Aurangabad corridor with BIS-certified automated forming systems. Enter through bioplastic forming R&D partnerships that address PLA processing constraints without requiring full machine-tool capabilities. For Investors and Strategic Acquirers: Capital is best deployed toward integrated machine-tool suppliers with captive tooling design capabilities and established CE marking pathways. Long-term viability favors vendors capable of delivering certified, traceable production lines under tightening EU CSRD obligations. Monitor F-Gas Regulation amendment timelines as inflection indicators for electric heating retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Heater Production | Reduces East Asian supply concentration exposure for German and Japanese OEMs. |
| Bioplastic Forming R&D Partnership | Captures premium machinery tiers as brand owners specify renewable-content packaging. |
| CE Marking Convergence Investment | Secures EU market access under Machinery Directive and impending CSRD reporting. |
| Aftermarket Service Unbundling | Addresses procurement team demands for transparent parts pricing in North America. |
| India Market Entry with BIS Certification | Exploits pharmaceutical and food tray demand exceeding domestic machinery supply. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across converter procurement teams, machinery OEM engineering directors, aftermarket service heads, and plant engineers at tier-one automotive suppliers. Secondary validation drew from EU Machinery Directive filings, EPA Clean Air Act enforcement records, SEC 10-K disclosures from listed machinery builders, and customs trade data for forming equipment imports. Bottom-up machinery shipment tallies were triangulated against top-down end-use demand estimates from packaging and automotive production databases.
Calibration against historical capacity utilization rates and regulatory implementation timelines anchored the projection framework across the analysis window. Segmentation dimensions modeled include product type automation intensity, end-use application precision requirements, material compatibility specifications, and regional regulatory clusters. CAGRs were derived from slope analysis of indexed shipment volumes against macro manufacturing indicators. Industry-specific inputs incorporated EU F-Gas Regulation phase-out schedules and automotive OEM lightweighting target trajectories.
Practitioners should monitor polymer-specific recycling mandate expansions and extended producer responsibility framework rollouts for early signals of material-forming technology displacement. Forecasts reflect assumptions regarding ceramic heater supply continuity and REACH compliance cost pass-through. Material shifts in bioplastic sheet commercialization timelines or injection molding cycle economics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Case Packaging Machinery Market
Packaging Machinery
Thermoform Fill Sealing Machine Market
Packaging Machinery
Tablet Packing Machine Market
Packaging Machinery
Enveloping & Stacking Machine Market
Packaging Machinery
Barcode Labeller Machine Market
Packaging Machinery
Bag in Box Packaging Machine Market
Packaging Machinery
Packaging Machine Heaters Market
Packaging Machinery
Cosmetic Packaging Machinery Market
Packaging Machinery
Lamination Systems Market
Packaging Machinery
Aseptic Filling Machines Market
Packaging Machinery
In-Line Thermoforming Machine Market
Packaging Machinery
Shrink Label Machine Market
Packaging Machinery
Carton Erecting Machinery Market
Packaging Machinery
Cosmetic Filling Machines Market
Packaging Machinery
Vial Capping Machines Market
Packaging Machinery
Thermal Laminating Machine Market