
 Die Cutting Machine Market | 2026-2036
Die Cutting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Die Cutting Machine Market Outlook
Skilled press operator shortages across European print hubs is unwinding capacity utilization at conventional die cutting installations. Bobst leverages its service network density to sustain aftermarket revenue streams in folding carton plants. MK Masterwork anchors high-volume rotary die cutter supply to Asian packaging exporters. Heidelberger Druckmaschinen AG differentiates through integrated workflow software that links prepress to cutting stations.
Die cutting machines mechanically or digitally sever sheeted substrates into precise shapes using hardened steel rules, rotary cylinders, or directed laser beams, with cutting forces ranging from ten to hundreds of tons depending on material gauge and web speed. Flatbed die cutters dominate corrugated board processing due to tooling flexibility across short runs, while digital die cutters capture prototype and variable-data label workflows where laser or knife-based systems eliminate physical die fabrication lead times. Rotary die cutters command the highest throughput in flexible packaging and adhesive label rolls, where cylinder-based repeatability justifies capital intensity.
CE marking under the EU Machinery Directive governs electrical safety and emergency stop architecture for die cutting equipment sold across Europe, while OSHA lockout-tagout standards shape guarding and maintenance access design for US-installed presses. China's GB standards on mechanical safety and NMPA-adjacent industrial equipment certification create separate compliance pathways for imported systems. Stakeholders must monitor how evolving extended producer responsibility frameworks in packaging reshape specifications for material yield and scrap minimization.
Market Dynamics
Packaging converters face a structural squeeze between EU Green Deal mandates demanding scrap reduction and e-commerce fulfillment networks in Southeast Asia demanding faster throughput at lower unit costs. This tension is forcing capital allocation trade-offs between digital retrofitting and greenfield rotary installations.
Growth Catalysts
- EU Green Deal packaging waste rules:Mandatory scrap reduction targets push converters toward precision flatbed and laser systems that minimize substrate waste during carton production.
- E-commerce fulfillment networks:Southeast Asian logistics hubs require high-speed rotary die cutters capable of processing variable-format corrugated shipping boxes at web speeds exceeding 300 meters per minute.
- Relocation of carton sourcing:Multinational consumer brands are shifting folding carton procurement from China to Vietnam and Indonesia, stimulating greenfield die cutting capacity installations.
Market Restraints
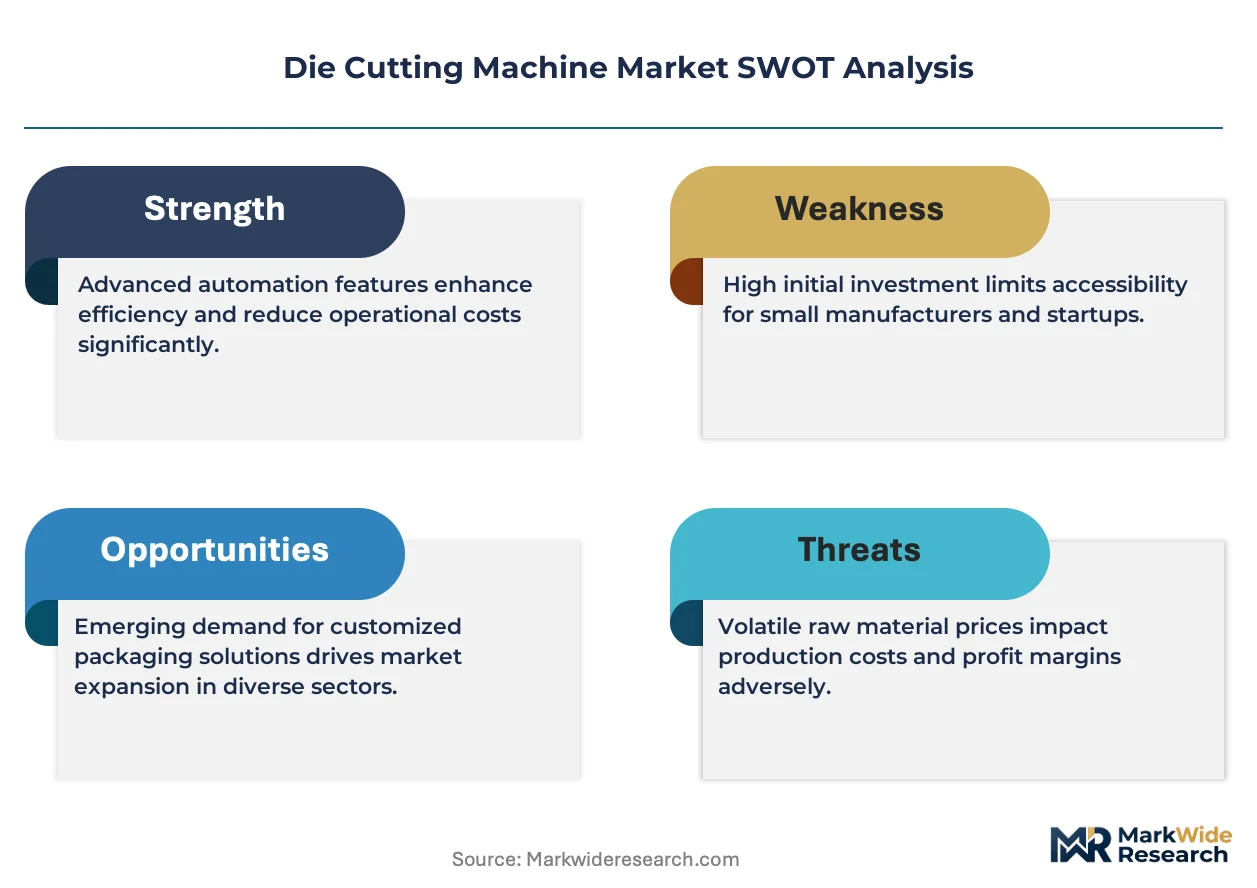
- Hardened steel rule supply concentration:Tooling fabrication for flatbed systems depends on specialty steel mills concentrated in Germany and Japan, creating input cost volatility and extended lead times.
- CE marking compliance burden:The EU Machinery Directive's electrical safety and emergency stop architecture requirements add certification timelines that delay European market entry for Asian equipment manufacturers.
- Digital cutting substitution:Laser and knife-based digital systems eliminate physical die fabrication for short-run prototyping, compressing addressable volume for conventional steel-rule flatbed installations.
Strategic Opportunities
- Indonesian packaging corridor:Underpenetrated secondary cities outside Jakarta offer first-mover positioning for rotary die cutter deployment serving domestic e-commerce growth.
- Extended producer responsibility frameworks:Evolving EU packaging regulations reward material yield optimization, creating specification pull for integrated prepress-to-cutting workflow software.
- Workflow software convergence:Integration of prepress automation with cutting station control enables converters to compress job changeover times and reduce labor dependency.
Industry Challenges
- Skilled press operator scarcity:European print hubs face acute shortages of technicians capable of maintaining conventional die cutting installations, unwinding capacity utilization at established plants.
- Legacy system integration complexity:Retrofitting digital cutting heads onto existing flatbed frames requires proprietary control architecture reconciliation that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Die Cutting Machine Market |
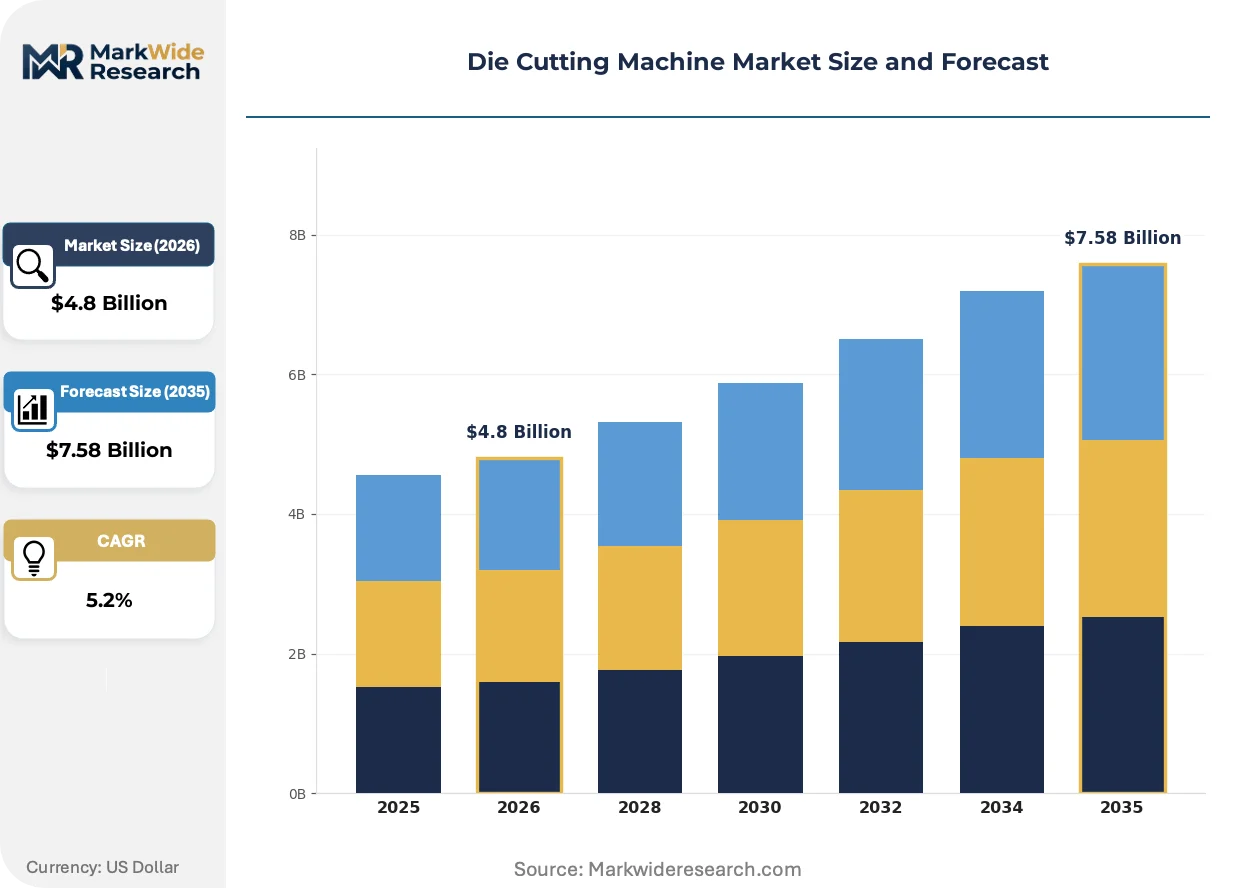
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flatbed Die Cutters, Rotary Die Cutters, Digital Die Cutters, Laser Die Cutters Material: Paper, Cardboard, Plastics, Metal End User: Packaging Industry, Textile Industry, Automotive Sector, Electronics Sector Technology: Mechanical Cutting, Hydraulic Cutting, Pneumatic Cutting, Electric Cutting |
| Companies Covered | Koenig & Bauer AG, Duplo International, MK Masterwork, Winkler+Dünnebier, Sanwa Co., Ltd., Bobst, Komori Corporation, H. Loeb Corp., Heidelberger Druckmaschinen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Die Cutting Machine Market Strategic Shifts
Active reshaping in die cutting equipment centers on three vectors: physical tooling giving ground to directed-energy systems, regulatory frameworks rewriting equipment specifications, and buyer procurement models compressing vendor relationships.
Laser die cutting technology severs sheeted substrates without physical tool fabrication, eliminating steel-rule lead times for prototype and variable-data label workflows. Pharmaceutical label converters in Switzerland and contract packagers in the Netherlands are adopting these systems at accelerating pace. The technology is miniaturizing capital requirements for entry-level digital cutting, enabling smaller converters to compete for short-run pharmaceutical serialization contracts without rotary cylinder investments.
REACH chemical safety regulations and the EU Green Deal's extended producer responsibility framework now govern substrate selection and scrap minimization specifications for packaging equipment sold across Europe. Industrial consequence includes mandatory material yield documentation and traceability systems integrated into cutting station controls. Folding carton converters in Germany and France are responding by specifying flatbed systems with automated nesting software that optimizes substrate utilization prior to cutting cycle initiation.
After-sales service unbundling is disrupting traditional vendor-customer relationships in die cutting equipment procurement. Large packaging groups in Vietnam and Indonesia now separate hardware acquisition from maintenance contracts, sourcing spare parts through third-party channels and independent service technicians. This pattern is most visible among export-oriented corrugated board processors seeking to reduce total cost of ownership across five-year equipment lifecycles.
Die Cutting Machine Market Segmentation
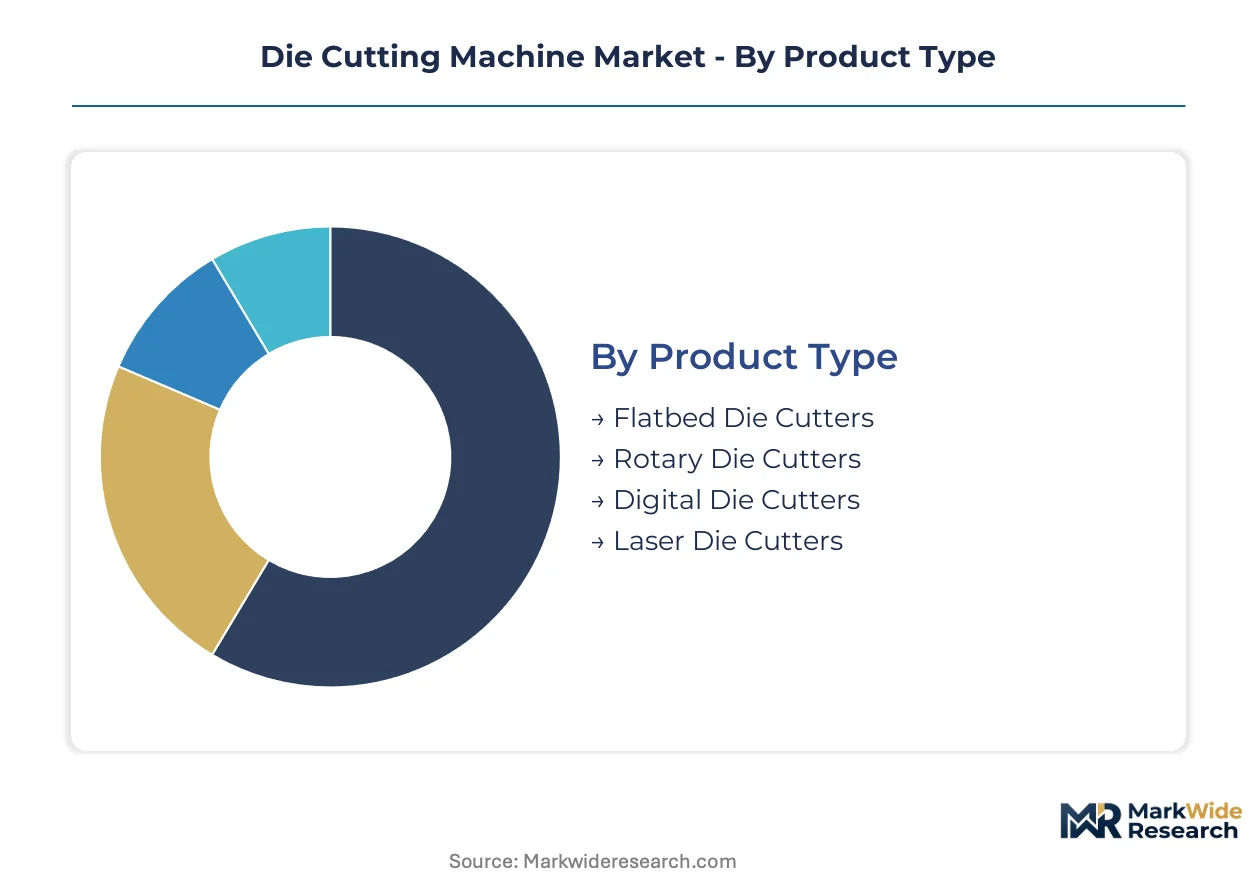
Die cutting equipment specifications diverge sharply across substrate types, regulatory environments, and production volumes. Understanding these segment boundaries enables capital allocation decisions between precision-focused European compliance investments and throughput-oriented Southeast Asian capacity expansion.
Product Type:
CE marking under the EU Machinery Directive imposes divergent electrical safety and emergency stop architecture requirements across mechanical versus directed-energy systems.
- Flatbed Die Cutters:Steel-rule tooling systems apply cutting forces through hardened dies pressed against stationary platens. German and French folding carton converters specify these for short-run flexibility amid EU Green Deal scrap reduction mandates.
- Rotary Die Cutters:Cylinder-based repeatability enables web speeds exceeding 300 meters per minute. Vietnamese and Indonesian packaging exporters favor these for e-commerce corrugated shipping box volume.
- Digital Die Cutters:Knife-based systems eliminate physical die fabrication lead times for prototyping workflows.
- Laser Die Cutters:Directed-energy severing removes tooling costs entirely for variable-data label production.
Established volume favors rotary die cutters; emerging adoption favors laser die cutters.
Material:
REACH chemical safety regulations and extended producer responsibility frameworks in Europe now govern substrate selection specifications.
- Paper:Lightweight, recyclable substrate dominates pharmaceutical and food contact packaging. Swiss label converters specify laser-compatible grades for serialization compliance.
- Cardboard:Corrugated and solid board grades absorb highest cutting tonnage. Indonesian e-commerce fulfillment networks drive demand for crush-resistant flute profiles.
- Plastics:Flexible films and rigid sheets require specialized rule geometries.
- Metal:Thin-gauge aluminum and steel foils demand extreme cutting force capacity.
Cardboard commands installed base dominance; plastics are climbing the fastest on flexible packaging conversion.
End User:
Customer procurement models separate capital-intensive packaging groups from fragmented specialty manufacturers.
- Packaging Industry:Folding carton and corrugated board converters represent the dominant equipment purchaser category. Vietnam and Indonesia absorb greenfield rotary capacity as multinational brands relocate sourcing from China.
- Textile Industry:Fabric pattern cutting requires specialized rule configurations for layered material stacks.
- Automotive Sector:Gasket and interior trim production demands precision tolerances.
- Electronics Sector:Flexible circuit and membrane switch cutting favors laser systems for micron-level accuracy.
Packaging industry concentration sustains vendor service network economics; electronics sector specifications pull technology advancement.
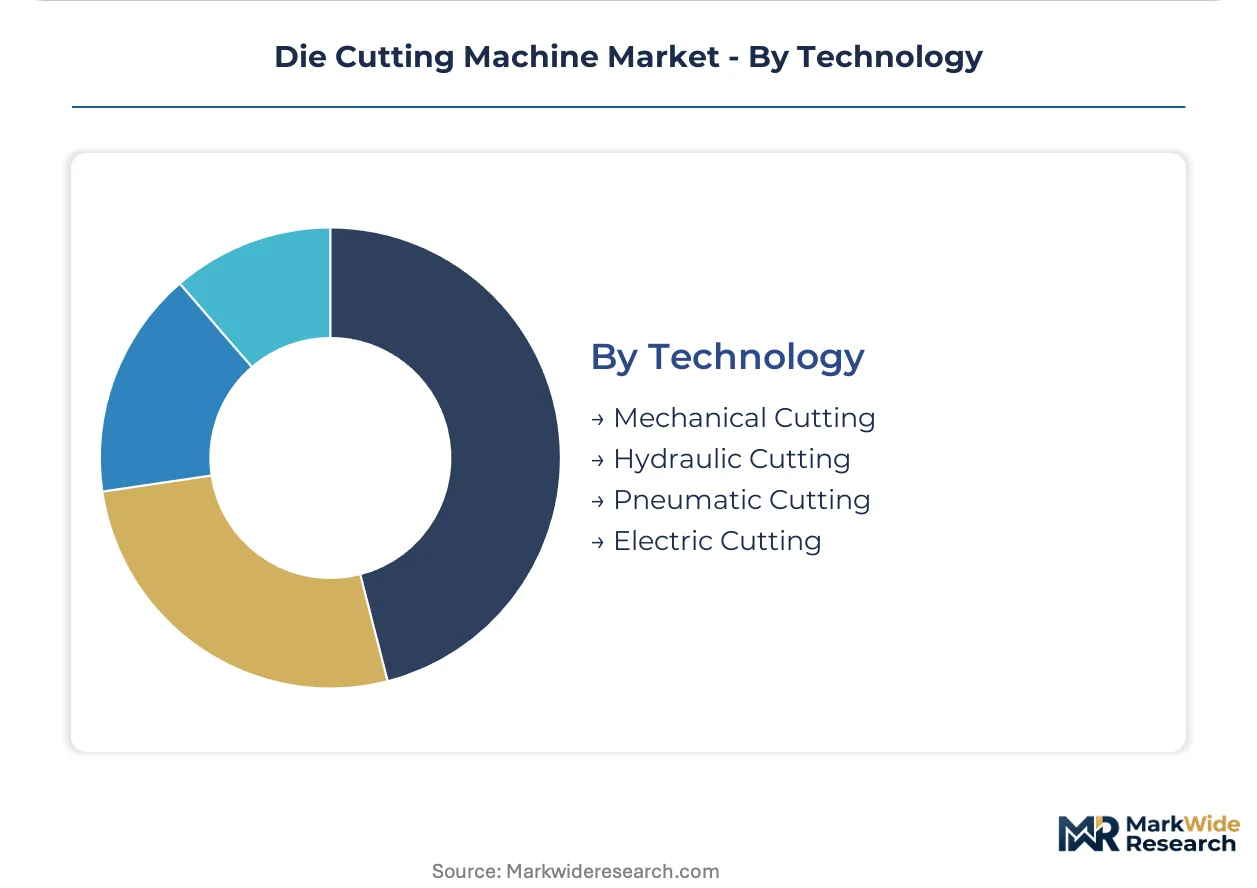
Technology:
Power transmission architectures determine maintenance intervals, energy consumption profiles, and OSHA lockout-tagout compliance pathways.
- Mechanical Cutting:Flywheel and clutch systems deliver high-force impact cutting. European print hubs face skilled operator scarcity for maintaining these conventional installations.
- Hydraulic Cutting:Fluid pressure amplification enables consistent force across material thickness variations. German automotive suppliers specify these for metal forming applications.
- Pneumatic Cutting:Compressed air systems offer rapid cycle rates for lightweight materials.
- Electric Cutting:Servo motor precision reduces energy consumption and noise emissions.
Mechanical cutting retains installed base dominance; electric cutting gains specification share on energy efficiency documentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal packaging waste rules and CE marking requirements under the EU Machinery Directive anchor European die cutting equipment specifications, while Southeast Asian e-commerce fulfillment networks and Indonesian carton sourcing relocations drive capacity expansion elsewhere.
Germany
Folding carton converters in the Rhine-Ruhr and Baden-Württemberg regions specify flatbed systems with automated nesting software to meet EU Green Deal scrap reduction mandates. REACH chemical safety regulations govern substrate selection for pharmaceutical and food contact packaging applications. Stuttgart and Mannheim host precision tooling fabricators supplying hardened steel rules across European print hubs.
United States
OSHA lockout-tagout standards shape guarding and maintenance access design for corrugated board processors serving e-commerce fulfillment networks. Contract packagers in the Midwest and Southeast deploy rotary die cutters for variable-format shipping boxes. Chicago and Atlanta industrial corridors concentrate aftermarket service demand for legacy mechanical cutting installations.
China
GB standards on mechanical safety and NMPA-adjacent industrial equipment certification create compliance pathways for domestic and imported die cutting systems. Yangtze River Delta packaging clusters maintain installed bases of flatbed and rotary equipment despite multinational brand sourcing relocations. Shanghai and Suzhou house specialty steel mills supplying tooling fabrication inputs.
Vietnam
E-commerce logistics hubs around Ho Chi Minh City and Hanoi require high-speed rotary die cutters processing corrugated shipping boxes at web speeds exceeding 300 meters per minute. Government industrial zone incentives attract greenfield packaging capacity as multinational brands relocate folding carton procurement from China. Binh Duong and Dong Nai provinces concentrate export-oriented converter investments.
Indonesia
Domestic e-commerce growth drives rotary die cutter deployment in underpenetrated secondary cities outside Jakarta. Ministry of Industry programs support packaging sector expansion to capture relocated sourcing from multinational consumer brands. Surabaya and Bandung emerging as secondary packaging corridors with first-mover positioning for equipment vendors.
Die Cutting Machine Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the die cutting equipment sector. European specialists dominate precision flatbed and integrated workflow software segments, while Asian fabricators anchor high-volume rotary supply. Three archetypes structure competitive positioning: precision-engineering houses with dense service networks, scale-oriented manufacturers serving export markets, and digital cutting specialists displacing conventional steel-rule systems. M&A activity concentrates workflow software capabilities, while capacity expansion targets Vietnamese and Indonesian industrial zones.
Among European precision-engineering houses, Bobst and Heidelberger Druckmaschinen AG occupy positions exemplifying integrated prepress-to-cutting workflow specialization. MK Masterwork represents the scale-oriented archetype anchoring rotary die cutter supply to Asian packaging exporters. These three entities collectively illustrate how geographic origin and company structure map onto divergent competitive vectors within the sector.
| Leading Market Players |
|---|
| Koenig & Bauer AG |
| Duplo International |
| MK Masterwork |
| Winkler+Dünnebier |
| Sanwa Co., Ltd. |
| Bobst |
| Komori Corporation |
| H. Loeb Corp. |
| Heidelberger Druckmaschinen AG |
| Others |
Value Chain & Pricing Dynamics
Tooling fabrication lead times stretching to 14-18 weeks for hardened steel rules concentrate pricing power with German and Japanese specialty mills, while Southeast Asian packaging converters absorb premium freight costs to secure rotary cylinder deliveries. This inventory pressure feeds back into equipment procurement decisions, pushing buyers toward bundled service contracts that lock in spare parts availability.
Pricing Analysis
Geographic price spreads of 15-25% separate European flatbed systems from Asian rotary equivalents, with CE marking compliance costs and automated nesting software premiums widening the gap. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying as Indonesian and Vietnamese buyers unbundle maintenance contracts. Export-oriented corrugated processors in Binh Duong province exhibit highest price sensitivity; Swiss pharmaceutical label converters show lowest.
Supply Chain Analysis
Inventory cycles of 90-120 days for hardened steel rules expose converters to input cost volatility when German and Japanese mill capacity tightens. Supply concentrates in Germany, Japan, and China for specialty steel inputs, with Yangtze River Delta fabricators feeding Asian equipment assembly. Distribution runs through OEM-direct channels in Europe and independent distributors in Southeast Asia. Single-source vulnerability in rule steel alloys remains the dominant structural risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
After-sales service revenue is expanding faster than hardware sales as Vietnamese and Indonesian packaging groups unbundle maintenance contracts, creating attach-rate expansion opportunities for vendors with dense technician networks.
For Market Incumbents: Shield installed base margins by deepening captive supply of hardened steel rules through backward integration into German or Japanese mill partnerships. Laser die cutting substitution threatens conventional flatbed volume; preempt defection by embedding workflow software that compresses job changeover times below digital system thresholds. For New Entrants and Emerging Players: Aftermarket parts availability gaps in Indonesia's secondary cities offer first-mover positioning for independent service technicians with rotary cylinder refurbishment capability. Target Surabaya and Bandung corridors with spare parts consignment models that bypass OEM-direct channels. Lead with total cost of ownership guarantees rather than capital equipment discounts. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across digital die cutting sub-segments as laser system miniaturization reduces entry thresholds. Five-to-ten year viability favors workflow software specialists with prepress-to-cutting integration capability. Monitor CE marking compliance timelines for Asian equipment manufacturers as signal for European market entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tooling Steel | German mill partnerships secure rule supply against Japanese competitor allocation. |
| Workflow Software Acquisition | Prepress-to-cutting integration compresses changeover times for EU Green Deal compliance. |
| Indonesian Service Network Expansion | Surabaya and Bandung corridors capture unbundled maintenance contract demand. |
| Laser System Miniaturization | Reduced capital thresholds enable entry-level competition for pharmaceutical serialization. |
| CE Marking Fast-Track Certification | Accelerated EU Machinery Directive compliance unlocks European flatbed replacement cycles. |
Study Parameters
Initial hypotheses were tested against primary input from maintenance directors at folding carton plants, aftermarket service heads at OEMs, and procurement leads at Vietnamese packaging exporters, then refined against secondary validation from SEC filings of listed equipment manufacturers, EU Machinery Directive certification databases, and Indonesian Ministry of Industry investment reports. Bottom-up equipment shipment tallies triangulated against top-down packaging capacity expansion announcements.
Variance decomposition across product type, material substrate, end-user industry, and power transmission architecture shaped the analytical framework over the projection horizon. CAGRs derived from segmented growth rate reconciliation with macro packaging investment indicators. Forecast inputs incorporated EU Green Deal scrap reduction mandate timelines and e-commerce fulfillment network expansion trajectories in Southeast Asia.
Underlying assumptions cover sustained multinational brand sourcing relocation from China, with deviation risk concentrated in hardened steel rule supply disruptions or accelerated digital cutting substitution. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Automatic Thermoforming Vacuum Machine Market
Packaging Machinery
Tubular Form Fill and Seal Machines Market
Packaging Machinery
Shrink Label Machine Market
Packaging Machinery
Induction Sealing Machine Market
Packaging Machinery
Flow Wrapper Market
Packaging Machinery
Cutter-Box Packaging Market
Packaging Machinery
Food Powder Packaging Machine Market
Packaging Machinery
Kraft Paper Machines Market
Packaging Machinery
Wicketed Bagging Machines Market
Packaging Machinery
Envelope Sealing Machines Market
Packaging Machinery
Plastic Extruding Equipment Market
Packaging Machinery
Banding Machine Market
Packaging Machinery
Volumetric Boom Filling Machine Market
Packaging Machinery
Orbital Wrapping Machine Market
Packaging Machinery
Global Form Fill Seal Machines Market
Packaging Machinery
Deblistering Machines Market