
 Food Contact Paper and Board Market | 2026-2036
Food Contact Paper and Board Market Size, Share, and Industry Trends Forecast 2026-2036
Food Contact Paper and Board Market Intelligence
Specialized barrier-coating chemists and pulp-process engineers is bifurcating the competitive landscape into technology-led and commodity-led tiers. Mondi Group leverages its integrated kraft pulp and paperboard assets across Central Europe to control raw material flows for greaseproof grades. International Paper sustains manufacturing scale across the southeastern United States, anchoring supply for quick-service restaurant chains. Huhtamaki competes through molded fiber and barrier-coated specialty positions in emerging Asian packaging markets.
Food contact paper and board encompasses cellulose-based substrates engineered with controlled porosity, wet strength, and barrier properties—typically specified by basis weight, Cobb value, and grease resistance (Kit number)—manufactured to prevent migration of contaminants while preserving food quality during storage, transport, and preparation. Coated board and greaseproof paper dominate margin pools in premium chilled and frozen food segments where moisture and oxygen barriers command pricing premiums. Unbleached kraft paper and biodegradable material grades are expanding fastest in European retail and catering channels where compostability certifications determine procurement eligibility.
The FDA governs food contact substance notifications under 21 CFR, while the EU enforces Framework Regulation (EC) No 1935/2004 and the Single-Use Plastics Directive to restrict non-recyclable food service items. China's NMPA and GB standards for food-contact materials impose additional testing protocols on imported coated boards. Stakeholders must monitor evolving state-level extended producer responsibility laws in the United States and emerging restrictions on per- and polyfluoroalkyl substances in European barrier coatings to anticipate reformulation cycles and certification investments.
Market Dynamics
The EU's Single-Use Plastics Directive and cascading state-level plastic bans across the United States are forcing a wholesale substrate migration from polymer-based food service items to barrier-coated paper and molded fiber alternatives.
Growth Catalysts
- Regulatory Mandates:The EU Single-Use Plastics Directive and FDA food contact notification requirements are eliminating competing plastic formats from quick-service restaurant supply chains.
- Quick-Service Procurement:Major quick-service restaurant chains in North America and Europe are expanding paper-based packaging procurement as plastic bans tighten across jurisdictions.
- German Retail Concentration:Centralized food retail chains in Germany, combined with stringent packaging waste regulations, are creating concentrated demand pull-through for certified sustainable board grades.
Market Restraints
- Pulp Input Volatility:Kraft pulp prices fluctuate with energy costs and softwood supply cycles, compressing margin stability for unbleached kraft paper producers.
- Barrier Coating Chemistry Constraints:Per- and polyfluoroalkyl substance restrictions under REACH and emerging state-level US prohibitions are forcing costly reformulation cycles for greaseproof grades.
- Competing Substrate Threat:Rigid molded fiber and biopolymer alternatives are capturing share in premium chilled segments where moisture barrier specifications exceed paper capabilities.
Strategic Opportunities
- Asian Emerging Markets:Quick-service restaurant expansion in India and Southeast Asia presents white space for barrier-coated specialty board as plastic restrictions propagate.
- Compostability Certification:European compostability certifications are determining procurement eligibility in retail and catering channels, creating premium positioning for certified biodegradable grades.
- Barrier Technology Convergence:Integration of bio-based coatings with controlled porosity engineering is opening oxygen-sensitive frozen food applications previously reserved for plastic laminates.
Industry Challenges
- Specialized Talent Scarcity:Barrier-coating chemists and pulp-process engineers are bifurcating the competitive landscape, with capability concentration in integrated European mills.
- Extended Certification Timelines:FDA food contact substance notifications and EU compliance testing protocols are extending product launch cycles by twelve to eighteen months.
- Legacy Equipment Retrofit Costs:Converting existing paperboard lines to handle multi-layer barrier coatings requires capital-intensive drying and coating section upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Contact Paper and Board Market |
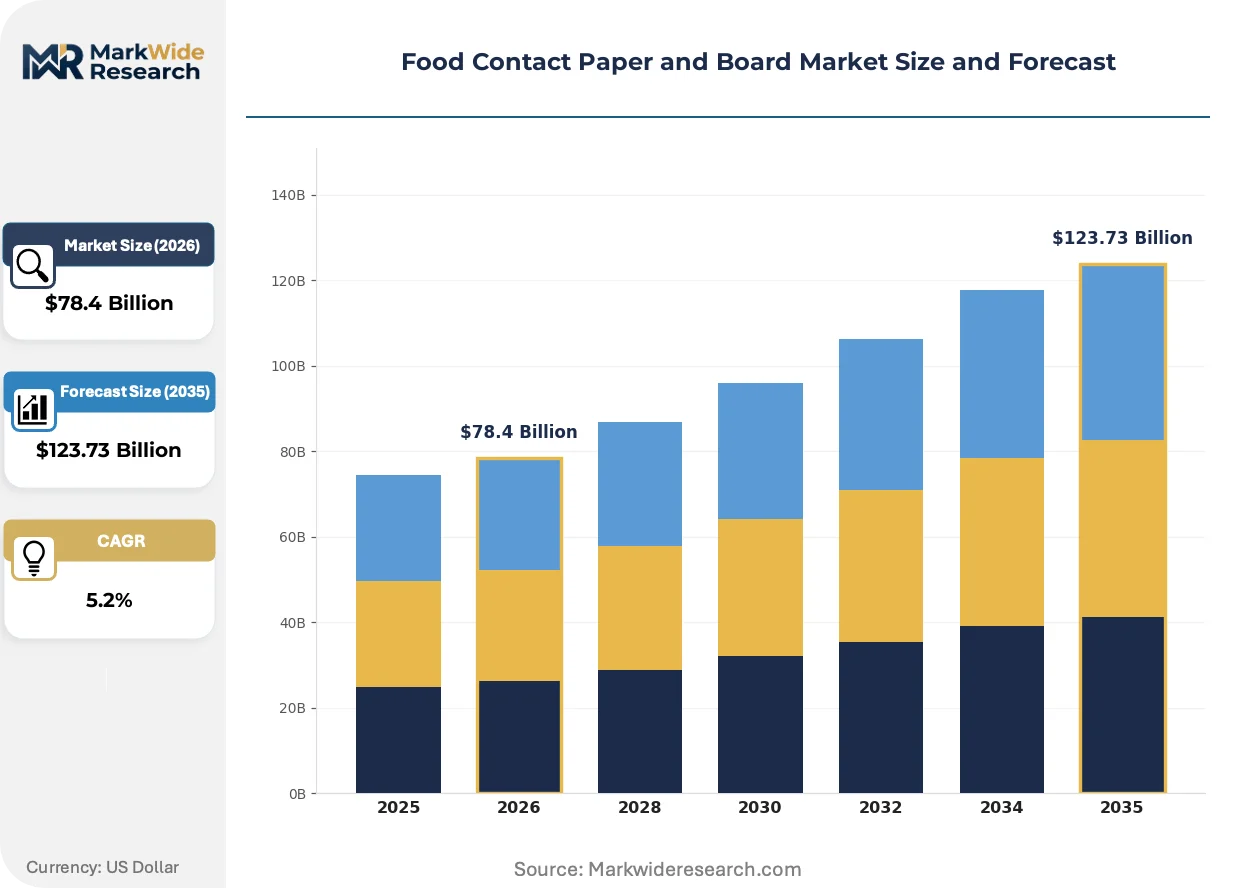
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $123.73 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bleached Paper, Coated Board, Unbleached Paper, Kraft Paper Application: Packaging, Baking, Tableware, Food Wrapping Material: Paperboard, Greaseproof Paper, Coated Paper, Biodegradable Materials End User: Food Manufacturers, Catering Services, Retailers, Food Processors |
| Companies Covered | International Paper, Mondi Group, Smurfit Kappa, WestRock, Amcor Plc, Graphic Packaging International, DS Smith, Georgia-Pacific, Huhtamaki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Contact Paper and Board Market Strategic Shifts & Innovations
Barrier coating chemistry and substrate engineering are advancing rapidly as regulatory pressure eliminates legacy plastic formats and end-users demand performance parity in paper-based alternatives.
Water-based bio-barrier coatings incorporating plant-derived waxes and polysaccharides are displacing conventional polyethylene extrusion in frozen food cartons and chilled ready-meal trays. Quick-service chains with net-zero commitments are adopting these grades at accelerated procurement cycles. This displacement is compressing the addressable market for fossil-based barrier substrates while expanding margin pools for compliant paperboard.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating long-chain fluorochemicals from greaseproof paper formulations across European manufacturing. Paperboard producers are reformulating with short-chain fluorotelomers and silicone-based alternatives at substantial R&D cost. The chilled and frozen food segment is most affected, with German retailers now requiring full substance disclosure for coated board procurement.
Centralized procurement by quick-service restaurant chains is consolidating supplier relationships around vertically integrated paperboard producers with captive pulp supply. Smaller converters without barrier-coating capabilities are losing direct supply contracts to integrated mills with in-house formulation expertise. This concentration is most visible in the southeastern United States, where restaurant chain headquarters proximity favors regional integrated producers.
Food Contact Paper and Board Market Segmentation
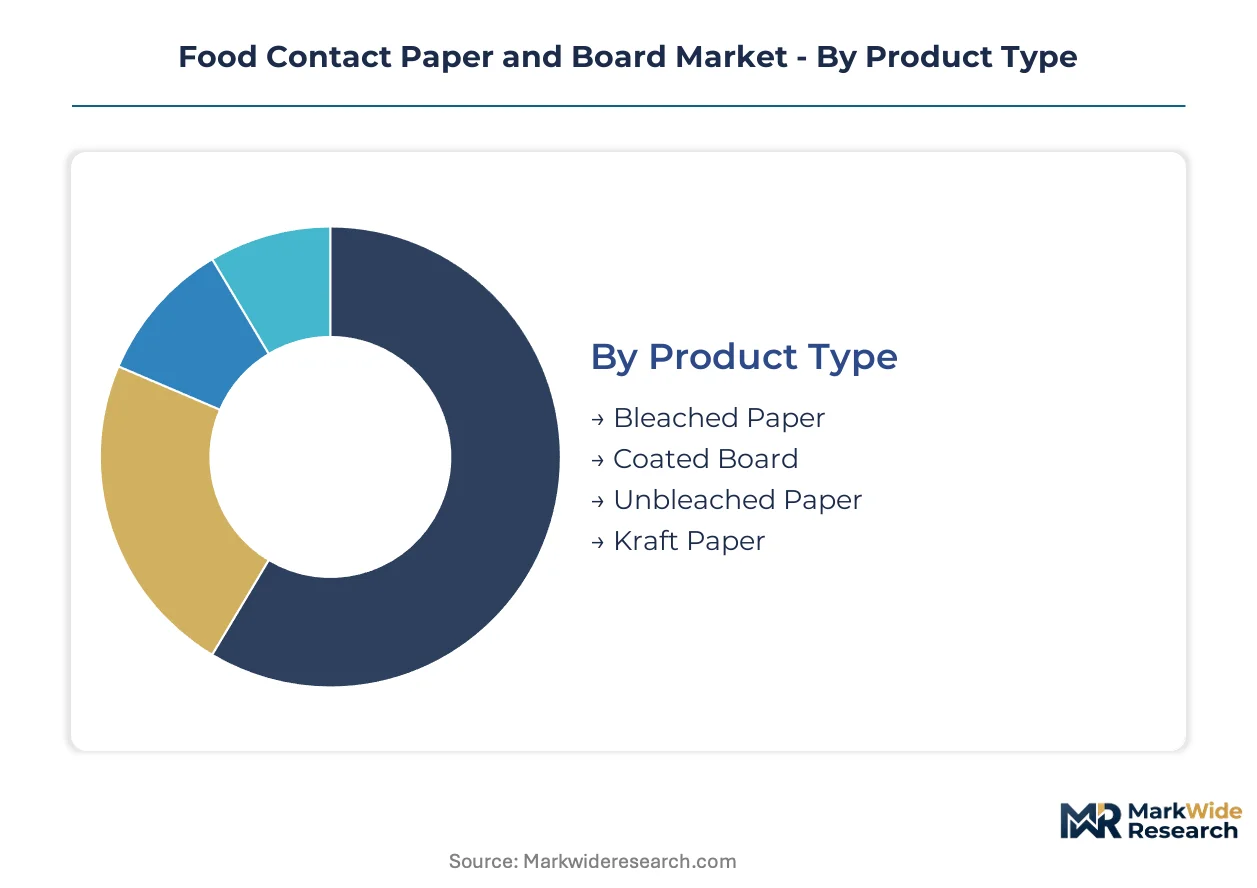
Segmentation in food contact paper and board reveals how substrate specifications, barrier requirements, and end-use durability demands fragment procurement patterns across quick-service chains, retail channels, and industrial food processors. Understanding these divisions exposes where margin pools concentrate and which material grades face substitution pressure from molded fiber or biopolymer alternatives.
Product Type:
Domestic production of unbleached grades dominates North American and European supply chains, while bleached and coated specialties flow through export-oriented mills serving Asian quick-service expansion.
- Coated Board:Multi-layer paperboard substrates engineered with extruded polyethylene or bio-based barrier coatings to control moisture vapor transmission and oxygen ingress. Quick-service restaurant chains in Germany and the United States specify these grades for chilled ready-meal trays and frozen food cartons where shelf-life extension commands procurement premiums. FDA food contact substance notifications and EU Framework Regulation compliance requirements extend qualification timelines, concentrating supply relationships around vertically integrated producers with captive coating formulation expertise.
- Unbleached Paper:Natural kraft fibers retaining lignin content for structural rigidity in dry food applications and outer packaging layers. Demand clusters in French and Italian retail channels where compostability certifications and reduced chemical processing align with extended producer responsibility mandates. Pulp input volatility from energy cost fluctuations compresses margin stability for independent converters lacking backward integration into kraft pulp supply.
- Bleached Paper:Chlorine-free or elemental chlorine-free treated cellulose substrates specified for direct food contact in premium bakery and confectionery wrapping. Japanese and South Korean food manufacturers favor these grades for visual cleanliness and print receptivity in branded consumer packaging.
- Kraft Paper:High-tensile strength unbleached grades specified for grocery sacks, quick-service carryout bags, and industrial food ingredient packaging. Brazilian and Indonesian pulp integration supports cost-competitive export supply to emerging market retail chains.
Coated board commands the established base. The steepest expansion runs through unbleached paper.
Application:
Volume concentration follows temperature-controlled supply chain requirements, with frozen and chilled applications demanding barrier performance that packaging alone cannot satisfy without coating engineering.
- Packaging:Primary and secondary containment for retail food products including folding cartons, corrugated cases, and rigid paperboard trays. German centralized retail chains and North American quick-service procurement departments specify certified sustainable grades with full substance disclosure under REACH and emerging state-level PFAS restrictions.
- Food Wrapping:Direct-contact sheets and rolls for deli meats, baked goods, and prepared foods requiring grease resistance and moisture control. REACH restrictions on long-chain fluorochemicals are forcing reformulation with short-chain fluorotelomers or silicone alternatives across European manufacturing.
- Baking:Oven-safe parchment and release papers specified for industrial bakeries and foodservice operations. Heat resistance requirements limit substitution by uncoated grades, preserving specialized silicone-treated supply relationships.
- Tableware:Plates, bowls, and serviceware molded from fiber or cut from board stock for single-use foodservice applications. EU Single-Use Plastics Directive implementation is accelerating displacement of polymer-based alternatives in French and Italian catering channels.
Packaging absorbs the dominant volume share. Food wrapping is climbing the fastest as quick-service chains eliminate plastic films.
Material:
Cost tier stratification separates commodity paperboard from engineered barrier grades, with biodegradable certifications creating premium positioning in European procurement.
- Paperboard:Rigid cellulose-based substrates spanning solid bleached sulfate, folding boxboard, and white-lined chipboard grades. North American quick-service restaurant headquarters proximity to southeastern United States integrated mills anchors regional supply concentration.
- Greaseproof Paper:Dense, low-porosity sheets engineered through mechanical refining or chemical treatment to resist oil and fat penetration. Chilled and frozen food segments in Germany require full PFAS substance disclosure, forcing costly reformulation cycles.
- Coated Paper:Surface-treated grades with clay, polymer, or bio-based barrier layers for print quality and functional performance. Water-based bio-barrier coatings incorporating plant-derived waxes are displacing polyethylene extrusion in net-zero committed quick-service procurement.
- Biodegradable Materials:Certified compostable substrates meeting EN 13432 or ASTM D6400 standards for industrial composting infrastructure. European retail and catering channels now mandate these certifications for procurement eligibility, creating margin premiums over conventional grades.
Paperboard retains the volume foundation. Biodegradable materials are gaining share fastest on certification mandates.
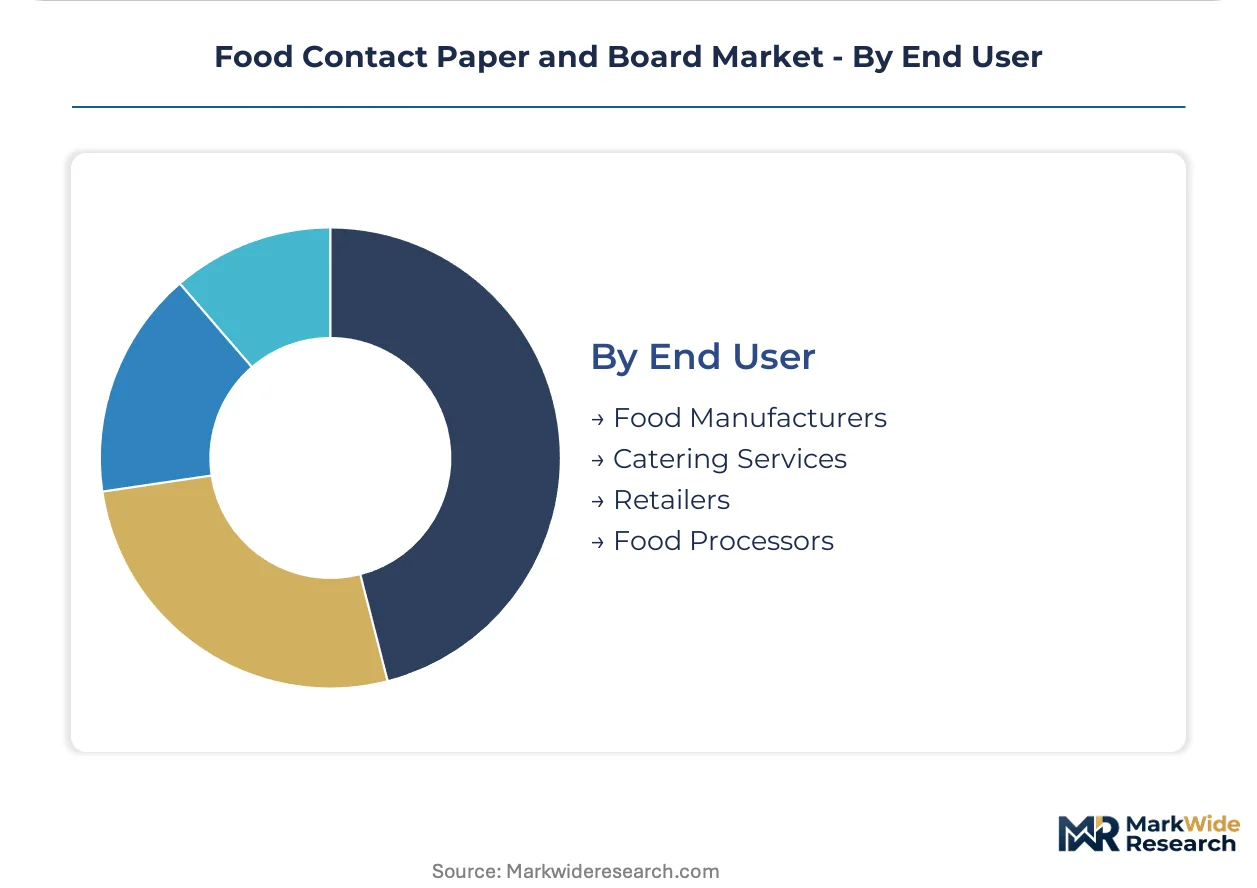
End User:
Customer scale determines specification complexity, with multinational food manufacturers driving standardization while regional catering operators prioritize cost and local certification compliance.
- Food Manufacturers:Industrial processors of packaged consumer goods requiring validated barrier performance for shelf-stable, refrigerated, and frozen product lines. FDA food contact notifications and EU compliance testing protocols extend product launch cycles, favoring established supplier relationships with regulatory documentation libraries.
- Retailers:Centralized food retail chains in Germany and France specifying private-label packaging with compostability certifications and extended producer responsibility compliance. Procurement concentration creates pull-through demand for certified sustainable board grades.
- Catering Services:Foodservice operators supplying events, institutions, and corporate dining with single-use tableware and wrapping. EU Single-Use Plastics Directive enforcement is accelerating substrate migration to molded fiber and barrier-coated paper alternatives.
- Food Processors:Intermediate handlers of raw and semi-processed ingredients requiring industrial packaging for bulk transport and storage. Unbleached kraft grades dominate this segment on cost and structural performance specifications.
Food manufacturers anchor the demand base. Retailers are expanding most quickly on sustainability procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA food contact substance notifications anchor United States regulatory frameworks, while EU Framework Regulation enforcement and REACH chemical restrictions dominate European procurement standards. Quick-service restaurant chain headquarters proximity and centralized retail concentration drive geographic demand clustering.
United States
Quick-service restaurant chains headquartered in Georgia and Tennessee are expanding paper-based packaging procurement as state-level plastic bans propagate across California, New York, and Washington. FDA 21 CFR notification requirements extend product qualification timelines, favoring established suppliers with regulatory documentation libraries. Southeastern integrated mills near Atlanta and Charlotte anchor supply relationships through backward integration into kraft pulp production.
Germany
Centralized food retail chains including REWE and EDEKA are mandating certified sustainable board grades with full substance disclosure under REACH and emerging PFAS restrictions. The EU Single-Use Plastics Directive implementation accelerates displacement of polymer-based food service items in Bavarian and North Rhine-Westphalian catering channels. Düsseldorf and Hamburg packaging clusters concentrate barrier-coating formulation expertise for chilled ready-meal applications.
China
NMPA and GB standards for food-contact materials impose additional testing protocols on imported coated boards, creating compliance barriers for foreign suppliers. Quick-service restaurant expansion in Shanghai and Beijing metro areas drives demand for barrier-coated specialty grades as municipal plastic restrictions tighten. Yangtze River Delta paperboard producers are capturing domestic quick-service procurement through localized coating capabilities.
France
Extended producer responsibility mandates and compostability certification requirements under EN 13432 are determining procurement eligibility in Parisian retail and catering channels. ANSM and CNIL oversight of food contact materials adds regulatory complexity for coated board importers. Lyon and Marseille foodservice operators are accelerating substrate migration to molded fiber and barrier-coated paper alternatives ahead of EU directive deadlines.
India
FSSAI food safety standards and emerging state-level plastic bans in Maharashtra and Karnataka are creating regulatory pull-through for compliant paperboard grades. Quick-service restaurant expansion in Mumbai and Bangalore metro areas presents white space for barrier-coated specialty board as plastic restrictions propagate. Domestic paperboard producers in Gujarat and Tamil Nadu are investing in coating capabilities to capture quick-service procurement growth.
Food Contact Paper and Board Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the food contact paper and board market. Mondi Group, International Paper, and Georgia-Pacific control captive pulp supply and in-house barrier-coating formulation, while regional converters compete on cost without backward integration. The competitive landscape fragments across three archetypes: vertically integrated multinational producers, specialized barrier-coating formulators, and regional commodity converters. Dominant competitive moves include capacity expansion in Southeast Asian quick-service corridors and strategic partnerships with bio-based coating technology developers.
Within the integrated multinational tier, Mondi Group and International Paper exemplify scale-driven positioning through Central European and southeastern United States manufacturing footprints. Huhtamaki occupies a specialist position in molded fiber and barrier-coated applications for emerging Asian packaging markets. These three companies represent the capability concentration that smaller converters confront as quick-service procurement consolidates around suppliers with regulatory documentation libraries and captive raw material supply.
| Leading Market Players |
|---|
| International Paper |
| Mondi Group |
| Smurfit Kappa |
| WestRock |
| Amcor Plc |
| Graphic Packaging International |
| DS Smith |
| Georgia-Pacific |
| Huhtamaki |
| Others |
Cost & Logistics Intelligence
Eighteen-month FDA food contact substance notification timelines concentrate pricing power among vertically integrated mills with established regulatory documentation libraries, while spot-market kraft pulp volatility compresses margins for independent converters lacking upstream pulp control.
Pricing Analysis
Geographic price spreads between German certified sustainable board and Southeast Asian commodity grades reflect certification tier and barrier-coating complexity. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant coated board from unbleached kraft and basic greaseproof grades. Price differentiation centers on PFAS-free certification status and captive pulp supply. Cost compression in commodity unbleached grades is intensifying because Brazilian and Indonesian pulp integration enables export price undercutting. Quick-service restaurant procurement departments show lowest price sensitivity; regional catering operators exhibit highest.
Supply Chain Analysis
Brazil and Indonesia anchor cost-competitive kraft pulp supply for export-oriented unbleached paper production, while Germany and the United States concentrate barrier-coating formulation expertise for premium coated board grades. Raw material flows draw from softwood pulp, bio-based wax emulsions, and silicone-based greaseproof treatments. Supply chain risk rests on single-source vulnerability for specialized fluorotelomer alternatives as REACH restrictions eliminate long-chain fluorochemicals. Distribution runs through centralized quick-service restaurant procurement hubs and German retail chain headquarters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across FDA, REACH, and emerging state-level PFAS restrictions is creating specialized formulation niches that favor targeted entrants over broad-based commodity producers.
For Market Incumbents: Shield margin pools in barrier-coated board by securing captive bio-based coating supply agreements before raw material constraints tighten. Deepen upstream control over kraft pulp through long-term offtake contracts with Brazilian and Indonesian producers. Invest in short-chain fluorotelomer reformulation capabilities ahead of cascading European PFAS prohibitions. For New Entrants and Emerging Players: EN 13432 compostability certification fast-tracks procurement eligibility in French and German retail channels where mandatory certification gates block commodity competition. White space concentrates in Indian quick-service restaurant expansion corridors where FSSAI compliance creates first-mover positioning. Target barrier-coated specialty board for chilled ready-meal applications through partnerships with Yangtze River Delta coating specialists. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because escalating chemical disclosure mandates and extended producer responsibility laws compound competitive moats for documented supply chains. Acquisition focus centers on mid-cap European mills with integrated coating formulation and established FDA notification libraries. Monitor PFAS restriction propagation across US state legislatures as inflection signal for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Coating Supply | Captive wax emulsion production insulates margin pools from agricultural commodity swings. |
| REACH-Compliant Reformulation Program | Short-chain fluorotelomer transition preserves German retail access as PFAS disclosure tightens. |
| Quick-Service Restaurant Co-Development Partnership | Net-zero committed chains accelerate procurement cycles for water-based bio-barrier grades. |
| Indian Coating Capability Expansion | Localized production captures Mumbai and Bangalore quick-service growth under FSSAI standards. |
| Compostability Certification Pre-Positioning | EN 13432 documentation unlocks Parisian retail procurement gates ahead of competitor qualification. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with barrier-coating chemists, quick-service restaurant procurement directors, pulp mill operations managers, and EU regulatory affairs specialists; and secondary validation through FDA food contact substance notification databases, ECHA REACH restriction proposals, customs trade flows for kraft pulp grades, and SEC filings from integrated paperboard producers. Bottom-up volume modeling triangulated against top-down spending estimates from centralized retail chain packaging budgets.
Across the analysis window, projections incorporate substrate migration rates from polymer-based food service items, segmented by coating chemistry tier, end-use temperature requirement, and regional regulatory enforcement intensity. CAGRs derive from regression analysis of historical pulp price elasticity and quick-service restaurant unit expansion patterns. Key inputs include kraft pulp futures curves, EU Single-Use Plastics Directive implementation timelines, and certified compostable packaging adoption rates in German retail.
Underlying assumptions cover sustained regulatory enforcement of PFAS restrictions and quick-service procurement commitment to net-zero packaging, with deviation risk concentrated in pulp price volatility and bio-barrier coating performance gaps in frozen food applications. Recalibration cycles align with material shifts in REACH substance restriction schedules and FDA food contact notification processing throughput.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paperboard Container Market
Paper & Paperboard Packaging
Australia Corrugated Board Packaging Market
Paper & Paperboard Packaging
Coated Paper Market
Paper & Paperboard Packaging
Global Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Stationery Films Packaging Market
Paper & Paperboard Packaging
United States Paper Packaging Market
Paper & Paperboard Packaging
Global Corrugated Board Packaging Market
Paper & Paperboard Packaging
Plywood Box Market
Paper & Paperboard Packaging
Coated Recycled Boxboard Market
Paper & Paperboard Packaging
Poly Coated Paperboard Market
Paper & Paperboard Packaging
US Corrugated and Folding Boxboard Market
Paper & Paperboard Packaging
Paper Bottles Market
Paper & Paperboard Packaging
GCC Paper Cup Market
Paper & Paperboard Packaging
India Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
United Kingdom (UK) Corrugated Board Packaging Market
Paper & Paperboard Packaging
Transfer Paper Market