
 Cellular Paper Cardboard Market | 2026-2036
Cellular Paper Cardboard Market Size, Share, and Industry Trends Forecast 2026-2036
Cellular Paper Cardboard Market Intelligence
E-commerce fulfillment operations are broadening the addressable base for cellular paper cardboard beyond traditional industrial packaging. WestRock Company leverages its North American containerboard network to supply high-volume fulfillment centers. Mondi Group anchors European demand through specialized kraft honeycomb grades for appliance protection. Smurfit Kappa Group competes across corrugated and fluted formats with integrated recycling infrastructure.
Cellular paper cardboard comprises engineered paper structures with internal void geometries—honeycomb hexagonal cells, fluted sinusoidal arches, or corrugated wave patterns—manufactured through adhesive bonding of linerboard and medium layers to achieve strength-to-weight ratios exceeding solid fiberboard. The material serves primarily as protective dunnage, structural reinforcement, and thermal insulation across transport and construction applications. Honeycomb configurations command premium positioning in automotive dunnage and flat-pack furniture where rigidity per kilogram drives specification. Kraft grades sustain margin pools in food-contact packaging governed by FDA and BfR migration limits. Fluted variants occupy high-volume construction void-forming where compressive strength requirements are moderate.
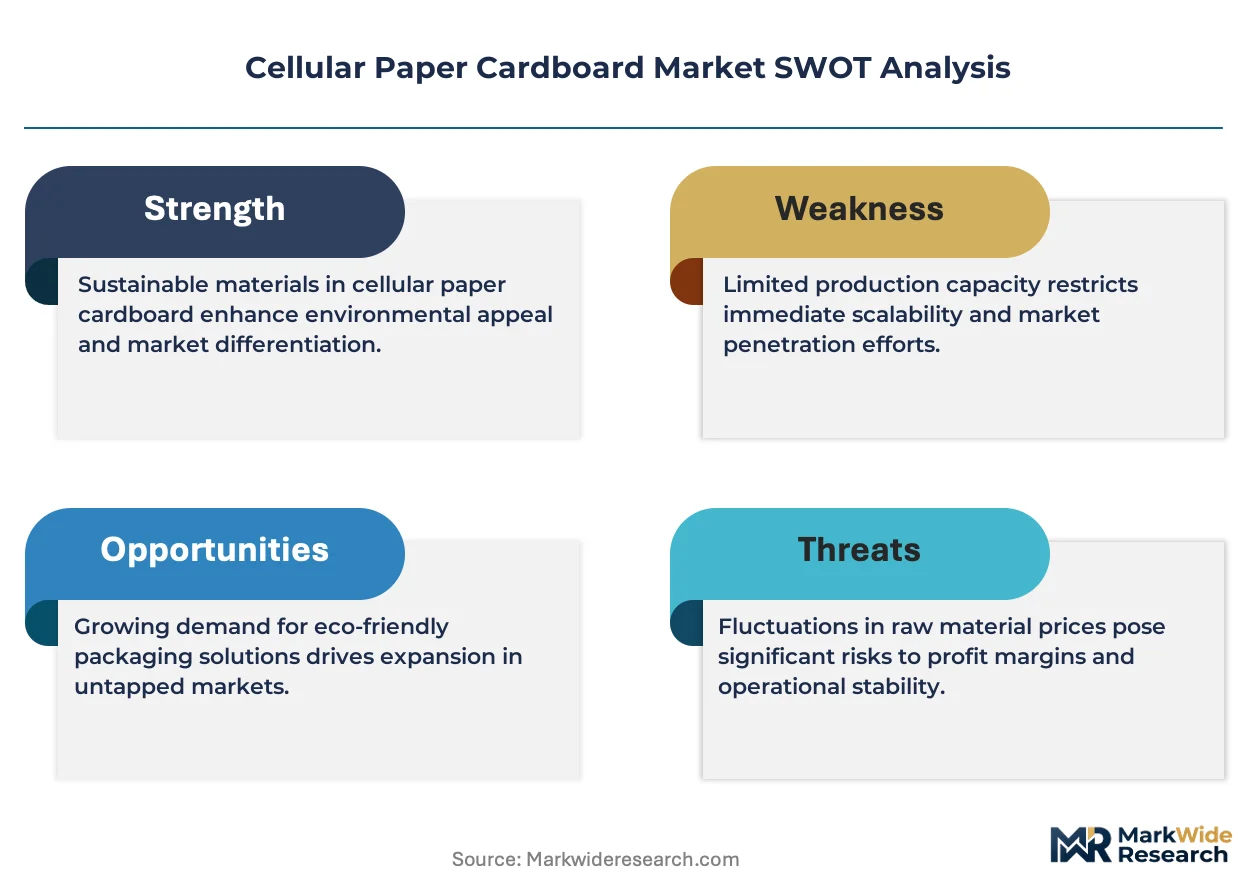
EPA recycled content guidelines, EU Packaging and Packaging Waste Regulation recovery mandates, and FDA food-contact substance notifications collectively shape material certification pathways and market access conditions for cellular paper cardboard producers. REACH restrictions on formaldehyde-based adhesives in European supply chains are forcing reformulation investments among medium producers. Stakeholders must monitor evolving extended producer responsibility fee structures to anticipate margin compression in export-oriented manufacturing footprints.
Market Dynamics
EU Packaging and Packaging Waste Regulation recovery mandates are compressing virgin fiber demand and forcing adhesive reformulation across European supply chains. This regulatory pressure is reshaping competitive positioning toward integrated recycling infrastructure and bio-based bonding chemistry.
Growth Catalysts
- E-commerce fulfillment density:High-volume distribution centers in Germany and the Netherlands are specifying honeycomb dunnage for flat-pack furniture and appliance protection, displacing expanded polystyrene in last-mile packaging.
- REACH adhesive restrictions:Formaldehyde-based resin bans in European medium production are accelerating water-based and starch-adhesive adoption, creating certification premiums for compliant kraft grades.
- Automotive lightweighting protocols:Tier-1 suppliers in Stuttgart and Wolfsburg are qualifying cellular paperboard for interior trim dunnage and battery pack insulation to meet OEM gram-per-kilometer targets.
Market Restraints
- Recovered fiber cost volatility:Old corrugated container prices in European spot markets fluctuate with Chinese import quota shifts, compressing margin pools for integrated producers dependent on external furnish.
- Natural gas process heat:Drying energy intensity in honeycomb expansion lines ties production economics to TTF hub pricing, disadvantaging Central European manufacturing footprints against Nordic biomass-powered competitors.
- Polypropylene honeycomb substitution:Automotive dunnage specifications in high-humidity climates increasingly specify thermoplastic cores for dimensional stability, eroding paperboard share in export-oriented vehicle logistics.
Strategic Opportunities
- CSRD supply chain disclosure:Corporate Sustainability Reporting Directive scope-3 tracking requirements are creating procurement preference for cellular paperboard with mass-balance certified recycled content and blockchain-tracked fiber provenance.
- Cold-chain thermal packaging:Phase-change material integration with fluted paperboard void formers is opening pharmaceutical distribution applications governed by EU GDP guidelines for temperature-sensitive biologics.
- Construction void-forming retrofit:Building energy renovation subsidies in France and Italy are accelerating demand for recyclable floor screed formers in heritage structure upgrades where polystyrene extraction is prohibited.
Industry Challenges
- Adhesive chemist scarcity:Formulation expertise for bio-based bonding systems that meet FDA and BfR migration limits is concentrated among a shrinking cohort of papermaking veterans, constraining European medium plant retrofits.
- Multi-certification timeline compression:Simultaneous pursuit of FSC chain-of-custody, EN 13432 compostability, and specific OEM automotive approvals extends qualification cycles beyond typical capital planning horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellular Paper Cardboard Market |
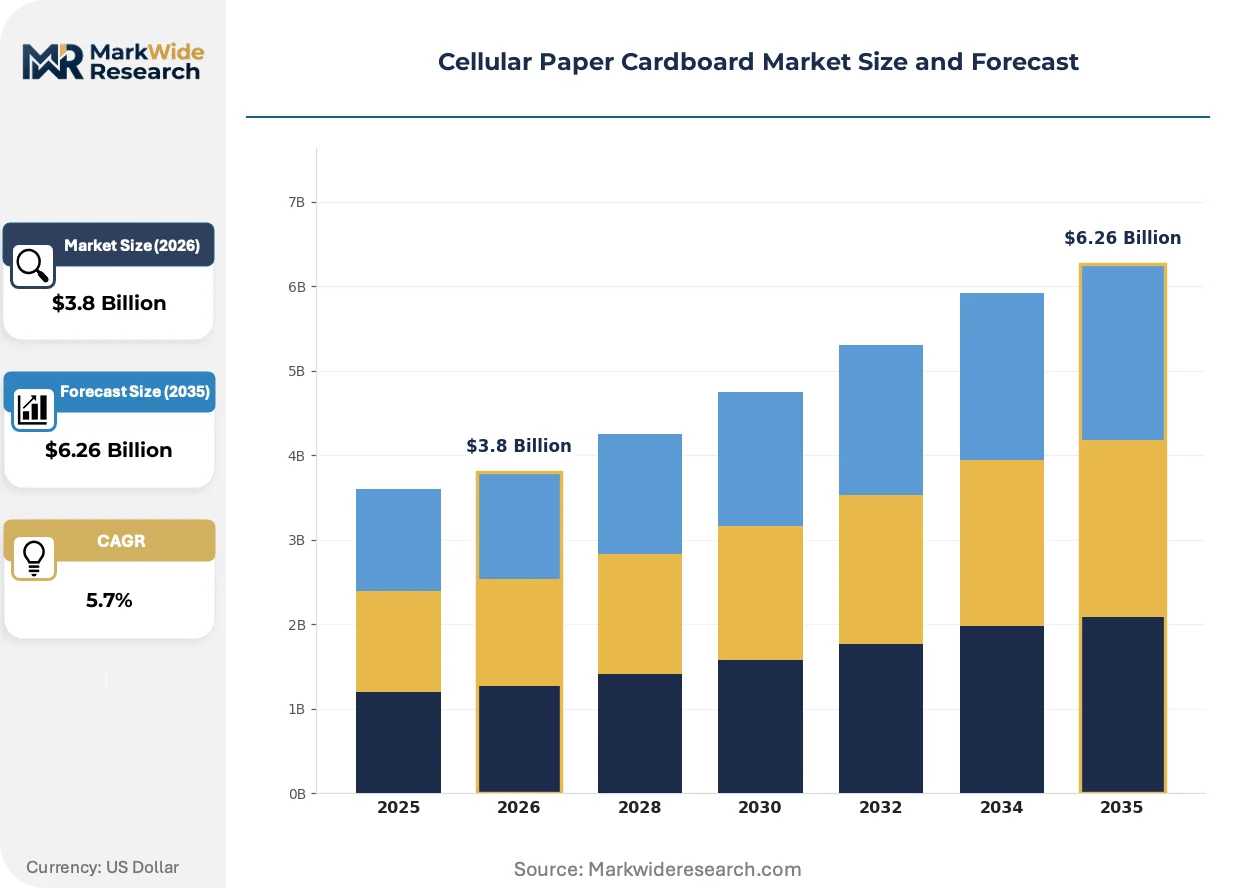
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Honeycomb, Kraft, Fluted, Corrugated Application: Packaging, Construction, Automotive, Stationery End User: Manufacturers, Retailers, Wholesalers, Distributors Distribution Channel: Online, Offline, Direct Sales, Third-party |
| Companies Covered | WestRock Company, Graphic Packaging International Inc, International Paper Company, Oji Holdings Corporation, Packaging Corporation of America, Mondi Group, Smurfit Kappa Group, Rengo Co., Ltd., DS Smith Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellular Paper Cardboard Market Strategic Shifts & Innovations
Dry-molded fiber processing is overtaking wet-forming in protective packaging applications where dimensional precision and surface finish requirements have historically favored plastic alternatives. This equipment transition is reshaping capital deployment patterns across European and North American manufacturing bases.
Water-based barrier coatings with oxygen and grease resistance are overtaking polyethylene extrusion lamination in food-contact honeycomb applications governed by FDA 21 CFR and BfR XXXVI migration limits. Quick-service restaurant chains and meal-kit distributors are qualifying these grades for direct food contact at line speeds matching legacy plastic-lined boards. The structural consequence is overtaking incumbent multi-material structures in circular economy procurement frameworks where mono-material recyclability determines vendor selection.
EU Green Deal carbon border adjustment mechanisms are tightening embodied emissions accounting for imported paperboard products entering the single market. Downstream buyers in automotive and appliance manufacturing are now requiring scope-1 and scope-2 disclosure from cellular paperboard suppliers as a condition of framework agreement renewal. German industrial packaging procurement teams are responding by consolidating supply bases toward domestic and near-shore producers with verified renewable electricity sourcing.
Direct mill-to-fulfillment-center contracting is compressing traditional merchant and converter intermediation in high-volume e-commerce protective packaging. Amazon, Zalando, and Otto Group logistics divisions are establishing specification libraries that bypass regional corrugators for honeycomb and fluted dunnage requirements above threshold volumes. This pattern is most visible in the Rhine-Ruhr corridor and northern Italian distribution clusters where last-mile density supports dedicated production lines.
Cellular Paper Cardboard Market Segmentation
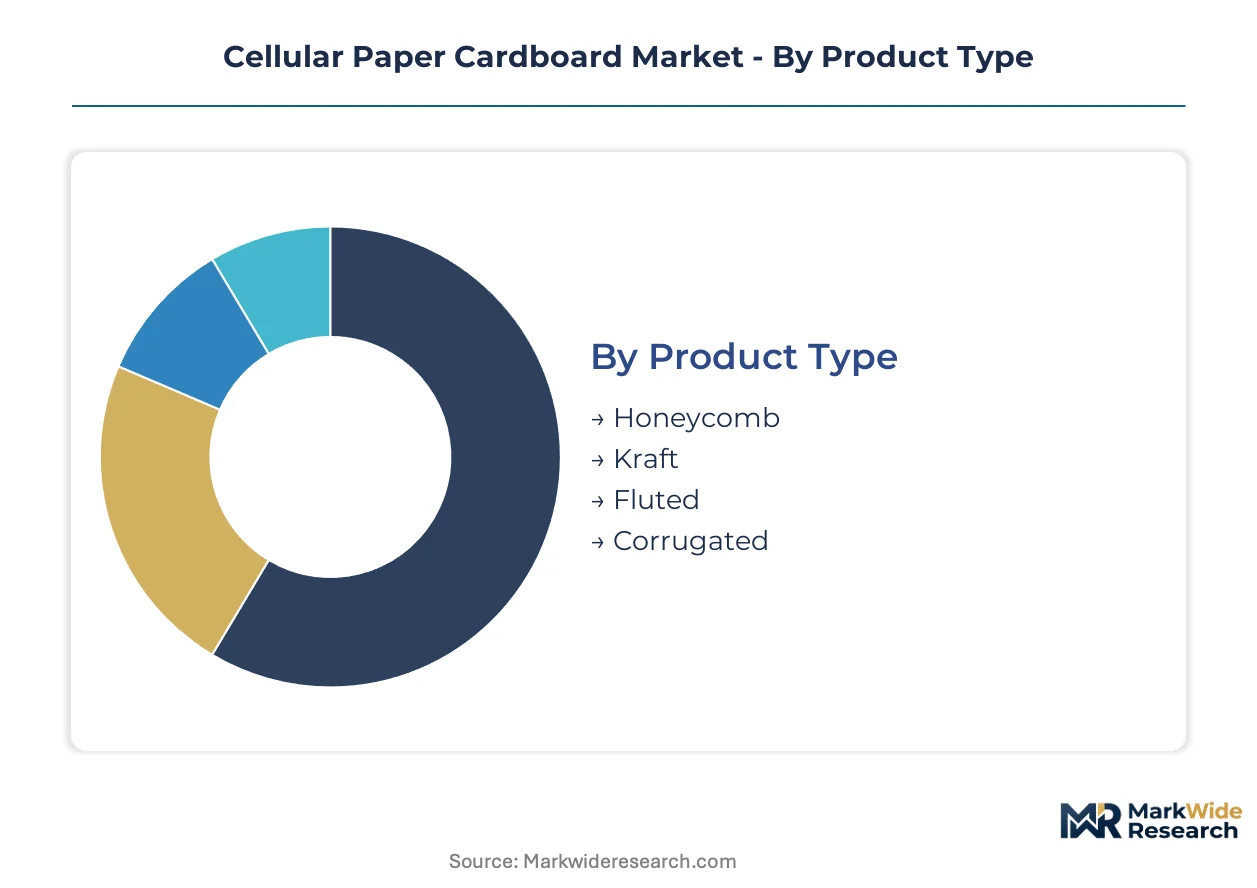
Cellular paper cardboard exhibits divergent performance characteristics across structural geometries and end-use specifications. Technology selection directly determines strength-to-weight ratios, recyclability credentials, and qualification pathways for regulated applications.
Product Type:
Structural geometry governs compressive strength, expansion ratios, and adhesive chemistry requirements.
- Honeycomb:Hexagonal cell structures bonded with water-based adhesives achieve the highest rigidity-to-mass ratios. German automotive suppliers in Stuttgart specify these grades for battery pack dunnage to meet OEM lightweighting protocols.
- Corrugated:Sinusoidal flute profiles laminated between linerboard layers dominate protective packaging volumes. E-commerce fulfillment centers in the Netherlands are displacing expanded polystyrene with B-flute and E-flute dunnage for appliance protection.
- Kraft:Unbleached virgin fiber grades meet FDA and BfR migration limits for direct food contact. Quick-service restaurant chains specify these for hot-fill container applications.
- Fluted:Single-face or double-wall configurations serve construction void-forming where moderate compressive strength suffices. French building renovation subsidies are accelerating demand for recyclable floor screed formers.
Corrugated leads on scale; honeycomb leads on momentum.
Application:
End-use specifications create divergent certification burdens and margin structures.
- Packaging:Protective dunnage for e-commerce fulfillment requires crush resistance and drop-test performance. Amazon and Zalando logistics divisions in the Rhine-Ruhr corridor are establishing direct mill contracts above threshold volumes.
- Construction:Void-forming and thermal insulation applications prioritize compressive strength and moisture resistance. Italian heritage structure upgrades specify recyclable formers where polystyrene extraction is prohibited.
- Automotive:Interior trim dunnage and battery insulation demand gram-per-kilometer weight targets. Tier-1 suppliers in Wolfsburg are qualifying cellular paperboard to meet OEM sustainability scorecards.
- Stationery:Desktop organizers and filing systems occupy lower specification tiers with minimal regulatory burden. Office supply retailers in Germany stock these as standard SKU categories.
Packaging commands volume concentration; automotive shows the steepest expansion trajectory.
End User:
Procurement scale and technical specification authority vary sharply across buyer types.
- Manufacturers:Industrial packaging buyers with in-house specification engineering. Appliance producers in Germany's industrial corridor issue bonded honeycomb requirements for export logistics.
- Retailers:Omnichannel operators with direct control over last-mile packaging decisions. Otto Group consolidates dunnage procurement across fulfillment center networks.
- Wholesalers:Intermediaries with limited technical influence but volume aggregation power. Building material distributors in France bundle fluted void formers with concrete supply contracts.
- Distributors:Merchant converters serving fragmented regional demand. Northern Italian corrugators maintain inventory positions for just-in-time construction deliveries.
Manufacturers anchor value capture; retailers are gaining procurement leverage fastest.
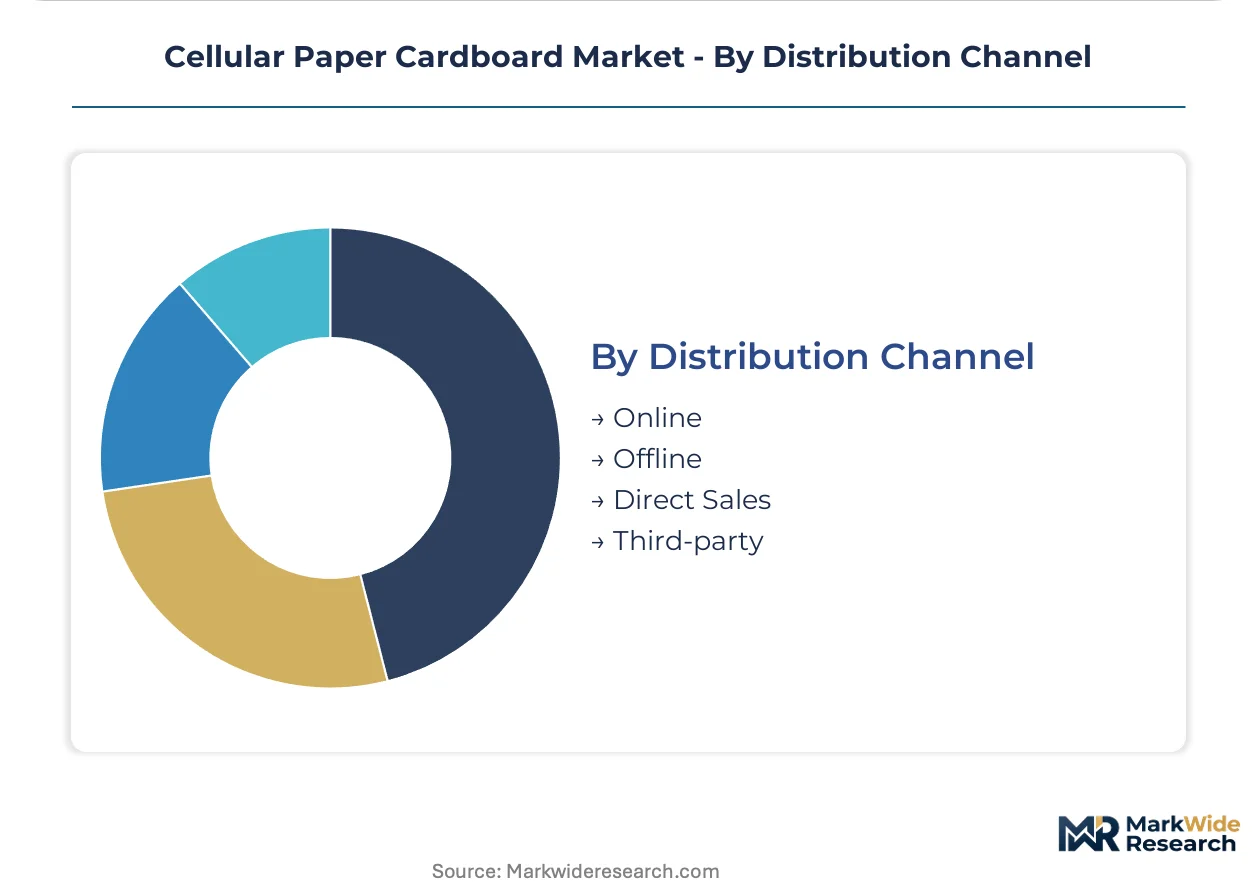
Distribution Channel:
Channel selection determines specification control, margin retention, and customer data access.
- Direct Sales:Mill-to-fulfillment contracting bypasses intermediation for high-volume accounts. WestRock and Mondi operate dedicated account teams for e-commerce platform procurement.
- Offline:Traditional merchant and converter networks serve fragmented regional demand. Smurfit Kappa's integrated recycling infrastructure supports this channel across European markets.
- Online:Digital catalog ordering for standardized grades with minimal customization. Small-format retailers in Germany use these platforms for stationery and light protective packaging.
- Third-party:Logistics service providers specifying dunnage on behalf of shipper clients. Contract packaging operators in the Netherlands manage honeycomb deployment for cross-border appliance distribution.
Direct sales concentrates margin; third-party channels are expanding service scope most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production economics for cellular paper cardboard hinge on adhesive chemistry compliance costs and energy-intensive honeycomb expansion processes. Manufacturers face divergent regulatory burdens across jurisdictions, creating cost-of-compliance arbitrage that reshapes sourcing footprints.
Germany
Automotive lightweighting mandates from Stuttgart OEMs drive honeycomb specification for battery pack dunnage. REACH restrictions on formaldehyde-based adhesives force medium producers toward water-based bonding systems. The Rhine-Ruhr corridor concentrates fulfillment center demand from Amazon and Zalando logistics divisions.
United States
EPA recycled content guidelines compress virgin fiber demand for protective packaging grades. FDA food-contact substance notifications govern kraft honeycomb migration limits for quick-service restaurant chains. WestRock's North American containerboard network supplies high-volume e-commerce fulfillment centers in the Southeast and Midwest.
France
Building energy renovation subsidies accelerate demand for recyclable floor screed formers in heritage structure upgrades. EU Green Deal carbon border adjustment mechanisms tighten embodied emissions accounting for imported paperboard. Construction material distributors in Île-de-France bundle fluted void formers with concrete supply contracts.
China
Dual carbon goals and GB standards for packaging waste recovery reshape medium production economics. NMPA and MEE oversight of adhesive emissions intensifies environmental compliance for honeycomb manufacturers. Yangtze River Delta industrial clusters supply appliance protection grades for export-oriented manufacturing.
Netherlands
High-volume distribution centers specify honeycomb dunnage for flat-pack furniture and appliance protection, displacing expanded polystyrene. CSRD supply chain disclosure requirements create procurement preference for mass-balance certified recycled content. Northern distribution clusters support dedicated production lines for last-mile packaging density.
Cellular Paper Cardboard Market Key Industry Players
Capacity expansion dominates the current landscape as producers retrofit medium plants for bio-based adhesive compliance. The vendor base concentrates among integrated paperboard conglomerates with captive recycling infrastructure and regional specialists serving niche certification tiers. Two strategic archetypes prevail: scale-driven containerboard networks with fulfillment center direct contracts, and technology-focused honeycomb specialists qualifying automotive and pharmaceutical applications. Competitive intensity centers on geographic proximity to demand clusters and simultaneous pursuit of FSC chain-of-custody and OEM automotive approvals.
Among North American integrated producers, WestRock Company and Packaging Corporation of America exemplify scale-driven archetypes with containerboard network leverage. Mondi Group anchors European positioning through specialized kraft grades. These three occupy positions reflecting divergent strategic emphases: direct mill-to-fulfillment contracting versus automotive qualification pathways versus integrated recycling infrastructure control.
| Leading Market Players |
|---|
| WestRock Company |
| Graphic Packaging International Inc |
| International Paper Company |
| Oji Holdings Corporation |
| Packaging Corporation of America |
| Mondi Group |
| Smurfit Kappa Group |
| Rengo Co., Ltd. |
| DS Smith Plc |
| Others |
Cost & Logistics Intelligence
Adhesive formulation expertise concentrated in Germany's papermaking corridor widens pricing-tier spreads between REACH-compliant kraft grades and commodity corrugated. Labor-cost differentials between Nordic biomass-powered producers and Central European natural gas-dependent plants amplify regional price stratification for honeycomb expansion lines.
Pricing Analysis
Distributor margin compression in traditional merchant channels forces direct-to-OEM contracting discounts at volume thresholds above ten thousand metric tons annually. Pricing stratifies across premium honeycomb automotive grades, standard corrugated protective packaging, and economy fluted construction formers based on certification burden and fiber provenance tracking. Cost compression in standard corrugated tiers intensifies because Chinese recovered fiber quota shifts destabilize Old Corrugated Container spot markets. Small-format stationery buyers exhibit highest price sensitivity; automotive Tier-1 suppliers with gram-per-kilometer targets show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Amazon and Zalando logistics divisions, bypassing regional corrugator intermediation. Supply concentrates in Germany, the United States, and China, with Germany anchoring automotive qualification pathways and China supplying appliance protection grades for export manufacturing. Raw material dependencies draw from Nordic softwood pulp, recovered fiber streams, and water-based adhesive chemistries. Single-source vulnerability in bio-based bonding formulation expertise constrains European medium plant retrofits. Distribution runs through integrated containerboard networks, merchant converter channels, and digital catalog platforms for standardized grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Cellular Paper Cardboard Market functions as a stable compounder anchored by e-commerce fulfillment density that sustains protective packaging demand through fulfillment center expansion cycles.
For Market Incumbents: Deploy captive recycling infrastructure control to defend margin pools against recovered fiber cost volatility. Secure FSC chain-of-custody and automotive OEM approvals simultaneously to compress qualification timelines. Backward integration into medium production with water-based adhesive capabilities insulates against REACH reformulation mandates and adhesive chemist scarcity. For New Entrants and Emerging Players: Capture cold-chain thermal packaging white space through phase-change material integration with fluted void formers for pharmaceutical distribution. Target French and Italian construction retrofit subsidies where heritage building regulations prohibit polystyrene extraction. Pursue digital-native go-to-market positioning through online catalog platforms for standardized stationery and light protective packaging grades. For Investors and Strategic Acquirers: Integrated paperboard conglomerates with fulfillment center direct contracts are the most active acquirer in this space, consolidating regional specialists for automotive qualification capabilities. Long-term viability centers on bio-based adhesive formulation expertise and blockchain-tracked fiber provenance systems. Monitor CSRD scope-3 disclosure adoption rates as the inflection signal for procurement preference shifts toward mass-balance certified recycled content.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Medium Production | Captive water-based adhesive capacity insulates against REACH formaldehyde restrictions and ECHA reformulation timelines. |
| Automotive OEM Qualification Pathway | Battery pack dunnage approval from Stuttgart and Wolfsburg Tier-1 suppliers unlocks gram-per-kilometer lightweighting protocols. |
| Fulfillment Center Direct Contracting | Mill-to-Amazon and Zalando agreements bypass merchant intermediation in Rhine-Ruhr and northern Italian clusters. |
| Cold-Chain Thermal Packaging Development | Phase-change material integration with fluted formers opens EU GDP-governed pharmaceutical distribution applications. |
| Blockchain Fiber Provenance Tracking | Mass-balance certification meets CSRD supply chain disclosure requirements for corporate procurement preference. |
Research Approach
Direct dialogue with adhesive formulation chemists, honeycomb production engineers, automotive Tier-1 procurement managers, and e-commerce logistics directors grounded qualitative assessment. Secondary validation drew from EPA recycled content guidelines, EU Packaging and Packaging Waste Regulation recovery mandates, FDA food-contact substance notification databases, and SEC 10-K disclosures from integrated paperboard producers. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Segment-level projections emerged from modeling structural geometry demand splits, end-use certification burden trajectories, and regional regulatory compliance cost differentials. CAGRs derived from curve-fitting historical volume patterns against e-commerce fulfillment center expansion rates and automotive lightweighting protocol adoption. Forecast inputs included Old Corrugated Container price volatility indices, TTF natural gas hub pricing, and REACH adhesive restriction implementation timelines.
Underlying measurement precision varies by segment; honeycomb automotive grades and kraft food-contact tiers carry tighter precision than commodity corrugated construction formers. Forecasts reflect documented assumptions around regulatory enforcement intensity and fiber recovery rate improvements. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Disposable Paper Cups Market
Paper & Paperboard Packaging
Vegetable Parchment Paper Market
Paper & Paperboard Packaging
Cardboard Tubs Market
Paper & Paperboard Packaging
Australia Paper Packaging Market
Paper & Paperboard Packaging
Macerated Paper Padded Mailers Market
Paper & Paperboard Packaging
Paperboard Container Market
Paper & Paperboard Packaging
North America Paper Packaging Market
Paper & Paperboard Packaging
Australia Corrugated Board Packaging Market
Paper & Paperboard Packaging
Coated Recycled Paperboard Market
Paper & Paperboard Packaging
Industrial Paper Sacks Market
Paper & Paperboard Packaging
SCK Paper Market
Paper & Paperboard Packaging
Canada Paper Packaging Market
Paper & Paperboard Packaging
Medical Packaging Paper Market
Paper & Paperboard Packaging
Stationery Films Packaging Market
Paper & Paperboard Packaging
Qatar Paper Packaging Products Market
Paper & Paperboard Packaging
Global Multi Depth Corrugated Boxes Market