
 Boxboard Packaging Market | 2026-2036
Boxboard Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Boxboard Packaging Market Outlook
The EU Green Deal is restructuring procurement criteria for consumer-facing packaging across European retail chains. Mondi Group leverages its integrated pulp-to-board operations to secure long-term supply contracts with multinational food brands. Stora Enso anchors its competitive position through extensive Nordic timber holdings and certified sustainable forestry practices. WestRock Company competes by dominating North American corrugated and boxboard conversion networks.
Boxboard packaging denotes paper-based rigid containers manufactured from layered fiberboard, typically ranging from 200 to 500 grams per square meter in basis weight, engineered to protect, display, and transport consumer goods. Folding boxboard commands the largest share of product-type demand due to its versatility in retail-ready applications and superior printability for brand messaging. Solid bleached board leads in healthcare and personal care end uses where hygiene standards and visual premiumization justify higher material costs. E-commerce shipping represents the fastest-growing application segment as unbleached kraft board gains preference for protective yet recyclable transit packaging.
The European Chemicals Agency enforces REACH compliance for coatings and adhesives used in food-contact boxboard, while the FDA regulates substance migration limits in the United States. China's State Administration for Market Regulation enforces GB standards for recycled fiber content, shaping export qualification requirements for multinational suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks and material traceability mandates to align capital allocation with compliance-driven demand shifts.
Market Dynamics
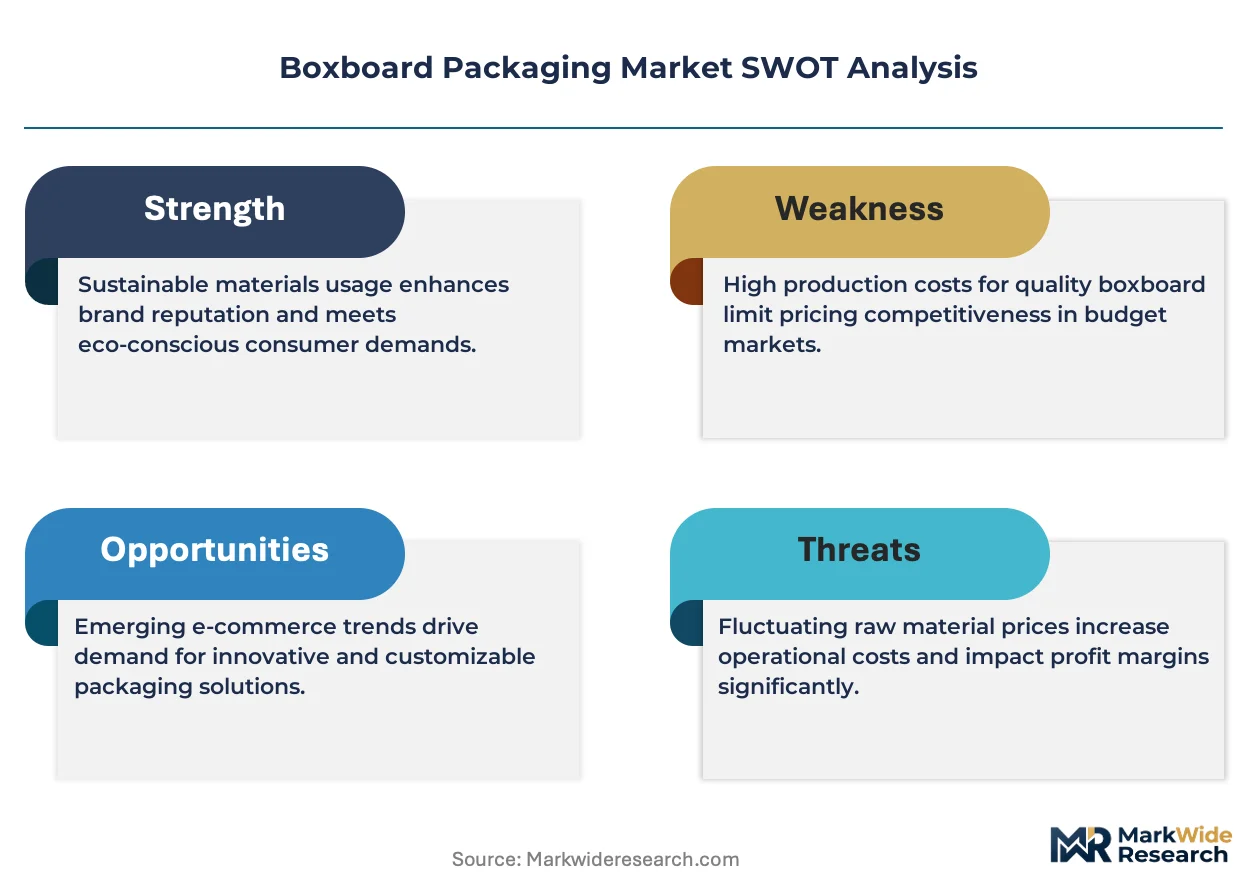
Material substitution mandates from the EU Green Deal are forcing packaging procurement teams to requalify fiber-based alternatives across food, personal care, and pharmaceutical supply chains. This regulatory pressure cascades through converter networks, reshaping capital allocation toward bleached and unbleached kraft capacity.
Growth Catalysts
- EU Packaging Waste Directive:Mandatory recycled content thresholds for consumer-facing packaging are pulling folding boxboard volumes into applications previously dominated by flexible plastic films.
- E-commerce protective packaging:Unbleached kraft board is absorbing demand from expanded polystyrene and plastic air pillows in fulfillment center operations across Germany, France, and the Netherlands.
- Barrier coating advances:Water-based and bio-based coatings are eliminating polyethylene lamination requirements, opening food-contact applications to mono-material fiber solutions.
Market Restraints
- Pulp cost volatility:Northern bleached softwood kraft pulp pricing swings directly compress converter margins, particularly for solid bleached board producers without captive pulp supply.
- Recycled fiber contamination limits:China's GB standards for recovered paper imports restrict feedstock availability for European mills dependent on Asian export markets for fiber sourcing.
- Plastic substitution ceiling:High-moisture and extended-shelf-life food applications retain polymer barriers where fiber-based alternatives fail oxygen and water vapor transmission specifications.
Strategic Opportunities
- Pharmaceutical serialization compliance:The EU's Falsified Medicines Directive creates demand for tamper-evident folding cartons with integrated track-and-trace features in secondary packaging.
- Direct-to-consumer fresh produce:Corrugated and solid fiber boxes are displacing single-use plastic clamshells in subscription meal-kit and organic grocery delivery channels.
- Carbon border adjustment mechanism:CBAM implementation favors European-sourced boxboard with verified Scope 3 emissions data over imports from carbon-intensive production geographies.
Industry Challenges
- Barrier coating migration compliance:ECHA enforcement of REACH substance restrictions for food-contact materials requires extensive laboratory validation timelines that delay new product launches by 12-18 months.
- Digital print integration:Converters face capex intensity from inkjet and toner-based production systems while managing legacy offset and flexo capacity utilization across shorter run lengths.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boxboard Packaging Market |
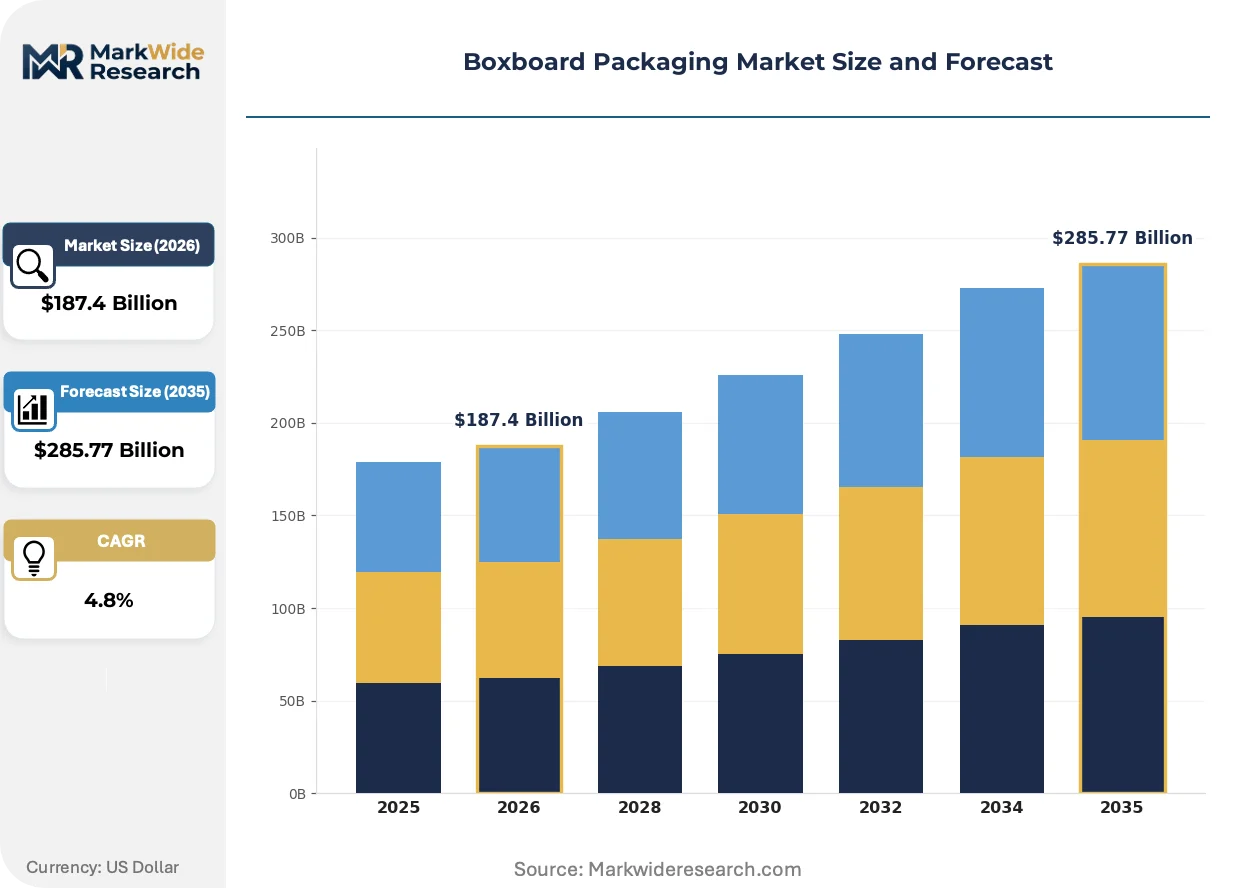
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding Boxboard, Solid Bleached Board, Unbleached Kraft Board, Coated Recycled Board End User: Food & Beverage, Personal Care, Healthcare, Consumer Electronics Application: Retail Packaging, Food Packaging, E-commerce Shipping, Industrial Packaging Material: Kraft Paper, Recycled Material, Coated Paperboard, Bio-based Plastics |
| Companies Covered | Mayr-Melnhof Karton AG, Mondi Group, WestRock Company, GMS Industries, Huhtamaki, International Paper Company, Stora Enso, Rengo Co., Ltd., Smurfit Kappa Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boxboard Packaging Market Strategic Shifts
Digitalization of packaging workflows is compressing design-to-delivery cycles while enabling mass customization. These shifts are converging with material science advances and regulatory disclosure requirements to redefine competitive advantage.
Barrier technology is unifying oxygen and moisture protection within single-layer fiber substrates, eliminating multi-material lamination complexity. Food brands in ready-meal and confectionery segments are qualifying these structures for shelf-life extension. The technology is unifying supply chains by reducing converter inventory SKUs and simplifying end-of-life recycling streams.
REACH compliance documentation is mandating full substance disclosure for coatings, adhesives, and printing inks used in food-contact applications. The European Chemicals Agency's SCIP database requirements are extending traceability obligations through the entire packaging value chain. Healthcare and infant nutrition brands are most affected, with procurement teams now requiring third-party certified material passports from board suppliers.
Brand-owner sustainability scorecards are weighting circularity metrics above unit cost in supplier selection criteria. Major retail chains in Germany and France are delisting packaging formats that fail to meet mono-material recyclability standards. This behavioral shift is most visible in private-label cosmetics and premium chocolate, where folding boxboard with water-based coatings is displacing metallized and plastic-windowed alternatives.
Boxboard Packaging Market Segmentation
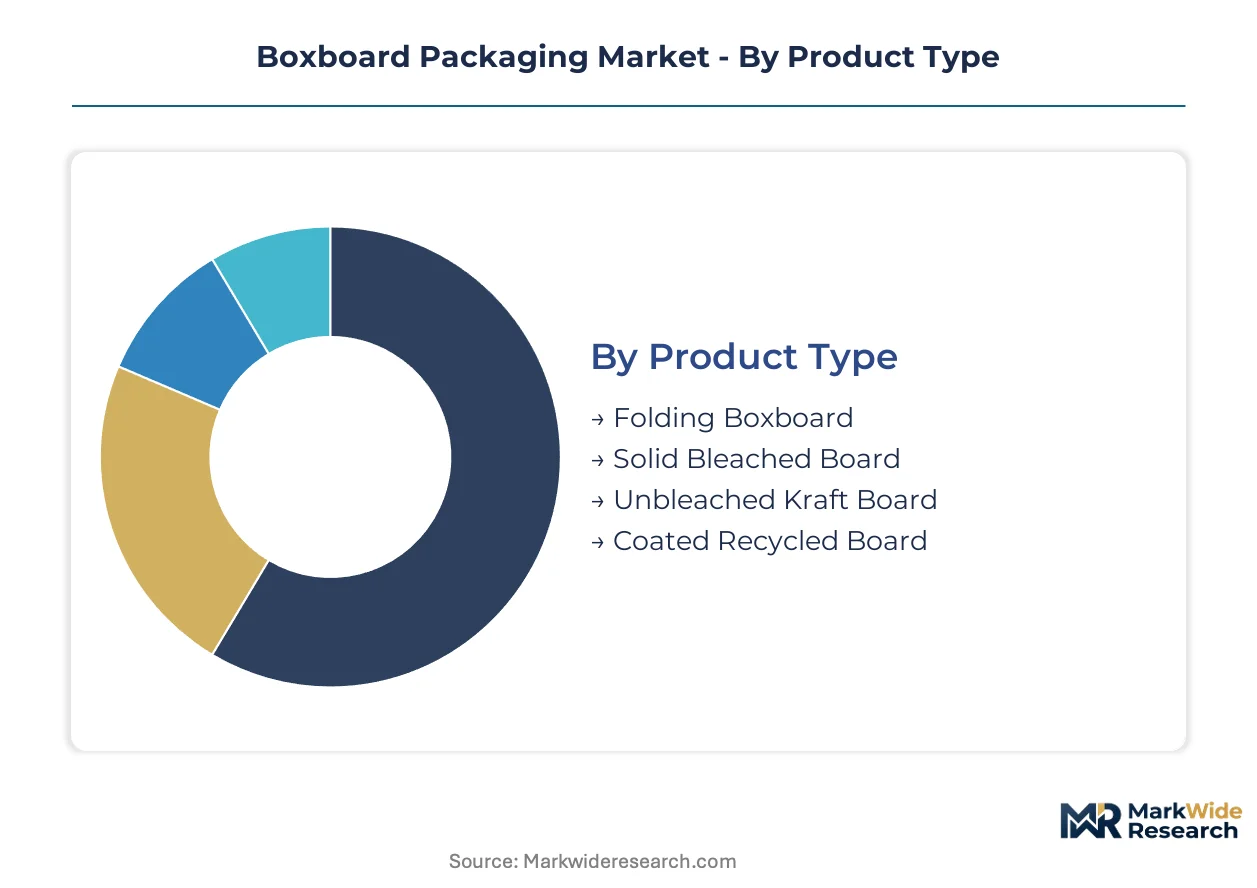
Boxboard packaging exhibits sharp performance divergence across substrate grades and end-use specifications. Procurement teams segment demand by barrier requirements, print fidelity needs, and end-of-life compliance obligations rather than unit cost alone.
Product Type:
Customization intensity varies from commodity unbleached grades to precision-engineered solid bleached substrates with tight caliper tolerances.
- Folding Boxboard:Multi-ply construction combines mechanical pulp core with bleached chemical pulp outer layers, delivering retail-grade print surfaces at moderate basis weights. German and French FMCG brands absorb rising volumes for chocolate, cosmetics, and premium dry foods where shelf impact governs purchase decisions. REACH-compliant water-based coatings are displacing polyethylene lamination in this grade.
- Solid Bleached Board:Homogeneous bleached chemical pulp structure provides exceptional stiffness-to-weight ratio and hygienic surface properties. Healthcare and infant nutrition sectors in Switzerland and the Netherlands specify this grade for tamper-evident cartons requiring FDA and EMA compliance documentation. Captive pulp integration separates profitable producers from margin-compressed converters.
- Unbleached Kraft Board:Natural lignin-bearing fibers yield high tear strength and moisture resistance for protective applications. E-commerce fulfillment centers in the Netherlands specify this grade for void-fill and edge protection replacing expanded polystyrene.
- Coated Recycled Board:Post-consumer fiber content with clay or calcium carbonate coating layers meets EU Packaging Waste Directive recycled content thresholds. Budget retail chains in Spain and Italy specify this grade for private-label dry groceries.
Leading the category by volume: Folding Boxboard. Growing fastest: Unbleached Kraft Board.
End User:
Regulatory exposure and margin structure differentiate these demand pools, with food-contact compliance commanding premium pricing.
- Food & Beverage:Largest demand concentration spanning confectionery, ready meals, and beverage multipacks. Barrier coating advances are extending fiber-based solutions into chilled and short-shelf-life categories previously polymer-dependent.
- Personal Care:Premium folding cartons for skincare and fragrance demand high-gloss print surfaces and rigid structural performance. German and French beauty brands are eliminating plastic windows in favor of mono-material fiber constructions.
- Healthcare:Pharmaceutical serialization requirements under the EU Falsified Medicines Directive drive demand for tamper-evident folding cartons with integrated track-and-trace compatibility. Swiss and Belgian packaging converters specialize in this compliance-intensive segment.
- Consumer Electronics:Protective transit packaging for smartphones, tablets, and accessories requires anti-static coatings and precise fitment. Unbleached kraft grades dominate this application with molded pulp inserts gaining share against plastic foam.
Food & Beverage generates absolute volume. Healthcare commands steepest price premiums per square meter.
Application:
Run length economics and speed-to-market requirements create distinct equipment and workflow configurations across these use cases.
- Retail Packaging:Point-of-sale visibility demands drive specification for bright white print surfaces, foil stamping compatibility, and precise die-cutting. Belgian and Dutch converters lead in short-run digital production for seasonal promotional campaigns.
- Food Packaging:Direct food contact compliance dominates specification criteria with ECHA substance restrictions and migration testing protocols extending qualification timelines. Water-based barrier coatings are qualifying for dry and semi-moist food categories.
- E-commerce Shipping:Protective yet recyclable transit formats are absorbing volume from plastic air pillows and bubble wrap. German fulfillment networks specify FEFCO-standard box designs optimized for automated packing lines.
- Industrial Packaging:Heavy-duty solid fiber and corrugated applications for automotive components and machinery parts prioritize stacking strength and moisture resistance over print quality.
E-commerce Shipping climbs fastest in annual volume growth. Retail Packaging retains highest value per ton.
Material:
Feedstock provenance and carbon intensity credentials increasingly govern supplier selection alongside functional performance.
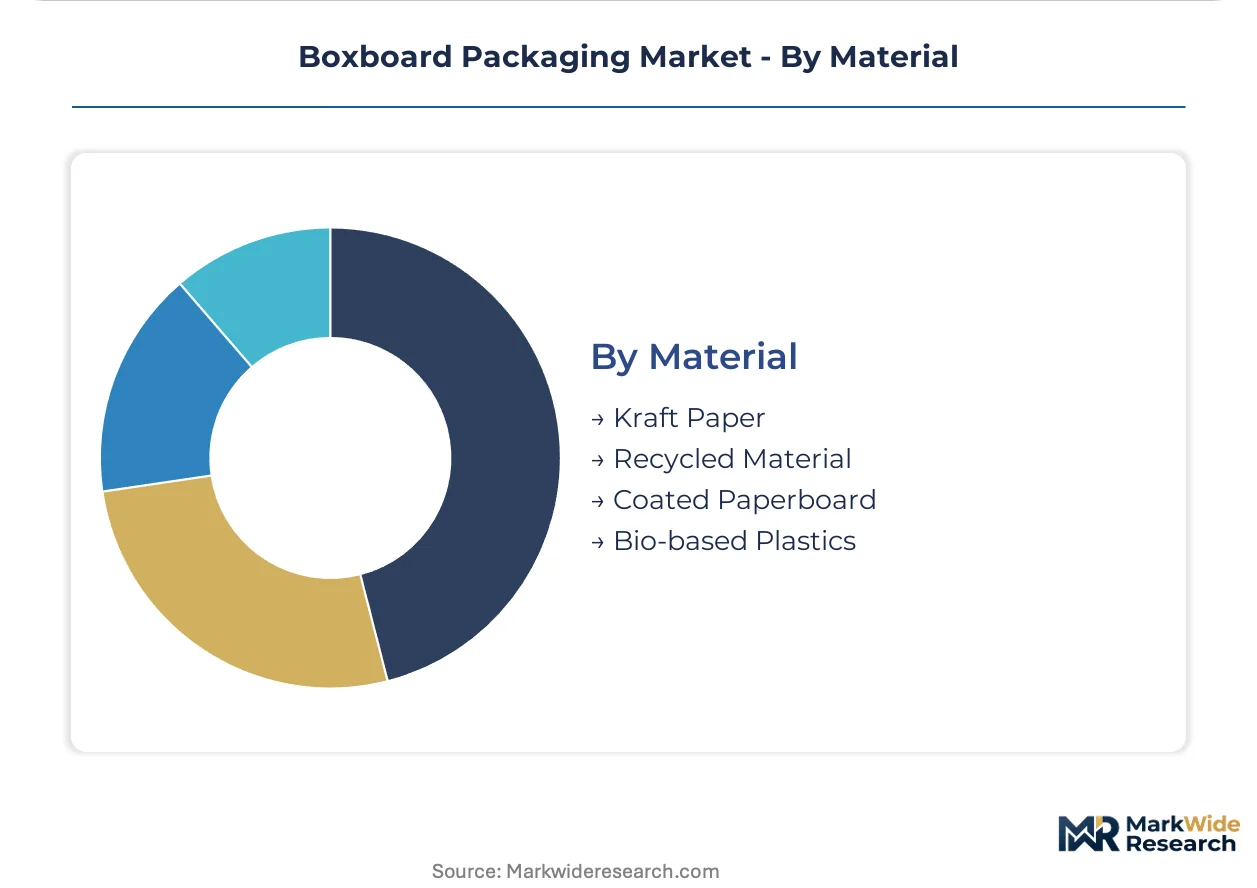
- Kraft Paper:Virgin softwood pulp delivers superior tear strength and printability for premium folding boxboard applications. Nordic forest certification schemes provide Scope 3 emissions documentation required by EU CBAM compliance.
- Recycled Material:Post-consumer fiber streams face contamination limits under China's GB standards, constraining European mill feedstock access. Quality sorting infrastructure in Germany and France determines usable yield rates.
- Coated Paperboard:Mineral coating layers enhance print gloss and ink holdout for high-end cosmetic and confectionery packaging. Coating formulation chemistry falls under REACH substance disclosure requirements.
- Bio-based Plastics:PLA and starch-based barrier layers provide oxygen and moisture protection in hybrid fiber-plastic structures. Composting infrastructure availability limits end-of-life claims in most European markets.
Recycled Material leads by tonnage consumed. Bio-based Platics expands most quickly from low base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Düsseldorf anchors European boxboard procurement as retail headquarters and converter networks cluster along the Rhine-Ruhr corridor. German FMCG brands drive premium folding boxboard specifications that cascade through neighboring supply chains.
Germany
Chocolate and cosmetics brands in Cologne and Hamburg absorb rising volumes of solid bleached board for shelf-ready packaging. The EU Packaging Waste Directive mandates recycled content thresholds that reshape converter sourcing criteria. Bavarian mills specializing in coated recycled board expand capacity to serve private-label grocery chains.
United States
E-commerce fulfillment centers in Chicago and Dallas specify unbleached kraft board for protective transit applications replacing plastic void fill. FDA migration limits for food-contact materials extend qualification timelines for coated folding cartons. Wisconsin and Georgia host concentrated corrugated and boxboard conversion corridors serving CPG distribution networks.
China
Export-oriented manufacturers in the Yangtze River Delta consume coated recycled board for consumer electronics and household goods packaging. SAMR enforces GB standards for recovered paper imports that constrain European mill feedstock access. Guangdong Province converters specialize in short-run digital production for seasonal promotional campaigns.
Netherlands
Rotterdam port logistics and distribution hubs drive demand for FEFCO-standard shipping boxes optimized for automated packing lines. REACH compliance documentation for coatings and adhesives extends supply chain traceability obligations. Eindhoven-region converters develop barrier-coated mono-material solutions for ready-meal applications.
Japan
Premium confectionery and gift packaging in Tokyo and Osaka sustain demand for high-gloss solid bleached board with precise caliper tolerances. METI circular economy guidelines accelerate mono-material fiber substitution for multi-layer plastic formats. Nagoya industrial clusters specialize in precision die-cutting for consumer electronics protective packaging.
Boxboard Packaging Market Competitive Environment
The competitive structure tilts toward integrated pulp-to-board operators with captive fiber supply and converter networks with regional density advantages. Tier-one players control Nordic timber holdings and bleached kraft pulp capacity that underpins margin stability. Mid-scale specialists concentrate on compliance-intensive pharmaceutical and infant nutrition segments. Dominant competitive moves include backward integration into pulp assets and geographic expansion through converter acquisition.
Among Nordic-integrated operators, Stora Enso exemplifies the timber-holding archetype with certified sustainable forestry coverage, while Mondi Group occupies a position spanning integrated pulp production and multinational supply contracting. Mayr-Melnhof Karton AG represents the European converter-network model with concentrated folding boxboard capacity serving German and Central European FMCG brands.
| Leading Market Players |
|---|
| Mayr-Melnhof Karton AG |
| Mondi Group |
| WestRock Company |
| GMS Industries |
| Huhtamaki |
| International Paper Company |
| Stora Enso |
| Rengo Co., Ltd. |
| Smurfit Kappa Group |
| Others |
Value Chain & Pricing Dynamics
Digital print integration across European converter networks is compressing run-length economics while simultaneously concentrating procurement leverage among equipment-scale players. This technology transition rewards mills with captive pulp supply and penalizes merchant converters exposed to spot fiber markets.
Pricing Analysis
Value-based pricing anchored to barrier performance and food-contact compliance certification commands premiums over commodity grades. Three-tier pricing structure across premium, standard, and economy levels stratifies by virgin fiber content, REACH documentation depth, and caliper precision. Cost compression in coated recycled board intensifies because Chinese GB contamination limits constrain European feedstock access. Budget retail chains exhibit highest price sensitivity, while pharmaceutical and infant nutrition brands absorb steep premiums for solid bleached board with full material traceability.
Supply Chain Analysis
Regional distribution centers along the Rhine-Ruhr corridor and Rotterdam port logistics hubs orchestrate just-in-time delivery to German FMCG headquarters. Pulp supply concentrates in Sweden, Finland, and Germany, with Nordic timber holdings providing Scope 3 emissions documentation for EU CBAM compliance. Raw material sourcing draws from northern bleached softwood kraft pulp, post-consumer recovered fiber streams, and mineral coating formulations. Single-source vulnerability persists for barrier coating chemistries subject to ECHA substance restrictions. Distribution runs through converter networks with dense geographic coverage in Benelux and German industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into pulp assets and converter network density defines competitive survival as players race to control fiber supply and regional logistics corridors.
For Market Incumbents: Anchor market position through certified sustainable forestry expansion and pharmaceutical serialization capability investment. Barrier coating R&D defends against plastic substitution ceilings in high-moisture food applications. Capacity consolidation in Central European folding boxboard addresses margin pressure from digital print disruption. For New Entrants and Emerging Players: The price-point gap between premium solid bleached board and economy coated recycled board creates entry space for mid-tier specialists. Target pharmaceutical contract packaging in Switzerland and Belgium where compliance documentation requirements deter commodity competition. Lead with water-based barrier coating qualification to bypass polyethylene lamination incumbency. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated Nordic operators seeking Central European converter density. Five-to-ten-year viability hinges on EU Packaging Waste Directive enforcement trajectory and carbon border adjustment mechanism scope expansion. Watch ECHA substance restriction expansion timelines as inflection signals for coating chemistry obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Assets | Nordic timber holdings provide Scope 3 emissions data required by EU CBAM compliance frameworks. |
| Barrier Coating R&D Investment | Water-based formulations qualify fiber substrates for food-contact applications previously polymer-dependent. |
| Pharmaceutical Serialization Capability | EU Falsified Medicines Directive mandates tamper-evident cartons with integrated track-and-trace features. |
| Converter Network Geographic Expansion | Rhine-Ruhr corridor density captures procurement decisions from Cologne and Hamburg FMCG headquarters. |
| Digital Print Production Scale-Up | Inkjet and toner systems compress design-to-delivery cycles for seasonal promotional campaigns. |
Study Parameters
Trade association filings, customs and import-export databases, and SEC regulatory disclosures formed the secondary backbone for volume and trade flow estimation. Primary interviews with mill procurement directors, converter operations managers, brand-owner packaging engineers, and retail category buyers validated fiber sourcing patterns and qualification timelines. Bottom-up and top-down triangulation reconciled capacity utilization data against end-use demand segmentation.
Bottom-up modeling built demand estimates from application-level consumption patterns across food, personal care, healthcare, and electronics segments. The analysis window spans product-type segmentation by substrate grade, end-user regulatory exposure tiers, and application run-length economics. CAGRs derived from historical volume trajectories and policy-driven substitution elasticities incorporated EU Green Deal implementation pace and e-commerce fulfillment center expansion curves.
Inputs from pulp futures markets and converter equipment utilization surveys were available through the study window; gaps in private-label contract pricing introduce uncertainty bands around margin estimates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Russia Paper Packaging Market
Paper & Paperboard Packaging
Global Paper Bags Market
Paper & Paperboard Packaging
Medical Packaging Paper Market
Paper & Paperboard Packaging
MMA Film & Sheet Market
Paper & Paperboard Packaging
Micro Flute Paper Market
Paper & Paperboard Packaging
Paper Cone Cup Market
Paper & Paperboard Packaging
Wax-Coated Paper Market
Paper & Paperboard Packaging
North America Corrugated Board Packaging Market
Paper & Paperboard Packaging
White Sack Kraft Paper Market
Paper & Paperboard Packaging
Vietnam Paper Packaging Market
Paper & Paperboard Packaging
Paper and Paperboard Trays Market
Paper & Paperboard Packaging
Paperboard Partition Market
Paper & Paperboard Packaging
Paper Cups Market
Paper & Paperboard Packaging
Unbleached Kraft Paperboard Market
Paper & Paperboard Packaging
Fast Food Wrapping Paper Market
Paper & Paperboard Packaging
Bamboo Packaging Market