
 Malaysia Commercial Real Estate Market | 2026-2036
Malaysia Commercial Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Commercial Real Estate Market Foresight
Real Estate Investment Trust (REIT) monetization and asset-light leasing structures are reshaping competitive entry in Malaysian commercial property. IGB REIT leverages its Mid Valley Megamall and The Gardens Mall assets to sustain dominant retail cash flows across the Klang Valley. S P Setia Bhd anchors its position through integrated township developments that combine commercial, residential, and industrial zoning. KLCC Property Holdings Bhd controls premium office stock surrounding the Petronas Towers, occupying the top tier of Kuala Lumpur's Grade A market.
Malaysia commercial real estate encompasses income-producing properties—office towers, retail centers, industrial warehouses, and mixed-use developments—designed for lease to business tenants and typically evaluated by net operating income, capitalization rates, and lease duration profiles. The sector serves as critical infrastructure for corporate operations, supply chain logistics, and consumer commerce across Peninsular Malaysia and East Malaysia. Industrial and logistics assets lead structural expansion as manufacturing reshoring and e-commerce fulfillment reshape tenant demand, while stabilized office properties in Kuala Lumpur's central business district retain the deepest institutional capital pools. Retail and mixed-use developments face more fragmented investor profiles, with family offices and private equity funds targeting value-add repositioning of aging suburban malls.
BIS Malaysia enforces green building standards through its Green Building Index certification, which shapes new construction specifications and retrofit requirements for commercial developments seeking premium rents. The Securities Commission Malaysia regulates REIT disclosures and distribution obligations, directly influencing how listed vehicles like Sunway REIT and Pavilion REIT structure acquisitions and capital recycling. Stakeholders must monitor how Bank Negara Malaysia's interest rate posture and the government's Industrial Master Plan implementation alter debt financing costs and permitted land-use conversions across key growth corridors.
Market Dynamics
Industrial and logistics asset demand in Malaysia is compressing development timelines as e-commerce fulfillment operators and contract logistics providers race to secure modern warehouse stock in Greater Kuala Lumpur and Johor Bahru. This supply-side pressure is reshaping land-use negotiations, construction procurement, and capital deployment priorities across the commercial property sector.
Growth Catalysts
- Industrial Master Plan incentives:Government tax allowances and infrastructure grants are accelerating manufacturing reshoring projects that require dedicated logistics facilities and purpose-built industrial estates.
- E-commerce fulfillment density:Last-mile delivery networks are expanding warehouse footprints to meet same-day delivery service level agreements in the Klang Valley corridor.
- BIS Malaysia green certification mandates:Green Building Index requirements for new commercial construction are driving premium rents for certified Grade A office and retail assets.
Market Restraints
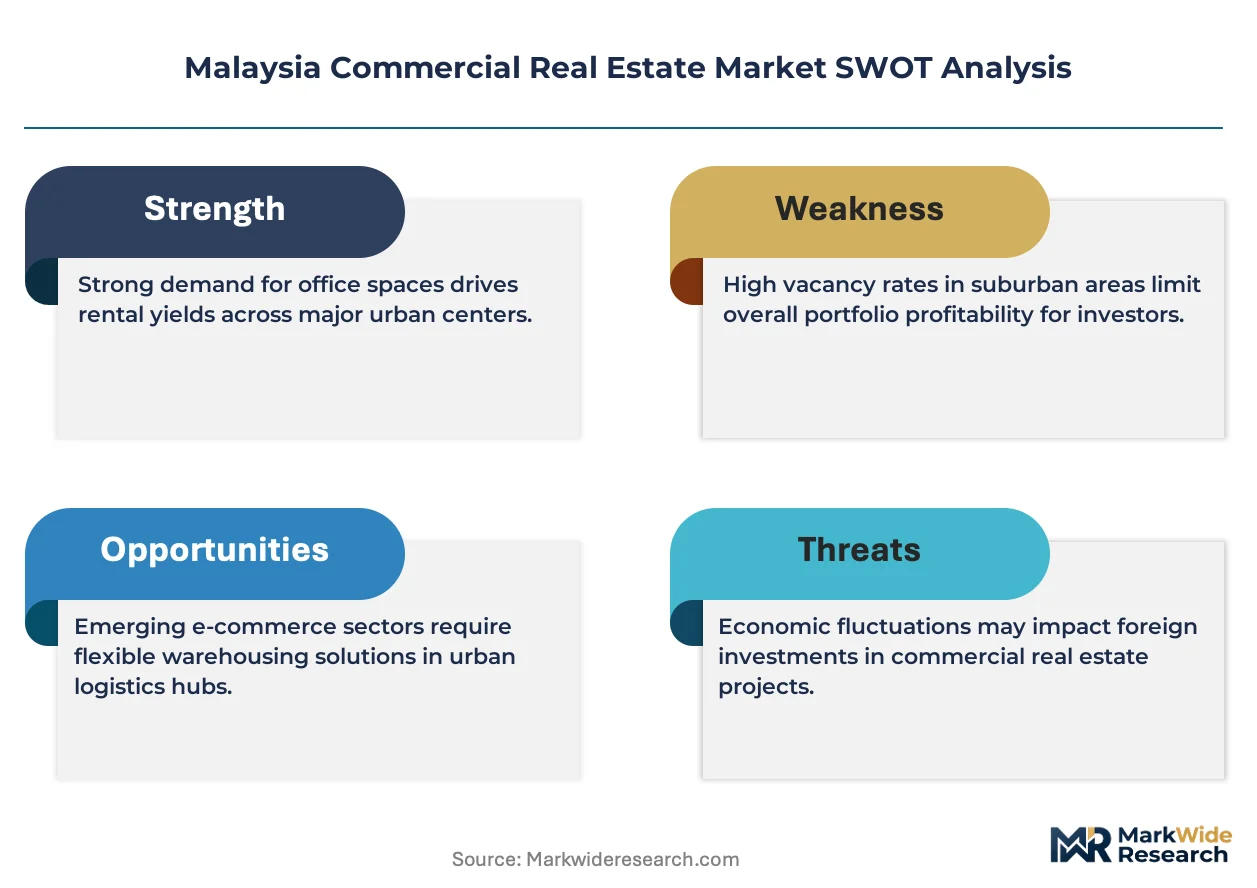
- Construction input cost volatility:Steel and cement price fluctuations are squeezing development margins and delaying project feasibility assessments for speculative industrial builds.
- Grade A office supply concentration:Premium stock remains clustered in Kuala Lumpur's central business district, limiting tenant expansion options in secondary submarkets.
- Land conversion regulatory friction:State-level planning approvals for industrial zoning changes create multi-year timelines that mismatch investor return expectations.
Strategic Opportunities
- Johor Bahru logistics corridor expansion:Proximity to Singapore's port infrastructure and the Iskandar Malaysia special economic zone is attracting cross-border distribution center investments.
- REIT monetization of suburban retail:Listed vehicles can unlock capital from aging mall assets through sale-leaseback structures and mixed-use redevelopment.
- Smart building technology convergence:Integration of building management systems with IoT sensors and energy analytics is enabling operational cost reductions for institutional landlords.
Industry Challenges
- Green building certification skill scarcity:Shortage of accredited professionals capable of navigating BIS Malaysia's Green Building Index documentation requirements is extending project timelines.
- Legacy asset retrofit capex intensity:Aging office and retail stock requires substantial capital for mechanical system upgrades to meet current energy efficiency standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Commercial Real Estate Market |
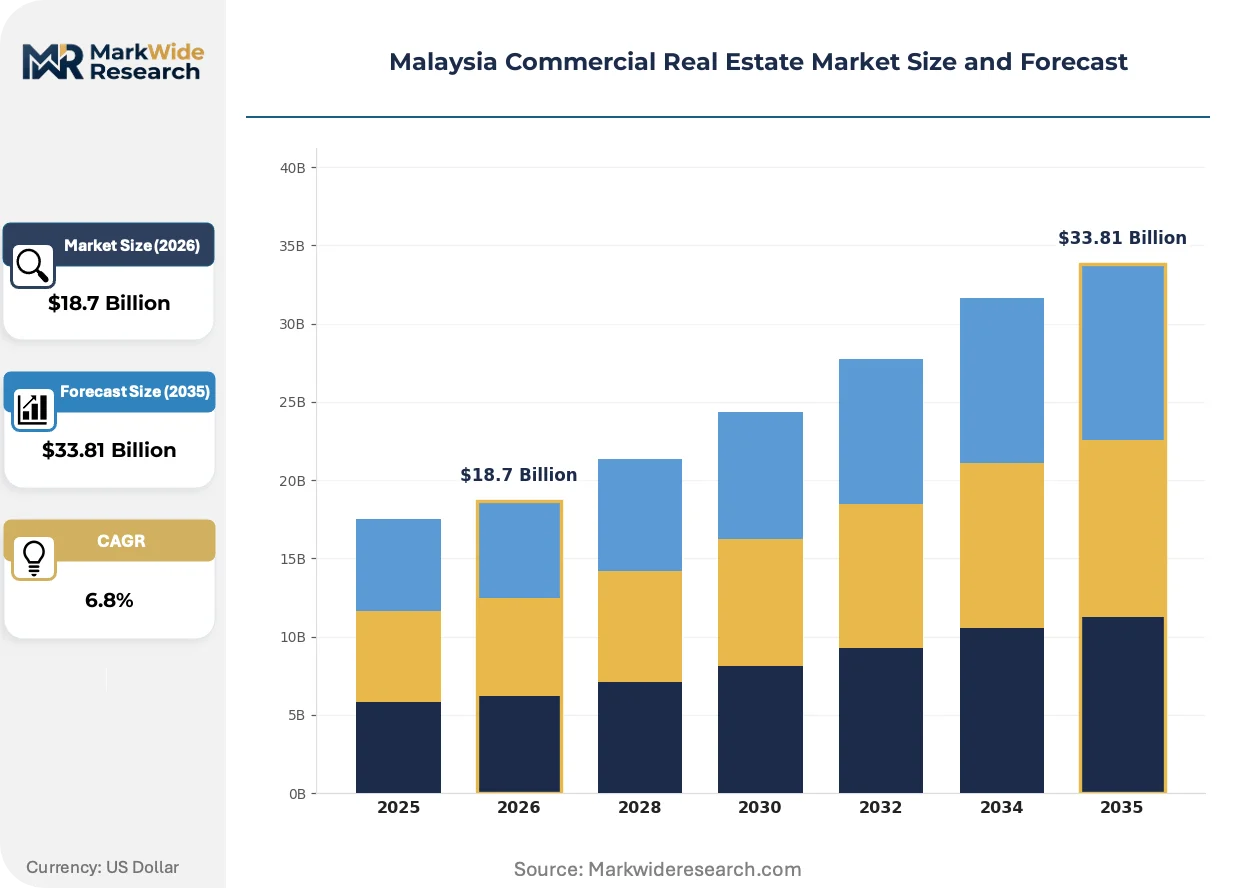
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Office, Retail, Industrial, Mixed-Use Investment Stage: Development, Stabilized, Value-Add, Opportunistic Client Type: Institutional Investors, Private Equity, REITs, Family Offices Lease Structure: Gross Lease, Net Lease, Modified Gross Lease, Ascending Lease |
| Companies Covered | IGB REIT, S P Setia Bhd, KLCC Property Holdings Bhd, Gamuda Bhd, UEM Sunrise Bhd, Sunway REIT, Sime Darby Property Bhd, IJM Corporation Bhd, Pavilion REIT, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Commercial Real Estate Market Shifts & Advancements
Technology deployment and regulatory tightening are converging to redefine asset valuation methodologies and tenant service expectations across Malaysian commercial property. These shifts are compressing traditional development cycles and elevating operational performance standards.
Building management platforms integrating IoT sensors, predictive analytics, and automated climate control are digitizing facility operations across Grade A office towers. Institutional landlords including KLCC Property Holdings and IGB REIT are deploying these systems to reduce energy expenditures and extend asset economic life. The structural consequence is digitizing how net operating income is calculated and reported to capital markets.
BIS Malaysia's Green Building Index certification requirements are mandating minimum performance thresholds for water efficiency, indoor environmental quality, and sustainable site planning in new commercial construction. Developers seeking premium tenant rates must incorporate solar photovoltaic systems, rainwater harvesting, and low-emissivity glazing from design inception. The office segment is responding fastest, with speculative development now routinely targeting Gold or Platinum ratings to differentiate against aging stock.
Tenant procurement of commercial space is compressing lease commitment cycles as corporates prioritize flexibility over long-term cost certainty. Short-term leases and fitted-out spec suites are displacing traditional ten-year bare shell agreements in Kuala Lumpur's central business district. This pattern is most visible among technology and professional services firms expanding regional headquarters operations.
Malaysia Commercial Real Estate Market Segmentation
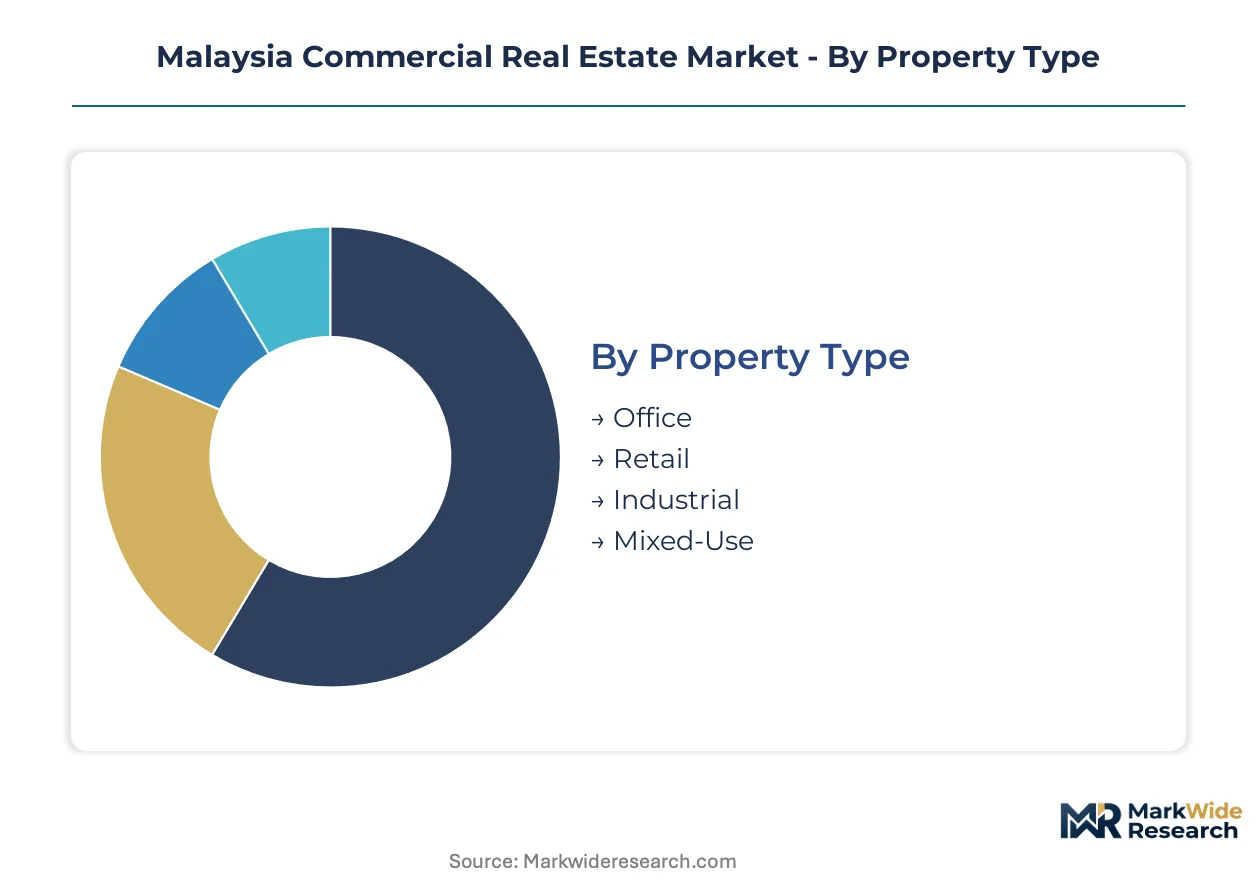
Property classification in Malaysian commercial real estate determines capital deployment horizons, risk-return profiles, and regulatory exposure. Each segmentation dimension reveals distinct liquidity patterns and tenant covenant quality that shape portfolio construction decisions across the Klang Valley and secondary growth corridors.
Property Type:
Development cycles vary dramatically across property types, with industrial assets turning over fastest due to compressed construction timelines and e-commerce-driven pre-leasing, while mixed-use developments require decade-long holding periods to capture full value crystallization.
- Office:Grade A towers in Kuala Lumpur's central business district command premium rents through floor efficiency ratios and smart building certifications. Demand concentrates among financial services and technology firms expanding regional headquarters operations, though secondary submarkets face elevated vacancy pressure from aging stock.
- Industrial:Modern logistics warehouses and purpose-built manufacturing facilities in Greater Kuala Lumpur and Johor Bahru are compressing delivery timelines as multinational operators secure build-to-suit commitments ahead of construction completion. E-commerce fulfillment density and contract logistics expansion are the dominant demand drivers reshaping land values.
- Retail:Shopping centers and street-front commercial units serve consumer commerce across urban and suburban catchments.
- Mixed-Use:Integrated developments combining residential, commercial, and hospitality components require extended capital commitment periods to synchronize phasing with infrastructure delivery.
Industrial assets anchor the volume base through accelerated development pipelines while mixed-use projects gain share at the steepest rate as developers pursue diversified revenue streams.
Investment Stage:
Risk-return positioning stratifies across maturity spectrums, with stabilized assets trading on yield compression and opportunistic plays requiring active repositioning expertise to unlock value.
- Development:Ground-up construction of commercial assets carries entitlement risk, construction cost volatility, and pre-leasing uncertainty. Returns concentrate in land value appreciation and development margin capture upon completion.
- Stabilized:Income-producing properties with lease rollover visibility and established tenant covenants trade on capitalization rate compression in institutional capital markets.
- Value-Add:Assets requiring capital infusion for renovation, re-tenanting, or operational improvement occupy the middle risk tier.
- Opportunistic:Distressed or structurally challenged properties demand specialized workout capabilities and extended hold periods.
Stabilized assets dominate institutional allocation while value-add strategies are expanding most quickly as private equity targets aging suburban retail and secondary office repositioning.
Client Type:
Capital source differentiation determines investment horizon preferences, governance requirements, and exit pathway flexibility across the Malaysian market.
- Institutional Investors:Pension funds and sovereign wealth vehicles prioritize core-plus office and logistics assets with inflation-linked lease structures and long-dated income visibility.
- REITs:Listed vehicles including Sunway REIT and Pavilion REIT deploy acquisition capacity against distribution yield requirements and regulatory disclosure obligations.
- Private Equity:Closed-end funds target value-add and opportunistic positions with three-to-five-year value creation horizons.
- Family Offices:Patient capital sources pursue legacy asset accumulation and development platform control with multi-generational holding capacity.
REITs anchor transaction liquidity while private equity is gaining deployment share fastest through specialized industrial and logistics mandates.
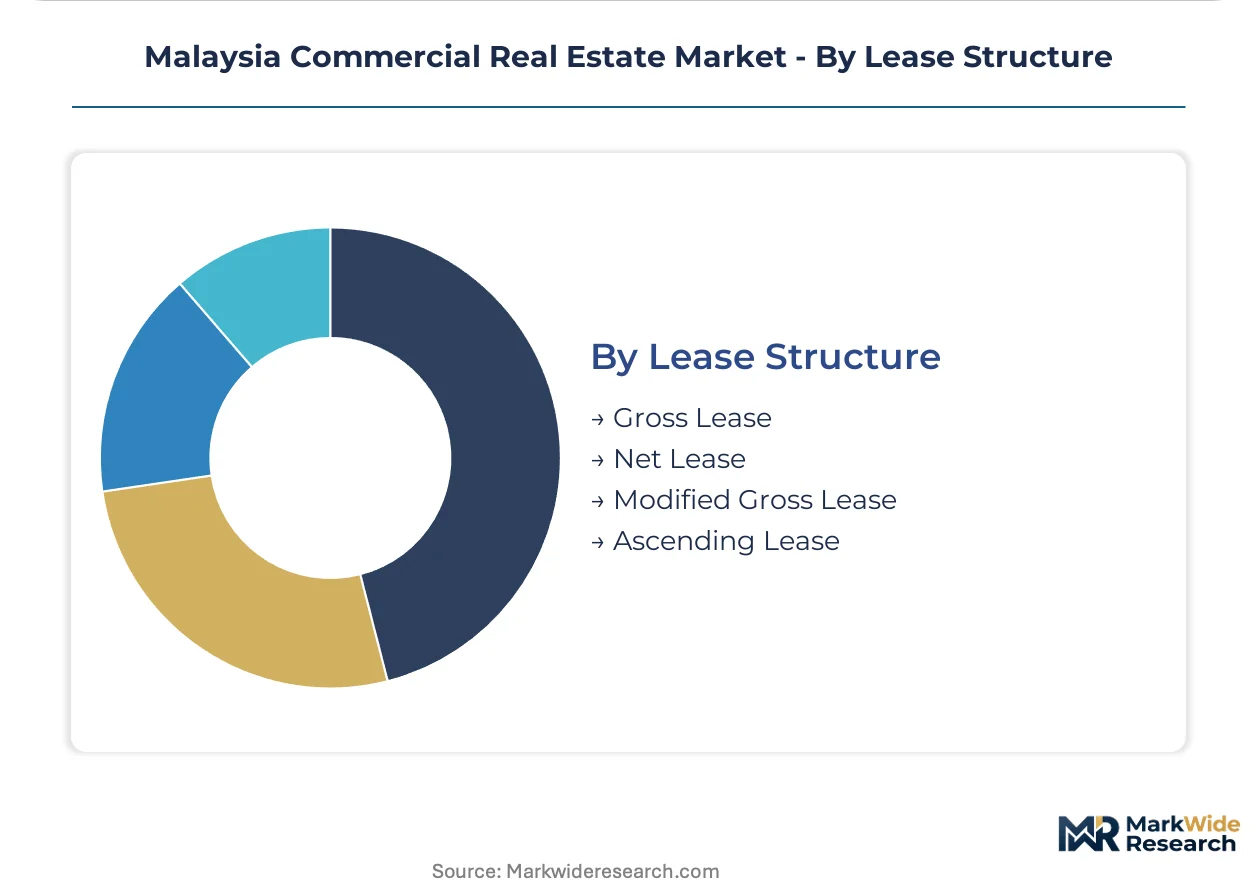
Lease Structure:
Contract economics distribute operating cost responsibilities and rent escalation mechanisms between landlords and tenants, directly impacting net operating income stability.
- Gross Lease:Landlord bears property tax, insurance, and maintenance costs in exchange for higher base rent, common in older office stock and retail centers.
- Net Lease:Tenant assumes operating cost responsibilities, providing landlords with predictable cash flows and reduced management intensity.
- Modified Gross Lease:Hybrid structures allocate specific expense categories to each party based on negotiation leverage and asset vintage.
- Ascending Lease:Step-up rent schedules align tenant obligations with projected income growth or business ramp timelines.
Net lease structures dominate new institutional-grade supply while ascending leases are proliferating fastest among technology and flexible workspace operators seeking occupancy cost alignment with revenue growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia's Industrial Master Plan incentives and BIS Malaysia green certification mandates are concentrating commercial real estate development in designated growth corridors. State-level planning authorities and federal infrastructure programs shape land-use conversion timelines across Peninsular Malaysia.
Klang Valley
Grade A office demand from financial services and technology firms drives premium rent formation in Kuala Lumpur's central business district. BIS Malaysia's Green Building Index requirements accelerate retrofit specifications for aging stock. Petaling Jaya and Subang Jaya submarkets absorb spillover demand as central district supply tightens.
Greater Kuala Lumpur
E-commerce fulfillment operators and contract logistics providers compress warehouse development timelines through build-to-suit pre-commitments. The Securities Commission Malaysia regulates REIT disclosures for listed vehicles acquiring industrial assets. Shah Alam and Klang logistics corridors attract multinational distribution center investments.
Johor Bahru
Proximity to Singapore's port infrastructure positions the Iskandar Malaysia special economic zone for cross-border distribution center expansion. State-level industrial zoning approvals determine land conversion velocity for speculative warehouse builds. Pasir Gudang and Tanjung Pelepas port vicinities concentrate modern logistics stock.
Penang
Manufacturing reshoring projects under the Industrial Master Plan generate demand for purpose-built industrial estates and supporting logistics facilities. Penang Development Corporation coordinates infrastructure delivery with private sector land assembly. Bayan Lepas and Batu Kawan industrial zones attract electronics and medical device manufacturing tenants.
Malaysia Commercial Real Estate Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Malaysia's commercial real estate sector. REITs and large-cap developers dominate institutional capital flows through portfolio scale and distribution visibility. Three archetypes structure competition: yield-focused listed vehicles, integrated township developers, and specialized industrial estate operators. Dominant competitive moves include REIT monetization of stabilized assets and strategic land banking in designated growth corridors.
Within the listed vehicle tier, IGB REIT and Sunway REIT exemplify yield-focused strategies through retail and mixed-use asset aggregation. S P Setia Bhd occupies a position among integrated township developers combining commercial, residential, and industrial zoning across extended holding periods. These three entities represent distinct capital deployment archetypes within Malaysia's commercial property sector.
| Leading Market Players |
|---|
| IGB REIT |
| S P Setia Bhd |
| KLCC Property Holdings Bhd |
| Gamuda Bhd |
| UEM Sunrise Bhd |
| Sunway REIT |
| Sime Darby Property Bhd |
| IJM Corporation Bhd |
| Pavilion REIT |
| Others |
Supply & Pricing Matrix
Undercapacity in Grade A office stock across Kuala Lumpur's central business district is compressing landlord pricing power while accelerating construction procurement cycles for speculative industrial builds in Greater Kuala Lumpur and Johor Bahru. This utilization asymmetry between asset classes is reshaping both tenant negotiation leverage and developer capital allocation priorities across Malaysian commercial property.
Pricing Analysis
Certification level under BIS Malaysia's Green Building Index creates the primary spread between premium Grade A office rents and secondary market rates, with Gold and Platinum ratings commanding measurable rent premiums over uncertified stock. Three-tier pricing structure across green-certified premium, aging standard-grade, and economy-tier suburban assets reflects tenant willingness to pay for operational efficiency and corporate sustainability mandates. Cost compression in speculative industrial development is intensifying because steel and cement input volatility is squeezing development margins before pre-leasing commitments crystallize. Multinational logistics operators exhibit lowest price sensitivity due to fulfillment network density requirements, while local retail tenants face acute occupancy cost pressure from consumer foot traffic fragmentation.
Supply Chain Analysis
Export-control restrictions on smart building technologies and IoT-enabled facility management systems are constraining equipment flows into Malaysian Grade A office developments, extending procurement timelines for institutional landlords pursuing digital retrofit programs. Manufacturing concentration for building automation hardware centers on China, Germany, and South Korea, with Malaysian developers drawing from these hubs for predictive analytics platforms and automated climate control infrastructure. Raw material dependencies for commercial construction span structural steel from China and Indonesia, cement from domestic producers, and specialized glazing systems from Japan and Taiwan. Single-source vulnerability in green certification consultancy capacity is elevating project documentation timelines as accredited professionals remain scarce relative to BIS Malaysia mandate compliance demand. Distribution runs through appointed mechanical and electrical contractors who bundle equipment procurement with installation services for speculative and build-to-suit developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysian commercial real estate is experiencing high-growth disruption from e-commerce fulfillment density requirements and BIS Malaysia green certification mandates that are simultaneously compressing development timelines and elevating operational performance standards. These converging forces are restructuring competitive entry barriers and capital deployment priorities across the Klang Valley and secondary growth corridors.
For Market Incumbents: Build land-bank moats in Johor Bahru logistics corridors and Penang industrial zones to preempt multinational distribution center demand from contract logistics operators and manufacturing reshoring projects. Anchor defensive positioning through backward integration into construction procurement to mitigate steel and cement cost volatility, while accelerating Green Building Index certification pipelines to differentiate stabilized assets against aging secondary stock. Monitor emerging threat from flexible workspace operators compressing lease commitment cycles in Kuala Lumpur's central business district. For New Entrants and Emerging Players: Geographic underpenetration in secondary Klang Valley submarkets including Petaling Jaya and Subang Jaya offers white-space acquisition targets for value-add office repositioning and suburban retail redevelopment. Target aging mall assets in family office portfolios where sale-leaseback structures and mixed-use conversion can unlock trapped capital. Pursue build-to-suit logistics development partnerships with e-commerce fulfillment operators as the most penetrable entry vector, leveraging pre-commitment financing to bypass speculative construction risk. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across green-certified Grade A office development as BIS Malaysia mandates require solar photovoltaic integration, rainwater harvesting infrastructure, and low-emissivity glazing from design inception. Long-term viability over the next decade rests on acquiring stabilized logistics assets with inflation-linked lease structures and multinational tenant covenants in Greater Kuala Lumpur and Johor Bahru corridors. Watch for inflection signal in Bank Negara Malaysia interest rate posture, which would alter debt financing costs and REIT distribution coverage ratios across listed vehicles.| Strategic Initiative | Industry Significance |
|---|---|
| Green Building Certification Pipeline | BIS Malaysia Gold and Platinum ratings unlock premium rent formation in Kuala Lumpur's central business district. |
| Build-to-Suit Logistics Development | Pre-leasing commitments from multinational e-commerce operators de-risk speculative industrial construction timelines. |
| REIT Monetization of Suburban Retail | Sale-leaseback structures enable capital recycling into mixed-use redevelopment of aging mall assets. |
| Smart Building Technology Integration | IoT-enabled facility management platforms reduce energy expenditures for institutional landlords like KLCC Property Holdings. |
| Strategic Land Banking in Johor Bahru | Proximity to Singapore's port infrastructure positions Iskandar Malaysia zone for cross-border distribution center demand. |
Research Methodology
Desk research of Securities Commission Malaysia regulatory filings, BIS Malaysia Green Building Index certification databases, and Industrial Master Plan policy documents preceded structured interviews with REIT portfolio managers, commercial property developers, contract logistics procurement leads, and state-level planning authority officers. Primary fieldwork captured capital deployment priorities, pre-leasing commitment patterns, and land conversion timeline expectations across the Klang Valley, Greater Kuala Lumpur, Johor Bahru, and Penang corridors. Secondary validation drew from Bank Negara Malaysia monetary policy statements, construction input cost indices, and warehouse absorption tracking from logistics operator network expansions. Bottom-up tenant demand modeling and top-down macroeconomic scenario analysis were triangulated to establish market sizing and growth trajectory projections.
Forecast assumptions held fixed the current BIS Malaysia green certification mandate trajectory and Industrial Master Plan incentive structure while varying interest rate posture, construction cost inflation scenarios, and cross-border logistics demand intensity across the projection horizon. Segmentation modeling incorporated property type, investment stage maturity, client capital source, and lease structure economics as primary dimensions, with secondary disaggregation by regional submarket and tenant industry vertical. CAGRs were derived from lease rollover visibility schedules, development pipeline completion estimates, and institutional capital flow tracking. Industry-specific inputs included e-commerce fulfillment density growth curves, manufacturing reshoring project announcements, and REIT distribution yield requirement thresholds.
Practitioners should monitor Bank Negara Malaysia rate decisions, BIS Malaysia certification requirement amendments, and state-level industrial zoning approval velocity for early signals of forecast deviation. Forecasts reflect assumptions regarding sustained e-commerce penetration growth and continued multinational logistics operator expansion into Malaysian distribution infrastructure. Material shifts in construction input cost trajectories, green certification professional capacity constraints, or cross-border trade policy configurations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Real Estate
South Africa Commercial Real Estate Market
Commercial Real Estate
UAE Commercial Real Estate Market
Commercial Real Estate
Global Shared Office Spaces Market
Commercial Real Estate
Indonesia Commercial Real Estate Market
Commercial Real Estate
Latin America Commercial Real Estate Market
Commercial Real Estate
Thailand Commercial Real Estate Market
Commercial Real Estate
United Arab Emirates Co-Working Space Market
Commercial Real Estate
Turkey Commercial Real Estate Market
Commercial Real Estate
India Commercial Real Estate Market
Commercial Real Estate
Saudi Arabia Commercial Real Estate Market
Commercial Real Estate
Hospitality Real Estate Sector Market
Commercial Real Estate
Asia Pacific Co-Working Office Spaces Market
Commercial Real Estate
Egypt Commercial Real Estate Market
Commercial Real Estate
Australia Commercial Real Estate Market
Commercial Real Estate
Spain Commercial Real Estate Market
Commercial Real Estate
Canada Hospitality Real Estate Sector Market