
 Egypt Residential Real Estate Market | 2026-2036
Egypt Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Residential Real Estate Market Foresight
Extended-payment financing and mortgage securitization is reshaping competitive access for developers without legacy land banks. Emaar Misr leverages its master-planned community scale to sustain premium positioning across Cairo's eastern periphery. Talaat Moustafa Group anchors mass-market supply through integrated township development in New Cairo. SODIC differentiates via design-led mid-range compounds that compete on finish quality rather than price alone.
Egypt residential real estate encompasses completed dwelling units traded for owner-occupation or rental income, spanning concrete-frame construction with reinforced masonry infill typical of seismic Zone 2B compliance. Apartments dominate transaction volume across Cairo and Alexandria, while villas command concentrated margin pools in gated compounds along the North Coast. Off-plan properties represent the fastest-growing investment type as presale structures allow developers to fund construction without full project finance. Mid-range price tier absorbs the bulk of first-time buyer demand, though luxury segments in New Alamein attract Gulf capital seeking Mediterranean exposure.
Egypt's Mortgage Finance Fund and Central Bank of Egypt shape credit availability through subsidized rate programs and loan-to-value caps that directly determine buyer purchasing power. New Urban Communities Authority land allocation policies dictate developer site access, while building codes enforced by the Housing and Building National Research Center establish seismic and energy efficiency standards. Stakeholders must monitor how currency fluctuation affects imported material costs and whether mortgage subsidy expansion can outpace inflation-driven payment erosion.
Market Dynamics
Subsidized mortgage finance from Egypt's Mortgage Finance Fund is compressing purchase timelines for first-time buyers while simultaneously inflating developer working-capital requirements through presale dependency.
Growth Catalysts
- Mortgage Finance Fund Subsidized Lending:The authority's below-market rate programs expand qualified buyer pools in Greater Cairo. Monthly payment-to-income ratios improve meaningfully for public-sector employees.
- New Urban Communities Authority Land Releases:Systematic parcel allocation in New Administrative City and 6th of October corridor enables scaled township development. Developer site access accelerates project pipeline formation.
- Seismic Zone 2B Compliance Standards:Reinforced masonry infill and concrete-frame specifications mandated by the Housing and Building National Research Center upgrade structural resilience. Buyer confidence in off-plan purchases strengthens accordingly.
Market Restraints
- Imported Construction Material Cost Volatility:Steel rebar and aluminum window systems denominated in foreign currency expose project margins to exchange-rate fluctuation. Developer pricing power erodes during EGP depreciation cycles.
- Concentrated Developer Land Banking:Legacy site accumulation by established players limits competitive entry for mid-tier developers without New Urban Communities Authority allocation history. Site scarcity inflates land-acquisition premiums.
- Mortgage Loan-to-Value Caps:Central Bank of Egypt limits on maximum financing ratios require substantial buyer equity contributions. Liquidity-constrained households face extended savings periods.
Strategic Opportunities
- North Coast Villa Segment:Mediterranean-facing compounds in New Alamein attract Gulf capital seeking second-home exposure. Foreign buyer transaction structures bypass domestic mortgage constraints.
- Integrated Township Development:Mixed-use master planning combining residential, retail, and educational facilities commands premium absorption rates. Talaat Moustafa Group's execution model demonstrates scalability.
- Mortgage Securitization Expansion:Secondary market instruments for pooled home loans deepen institutional investor participation. Long-term capital inflows reduce developer construction-finance dependence.
Industry Challenges
- Project Management Expertise Scarcity:Complex phased delivery of multi-year township developments exceeds capabilities of traditional contractor networks. Qualified development managers command premium compensation.
- Off-Plan Buyer Protection Compliance:Escrow account enforcement and construction-milestone verification require enhanced legal frameworks. Regulatory lag creates developer-buyer trust deficits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Residential Real Estate Market |
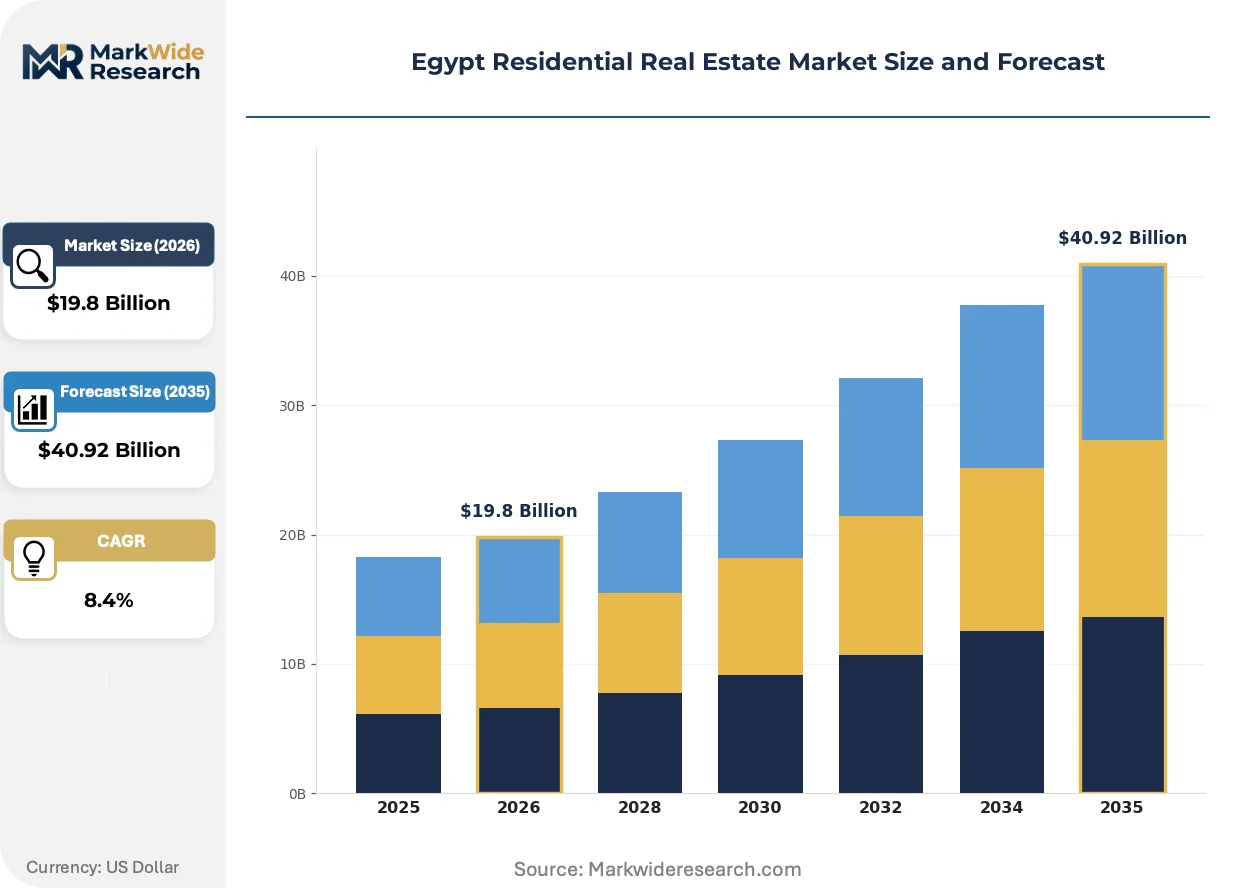
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $40.92 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Apartments, Villas, Townhouses, Studios Investment Type: Buy-to-Let, Long-Term Investment, Renewal Projects, Off-Plan Properties Price Tier: Luxury, Mid-Range, Affordable, Budget Target Buyer: First-Time Buyers, Investors, Foreign Buyers, Retirees |
| Companies Covered | Emaar Misr, Rock Developments, Talaat Moustafa Group (TMG), Hyde Park Developments, Hassan Allam Properties, Orascom Development, SODIC, Tatweer Misr, Palm Hills Developments, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Residential Real Estate Market Shifts & Advancements
Digital transaction infrastructure and energy-efficiency mandates are restructuring how Egyptian residential properties are marketed, financed, and constructed across income tiers.
Building Information Modeling software is digitizing design-to-construction workflows for master-planned communities in New Cairo. Mid-scale developers adopting these platforms compress project timelines by enabling clash detection before ground-breaking. The technology is digitizing coordination between structural engineers and MEP contractors, reducing on-site rework incidence.
Egypt's Mortgage Finance Fund has expanded eligibility criteria for subsidized-rate programs to informal-sector workers with documented payment histories. The policy shift broadens addressable demand beyond salaried public and private employees. First-time buyer segments in 6th of October and Sheikh Zayed are responding with accelerated pre-qualification applications.
Buyer preference is migrating toward gated compounds with embedded retail and educational facilities rather than standalone apartment towers. Young professional households in Greater Cairo prioritize time-saving convenience over pure unit economics. This behavioral pivot is most visible in New Administrative City, where integrated township pre-sales outpace conventional apartment project absorption.
Egypt Residential Real Estate Market Segmentation
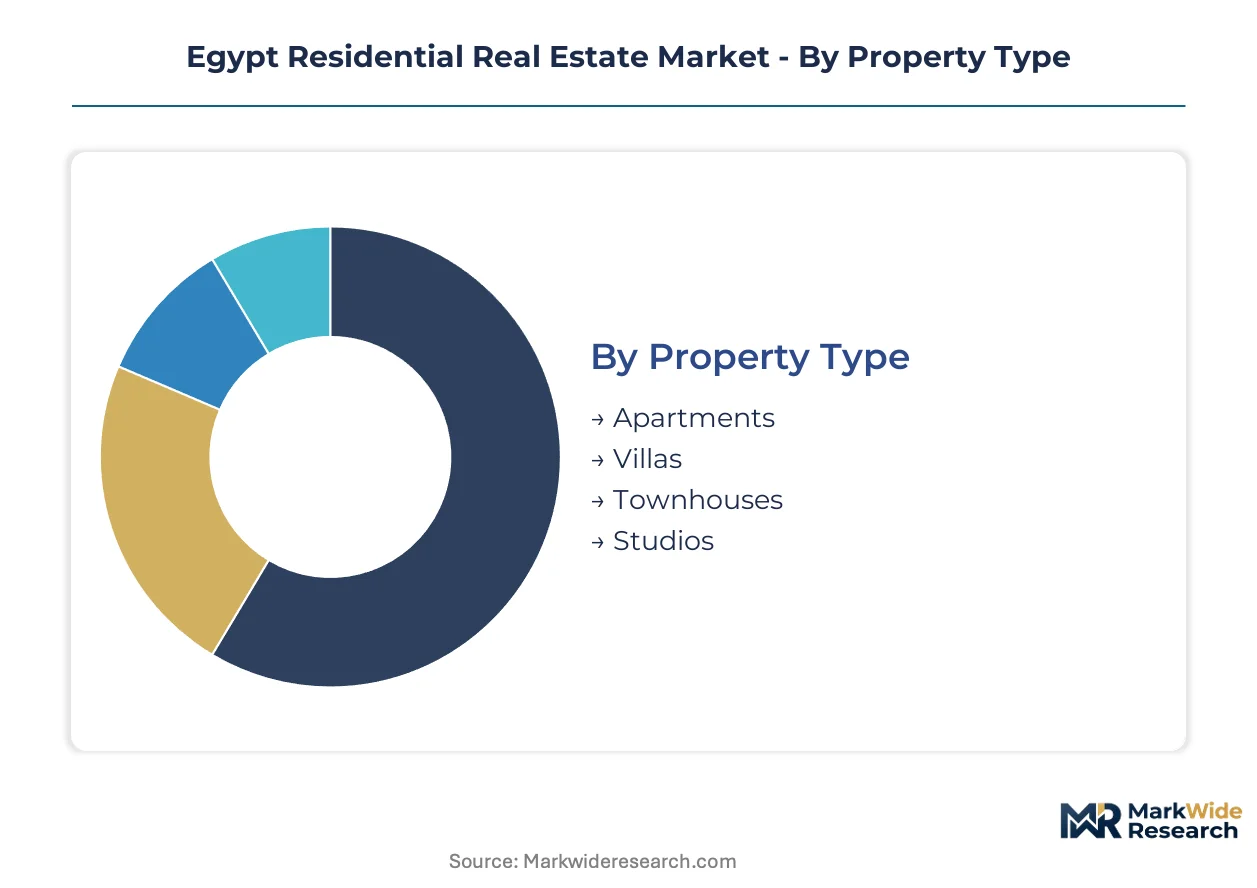
Egypt's residential market fragments across four structural dimensions that determine developer positioning and buyer access. Property type and price tier govern construction economics, while investment type and target buyer shape financing structures and absorption velocity.
Property Type:
Turnover velocity varies dramatically across dwelling formats, with compact units transacting fastest and villa compounds requiring extended marketing cycles.
- Apartments:Concrete-frame construction with reinforced masonry infill dominates Cairo and Alexandria transaction volumes. Demand concentrates in 6th of October and Sheikh Zayed where Mortgage Finance Fund subsidies reach salaried professionals most efficiently.
- Villas:Mediterranean-facing compounds in New Alamein attract Gulf capital seeking second-home exposure. Foreign buyer transaction structures bypass domestic mortgage constraints entirely, insulating this segment from Central Bank of Egypt LTV caps.
- Townhouses:Hybrid format gaining traction in New Cairo's integrated townships where young professional households prioritize embedded retail and educational facilities.
- Studios:Compact units in Greater Cairo's eastern periphery serve entry-level buyers with constrained equity contributions.
Apartments anchor the volume base while villas gain share at the steepest rate.
Investment Type:
Capital deployment horizons separate passive income seekers from speculative buyers betting on construction-phase appreciation.
- Off-Plan Properties:Presale structures allow developers to fund construction without full project finance, making this the fastest-expanding investment category. Buyer confidence strengthens as Housing and Building National Research Center seismic compliance standards harden structural resilience.
- Buy-to-Let:Rental income strategies concentrate in New Administrative City where government employee housing allowances sustain tenant pools.
- Long-Term Investment:Hold periods extending beyond five years dominate villa purchases along the North Coast.
- Renewal Projects:Urban regeneration in older Cairo districts attracts specialized developers with contractor network capabilities for complex phased delivery.
Off-plan properties command the steepest expansion trajectory as developer working-capital requirements deepen presale dependency.
Price Tier:
Margin structures stratify sharply, with luxury segments capturing concentrated profit pools and affordable tiers depending on subsidy program access.
- Mid-Range:Absorbs the bulk of first-time buyer demand across Greater Cairo. Talaat Moustafa Group's integrated township model demonstrates scalability at this tier.
- Luxury:Premium compounds in New Alamein compete on Mediterranean exposure and finish quality rather than price alone.
- Affordable:Mortgage Finance Fund subsidized lending programs expand qualified buyer pools most meaningfully at this tier.
- Budget:Informal-sector workers with documented payment histories drive recent eligibility expansion by the Mortgage Finance Fund.
Mid-range units generate the volume foundation while luxury segments climb fastest on Gulf capital inflows.
Target Buyer:
Customer acquisition economics diverge between domestic households navigating mortgage complexity and foreign purchasers transacting in hard currency.
- First-Time Buyers:Public-sector employees in Greater Cairo respond most aggressively to below-market rate programs. Monthly payment-to-income ratios improve meaningfully for this cohort.
- Foreign Buyers:Gulf capital seeking Mediterranean exposure bypasses domestic mortgage constraints entirely. New Alamein compounds tailor transaction structures to this segment.
- Investors:Portfolio buyers concentrate in off-plan presales where construction-phase appreciation offers leveraged returns.
- Retirees:Downsizing demand from older households concentrates in gated compounds with embedded healthcare and retail facilities.
First-time buyers sustain transaction velocity while foreign buyers expand most quickly on currency-advantaged purchasing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Subsidized mortgage finance from Egypt's Mortgage Finance Fund is compressing purchase timelines for first-time buyers while simultaneously inflating developer working-capital requirements through presale dependency. Demand concentrates in Greater Cairo's eastern periphery and Mediterranean coastal corridors where government land allocation policies enable scaled township development.
Greater Cairo
New Cairo and 6th of October corridor developments absorb the bulk of first-time buyer demand as Mortgage Finance Fund subsidies reach salaried professionals most efficiently. The New Urban Communities Authority's systematic parcel allocation in New Administrative City accelerates project pipeline formation for developers with established allocation history. Emaar Misr and Talaat Moustafa Group anchor supply through master-planned community execution across Cairo's eastern periphery.
Alexandria
Concrete-frame apartment construction dominates transaction volumes in Egypt's second-largest metropolitan market. Central Bank of Egypt loan-to-value caps constrain buyer purchasing power less severely here due to lower absolute price points compared to Greater Cairo. Mediterranean-facing compounds along the Corniche attract downsizing demand from retiree households seeking embedded healthcare and retail facilities.
North Coast
New Alamein compounds command concentrated margin pools as Gulf capital seeking second-home exposure bypasses domestic mortgage constraints entirely. Foreign buyer transaction structures denominated in hard currency insulate developers from EGP depreciation cycles affecting imported construction materials. Luxury villa segments here climb fastest on currency-advantaged purchasing power from Saudi and UAE investors.
Red Sea Corridor
Hurghada and Sharm El-Sheikh residential developments pivot toward rental-income strategies serving European tourist demand. The Housing and Building National Research Center's seismic Zone 2B compliance standards harden structural resilience for off-plan buyer confidence. Specialized developers with contractor network capabilities for complex phased delivery concentrate supply in this tourism-dependent sub-market.
Upper Egypt
Affordable tier demand in Luxor and Aswan expands as Mortgage Finance Fund eligibility criteria broaden to informal-sector workers with documented payment histories. Site scarcity and limited New Urban Communities Authority allocation history restrict competitive entry for mid-tier developers. Local contractors execute smaller-scale concrete-frame construction without the master-planned community economics viable in Greater Cairo.
Egypt Residential Real Estate Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Egypt's residential real estate market. Established developers with legacy land banks from New Urban Communities Authority allocations dominate site access, while design-led specialists compete on finish quality rather than price alone. Three archetypes define competitive positioning: master-planned community scale players, integrated township developers, and mid-range compound specialists. Dominant competitive moves include mortgage securitization partnerships to reduce construction-finance dependence and backward integration into construction management capabilities.
Within the master-planned community tier, Emaar Misr and Talaat Moustafa Group exemplify scale-driven execution models. Emaar Misr occupies a position anchored in premium positioning across Cairo's eastern periphery. Talaat Moustafa Group represents the integrated township archetype through mixed-use master planning combining residential, retail, and educational facilities. SODIC sits within the design-led specialist category, competing on finish quality in mid-range compounds.
| Leading Market Players |
|---|
| Emaar Misr |
| Rock Developments |
| Talaat Moustafa Group (TMG) |
| Hyde Park Developments |
| Hassan Allam Properties |
| Orascom Development |
| SODIC |
| Tatweer Misr |
| Palm Hills Developments |
| Others |
Supply & Pricing Matrix
Overcapacity in Egypt's cement sector compresses input costs for concrete-frame construction while simultaneously pressuring developer margins through competitive project bidding. This utilization dynamic shapes both supplier payment-term negotiations and buyer pricing power across Greater Cairo's residential pipeline.
Pricing Analysis
Finish quality and seismic certification grade create the primary spread between mid-range compounds and premium gated communities in New Cairo. Three-tier pricing structure across luxury, mid-market, and affordable levels reflects embedded retail and educational amenity bundling rather than unit economics alone. Cost compression in the affordable tier intensifies as Mortgage Finance Fund subsidies cap achievable price points. First-time buyers in 6th of October demonstrate highest price sensitivity, while Gulf capital in New Alamein exhibits minimal elasticity.
Supply Chain Analysis
Extended payment terms from steel rebar distributors now stretch to 90-120 days as liquidity constraints ripple through contractor networks. Manufacturing concentration in Turkey, China, and Saudi Arabia for aluminum window systems and HVAC equipment exposes developers to EGP depreciation cycles. Supply chain risk centers on single-source vulnerability for seismic-grade reinforcement bars certified by the Housing and Building National Research Center. Distribution runs through developer-procurement teams with direct contractor relationships rather than third-party logistics platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's residential market fragments across income tiers and geographic corridors, creating niches for specialized positioning as first-time buyer demand diversifies beyond salaried public-sector employees.
For Market Incumbents: Harden escrow account compliance capabilities to preempt regulatory enforcement lag in off-plan sales. Anchor land-bank renewal through New Urban Communities Authority allocation history while backward integration into construction management reduces contractor network dependence. Threat of mid-tier developers accessing mortgage securitization partnerships demands accelerated scale deployment in integrated townships. For New Entrants and Emerging Players: Upper Egypt's affordable tier presents the most penetrable geography given limited legacy developer presence in Luxor and Aswan corridors. Target informal-sector workers newly eligible for Mortgage Finance Fund subsidies with compact studio formats requiring minimal equity contributions. Go-to-market execution should emphasize documented payment-history verification partnerships with mobile money platforms. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across master-planned community developments as phased infrastructure requirements deepen working-capital demands. Acquisition targets should display proven township execution capabilities with embedded retail and educational facilities generating recurring revenue streams. Monitor Mortgage Finance Fund subsidy expansion rates as the inflection signal for addressable demand growth.| Strategic Initiative | Industry Significance |
|---|---|
| Mortgage Securitization Partnership | Pooled home loan instruments attract institutional capital reducing developer construction-finance dependence. |
| Integrated Township Development | Mixed-use master planning commands premium absorption rates through embedded retail and educational facilities. |
| Backward Integration into Construction Management | In-house project delivery capabilities address qualified development manager scarcity in complex phased developments. |
| Escrow Account Infrastructure Investment | Enhanced buyer protection compliance preempts regulatory enforcement lag in off-plan transaction structures. |
| North Coast Foreign Buyer Transaction Structuring | Hard-currency denominated sales to Gulf capital bypass Central Bank of Egypt LTV constraints entirely. |
Research Methodology
The analysis maps property type segments, price tier stratifications, and regional demand corridors, each validated through primary interviews with development executives, mortgage finance officers, New Urban Communities Authority planners, and contractor network managers. Secondary validation draws from Central Bank of Egypt regulatory filings, Mortgage Finance Fund disbursement records, Housing and Building National Research Center compliance databases, and New Urban Communities Authority land allocation registers. Bottom-up project pipeline enumeration triangulates against top-down macroeconomic demand modeling.
Forecast assumptions hold fixed current Mortgage Finance Fund subsidy eligibility criteria and Central Bank of Egypt LTV caps while varying EGP exchange rate trajectories and construction material import cost scenarios across the analysis window. Segmentation dimensions modeled include property type, price tier, investment type, and target buyer archetype alongside regional absorption velocity differentials. CAGRs derive from unit completion forecasts cross-referenced with mortgage origination growth patterns and informal-sector employment documentation expansion.
Practitioners should monitor currency fluctuation magnitude and mortgage subsidy program expansion velocity for early signals of demand inflection. Forecasts reflect assumptions regarding sustained New Urban Communities Authority land release schedules and stable seismic compliance enforcement. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
Armenia Real Estate Market
Residential Real Estate Market
Indonesia Residential Real Estate Market
Residential Real Estate Market
Turkey Residential Real Estate Market
Residential Real Estate Market
Qatar Residential Real Estate Market
Residential Real Estate Market
Global Log Cabins or Log Homes Market
Residential Real Estate Market
France Condominiums and Apartments Market
Residential Real Estate Market
Singapore Real Estate Market
Residential Real Estate Market
Indonesia Real Estate Market
Residential Real Estate Market
UK Real Estate Market
Residential Real Estate Market
Global Manufactured Housing Market
Residential Real Estate Market
Malaysia Residential Real Estate Market
Residential Real Estate Market
North America Tiny Homes Market
Residential Real Estate Market
Canada Residential Real Estate Market
Residential Real Estate Market
E House Market
Residential Real Estate Market
Spain Manufactured Homes Market
Residential Real Estate Market
France Residential Real Estate Market