
 Asia Pacific Brachytherapy Devices Market | 2026-2036
Asia Pacific Brachytherapy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Brachytherapy Devices Market Outlook
Modular afterloader system configurations is realigning procurement patterns across Asia Pacific cancer centers. Varian Medical Systems leverages integrated software-hardware bundles to anchor its position in Australian and Japanese tertiary hospitals. Elekta AB competes through specialized HDR workflow platforms that dominate Nordic-influenced clinical protocols in the region. Shanghai Atom High-Tech sustains cost-engineered LDR seed production that occupies the mid-tier hospital segment in China and Southeast Asia.
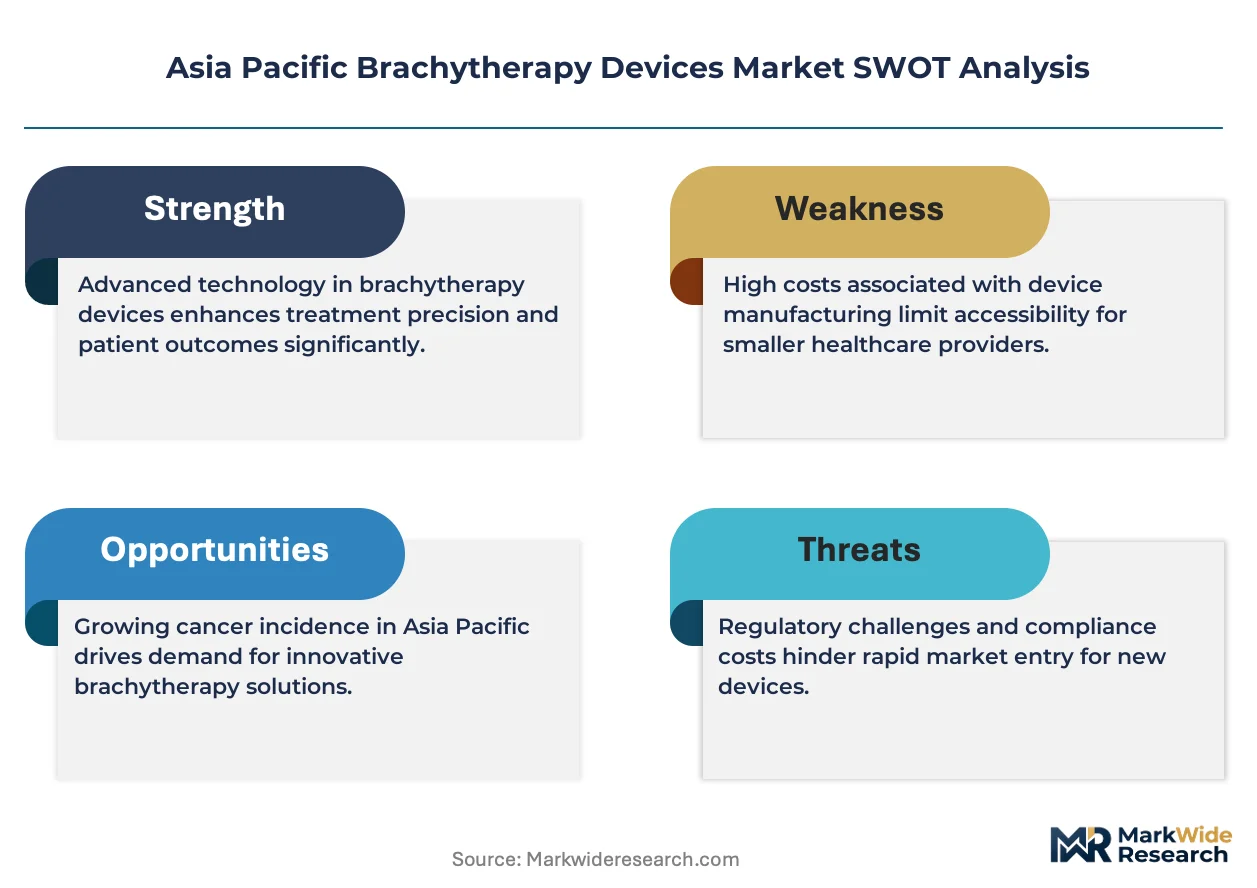
Brachytherapy devices deliver sealed radioactive sources directly into or adjacent to tumor tissue through catheters, applicators, or implanted seeds, with dose rates typically calibrated between 0.4 Gy/hour for LDR and above 12 Gy/hour for HDR systems. These instruments enable conformal radiation delivery that spares surrounding healthy tissue in prostate, cervical, and breast malignancies. Afterloader devices command the strongest margin pools due to capital intensity and recurring source replacement revenue, while seed implants generate volume leadership through single-use disposability and expanding prostate cancer protocols. High Dose Rate technique adoption outpaces Low Dose Rate across tertiary centers seeking shorter patient throughput cycles and reduced hospitalization.
Japan's PMDA enforces JIS-compliant source encapsulation standards that elevate manufacturing compliance costs for foreign entrants. Australia's TGA aligns with ISO 2919 for sealed source classification, creating harmonized but stringent quality gates across the developed Asia Pacific perimeter. India's CDSCO has issued draft guidance on brachytherapy source import licensing that will reshape supply chain registration requirements. Stakeholders must monitor how China's NMPA integrates GB standards with international source traceability protocols as domestic production scales.
Market Dynamics
Modular afterloader configurations are restructuring procurement patterns across Asia Pacific oncology centers, as hospitals prioritize capital-efficient HDR platforms that reduce patient throughput cycles while maintaining JIS and GB compliance for radioactive source handling.
Growth Catalysts
- Cervical cancer protocols:Rising incidence across India and Southeast Asia drives installation of HDR afterloaders in tier-two hospital networks.
- PMDA source encapsulation standards:Japan's tightened quality benchmarks create upgrade cycles for legacy LDR systems in tertiary centers.
- Prostate seed implants:China's NMPA streamlined registration pathways accelerate domestic production scaling for cost-engineered LDR devices.
Market Restraints
- Iridium-192 source volatility:Supply concentration in Russian and South African enrichment facilities exposes afterloader operators to price swings and shipment delays.
- CDSCO import licensing:India's draft guidance on brachytherapy source registration extends approval timelines for foreign manufacturers.
- Technical staffing gaps:Qualified medical physicists and radiation safety officers remain scarce across Vietnam, Indonesia, and Philippines hospital systems.
Strategic Opportunities
- Vietnam and Philippines:Underpenetrated radiation oncology infrastructure presents first-mover positioning for HDR platform vendors.
- TGA-ISO harmonization:Australia's alignment with international sealed source standards reduces compliance duplication for suppliers targeting developed Asia Pacific markets.
- AI-driven treatment planning:Convergence of machine learning algorithms with HDR workflow software compresses dosimetry calculation cycles in Japanese and Australian centers.
Industry Challenges
- Medical physicist certification:Extended training periods and emigration of qualified staff to Gulf markets strain operational capacity in Indian and Southeast Asian clinics.
- Legacy LDR integration:Hybrid facilities face workflow friction when combining permanent seed programs with temporary HDR catheter protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Brachytherapy Devices Market |
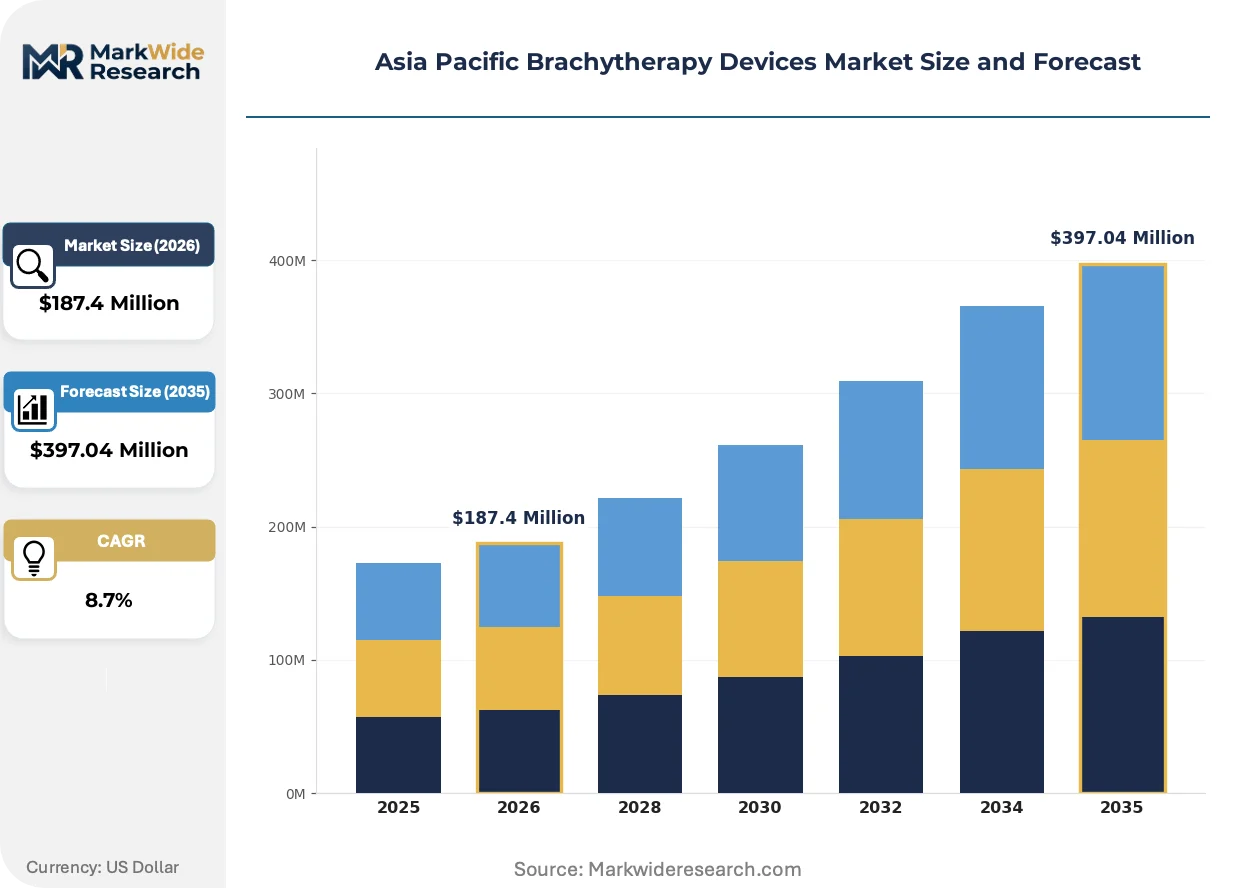
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seed Implants, Afterloader Devices, Catheters, Applicators End User: Hospitals, Oncology Clinics, Research Institutions, Home Care Technique: High Dose Rate, Low Dose Rate, Pulsed Dose Rate, Intracavitary Material: Gold, Titanium, Plastics, Others |
| Companies Covered | Varian Medical Systems, Elekta AB, Eckert & Ziegler, Becton Dickinson and Company, IsoRay Medical, Theragenics Corporation, Shanghai Atom High-Tech, Best Medical International, C-RAD AB, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Brachytherapy Devices Market Strategic Shifts
Digital integration and source traceability protocols are redefining competitive positioning across Asia Pacific brachytherapy supply chains. Three developments warrant particular attention.
Robotic applicator positioning systems are expanding into Australian and Japanese tertiary hospitals, where sub-millimeter placement accuracy reduces rectal toxicity in prostate treatments. Urology and gynecology departments in Sydney, Melbourne, and Osaka academic medical centers have adopted these platforms at accelerated procurement cycles. The technology is expanding into mid-tier Chinese hospitals as NMPA clears domestically manufactured equivalents.
Japan's PMDA revised its sealed source encapsulation guidelines to incorporate real-time temperature monitoring during transport, elevating cold-chain compliance costs for foreign afterloader suppliers. Domestic Japanese manufacturers have absorbed these requirements through captive logistics networks. Australian importers now face parallel TGA documentation demands, compressing margins for smaller distributors.
Hospital procurement committees across China and India now unbundle afterloader hardware from proprietary software licenses, favoring open-architecture platforms that permit third-party treatment planning integration. This pattern disrupts traditional bundled pricing models in Shanghai and Beijing hospital networks. Radiation oncology departments in Mumbai and Delhi private hospital chains have replicated this approach, pressuring incumbent vendors to decouple service contracts from capital sales.
Asia Pacific Brachytherapy Devices Market Segmentation
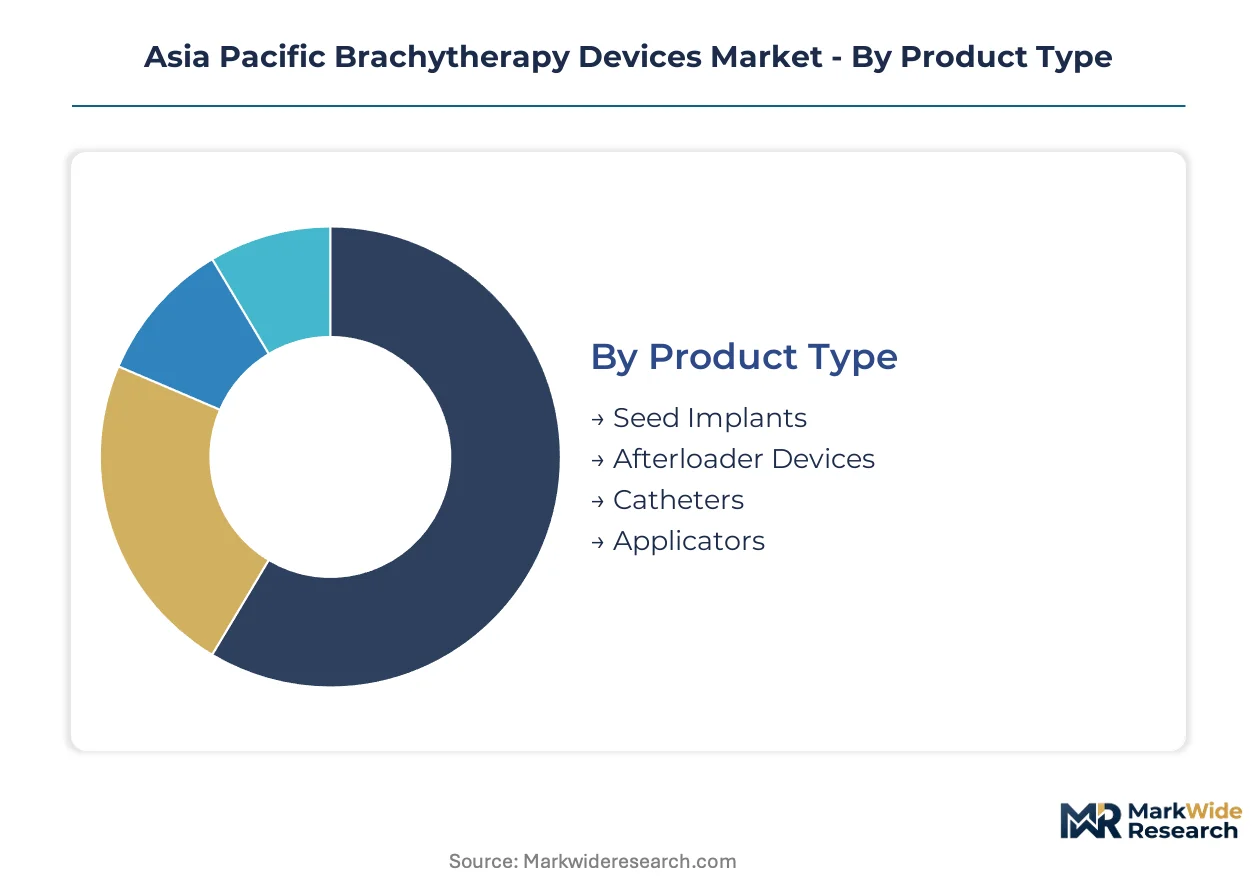
Brachytherapy device segmentation reveals distinct margin structures and procurement patterns across Asia Pacific cancer centers. Supply concentration in afterloader systems contrasts with commoditized seed implant volumes, while technique selection determines hospital workflow design and physicist staffing requirements.
Product Type:
Afterloader systems concentrate manufacturing among specialized radiation equipment suppliers serving tertiary hospital networks across Japan, Australia, and China.
- Seed Implants:Permanent radioactive sources—typically iodine-125 or palladium-103—delivered via transperineal needle insertion for prostate malignancies. China's NMPA streamlined domestic registration pathways accelerate cost-engineered production scaling for mid-tier hospital procurement in Shanghai and Beijing networks.
- Afterloader Devices:Motorized systems that remotely position Iridium-192 sources through catheters with dose rates exceeding 12 Gy/hour. Japanese tertiary centers and Australian academic hospitals anchor demand for HDR platforms that reduce patient throughput cycles while maintaining PMDA and TGA compliance standards.
- Catheters:Flexible delivery channels constructed from biocompatible polymers for temporary source positioning.
- Applicators:Rigid intracavitary instruments designed for gynecologic and rectal tumor access.
Afterloader devices absorb the bulk of installed capacity; seed implants are expanding most quickly across China's tier-two hospital networks.
End User:
Procurement authority concentrates in hospital radiation oncology departments with dedicated medical physics support and radioactive materials licenses.
- Hospitals:Comprehensive cancer centers with multidisciplinary tumor boards and captive brachytherapy suites. China's tier-one hospital networks in Beijing, Shanghai, and Guangzhou drive capital expenditure for HDR platform upgrades as cervical and prostate cancer caseloads climb.
- Oncology Clinics:Specialized outpatient facilities focused on radiation therapy delivery. India's private clinic chains in Mumbai and Delhi expand LDR seed implant capacity for prostate protocols, though CDSCO import licensing delays constrain foreign afterloader deployment.
- Research Institutions:Academic medical centers conducting clinical trials and dosimetry protocol development.
- Home Care:Limited to post-implant patient monitoring and palliative pain management support.
Hospitals command the dominant share of capital equipment procurement; oncology clinics show the steepest expansion trajectory for high-volume LDR procedures.
Technique:
Clinical workflow efficiency and hospitalization duration differentiate technique selection across developed and emerging Asia Pacific markets.
- High Dose Rate:Delivers concentrated radiation doses in minutes through remote afterloader systems. Australian and Japanese tertiary centers prioritize HDR adoption to compress treatment schedules and reduce inpatient bed utilization for cervical and breast malignancies.
- Low Dose Rate:Sustained dose delivery over hours or days via permanent seed implants or temporary catheter placement. China's domestic manufacturers dominate cost-optimized LDR seed production for prostate cancer protocols in mid-tier provincial hospitals.
- Pulsed Dose Rate:Intermittent source positioning that mimics LDR biological effectiveness with HDR equipment flexibility.
- Intracavitary:Direct tumor cavity source placement for gynecologic and nasopharyngeal applications.
High Dose Rate systems anchor revenue concentration in developed markets; Low Dose Rate seed implants gain share fastest across India's expanding private oncology infrastructure.
Material:
Encapsulation material selection balances radiopacity requirements, biocompatibility certification, and manufacturing cost structures.
- Gold:Dense radiopaque marker construction enabling fluoroscopic visualization during transperineal seed placement. Japanese PMDA encapsulation standards elevate gold seed manufacturing compliance costs, favoring domestic suppliers with captive JIS-certified production lines.
- Titanium:Lightweight corrosion-resistant encapsulation for permanent implants with reduced artifact generation in MRI surveillance. Australian clinics specify titanium-clad sources to align with TGA-ISO harmonized quality benchmarks for long-term biocompatibility.
- Plastics:Biocompatible polymers for catheter and applicator construction with disposable single-use economics.
- Others:Specialty alloys and composite materials for niche clinical applications.
Gold encapsulation dominates premium seed production; titanium sources are climbing the fastest as MRI-compatible surveillance protocols expand across Australian and Japanese treatment centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates domestic manufacturing capacity for LDR seed production while Japan and Australia import premium HDR afterloader systems. India bridges both consumption patterns with expanding oncology infrastructure. Southeast Asian markets remain dependent on foreign equipment supply chains.
China
Cervical and prostate cancer caseloads drive tier-one hospital procurement of HDR platforms in Beijing, Shanghai, and Guangzhou. NMPA streamlined registration pathways accelerate domestic production scaling for cost-engineered LDR devices. Shanghai Atom High-Tech anchors mid-tier seed manufacturing for provincial hospital networks across the Yangtze River Delta.
Japan
PMDA-enforced JIS encapsulation standards elevate compliance costs for foreign afterloader suppliers entering tertiary centers. Aging demographics expand prostate and breast malignancy treatment volumes requiring precision brachytherapy delivery. Osaka and Nagoya academic medical centers prioritize robotic applicator adoption for sub-millimeter placement accuracy.
India
Private oncology clinic chains in Mumbai and Delhi expand LDR seed implant capacity for prostate protocols. CDSCO draft guidance on brachytherapy source import licensing extends approval timelines for foreign manufacturers. Tier-two hospital networks in Bangalore and Hyderabad install first-generation HDR afterloaders as cervical cancer incidence climbs.
Australia
TGA alignment with ISO 2919 sealed source classification reduces compliance duplication for equipment suppliers. Tertiary centers in Sydney and Melbourne compress patient throughput cycles through HDR adoption for breast and gynecologic malignancies. Robotic positioning systems penetrate academic medical centers at accelerated procurement rates.
Vietnam
Underpenetrated radiation oncology infrastructure creates first-mover positioning opportunities for HDR platform vendors. Technical staffing gaps in medical physics and radiation safety constrain operational capacity in Ho Chi Minh City and Hanoi hospital systems. Foreign equipment suppliers navigate extended import licensing procedures through the national pharmaceutical regulator.
Asia Pacific Brachytherapy Devices Market Competitive Environment
The competitive structure tilts toward integrated radiation therapy specialists with captive software-hardware ecosystems. Varian Medical Systems and Elekta AB anchor premium-tier positioning through bundled afterloader platforms serving Japanese and Australian tertiary centers. Three archetypes dominate: multinational radiation equipment conglomerates with proprietary treatment planning ecosystems, regional cost-engineered device fabricators serving mid-tier hospital procurement, and specialized radioisotope suppliers controlling source enrichment and encapsulation. Capacity expansion and strategic partnerships represent the dominant competitive vectors as vendors seek to secure Iridium-192 supply chains and localize manufacturing within China and India.
Among multinational radiation equipment suppliers, Varian Medical Systems exemplifies the integrated software-hardware archetype anchoring premium positioning in developed Asia Pacific markets. Elekta AB occupies a parallel tier through specialized HDR workflow platforms. Shanghai Atom High-Tech represents the cost-engineered domestic manufacturer archetype, sustaining mid-tier penetration across Chinese provincial hospital networks and Southeast Asian expansion markets.
| Leading Market Players |
|---|
| Varian Medical Systems |
| Elekta AB |
| Eckert & Ziegler |
| Becton Dickinson and Company |
| IsoRay Medical |
| Theragenics Corporation |
| Shanghai Atom High-Tech |
| Best Medical International |
| C-RAD AB |
| Others |
Value Chain & Pricing Dynamics
Iridium-192 spot price volatility cascades through afterloader system pricing tiers, compressing margins for HDR platform vendors serving Japanese and Australian tertiary hospitals while amplifying cost advantages for Chinese domestic LDR seed manufacturers with captive isotope sourcing.
Pricing Analysis
Margin tightening in premium-tier afterloader systems reflects JIS and TGA compliance cost absorption by foreign suppliers competing against bundled software-hardware offerings. Three-tier pricing structure across premium, standard, and economy levels separates PMDA-certified HDR platforms from CDSCO-registered mid-tier devices and NMPA-domesticated LDR seeds. Cost-down pressure on economy-tier seed implants accelerates because Shanghai Atom High-Tech scales provincial hospital penetration. Oncology clinics in India's private chains exhibit highest price sensitivity; Japanese academic medical centers demonstrate lowest sensitivity due to robotic applicator precision requirements.
Supply Chain Analysis
Direct-to-hospital channels dominate HDR afterloader procurement in Australian and Japanese tertiary centers, while distributor networks handle LDR seed distribution across China's tier-two provincial hospitals. Iridium-192 enrichment concentrates in Russian and South African facilities; gold and titanium encapsulation materials draw from Australian mining outputs and Chinese refining capacity. Single-source vulnerability in radioisotope supply exposes afterloader operators to shipment delays and quota restrictions. Distribution runs through specialized medical device logistics providers with radioactive materials handling certifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific brachytherapy devices consolidation accelerates as PMDA and NMPA regulatory compliance costs force sub-scale foreign entrants toward exit or acquisition, concentrating procurement authority among integrated radiation therapy specialists with captive software ecosystems.
For Market Incumbents: To counter unbundling pressure from Chinese and Indian hospital procurement committees, Varian Medical Systems and Elekta AB should deepen backward integration into proprietary treatment planning software development while expanding service contract anchoring in Australian and Japanese academic centers. Certification investment in GB standards compliance secures NMPA pathway access for mid-tier platform localization. For New Entrants and Emerging Players: Regional distributors with radiation oncology specialization represent the most viable channel partner type for penetrating Vietnam and Philippines underpenetrated hospital networks. White-space targets include HDR afterloader deployment in Ho Chi Minh City and Hanoi where technical staffing gaps constrain incumbent expansion, plus robotic applicator positioning systems for mid-tier Chinese hospitals seeking NMPA-cleared domestic equivalents. For Investors and Strategic Acquirers: Distressed-cycle entries favor cost-engineered LDR seed manufacturers with NMPA registration and provincial hospital contracts in China's Yangtze River Delta region. Long-term viability hinges on securing Iridium-192 supply agreements or alternative isotope sourcing before enrichment facility concentration tightens further. Monitor CDSCO final guidance on brachytherapy source import licensing for Indian market access inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA JIS Certification Investment | Foreign afterloader vendors absorb compliance costs to maintain Japanese tertiary hospital positioning against domestic competitors. |
| Backward Integration into Treatment Planning Software | Integrated software-hardware bundles defend margin pools against procurement committee unbundling pressure in China and India. |
| Provincial Hospital Network Partnerships | Mid-tier LDR seed penetration in China's tier-two cities builds volume leadership through cost-engineered domestic production scaling. |
| Robotic Applicator Regulatory Clearance | NMPA approval for sub-millimeter positioning systems opens mid-tier Chinese hospital segments previously reserved to Japanese and Australian academic centers. |
| Iridium-192 Supply Agreement Securement | Long-term offtake contracts with Russian and South African enrichment facilities hedge against radioisotope shipment delays and quota volatility. |
Study Parameters
Multi-period observation of HDR afterloader installation rates, LDR seed procurement volumes, and regulatory submission timelines anchored the trend analysis, supplemented by interviews with radiation oncology department heads, hospital biomedical engineers, GPO contracts managers, and medical physicists across China, Japan, India, and Australia. Secondary validation drew from PMDA medical device filings, NMPA registration databases, TGA therapeutic goods approvals, CDSCO draft guidance documents, and hospital procurement platform disclosures. Bottom-up facility-level capacity tracking triangulated against top-down manufacturer shipment data.
Segment-weighting across product type, technique, end user, and material dimensions structured the analytical framework, with CAGRs derived from logistic adoption curve modeling calibrated to cervical and prostate cancer incidence trajectories. Technique transition assumptions from LDR to HDR incorporated patient throughput cycle compression targets and inpatient bed utilization metrics from Japanese and Australian tertiary centers. Radioisotope supply constraints and regulatory approval timeline distributions informed scenario-boundary sensitivity testing throughout the projection horizon.
Caveats apply where PMDA encapsulation standard revisions, CDSCO import licensing finalization, or Iridium-192 supply disruptions could materially shift the outlook. Forecasts embed assumptions regarding medical physicist training pipeline expansion and NMPA domestic production incentive continuity. Practitioners should monitor cervical cancer protocol adoption rates in India's tier-two hospital networks and robotic applicator NMPA clearance velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Spinal Traction Market
Medical Devices
Italy Ophthalmic Devices Market
Medical Devices
Global Extracorporeal Shock Wave Lithotripsy Market
Medical Devices
Global Cardiac Prosthetic Devices Market
Medical Devices
Fluid and Blood Warmer Market
Medical Devices
Global Spirometers Market
Medical Devices
Gamma Knife Market
Medical Devices
Global Coronary Artery Bypass Graft Devices Market
Medical Devices
Global Wearable Pregnancy Devices Market
Medical Devices
Disabled and Elderly Assistive Technologies Market
Medical Devices
Ventilator Accessories Market
Medical Devices
Public Access Automated External Defibrillators (Aeds) Market
Medical Devices
Computer-Aided Oral and Maxillofacial Surgery Market
Medical Devices
Global Anesthesia Gas Blender Market
Medical Devices
Arthroscopy Visualization Systems Market
Medical Devices
North America Smart Medical Devices Market