
 Walkers and Rollators Market | 2026-2036
Walkers and Rollators Market Size, Share, and Industry Trends Forecast 2026-2036
Walkers and Rollators Market Analysis
The EU Medical Device Regulation (MDR) is restructuring compliance obligations for walker and rollator manufacturers selling into European markets. Drive DeVilbiss Healthcare leverages extensive distribution networks across North America and Europe to sustain market presence. Graham Field anchors its competitive position through durable medical equipment specialization and long-standing relationships with institutional buyers. TOPRO competes on Scandinavian design heritage and premium positioning in European homecare channels.
Walkers and rollators are ambulatory assistive devices constructed from aluminum tubing, steel framing, or polymer composites, typically incorporating handgrips, braking mechanisms, and optional seating surfaces to support individuals with compromised gait stability. Rollator walkers integrate four wheels with hand-operated brakes and foldable frames, commanding higher average selling prices than standard walkers due to added functionality and user independence. Aluminum construction dominates material segmentation owing to its strength-to-weight ratio and corrosion resistance, while senior citizens represent the largest end-user category as demographic aging accelerates across developed economies. Integrated seats and adjustable height features are gaining preference in long-term care facilities seeking to reduce fall incidents and staff assistance demands.
FDA 510(k) clearance requirements and ISO 11199-2 standards for rollator stability govern product entry and safety benchmarks in the United States, while the EU MDR mandates notified body certification and post-market surveillance for CE-marked devices. Japan's Ministry of Health, Labour and Welfare (MHLW) classifies these products as designated medical devices, requiring in-country testing and quality system registration for reimbursement eligibility. Stakeholders must monitor evolving reimbursement thresholds and home-based care policy shifts that will determine volume access across Medicare, statutory health insurance, and long-term care insurance programs.
Market Dynamics
Long-term care facilities are consolidating purchasing power through group procurement organizations while demanding lighter, more configurable mobility aids that reduce staff handling time and fall liability exposure.
Growth Catalysts
- Medicare Part B reimbursement:The durable medical equipment fee schedule in the United States covers 80% of allowable costs for prescribed walkers and rollators, lowering out-of-pocket barriers for seniors with mobility limitations.
- Aluminum-lithium alloys:Advanced material formulations are reducing frame weight by 15-20% without sacrificing load capacity, enabling manufacturers to serve bariatric and pediatric segments with unified platform designs.
- Japan's long-term care insurance:Kaigo Hoken subsidizes assistive device acquisition for citizens aged 65+, creating institutional demand channels distinct from retail pharmacy distribution.
Market Restraints
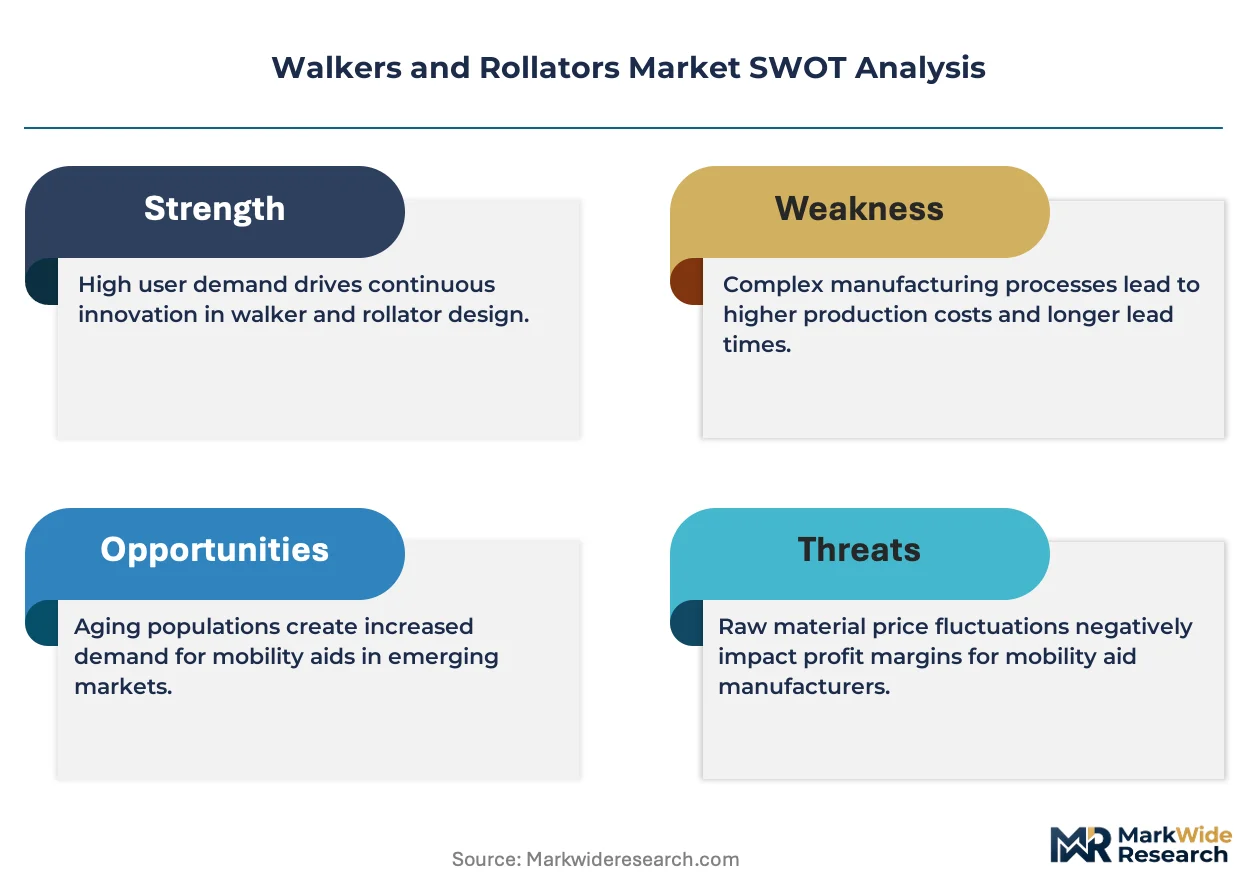
- Raw material volatility:Aluminum ingot prices fluctuate with energy costs, compressing margins for mid-tier manufacturers without captive smelter relationships or forward hedging programs.
- Supply concentration in Chinese extrusion:Over 60% of aluminum tubing for mobility devices originates from Zhejiang and Guangdong provinces, exposing brands to tariff discontinuities and shipping rate spikes.
- ISO 11199-2 testing burden:Stability validation for four-wheeled rollators requires specialized tilt-table equipment and third-party laboratory accreditation, extending product development cycles.
Strategic Opportunities
- Germany's homecare expansion:Statutory health insurance reforms are shifting rehabilitation funding toward outpatient settings, expanding addressable demand for premium rollators with integrated seating and storage.
- Telehealth-integrated mobility monitoring:Sensor-equipped rollators transmitting usage data to remote care teams are converging with RPM reimbursement codes, opening subscription revenue streams.
- Direct-to-consumer e-commerce:Amazon and specialized medical supply platforms are bypassing durable medical equipment distributors, allowing brands to capture margin and build first-party customer data assets.
Industry Challenges
- Biomechanical engineering talent scarcity:Designing frames that accommodate anthropometric variation across elderly, bariatric, and pediatric users requires specialized expertise concentrated in orthopedic device firms and university research centers.
- EU MDR technical documentation:Notified body review timelines for Class I medical devices have extended from 3-6 months to 12-18 months, freezing product line refreshes and competitive repositioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Walkers and Rollators Market |
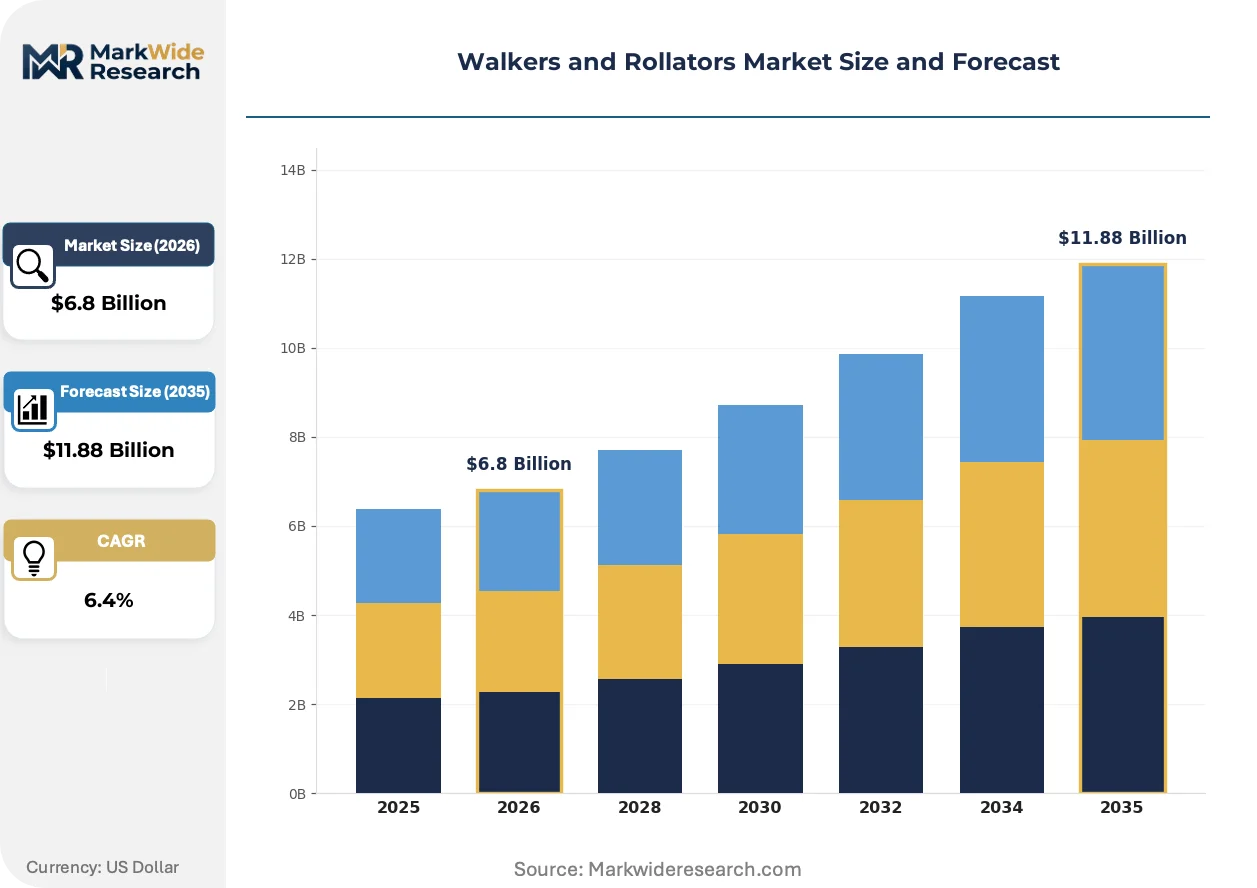
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Walkers, Rollator Walkers, Three-Wheel Rollators, Four-Wheel Rollators End User: Senior Citizens, Physically Disabled, Rehabilitation Patients, Long-Term Care Facilities Material: Aluminum, Steel, Plastic, Composite Materials Feature: Foldable Design, Lightweight, Adjustable Height, Integrated Seats |
| Companies Covered | TOPRO, Graham Field, Drive DeVilbiss Healthcare, Karman Healthcare, Thuasne, Sunrise Medical, Human Care, Meyra, Medline Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Walkers and Rollators Market Emerging Trajectories
Carbon fiber composites, embedded sensor systems, and modular accessory ecosystems are restructuring product architecture and value capture models across the walker and rollator category.
Carbon fiber reinforced polymer construction is converging with aerospace manufacturing techniques to produce frames under 2.5 kilograms that maintain 150-kilogram load ratings. German and Japanese premium brands are adopting these materials for private-pay customers who prioritize portability over reimbursement eligibility. The technology is compressing the traditional trade-off between weight capacity and frame mass, enabling single-product platforms to span bariatric and travel-use cases.
The EU Medical Device Regulation is mandating unique device identification and post-market surveillance for all CE-marked mobility aids sold in European Economic Area member states. Manufacturers must maintain vigilance systems for adverse event reporting and periodic safety update reports, elevating compliance costs for smaller exporters. Scandinavian homecare providers are responding by consolidating supplier relationships toward vertically integrated manufacturers with established quality management systems.
Institutional buyers in the United States are unbundling after-sales service from equipment procurement, separating maintenance contracts from initial purchase orders. Hospital systems and skilled nursing facilities now solicit three-year total cost of ownership bids that include parts availability guarantees and loaner unit provisions. This behavioral shift is most visible in California and Florida markets where large senior living operators manage multi-site equipment fleets across dozens of properties.
Walkers and Rollators Market Segmentation
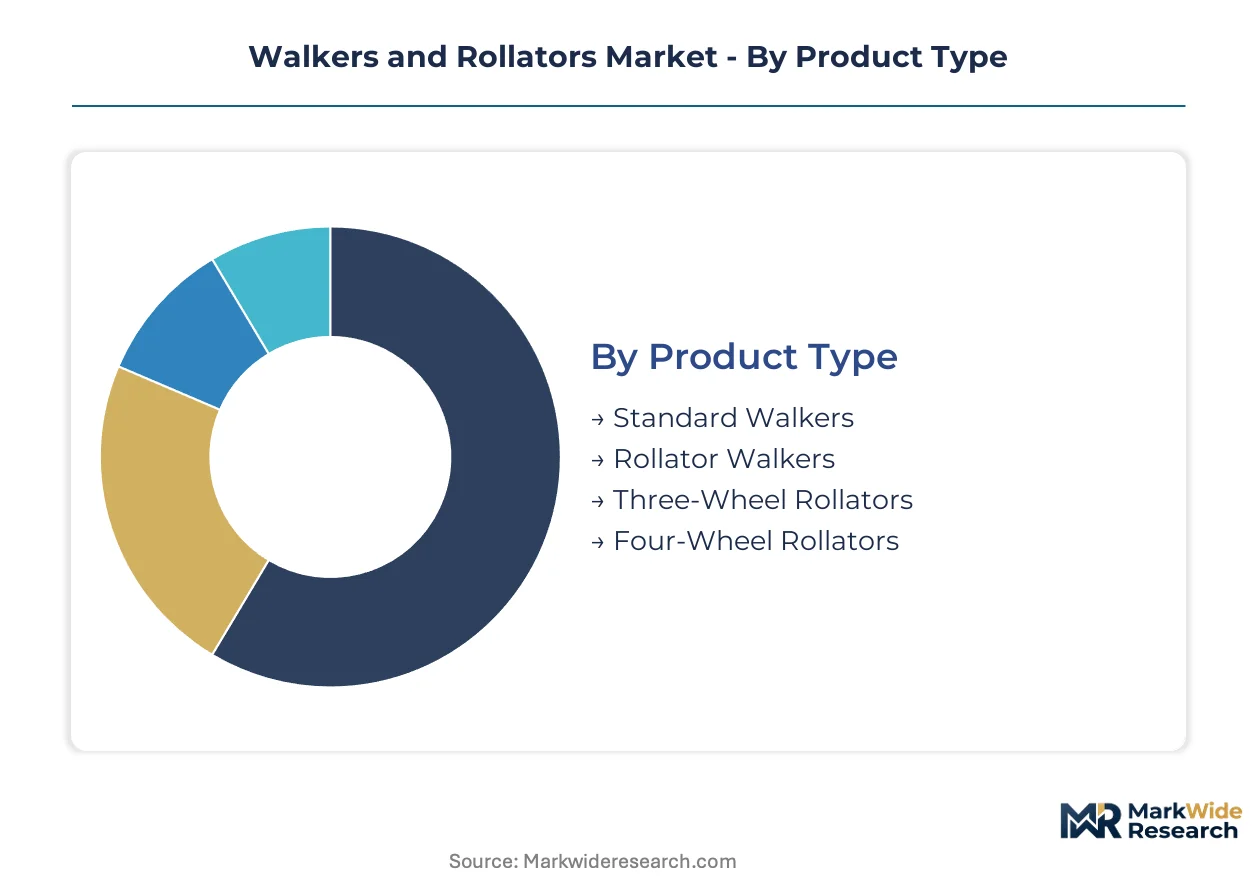
Segmentation in walkers and rollators determines procurement pathways, reimbursement eligibility, and manufacturing scale economics. Product architecture choices cascade through material sourcing, regulatory classification, and end-user pricing tiers.
Product Type:
Supply concentration in four-wheeled platforms has compressed development resources toward rollator variants with integrated braking and seating systems.
- Standard Walkers:Basic aluminum-framed devices without wheels, prescribed for post-surgical gait training where maximum stability outweighs mobility convenience. Demand concentrates in Medicare Part B channels where cost minimization drives formulary placement, though volume is plateauing as rollators capture preference.
- Rollator Walkers:Four-wheeled frames with hand-operated brakes and foldable construction, commanding premium positioning through added functionality. German statutory health insurance and Japan's Kaigo Hoken subsidize these devices, accelerating replacement of standard walkers in institutional procurement.
- Three-Wheel Rollators:Maneuverable triangular-base design prioritizing indoor navigation over outdoor stability.
- Four-Wheel Rollators:Dominant platform incorporating seats, storage, and advanced braking for bariatric and travel use cases.
Today's leader: Rollator Walkers. Tomorrow's challenger: Four-Wheel Rollators.
End User:
Cost tier differentiation separates retail pharmacy self-pay from institutional volume contracting with maintenance-included terms.
- Senior Citizens:Private-pay consumers aged 65+ purchasing through durable medical equipment suppliers or direct-to-consumer platforms. United States demand clusters in Florida and Arizona retirement corridors where Medicare Advantage plans influence brand access.
- Physically Disabled:Users with permanent mobility limitations requiring customized frame dimensions and pressure-redistribution seating. Medicaid waiver programs and vocational rehabilitation funding shape acquisition pathways distinct from Medicare channels.
- Rehabilitation Patients:Short-term users transitioning from hospital discharge to outpatient recovery.
- Long-Term Care Facilities:Multi-site operators managing fleet standardization across skilled nursing and assisted living properties.
Volume concentrates with Long-Term Care Facilities. Margin expansion sits with Physically Disabled.
Material:
Geography of raw material extraction and extrusion capacity dictates landed cost structures and tariff exposure.
- Aluminum:6061-T6 and 7000-series alloys deliver strength-to-weight ratios enabling sub-3-kilogram frame construction. Zhejiang and Guangdong province extruders supply over sixty percent of tubing, exposing manufacturers to shipping rate volatility and trade policy discontinuities.
- Steel:Chromoly and carbon steel frames serve bariatric load ratings exceeding 150 kilograms where deflection tolerance matters more than portability. German and Japanese domestic mills supply institutional buyers with multi-year durability specifications.
- Plastic:Polymer components for handgrips, wheels, and seating surfaces.
- Composite Materials:Carbon fiber reinforced polymer construction for sub-2.5-kilogram travel rollators.
Aluminum anchors current production. Composite Materials command the steepest expansion trajectory.
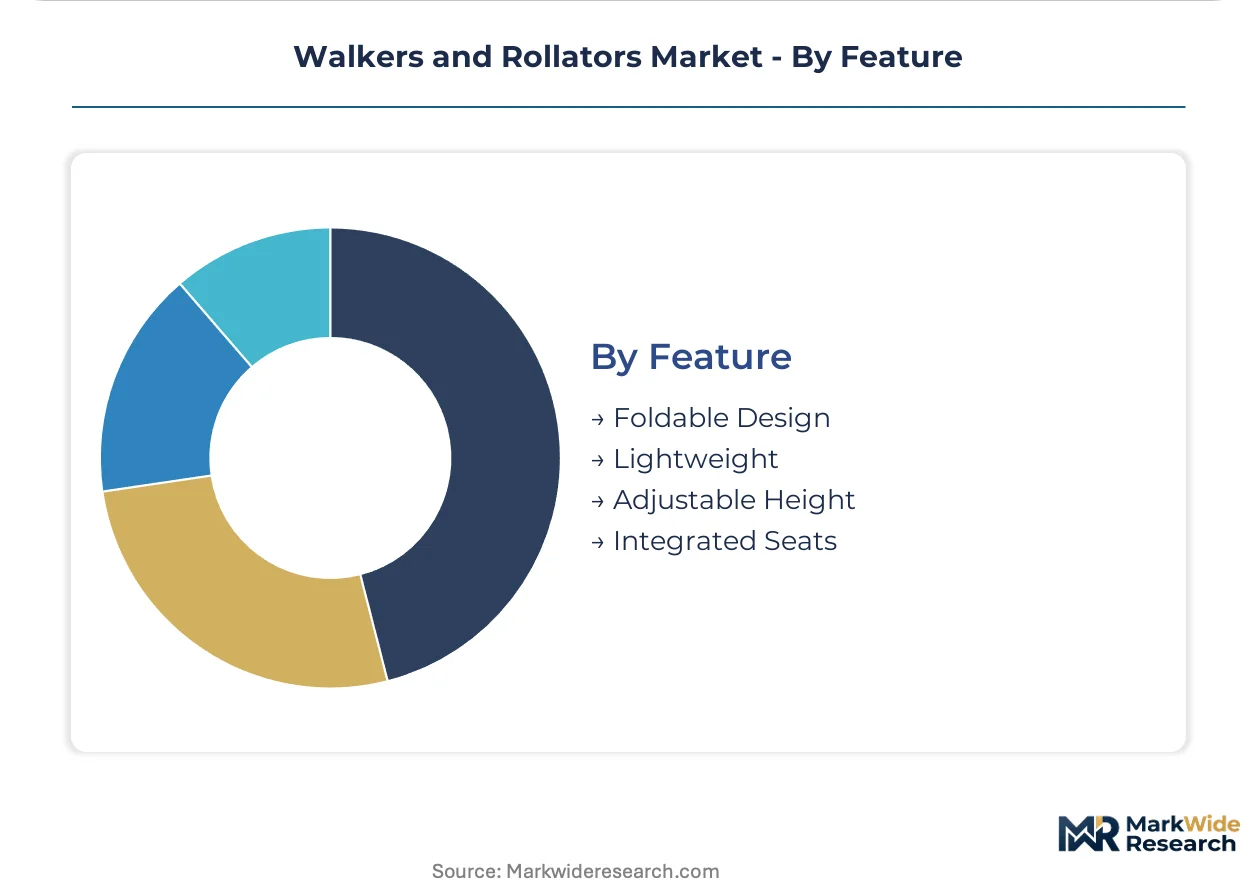
Feature:
Customer type requirements from institutional buyers versus retail consumers drive feature bundling strategies.
- Foldable Design:Collapsible frames enabling vehicle trunk storage and air travel compliance. Scandinavian homecare providers mandate this specification for community-dwelling elderly maintaining active lifestyles outside residential facilities.
- Lightweight:Sub-3-kilogram construction achieved through aluminum-lithium alloys or carbon fiber, reducing caregiver handling burden in long-term care settings. Japanese MHLW reimbursement codes incentivize weight reduction through higher fee schedule allowances.
- Adjustable Height:Telescoping leg extensions accommodating anthropometric variation across user populations.
- Integrated Seats:Padded resting surfaces with locking brakes for fall prevention during standing transitions.
Integrated Seats dominate institutional specifications. Lightweight captures retail premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomechanical engineering talent clusters in Germany, Japan, and the United States anchor walker and rollator innovation pipelines. These three countries concentrate industrial design expertise, regulatory science capability, and aging populations that validate product iterations.
United States
Medicare Part B fee schedules drive durable medical equipment procurement through 80% cost coverage for prescribed devices. FDA 510(k) clearance pathways govern product entry, with ISO 11199-2 stability standards mandating tilt-table validation. Florida and Arizona retirement corridors concentrate retail demand as Medicare Advantage plans influence brand access across senior living networks.
Germany
Statutory health insurance reforms shift rehabilitation funding toward outpatient settings, expanding premium rollator demand with integrated seating and storage. EU MDR notified body certification extends review timelines to 12-18 months for Class I medical devices. North Rhine-Westphalia and Baden-Württemberg host medical device engineering clusters where aluminum-lithium alloy formulations undergo fatigue testing.
Japan
Kaigo Hoken long-term care insurance subsidizes assistive device acquisition for citizens aged 65+, creating institutional procurement channels distinct from retail pharmacy distribution. MHLW classifies walkers and rollators as designated medical devices requiring in-country testing and quality system registration. Kanto and Kansai regions concentrate manufacturing partnerships between domestic brands and Zhejiang province extruders.
China
Zhejiang and Guangdong provinces supply over 60% of aluminum tubing for global mobility device production, exposing manufacturers to tariff discontinuities and shipping rate volatility. GB standards and NMPA medical device classification govern domestic market entry. Shanghai and Shenzhen medical device parks host contract manufacturers serving European and North American OEMs with ISO 13485-certified assembly lines.
United Kingdom
NHS continuing healthcare budgets determine institutional procurement volumes for long-term care facilities managing multi-site equipment fleets. MHRA post-Brexit regulatory alignment with EU MDR technical documentation requirements persists through transitional arrangements. London and Southeast England concentrate homecare provider headquarters where group purchasing organizations consolidate supplier relationships toward vertically integrated manufacturers.
Walkers and Rollators Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across walker and rollator supply chains, with aluminum extruders and polymer molders maintaining captive fabrication capacity while brand owners outsource assembly to contract manufacturers. Market structure tilts toward consolidation among institutional suppliers serving long-term care facilities, while direct-to-consumer channels fragment across specialized medical supply platforms and Amazon marketplace sellers. Three archetypes dominate: vertically integrated European premium brands, North American durable medical equipment specialists with distributor networks, and Asian contract manufacturers with ISO-certified production lines. Competitive moves concentrate on M&A to secure distribution access and strategic partnerships to embed sensor-enabled monitoring capabilities.
Within the premium Scandinavian design tier, TOPRO exemplifies heritage positioning through Norwegian engineering pedigree. North American durable medical equipment specialists include Graham Field and Drive DeVilbiss Healthcare, both occupying positions anchored by institutional buyer relationships and Medicare reimbursement channel access. These three companies represent distinct competitive vectors: European design premiumization, domestic regulatory navigation, and scale-driven distribution breadth.
| Leading Market Players |
|---|
| TOPRO |
| Graham Field |
| Drive DeVilbiss Healthcare |
| Karman Healthcare |
| Thuasne |
| Sunrise Medical |
| Human Care |
| Meyra |
| Medline Industries |
| Others |
Supply Flow & Price Mechanics
London Metal Exchange aluminum futures pricing cascades through Zhejiang extrusion mills into three-tier pricing stratification across premium carbon fiber rollators, standard aluminum-lithium platforms, and economy steel-framed walkers, with institutional buyers capturing volume discounts while direct-to-consumer channels absorb logistics premiums.
Pricing Analysis
The bundled-vs-unbundled service split distinguishes institutional procurement from retail acquisition, with long-term care facilities negotiating three-year total cost of ownership contracts encompassing maintenance guarantees and loaner unit provisions while Amazon marketplace sellers transact per-unit with freight absorption. Price differentiation rests on ISO 13485 certification tier and after-sales service bundling, with FDA 510(k) cleared devices commanding premiums over uncertified imports. Cost compression in the economy tier intensifies because Chinese contract manufacturers compete on extrusion efficiency, squeezing mid-tier brands without captive alloy sourcing. Medicaid waiver programs exhibit highest price sensitivity due to fixed reimbursement ceilings, whereas Japanese Kaigo Hoken channels tolerate premium positioning for sub-3-kilogram lightweight platforms.
Supply Chain Analysis
Reverse-logistics flows for rollator refurbishment and parts harvesting remain underdeveloped, creating aftermarket voids that third-party service providers are beginning to populate with brake pad replacement and wheel assembly programs. Manufacturing gravity draws from Zhejiang and Guangdong provinces for aluminum tubing, German mills for chromoly steel, and Japanese carbon fiber weavers for premium travel platforms. Raw material dependencies encompass 6061-T6 aluminum alloy, polymer composites for handgrips, and pneumatic tire assemblies. Single-source vulnerability concentrates in Chinese extrusion capacity, exposing brands to tariff discontinuities and transpacific shipping rate spikes. Distribution runs through durable medical equipment distributors for Medicare Part B channels, direct-to-consumer platforms for private-pay seniors, and group purchasing organizations for multi-site long-term care operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in walkers and rollators hinges on aluminum-lithium alloy adoption compressing frame costs by fifteen to twenty percent without sacrificing load ratings, enabling unified platform designs to capture both bariatric and pediatric segments.
For Market Incumbents: Anchor market position through backward integration into Zhejiang extrusion partnerships or captive aluminum-lithium alloy sourcing, securing cost advantages against emerging carbon fiber entrants while accelerating ISO 11199-2 stability testing capacity to compress EU MDR notified body review timelines from eighteen months toward competitive twelve-month benchmarks.
For New Entrants and Emerging Players: The mid-tier price-point gap between Scandinavian carbon fiber premiums and Chinese economy steel frames creates white-space opportunity for aluminum-lithium platforms with telehealth-integrated sensor systems, targeting Germany's outpatient rehabilitation expansion and Japan's Kaigo Hoken reimbursement channels through direct-to-consumer e-commerce bypassing traditional durable medical equipment distributor markups.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated manufacturers possessing ISO 13485-certified production lines and established EU MDR technical documentation capabilities, as consolidation pressure intensifies among institutional suppliers serving long-term care facility group purchasing organizations. Acquisition targets should demonstrate five-to-ten year viability through reimbursement code capture and sensor-enabled remote patient monitoring integration. Monitor Medicare Advantage plan formulary placement decisions and Japan MHLW designated medical device registration timelines as inflection indicators for volume access shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR notified body certification compresses competitive positioning timelines for Class I mobility devices. |
| Hospital System Partnership | Multi-site long-term care operators consolidate supplier relationships toward vertically integrated manufacturers with maintenance bundling. |
| Software Companion Development | Sensor-equipped rollators transmitting usage data converge with remote patient monitoring reimbursement codes. |
| Reimbursement Strategy | Medicare Part B fee schedule navigation and Japan Kaigo Hoken code capture determine volume access. |
| Backward Integration into Aluminum Extrusion | Captive supply of 6061-T6 and aluminum-lithium alloys insulates margins from London Metal Exchange volatility. |
Methodological Framework
Bottom-up long-term care facility and retail pharmacy modeling reconciled against top-down aluminum extrusion and carbon fiber composite supply tracking forms the analytical core of this study. Primary interviews with biomedical engineers, durable medical equipment procurement managers, GPO contracts specialists, and rehabilitation clinicians combined with secondary validation against FDA 510(k) filings, CMS Medicare claims data, EU MDR notified body certification databases, and Japan MHLW designated medical device registrations. Triangulation across these sources ensures segmentation integrity across product architecture, material composition, and reimbursement channel dimensions.
Input-output matrices map rollator frame production from Zhejiang and Guangdong extrusion through German and Japanese final assembly, with volume and value outputs derived across the projection horizon through elasticity modeling of Medicare Part B reimbursement thresholds, Japan Kaigo Hoken fee schedule adjustments, and EU MDR compliance cost pass-through. Segmentation dimensions encompass product type (standard walker, three-wheel rollator, four-wheel rollator), material (aluminum, steel, carbon fiber composite), end user (senior citizens, physically disabled, rehabilitation patients, long-term care facilities), and feature configuration (foldable design, lightweight construction, integrated seating). CAGRs reflect installed base replacement cycles, demographic aging trajectories, and outpatient rehabilitation policy shifts.
Caveats apply where aluminum ingot price volatility, EU MDR notified body review timeline extensions, or Medicare reimbursement compression could materially shift the outlook. Forecasts embed assumptions regarding statutory health insurance reform continuity in Germany and Kaigo Hoken benefit sustainability in Japan. Practitioners should monitor London Metal Exchange aluminum futures, FDA 510(k) clearance backlogs, and group purchasing organization consolidation activity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Diagnostic Catheter Market
Medical Devices
United Arab Emirates Drug Delivery Devices Market
Medical Devices
Endoprosthesis Market
Medical Devices
South Korea ECG Market
Medical Devices
Joint Reconstruction Devices Market
Medical Devices
Pharma Robots Market
Medical Devices
Left Atrial Appendage (LAA) Closure Device Market
Medical Devices
Global Mobile ECG Devices Market
Medical Devices
Global Cryotherapy Market
Medical Devices
Actigraphy Sensors & PSG Devices Market
Medical Devices
Midline Catheters Market
Medical Devices
Global Concussion Market
Medical Devices
Hearing Devices 3D Printing Market
Medical Devices
Cardiac Implants Market
Medical Devices
Neurovascular Devices Market
Medical Devices
Intravenous Stopcock Market