
 China Diagnostic Imaging Equipment Market | 2026-2036
China Diagnostic Imaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
China Diagnostic Imaging Equipment Market Analysis
Tertiary hospital procurement is realigning toward high-field MRI and spectral CT configurations as China's tier-one medical centers pursue imaging parity with Western counterparts. GE HealthCare Technologies leverages its established service infrastructure across provincial capitals to sustain long-term equipment contracts. Siemens Healthineers anchors its position through localized R&D centers in Shanghai that adapt global platforms to domestic clinical workflows. United Imaging Healthcare competes aggressively on total cost of ownership while expanding its installed base beyond coastal provinces.
China diagnostic imaging equipment encompasses electromagnetic and acoustic systems engineered to generate visual representations of internal anatomy for clinical diagnosis, with MRI systems employing superconducting magnets operating at 1.5 to 3.0 Tesla and CT scanners utilizing rotating X-ray tube-detector gantries capable of sub-millimeter spatial resolution. CT scanners lead volume deployment in county-level hospital upgrades funded by central fiscal transfers, while MRI systems command premium positioning in neurological and oncological applications where tissue contrast specificity determines diagnostic confidence. Digital imaging technology dominates new installations as analog systems face accelerated replacement cycles driven by NMPA imaging quality standards and hospital accreditation requirements.
NMPA Class III device regulations mandate clinical trial data for novel imaging modalities, while GB standards govern electromagnetic compatibility and radiation safety thresholds for installed equipment. China's dual carbon goals pressure manufacturers to reduce helium consumption in MRI magnet cooling and improve CT energy efficiency metrics. Stakeholders must monitor provincial centralized procurement tender designs, as volume-based purchasing mechanisms reshape pricing dynamics and vendor selection criteria across sub-national health systems.
Market Dynamics
Provincial centralized procurement is consolidating vendor selection power across China's hospital tiers, compressing pricing autonomy and forcing equipment manufacturers to restructure channel economics around volume commitments rather than unit margins.
Growth Catalysts
- NMPA Class III streamlined review pathways:Compressed approval timelines for domestic MRI and CT manufacturers accelerate market entry and reduce regulatory lag for novel imaging modalities.
- County-level hospital infrastructure upgrades:Central fiscal transfers fund CT scanner deployment in secondary care facilities, expanding addressable installed base beyond tertiary centers.
- Helium-3 recovery systems:Closed-loop magnet cooling technology reduces operational dependency on volatile helium supply chains while supporting China's dual carbon goals.
Market Restraints
- Superconducting wire supply concentration:Niobium-titanium filament production concentrates among limited international suppliers, exposing domestic MRI manufacturers to input cost volatility and quota constraints.
- GB electromagnetic compatibility certification:Stringent testing protocols for 3.0 Tesla systems create technical friction and extend pre-market validation timelines.
- Refurbished equipment arbitrage:Secondary market CT and MRI systems from decommissioned Western hospitals compete on total cost of ownership in budget-constrained county facilities.
Strategic Opportunities
- Central and Western China hospital clusters:Underpenetrated provinces beyond Beijing-Shanghai-Guangzhou corridors present whitespace for spectral CT and high-field MRI penetration as healthcare infrastructure balances develop.
- AI-integrated diagnostic workflows:Convergence of deep learning reconstruction algorithms with spectral CT data streams enables automated lesion characterization and radiologist productivity gains.
- Provincial volume-based purchasing mechanisms:Tender designs favoring multi-year service bundling create openings for manufacturers to capture aftermarket revenue through predictive maintenance contracts.
Industry Challenges
- Superconducting magnet engineering talent:Scarcity of cryogenic system specialists and high-field coil designers constrains domestic R&D velocity and service capability buildout.
- Legacy PACS integration complexity:New digital imaging platforms face interoperability friction with hospital information systems deployed during prior upgrade cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Diagnostic Imaging Equipment Market |
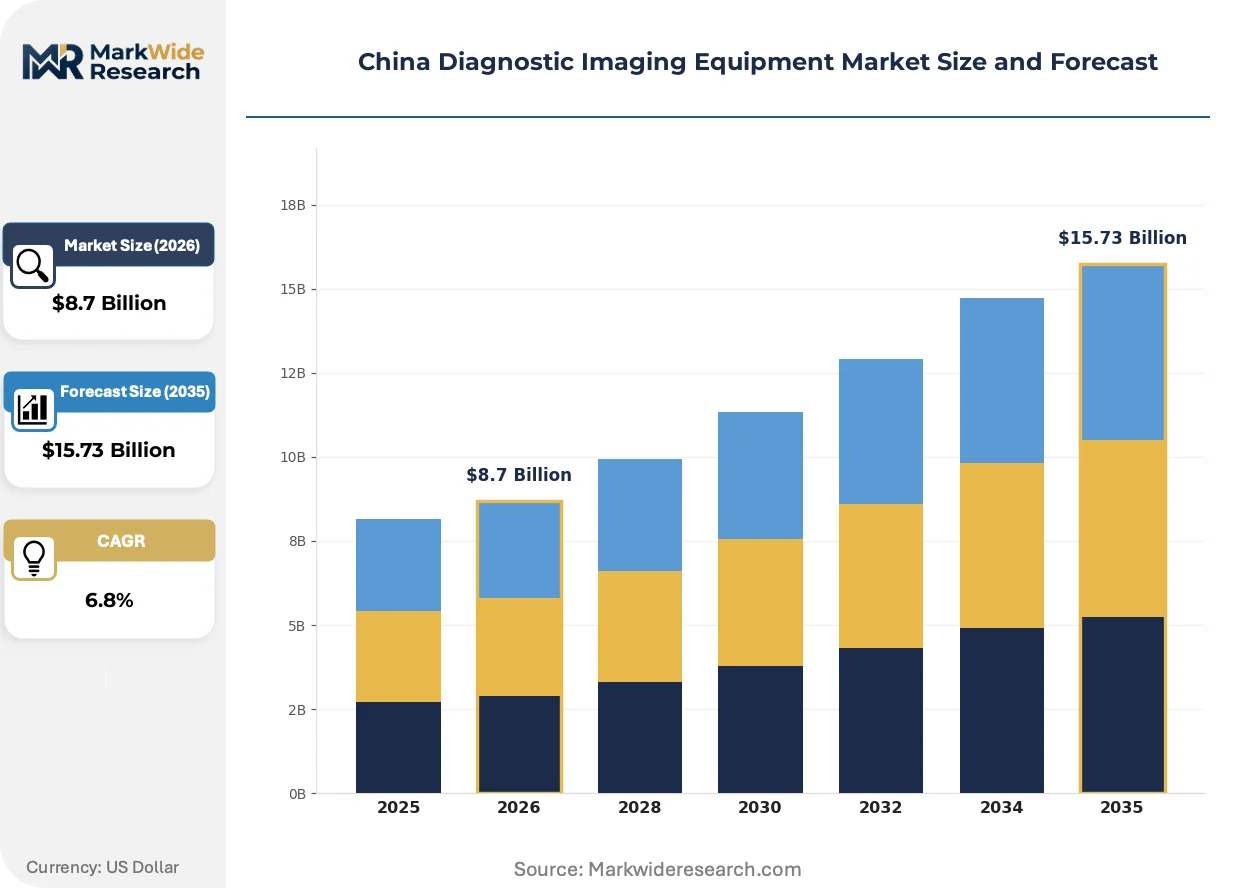
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray Machines, MRI Systems, Ultrasound Devices, CT Scanners End User: Hospitals, Diagnostic Laboratories, Research Institutes, Clinics Technology: Digital Imaging, Analog Imaging, Hybrid Imaging, 3D Imaging Application: Oncology, Cardiology, Neurology, Orthopedics |
| Companies Covered | GE HealthCare Technologies, Siemens Healthineers, Koninklijke Philips, Canon, United Imaging Healthcare, Neusoft Medical Systems, Mindray, Shimadzu, Hitachi, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Diagnostic Imaging Equipment Market Emerging Trajectories
Spectral detector technology and AI-native reconstruction are compressing scan times while expanding tissue characterization capabilities, reshaping competitive differentiation around software-defined imaging rather than hardware specifications alone.
Photon-counting CT detector arrays are consolidating diagnostic confidence in cardiovascular and oncological applications by resolving iodine contrast at sub-millimeter spatial scales. Tertiary hospitals in Beijing and Shanghai are piloting these configurations for coronary plaque characterization. The technology is consolidating premium positioning in high-throughput centers where throughput per scanner hour determines capital efficiency.
NMPA's alignment with GB standards for electromagnetic compatibility and radiation safety is tightening compliance thresholds for imported equipment while accelerating domestic platform validation. Manufacturers must now submit clinical trial data from Chinese patient cohorts for novel imaging modalities. This regulatory posture is favoring localized R&D centers that adapt global platforms to domestic clinical workflows.
Hospital procurement committees are unbundling equipment acquisition from long-term service contracts, compressing vendor lock-in and forcing manufacturers to compete on transparent lifecycle cost models. Provincial health commissions in Jiangsu and Zhejiang are piloting this separation in centralized tenders. The pattern is most visible in East China where hospital cluster density enables multi-site service consolidation.
China Diagnostic Imaging Equipment Market Segmentation
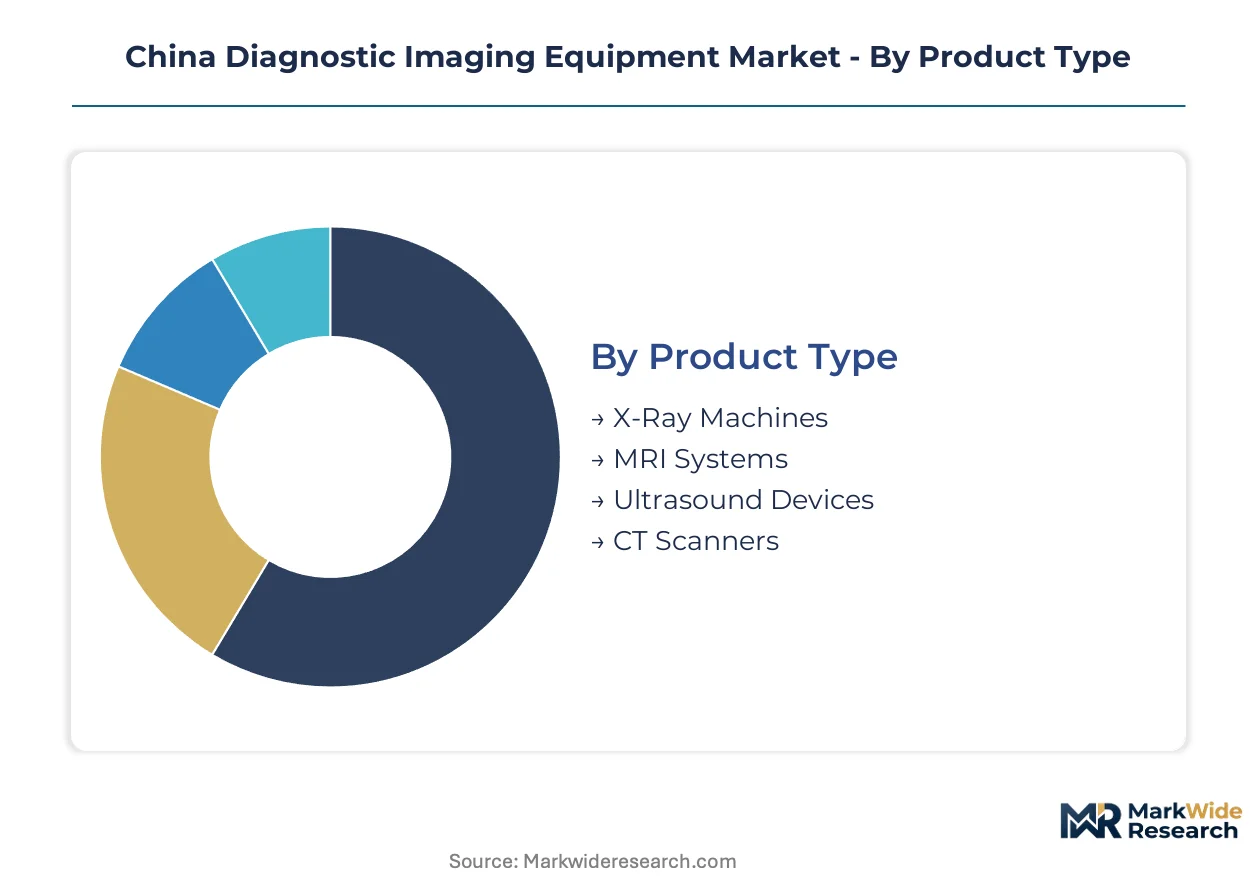
Equipment segmentation in China's diagnostic imaging market determines regulatory pathway complexity and procurement tier eligibility. NMPA Class III certification requirements vary substantially across product categories, shaping manufacturer competitive positioning and hospital acquisition timelines.
Product Type:
NMPA Class III clinical trial mandates apply differentially across modalities, with superconducting MRI systems facing the most stringent pre-market validation requirements while digital X-ray platforms navigate abbreviated review tracks.
- CT Scanners:Rotating gantry systems utilizing X-ray tube-detector arrays achieve sub-millimeter spatial resolution for thoracic and abdominal diagnostics. County-level hospitals in Jiangsu and Sichuan drive volume procurement through central fiscal transfer programs, with spectral detector configurations gaining traction in tertiary centers.
- MRI Systems:Superconducting magnet platforms operating at 1.5 to 3.0 Tesla generate tissue contrast for neurological and oncological applications. Beijing and Shanghai tertiary hospitals concentrate demand for high-field configurations, though helium supply volatility constrains operational expansion in inland provinces.
- X-Ray Machines:Digital radiography systems with flat-panel detectors dominate replacement cycles in secondary care facilities.
- Ultrasound Devices:Piezoelectric transducer systems span portable cart-based to premium console configurations for cardiac and obstetric workflows.
Leading the category by volume: CT Scanners. Growing fastest: MRI Systems.
End User:
Procurement authority concentrates in hospital procurement committees, while diagnostic laboratories and research institutes operate under distinct budgetary streams with specialized equipment specifications.
- Hospitals:Tertiary medical centers in Beijing, Shanghai, and Guangzhou anchor premium equipment demand, with centralized provincial tenders consolidating vendor selection power across multi-site networks.
- Diagnostic Laboratories:Independent imaging chains and hospital-affiliated centers pursue throughput-optimized configurations for high-volume screening protocols.
- Research Institutes:Academic medical centers and national laboratories acquire preclinical and experimental imaging platforms for translational research applications.
- Clinics:Primary care facilities and specialty outpatient centers deploy compact ultrasound and digital X-ray systems for point-of-care diagnostics.
Dominating procurement value: Hospitals. Expanding most quickly: Diagnostic Laboratories.
Technology:
Digital imaging platforms command premium positioning against legacy analog installations, with hybrid configurations bridging transitional upgrade pathways for budget-constrained facilities.
- Digital Imaging:Detector arrays with direct or indirect conversion architectures enable DICOM-native workflow integration and PACS connectivity. East China hospital clusters drive replacement demand as NMPA imaging quality standards accelerate analog phase-out timelines.
- 3D Imaging:Volumetric reconstruction algorithms applied to CT and MRI datasets enable multi-planar visualization for surgical planning and interventional guidance.
- Hybrid Imaging:PET-CT and PET-MRI fusion systems combine functional and anatomical data streams for oncological staging.
- Analog Imaging:Film-based radiography persists in remote county facilities with limited digital infrastructure.
Commanding installed base share: Digital Imaging. Gaining share fastest: 3D Imaging.
Application:
Clinical specialization dictates equipment specification requirements, with oncology and cardiology applications driving highest-value procurement decisions.
- Oncology:Tumor characterization workflows demand spectral CT tissue differentiation and multi-parametric MRI sequences for treatment response monitoring.
- Cardiology:Coronary CT angiography and cardiac MRI stress perfusion imaging require sub-second temporal resolution and ECG-gated acquisition protocols.
- Neurology:Functional MRI and diffusion tensor imaging support stroke assessment and neurosurgical planning in tertiary referral centers.
- Orthopedics:Weight-bearing CT and dedicated extremity MRI configurations address musculoskeletal trauma and degenerative joint disease.
Generating highest equipment revenue: Oncology. Climbing the fastest: Cardiology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta Economic Zone concentrates China's diagnostic imaging manufacturing capacity through tax incentives and bonded logistics zones. Provincial health commissions in Jiangsu and Zhejiang pilot volume-based procurement mechanisms that reshape vendor economics across East China hospital clusters.
Beijing-Tianjin-Hebei
Tertiary hospitals in Beijing anchor premium MRI demand for neurological and oncological applications. NMPA's streamlined Class III review pathways accelerate domestic manufacturer market entry for novel imaging modalities. Tianjin's port infrastructure supports superconducting magnet import logistics for regional MRI assembly facilities.
Yangtze River Delta
Shanghai's hospital procurement committees drive spectral CT adoption for coronary plaque characterization workflows. GB electromagnetic compatibility certification requirements tighten compliance thresholds for 3.0 Tesla installations. Suzhou and Hangzhou manufacturing parks host localized R&D centers adapting global platforms to domestic clinical protocols.
Pearl River Delta
Guangzhou and Shenzhen hospital networks expand CT scanner deployment through central fiscal transfer programs. SAMR oversight of medical device pricing enforces transparency in provincial tender processes. Dongguan's electronics manufacturing base supplies detector array components for digital radiography systems.
Sichuan-Chongqing
County-level hospital upgrades in Sichuan province absorb volume CT procurement from centralized tenders. Dual carbon goals pressure manufacturers to reduce helium consumption in MRI magnet cooling for inland operations. Chengdu's medical device industrial park anchors Western China distribution networks.
Shandong Peninsula
Qingdao and Jinan secondary care facilities drive digital X-ray replacement cycles under NMPA imaging quality standards. Provincial centralized procurement consolidates vendor selection power across municipal hospital networks. Yantai's port facilities handle refurbished equipment imports competing in budget-constrained segments.
China Diagnostic Imaging Equipment Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational installed bases defending service infrastructure contracts while domestic challengers compete on total cost of ownership. Market structure exhibits tiered consolidation: premium imaging platforms concentrate among magnet engineering specialists, mid-range CT scanners fragment across provincial tender participants, and portable ultrasound commoditizes. Three archetypes dominate: integrated system houses with captive magnet production, modular assemblers sourcing superconducting wire internationally, and software-defined imaging platforms leveraging AI reconstruction. Competitive moves center on multi-year service bundling and predictive maintenance contracts that capture aftermarket revenue.
Among multinational imaging houses, GE HealthCare Technologies and Siemens Healthineers occupy positions anchored by established service networks across provincial capitals. United Imaging Healthcare exemplifies the domestic challenger archetype, competing aggressively beyond coastal provinces while expanding installed base through volume commitments. These three represent the competitive tension between global platform adaptation and localized R&D velocity in China's NMPA-regulated environment.
| Leading Market Players |
|---|
| GE HealthCare Technologies |
| Siemens Healthineers |
| Koninklijke Philips |
| Canon |
| United Imaging Healthcare |
| Neusoft Medical Systems |
| Mindray |
| Shimadzu |
| Hitachi |
| Others |
Supply Flow & Price Mechanics
Provincial centralized procurement committees in Jiangsu and Zhejiang anchor pricing power through volume-based tender mechanisms that compress unit margins while extending contract duration. NMPA Class III certification tiers stratify equipment valuations across tertiary hospital networks, with spectral CT configurations commanding premium positioning against county-level standard CT deployments.
Pricing Analysis
Short lead-time premiums for superconducting MRI systems widen spreads against spot-inventory refurbished units arriving through Yantai port facilities. Three-tier pricing structure across premium, standard, and economy levels separates NMPA-validated 3.0 Tesla platforms from 1.5 Tesla workhorse configurations and secondary-market analog replacements. Cost compression in mid-field MRI segments intensifies because United Imaging Healthcare and Neusoft Medical Systems compete aggressively on total cost of ownership. County-level hospital procurement committees exhibit highest price sensitivity, while Beijing and Shanghai tertiary centers prioritize spectral detector capabilities over unit economics.
Supply Chain Analysis
Cryogenic engineering talent scarcity in Suzhou and Hangzhou manufacturing parks constrains domestic superconducting magnet production velocity. Niobium-titanium filament supply concentrates in Japan and Germany, while helium-3 recovery system components source from specialized US and European vendors. Single-source vulnerability in superconducting wire supply exposes domestic MRI assemblers to quota constraints and input cost volatility. Distribution runs through provincial health commission tender platforms that consolidate multi-site hospital network procurement under centralized vendor selection protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's diagnostic imaging market sits in a technology-transition phase as photon-counting CT detector arrays displace conventional energy-integrating configurations in tertiary hospital upgrade cycles.
For Market Incumbents: Anticipate margin compression in standard CT segments as provincial volume-based procurement consolidates vendor selection power. Defensive positioning requires captive magnet production capacity in Yangtze River Delta manufacturing parks and predictive maintenance service bundling that captures aftermarket revenue through multi-year contracts. The threat of AI-native reconstruction algorithms commoditizing hardware specifications demands accelerated software R&D investment in Shanghai localized development centers. For New Entrants and Emerging Players: The premium-to-economy price-point gap in spectral CT configurations creates entry whitespace for mid-tier challengers. Underpenetrated Central and Western China hospital clusters present the most penetrable geography, with Sichuan and Chongqing county-level facilities absorbing volume procurement through central fiscal transfers. A software-defined imaging platform leveraging deep learning reconstruction algorithms offers differentiation without superconducting magnet engineering dependency. For Investors and Strategic Acquirers: The window for entry favors domestic challengers with NMPA Class III approval momentum and established provincial tender participation records. Long-term viability hinges on five-to-ten year infrastructure investment cycles as China's healthcare system balances toward inland provinces. Watch helium supply chain restructuring and closed-loop magnet cooling technology adoption as inflection indicators for domestic manufacturer competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Class III Streamlined Review Pathway | Compressed approval timelines accelerate domestic MRI and CT manufacturer market entry. |
| Helium-3 Recovery System Deployment | Closed-loop magnet cooling reduces operational dependency on volatile helium supply chains. |
| AI-Native Reconstruction Algorithm Integration | Deep learning convergence with spectral CT data enables automated lesion characterization. |
| Provincial Volume-Based Procurement Participation | Multi-year service bundling captures aftermarket revenue through predictive maintenance contracts. |
| Central and Western China Distribution Network Buildout | Underpenetrated provinces beyond Beijing-Shanghai corridors present whitespace expansion opportunity. |
Methodological Framework
NMPA medical device registration databases, provincial health commission tender records, and hospital procurement committee documentation formed the secondary backbone of this analysis. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and superconducting magnet engineering specialists combined with secondary validation through bottom-up and top-down triangulation approaches.
Bottom-up modeling anchored volume projections to county-level hospital infrastructure upgrade pipelines and tertiary center replacement cycles, while top-down analysis cross-checked against central fiscal transfer allocation patterns. Segmentation dimensions spanned product type, end user tier, technology platform, and clinical application, with CAGRs derived from installed base expansion rates and unit pricing trajectory assumptions. Helium supply volatility indices and NMPA review pathway efficiency metrics informed scenario-weighted outputs across the projection horizon.
Inputs from NMPA registration databases and provincial tender platforms were available through the study window; gaps in real-time hospital procurement decision rationale introduce uncertainty bands around vendor share assumptions. Forecasts reflect documented assumptions regarding fiscal transfer continuity and regulatory pathway streamlining. Material deviation in helium supply chain restructuring or centralized procurement mechanism redesign warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Argentina Computed Tomography Market
Medical Imaging
Veterinary Imaging Systems Market
Medical Imaging
Mexico Diagnostic Imaging Equipment Market
Medical Imaging
Open System MRI Market
Medical Imaging
X-Ray Flat Panel Detectors Market
Medical Imaging
Digital X-Ray Imaging Market
Medical Imaging
Multiphoton Microscopy Market
Medical Imaging
Meningitis Imaging Market
Medical Imaging
Spain Digital X-Ray Market
Medical Imaging
Advanced Computed Tomography (CT) Scanner Market
Medical Imaging
AI Fetal Ultrasound View Detection Software Market
Medical Imaging
Middle East and Africa Magnetic Resonance Imaging (MRI) Market
Medical Imaging
China Digital X-Ray Market
Medical Imaging
Global Image-Guided Radiation Therapy (IGRT) Market
Medical Imaging
Preclinical Brain Imaging Market
Medical Imaging
United States Diagnostic Imaging Market