
 Australia Dairy Alternatives Market | 2026-2036
Australia Dairy Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Dairy Alternatives Market Insights
Barista-trained labor is rotating through Australia's café sector at accelerating velocity, creating bottlenecks for oat milk frothing expertise that suppliers must address through equipment partnerships. Danone SA leverages its fortified beverage portfolio to anchor shelf presence in Coles and Woolworths. Sanitarium Health and Wellbeing Company sustains domestic manufacturing scale from its New South Wales base. Oatly Group AB competes through dedicated barista edition formulations tailored to Australian espresso culture.
Dairy alternatives encompass plant-derived beverages and food products formulated from nuts, grains, legumes, or seeds, typically achieving protein content between 0.5-4% and fat profiles adjusted through enzymatic processing or homogenization for functional parity with bovine milk. These products serve commercial foodservice operators and retail consumers seeking lactose-free, lower-saturated-fat, or ethically positioned nutrition options. Almond milk occupies the most mature position with established household penetration, while oat milk captures the fastest growth trajectory driven by café channel expansion and neutral flavor compatibility. Liquid form dominates volume throughput, though yogurt and creamer segments attract margin premiums through convenience positioning and dessert application versatility.
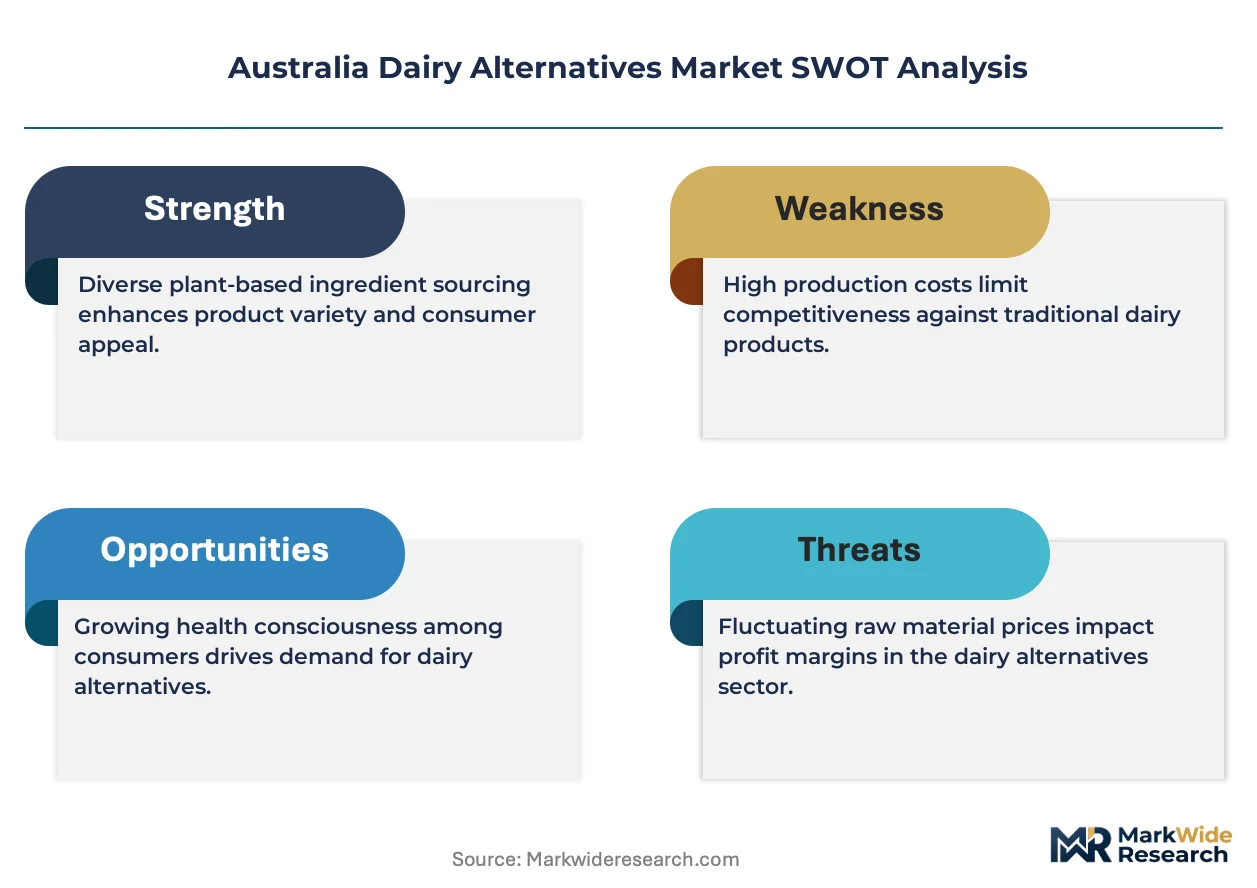
FSANZ governs compositional standards and nutrition claims enforcement, while the ACCC monitors misleading "dairy" terminology in advertising, collectively elevating compliance costs for imported brands. The ACCC's scrutiny of environmental claims additionally constrains how producers market water usage and carbon narratives. Stakeholders must track impending protein content threshold debates and decide whether to reformulate ahead of potential standard tightening or absorb label adjustment costs reactively.
Market Dynamics
FSANZ labelling reforms around "milk" descriptor restrictions are compressing product positioning flexibility while simultaneously elevating compliance investments across the Australian dairy alternatives sector.
Growth Catalysts
- Café Channel Expansion:Melbourne and Sydney espresso bars are normalizing oat milk as default milk options, creating visible demand anchors that penetrate household purchasing patterns through repeated exposure.
- FSANZ Compositional Standards:Regulatory clarity on permitted fortification levels enables suppliers to formulate with confidence around calcium and vitamin D additions that support nutrition parity claims.
- Enzymatic Processing Advances:Lipase and protease treatments now achieve fat globule size distributions matching bovine milk homogenization, improving mouthfeel acceptance among skeptical dairy consumers.
Market Restraints
- Oat Raw Material Concentration:Australian milling capacity for food-grade oats concentrates in South Australia and Victoria, exposing supply continuity to regional drought cycles and freight cost spikes.
- Protein Content Ceiling:Current extraction methods hit functional limits near 4% protein in oat bases, constraining nutritional positioning against dairy and soy alternatives in sports nutrition applications.
- ACCC Greenwashing Scrutiny:The regulator's intensified examination of water usage and carbon footprint claims forces marketing teams to retreat from environmental narratives that previously differentiated premium tiers.
Strategic Opportunities
- Queensland and Western Australia Underpenetration:Brisbane and Perth café markets show half the oat milk menu penetration of Melbourne-Sydney, presenting first-mover shelf allocation advantages for barista-edition suppliers.
- Precision Fermentation Convergence:Integration of recombinant protein production with existing plant bases enables animal-identical whey and casein fortification without lactose, opening pediatric and clinical nutrition channels.
- Direct-to-Office Subscription Channels:Workplace coffee station refreshment contracts bypass retail margin stacking and build habitual consumption through employer-subsidized placement.
Industry Challenges
- Barista Frothing Expertise Gap:Accelerating labor rotation through Australian cafés erodes accumulated oat milk steaming knowledge, forcing suppliers to maintain continuous training partnerships with equipment manufacturers.
- Organic Certification Timelines:Conversion periods for oat suppliers seeking Australian Certified Organic status extend 24-36 months, lagging behind demand spikes for clean-label positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Dairy Alternatives Market |
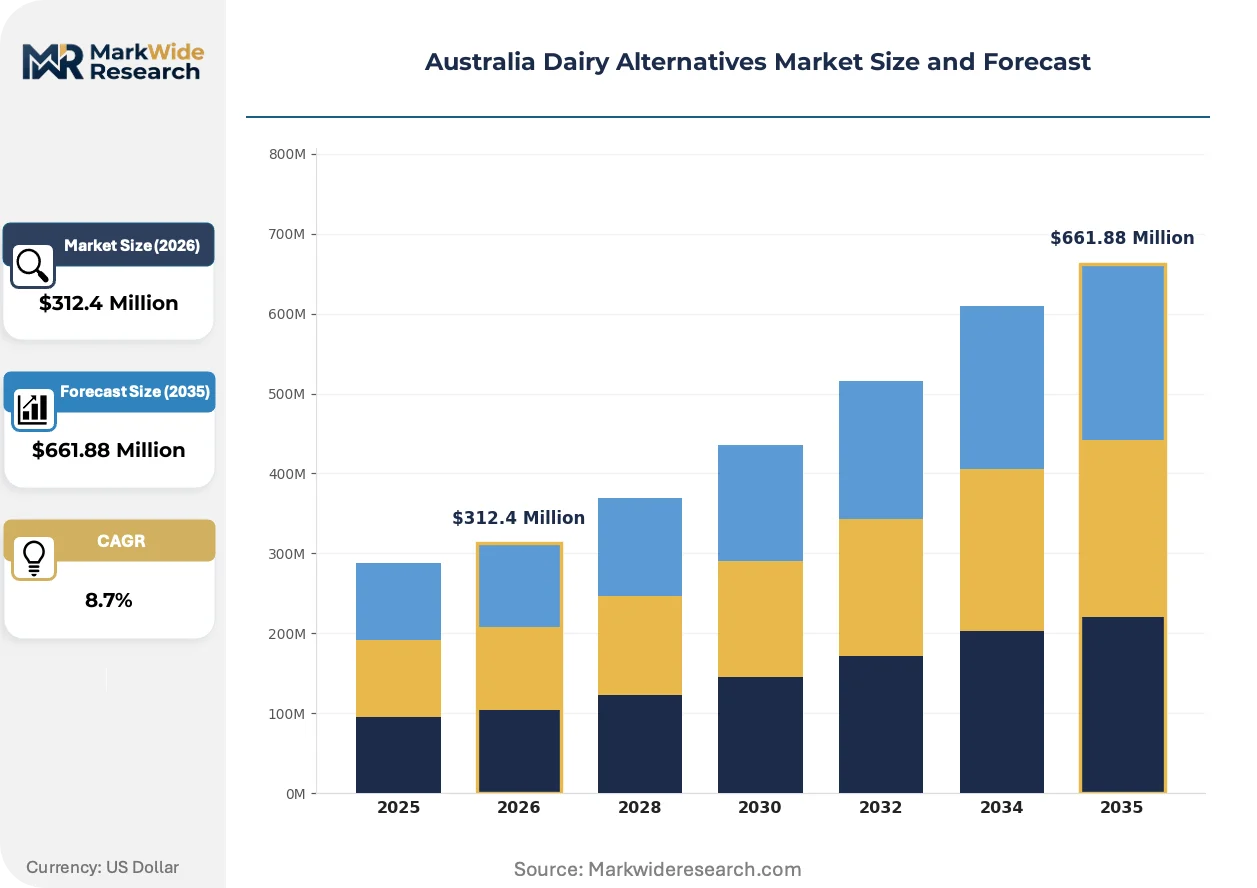
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Milk, Soy Milk, Oat Milk, Coconut Milk Form: Liquid, Powder, Creamer, Yogurt Distribution Channel: Online, Supermarkets, Specialty Stores, Health Stores End User: Households, Restaurants, Cafés, Food Producers |
| Companies Covered | Danone SA, Nestlé SA, Sanitarium Health and Wellbeing Company, Noumi Limited, Oatly Group AB, Blue Diamond Growers, PureHarvest, Califia Farms LLC, Dairy-Free Down Under, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Dairy Alternatives Market Trends and Innovations
Enzymatic modification and fermentation technologies are splitting the competitive landscape between commodity-acceptable taste profiles and premium functional positioning. This divergence reshapes where suppliers invest capital and which channels they prioritize.
High-pressure homogenization combined with lipid encapsulation is bifurcating the oat milk category. Specialty roasters in Sydney and Melbourne are adopting these formulations for latte art stability, while value-tier retail SKUs retain conventional processing to protect margin. The technology gap is compressing private-label suppliers into undifferentiated commodity positioning while enabling branded players to command café-exclusive premiums.
FSANZ's pending protein content threshold consultations are forcing reformulation roadmaps across the sector. Manufacturers must decide between pre-emptive protein fortification investments or reactive label adjustment costs. The draft standards most directly impact almond milk portfolios where natural protein levels sit below proposed minimums, pushing those suppliers toward blended nut-grain formulations.
Café procurement patterns are consolidating around single-source oat milk contracts with equipment bundling. Melbourne's independent roasters increasingly demand dedicated steam wand calibration and on-site barista certification as table stakes for supplier selection. This behavioral shift concentrates volume with vertically integrated players capable of delivering technical service alongside liquid product.
Australia Dairy Alternatives Market Segmentation
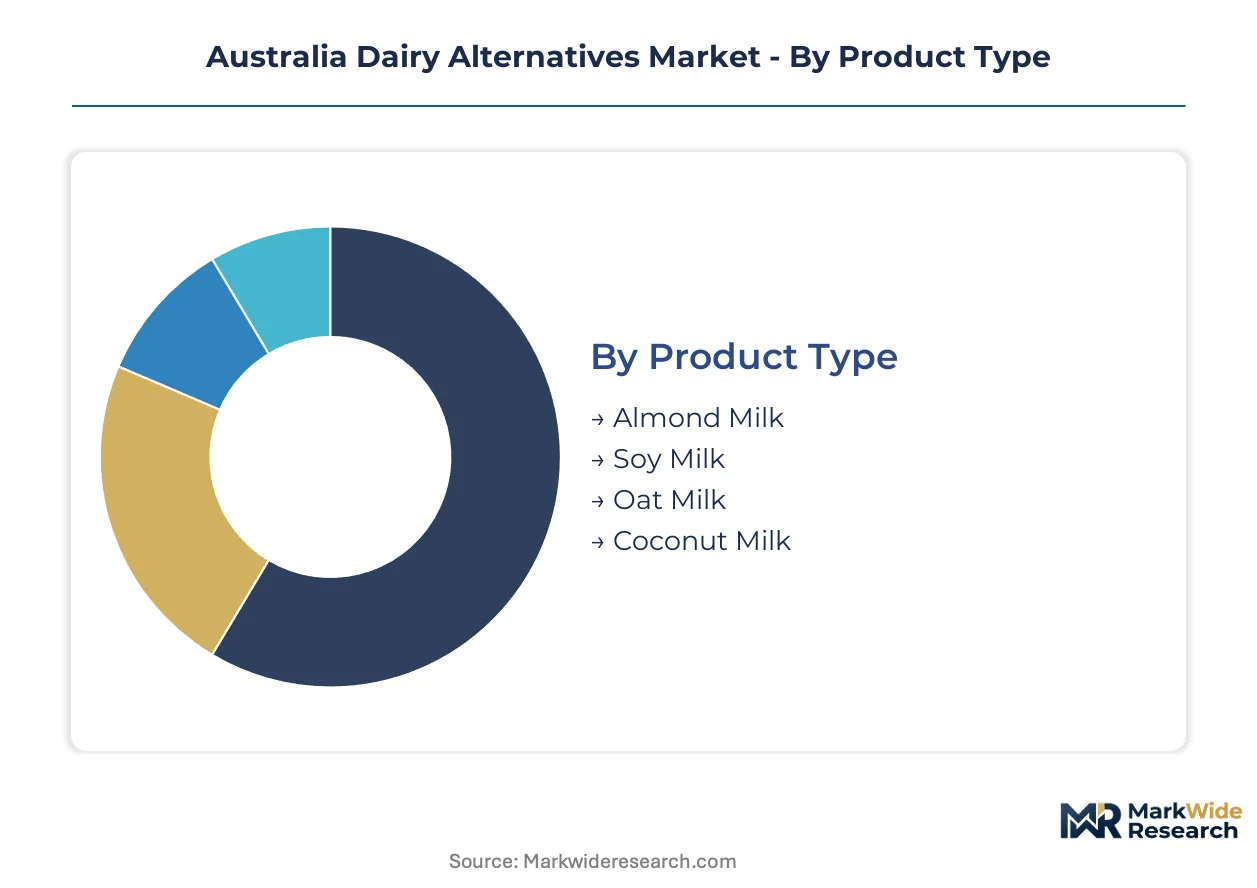
Segmentation in Australia's dairy alternatives market reveals how café channel dominance and FSANZ regulatory boundaries reshape profitability across product formats and distribution pathways. Understanding where margin pools concentrate enables suppliers to allocate reformulation and marketing investments against tightening compositional standards.
Product Type:
Margin pools concentrate in oat milk's barista-grade formulations where café exclusivity commands wholesale premiums, while almond milk's retail commoditization compresses shelf economics.
- Oat Milk:Neutral flavor profile and superior frothing stability position this segment as the default choice for Melbourne and Sydney espresso bars. Barista edition formulations with enzymatically modified lipid structures capture recurring café contracts through equipment bundling and on-site training support.
- Almond Milk:Established household penetration and longest shelf presence in Coles and Woolworths generate volume throughput, though protein content near 1% exposes suppliers to FSANZ's pending minimum threshold consultations. Blended nut-grain formulations are emerging as a defensive reformulation pathway.
- Soy Milk:Highest native protein content among plant bases supports sports nutrition positioning and clinical applications. Fortified variants with calcium and vitamin D additions maintain nutrition parity claims against dairy.
- Coconut Milk:Dessert and cooking applications in Southeast Asian cuisine clusters sustain demand in Sydney's western suburbs. Limited café adoption constrains premium pricing power relative to oat alternatives.
Oat milk holds installed capacity. Almond milk is rotating up the share rankings.
Form:
Volume throughput concentrates in liquid formats, though margin extraction favors convenience-positioned creamers and yogurt where enzymatic processing investments translate into dessert application versatility.
- Liquid:Dominates absolute volume through retail carton sales and foodservice bulk dispensing. High-pressure homogenization combined with lipid encapsulation now bifurcates the category between commodity-acceptable taste profiles and premium functional positioning for latte art stability.
- Creamer:Single-serve pods and barista-specific concentrates capture margin premiums through workplace coffee station contracts and hospitality procurement. Direct-to-office subscription channels bypass retail margin stacking while building habitual consumption.
- Powder:Extended shelf life supports export-oriented production from New South Wales manufacturing bases. Reconstitution quality gaps versus fresh liquid constrain household adoption outside camping and emergency preparation niches.
- Yogurt:Fermentation technology convergence with precision protein fortification opens pediatric and clinical nutrition channels. Australian Certified Organic status lags demand spikes due to 24-36 month conversion timelines for oat suppliers.
Liquid commands absolute volume. Creamer is climbing the fastest.
Distribution Channel:
Supermarket concentration in Coles and Woolworths determines shelf survival, while online and specialty channels enable clean-label positioning that escapes retail margin compression.
- Supermarkets:National duopoly shelf placement requires slotting fee negotiations and promotional calendar alignment. Danone SA and Sanitarium Health and Wellbeing Company leverage fortified beverage portfolios to anchor presence across refrigerated and ambient sets.
- Online:Direct-to-consumer subscriptions and marketplace platforms support niche positioning for organic and precision-fermented variants. Subscription bundling with equipment partnerships replicates café technical service in home settings.
- Specialty Stores:Independent grocers in Melbourne's inner north and Sydney's eastern suburbs curate premium tier assortments. Barista-trained staff provide category education that accelerates trial among skeptical dairy consumers.
- Health Stores:Practitioner-channel positioning for clinical nutrition and allergen-free applications. TGA-adjacent therapeutic claims require careful navigation to avoid ACCC scrutiny of misleading health assertions.
Supermarkets hold installed capacity. Online is gaining share fastest.
End User:
Café procurement consolidation around single-source oat milk contracts concentrates supplier power, while food producer demand for ingredient-grade bases diversifies revenue exposure beyond retail volatility.
- Cafés:Melbourne and Sydney espresso bars normalize oat milk as default options, creating visible demand anchors that penetrate household purchasing. Dedicated steam wand calibration and on-site barista certification emerge as table stakes for supplier selection among independent roasters.
- Households:Repeated café exposure drives retail trial and brand loyalty transfer. Queensland and Western Australia underpenetration relative to Melbourne-Sydney presents first-mover shelf allocation advantages.
- Restaurants:Menu integration for lactose-free and vegan positioning supports mid-tier dining differentiation. Volume concentration in group procurement contracts limits individual outlet supplier switching flexibility.
- Food Producers:Ingredient-grade bases for ice cream, bakery, and confectionery applications demand functional parity with bovine milk in emulsion stability and browning reactions. Enzymatic processing advances enable fat globule size distributions matching dairy homogenization.
Cafés hold installed capacity. Food producers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Melbourne and Sydney command wholesale premiums for barista-grade oat milk that Brisbane and Perth markets cannot yet match, creating a two-tier pricing architecture that suppliers exploit through geographic rollout sequencing.
New South Wales
Sydney's eastern suburbs and inner west sustain Australia's deepest café density, with single-source oat milk contracts now bundling equipment calibration and staff certification. FSANZ's Sydney office anchors national regulatory interpretation, accelerating compliance adaptation for fortified beverage portfolios. Sanitarium Health and Wellbeing Company's New South Wales manufacturing base supplies domestic production scale that reduces freight exposure to drought-affected South Australian oat milling.
Victoria
Melbourne's laneway espresso culture normalizes oat milk as default choice, penetrating household purchasing through repeated café exposure. The state's food-grade oat milling capacity concentrates in regional Victoria, exposing supply continuity to rainfall variability. Independent roasters in Brunswick and Fitzroy demand dedicated steam wand calibration as table stakes for supplier selection, consolidating volume with technically capable vendors.
Queensland
Brisbane café markets show half the oat milk menu penetration of Melbourne-Sydney, presenting first-mover shelf allocation advantages for barista-edition suppliers. Queensland's subtropical climate limits local oat cultivation, forcing reliance on interstate grain supply chains. Gold Coast and Sunshine Coast hospitality precincts are emerging as trial markets for workplace coffee station subscription channels that bypass retail margin stacking.
Western Australia
Perth's geographic isolation from eastern manufacturing centers elevates landed costs for liquid dairy alternatives, compressing retail margins unless suppliers establish local distribution partnerships. The state's mining sector drives fly-in-fly-out workforce patterns that sustain convenience-store and airport channel demand for long-life formats. Fremantle's specialty coffee scene lags Melbourne-Sydney by three to five years in oat milk normalization, extending the premium pricing window for early entrants.
South Australia
Adelaide's food-grade oat milling infrastructure supplies raw material to national beverage manufacturers, concentrating upstream supply risk during drought cycles. The state's grain belt variability directly impacts oat milk production economics for brands dependent on Australian-sourced inputs. Local café penetration remains shallow relative to population, suggesting latent demand expansion as Melbourne-Sydney consumption patterns diffuse.
Australia Dairy Alternatives Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with enzymatic processing specialists commanding café premiums while private-label suppliers defend retail volume through conventional homogenization. The market structures around three tiers: multinational fortified beverage portfolios anchoring supermarket duopoly placement, domestic manufacturers leveraging geographic proximity to reduce freight exposure, and specialist barista-edition formulators capturing hospitality exclusivity. Consolidation pressures intensify as FSANZ protein threshold consultations force reformulation investments that favor balance-sheet capacity. Dominant competitive moves include equipment bundling partnerships with café roasters and pre-emptive organic certification timelines that lock in clean-label positioning ahead of demand spikes.
Among multinational CPG conglomerates, Danone SA and Nestlé SA occupy positions defined by fortified beverage scale and supermarket slotting fee capacity. Sanitarium Health and Wellbeing Company anchors domestic manufacturing from its New South Wales base, representing the geographic-proximity archetype that reduces supply chain exposure to interstate freight volatility. Oatly Group AB exemplifies the barista-specialist tier, with dedicated espresso-culture formulations that capture recurring café contracts through technical service bundling rather than price competition alone.
| Leading Market Players |
|---|
| Danone SA |
| Nestlé SA |
| Sanitarium Health and Wellbeing Company |
| Noumi Limited |
| Oatly Group AB |
| Blue Diamond Growers |
| PureHarvest |
| Califia Farms LLC |
| Dairy-Free Down Under |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day oat inventory cycles at Victorian milling facilities compress pricing power for brands dependent on interstate grain flows, while barista-edition premiums in Sydney and Melbourne cafés offset freight cost volatility through equipment-bundled contracts. FSANZ protein threshold consultations add reformulation cost uncertainty that suppliers must price into forward contracts with Coles and Woolworths.
Pricing Analysis
The customization-premium spread between barista-edition oat milk and retail-standard formulations runs wide in Australian foodservice, with steam-wand-calibrated products commanding wholesale premiums through dedicated equipment partnerships. Three-tier pricing structure across premium, standard, and economy levels stratifies by enzymatic processing intensity and fortification grade. Cost compression in retail almond milk intensifies because FSANZ's pending protein minimums force blended nut-grain reformulation. Food producers sourcing ingredient-grade bases exhibit highest price sensitivity, while Melbourne independent roasters prioritize technical service over per-litre cost.
Supply Chain Analysis
South Australia and Victoria anchor food-grade oat milling for Australian beverage manufacturers, drawing from grain belts exposed to rainfall variability. New South Wales hosts Sanitarium's domestic production base, reducing freight exposure for eastern seaboard distribution. Supply chain risk centers on single-source vulnerability to drought cycles that disrupt raw material flows from South Australian suppliers. Distribution runs through supermarket duopoly shelf placement, with direct-to-office subscription channels emerging as bypass routes for margin preservation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Café procurement consolidation around single-source oat milk contracts signals platform-economics inflection, with equipment-software interoperability between steam wand calibration and supplier technical service locking in habitual volume.
For Market Incumbents: Consolidate barista training partnerships with equipment manufacturers to offset labor rotation erosion of frothing expertise. Lock in organic certification timelines ahead of demand spikes that outpace Australian Certified Organic conversion periods. FSANZ protein threshold tightening threatens almond milk portfolios, requiring pre-emptive blended formulation R&D to defend shelf position. For New Entrants and Emerging Players: Differentiate on Queensland and Western Australia geographic whitespace where Brisbane and Perth café penetration lags Melbourne-Sydney by half. Target workplace coffee station subscription channels that bypass Coles and Woolworths margin stacking. Precision fermentation convergence with plant bases offers pediatric nutrition positioning as a go-to-market angle absent from commodity oat milk. For Investors and Strategic Acquirers: Long-term, this sits as a nutrition-parity infrastructure play because enzymatic processing and fortification technology determine who captures clinical and sports nutrition channel expansion. Acquisition target archetype: barista-edition formulators with embedded equipment partnerships and New South Wales manufacturing footprint. Watch FSANZ protein standard finalization as inflection signal that triggers reformulation capex requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Barista Equipment Partnership | Steam wand calibration bundling locks in recurring café volume against competitor switching. |
| Organic Certification Acceleration | Australian Certified Organic status ahead of demand spikes captures clean-label premium tier. |
| Precision Fermentation Integration | Recombinant protein fortification opens pediatric nutrition channels beyond commodity positioning. |
| Direct-to-Office Subscription Launch | Workplace coffee station contracts bypass retail margin compression while building habitual consumption. |
| Queensland-Western Australia Expansion | First-mover shelf allocation in underpenetrated Brisbane-Perth markets secures volume before saturation. |
Research Methodology
Operator-level perspectives from café owners, barista trainers, Coles and Woolworths category buyers, and FSANZ regulatory affairs specialists anchored the qualitative base for this study. Primary interviews combined with secondary validation from FSANZ consultation papers, ACCC advertising guidance, Australian Bureau of Agricultural and Resource Economics grain production data, and supermarket promotional calendar disclosures. Bottom-up volume triangulation across café procurement patterns and retail scan data intersected with top-down category sizing.
Sensitivity analysis tested oat raw material cost volatility, protein threshold regulatory scenarios, and café channel penetration rates across the projection horizon. Segmentation dimensions modeled include product type, form, distribution channel, and end user, with regional café density as an industry-specific overlay. CAGRs derived from trend extrapolation anchored by named player volume disclosures and channel growth trajectories. Forecast inputs incorporated enzymatic processing adoption curves and precision fermentation regulatory pathway timelines.
Material uncertainties — FSANZ standard finalization timing, drought cycle severity in South Australian grain belts, and barista labor retention rates — sit outside the modeled envelope. Forecasts reflect assumptions around continued café channel normalization and protein fortification cost pass-through capacity. Recalibration cycles align with material shifts in regulatory consultation outcomes and interstate freight cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Low-Calorie Coconut Milk Market
Dairy Alternatives
Asia-Pacific Oat Milk Market
Dairy Alternatives
Saudi Arabia Dairy Alternatives Market
Dairy Alternatives
Global Soy Desserts Market
Dairy Alternatives
North America Drinkable Yogurt Market
Dairy Alternatives
South America Dairy Alternatives Market
Dairy Alternatives
Hemp Milk Market
Dairy Alternatives
Reduced Fat Coconut Milk Market
Dairy Alternatives
Dairy Alternatives Market
Dairy Alternatives
Peanut Milk Market
Dairy Alternatives
Protein Ice Cream Market
Dairy Alternatives
Legumes Plant-Based Milk Market
Dairy Alternatives
United States Coffee Creamer Market
Dairy Alternatives
Sesame Milk Market
Dairy Alternatives
Europe Dairy Alternatives Market
Dairy Alternatives
Europe Non-Dairy Cheese Market