
 South Korea Dairy Alternatives Market | 2026-2036
South Korea Dairy Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Dairy Alternatives Market Insights
South Korean oat milk production capacity is consolidating around domestic processors with imported grain supply agreements. Sahmyook Foods leverages its heritage in soy processing to anchor shelf presence across major retail banners. Maeil Co. Ltd sustains R&D intensity in enzymatic formulation, while Lotte Chilsung Beverage Co Ltd competes through chilled distribution infrastructure that reaches convenience store networks nationwide.
Dairy alternatives encompass plant-derived beverages formulated from legumes, cereals, or nuts through aqueous extraction, enzymatic hydrolysis, and homogenization to achieve protein dispersion and sensory parity with bovine milk; these products serve lactose-intolerant consumers, flexitarian households, and foodservice operators requiring stable foaming performance. Soy milk occupies the most mature position with established price benchmarks, yet oat milk generates the fastest velocity gains as barista-grade formulations penetrate cafe channels. Carton packaging dominates ambient retail, though pouch formats are gaining traction in online retail subscriptions where storage efficiency reduces last-mile costs.
MFDS enforces allergen labeling and nutritional claim verification for plant-based beverages, while KFDA-established standards for protein content and fortification levels determine shelf positioning and premium pricing eligibility. The Ministry of Food and Drug Safety's evolving stance on dairy terminology restrictions shapes how brands communicate functional benefits without infringing on dairy product definitions. Stakeholders must monitor regulatory clarity on novel protein sources and fortification ceilings as these boundaries will determine next-generation product viability and market access thresholds.
Market Dynamics
MFDS labeling requirements for allergen disclosure and nutritional claims are compressing formulation timelines and forcing domestic manufacturers to revalidate protein fortification protocols before shelf placement.
Growth Catalysts
- Cafe channel expansion:Specialty coffee shops in Seoul and Busan are standardizing barista-grade oat milk as a default option, creating pull-through demand for retail formats.
- MFDS fortification standards:Clarified protein content thresholds enable premium positioning for calcium and vitamin D enriched variants, rewarding R&D investment with shelf tier access.
- Enzymatic hydrolysis advances:Improved protein dispersion technology reduces sedimentation in ambient cartons, extending product stability and reducing return rates.
Market Restraints
- Imported oat grain dependency:Domestic processors rely on Nordic and Australian supply agreements, exposing margins to currency volatility and shipping cost spikes.
- Soy milk price anchoring:Mature category benchmarks cap oat milk premium capture, forcing brands to absorb higher input costs or sacrifice volume.
- MFDS dairy terminology restrictions:Functional benefit communication is constrained by evolving enforcement on "milk" descriptor usage, complicating marketing execution.
Strategic Opportunities
- Gyeonggi province penetration:Satellite cities surrounding Seoul show underdeveloped modern trade coverage relative to capital density, offering whitespace for chilled distribution expansion.
- Pouch format subscription channels:Online retail platforms are adopting storage-efficient packaging for recurring delivery models, reducing last-mile logistics costs.
- Novel protein source approval:MFDS regulatory clarity on emerging legume and seed bases would unlock next-generation formulation pipelines currently in pilot phase.
Industry Challenges
- Food technologist scarcity:Specialized expertise in enzymatic formulation and sensory masking is concentrated among legacy soy processors, constraining new entrant R&D velocity.
- Chilled infrastructure capex:Cold chain expansion into convenience store networks requires substantial capital outlay for temperature-controlled last-mile logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Dairy Alternatives Market |
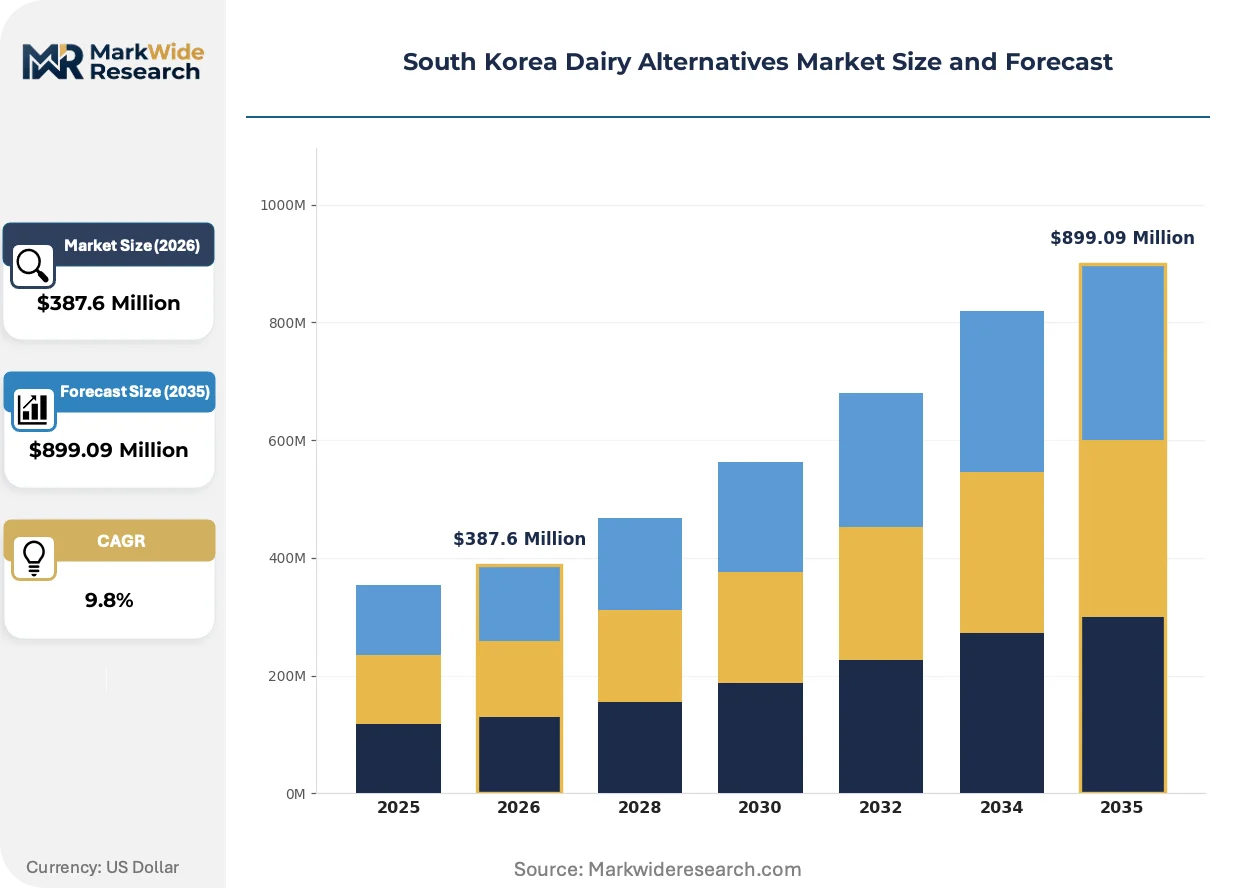
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $899.09 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Milk, Soy Milk, Oat Milk, Coconut Milk Packaging Type: Carton, Bottle, Pouch, Bag End User: Households, Restaurants, Cafes, Nutritional Shops Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Convenience Stores |
| Companies Covered | Sahmyook Foods, Bobsnu Co Ltd, Dr. Chung’s Food Co. Ltd, Yonsei Milk, Lotte Chilsung Beverage Co Ltd, Maeil Co. Ltd, Otsuka Holdings Co. Ltd, Seoul Milk, Namyang Dairy Products Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Dairy Alternatives Market Trends and Innovations
Barista-grade oat formulations are reshaping competitive positioning in South Korea's foodservice channel, while regulatory clarity on fortification and packaging innovation create parallel vectors for product differentiation.
Enzymatic lipid hydrolysis is overtaking conventional homogenization methods in premium oat milk production. Specialty coffee chains in Gangnam and Hongdae districts are adopting these formulations for superior microfoam stability. This technical shift is compressing the performance gap between plant-based and dairy options in latte art applications.
MFDS is tightening enforcement of allergen cross-contamination disclosure requirements for multi-product manufacturing facilities. Plant-based beverage producers must now segregate production lines or implement validated cleaning protocols. Soy-dominant manufacturers with legacy infrastructure face higher compliance costs than greenfield oat specialists.
Subscription-based replenishment models are displacing traditional supermarket stock-up behavior among Seoul metropolitan flexitarian households. Online platforms offering monthly pouch deliveries are capturing trial-to-loyalty conversion at rates exceeding conventional retail. This channel pivot is most pronounced among dual-income households in Seongnam and Goyang satellite cities.
South Korea Dairy Alternatives Market Segmentation
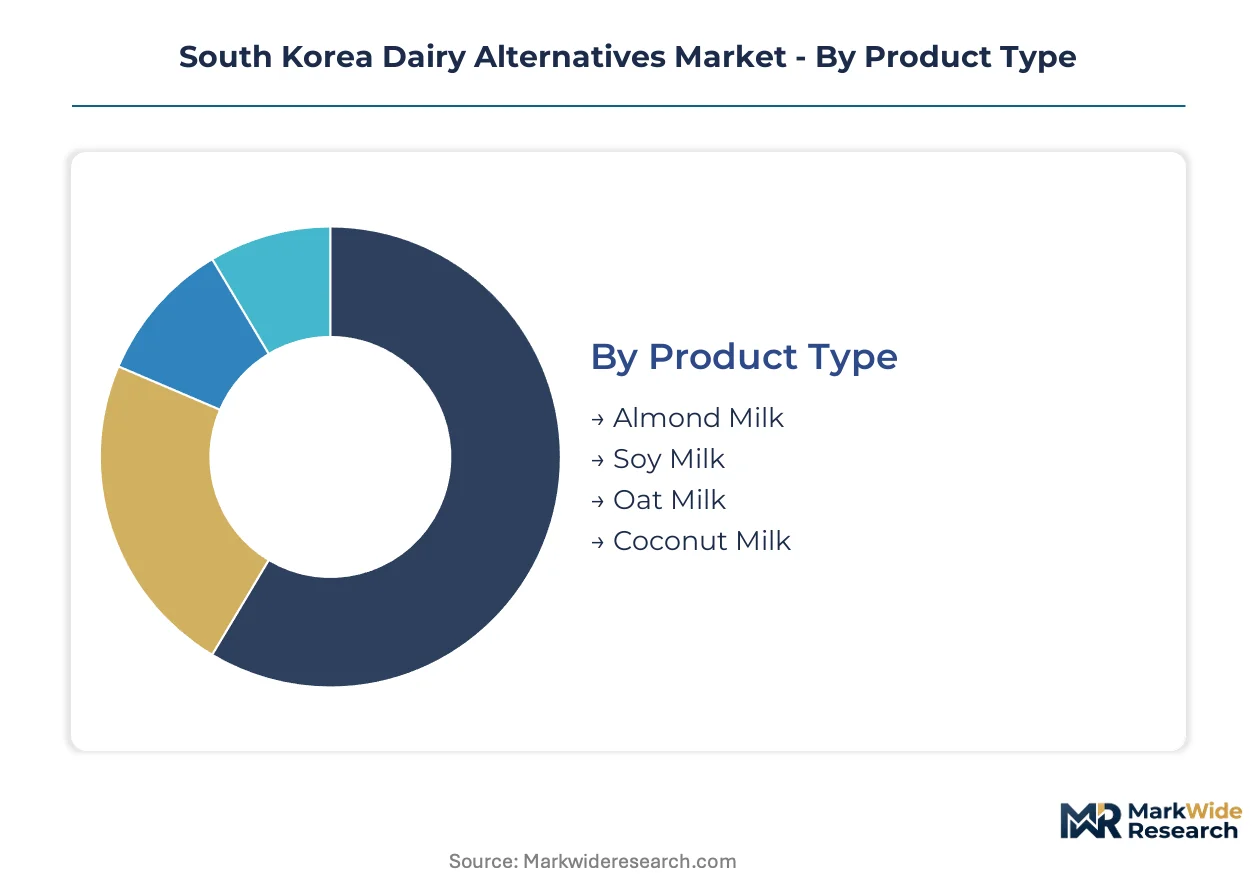
Segmentation in South Korea's dairy alternatives market reveals how product format, channel access, and end-use application determine margin capture and regulatory exposure. Manufacturers must align formulation investments with the specific performance requirements of each consumption context.
Product Type:
Soy milk functions as a standalone pantry staple with minimal preparation requirements, while oat milk embeds primarily in foodservice equipment and beverage preparation workflows.
- Soy Milk:Long-established category with enzymatic processing heritage and stable protein fortification protocols. Demand concentrates in multi-generational households across Gyeonggi province where price sensitivity and familiarity sustain volume. MFDS protein content thresholds favor legacy manufacturers with validated analytical methods.
- Oat Milk:Barista-grade formulations with lipid hydrolysis technology achieve microfoam stability matching dairy performance. Seoul cafe chains in Gangnam and Hongdae districts drive adoption as default milk alternatives, pulling retail trial through brand recognition.
- Almond Milk:Lower protein content limits premium positioning under MFDS fortification standards, constraining shelf placement in modern trade.
- Coconut Milk:Tropical flavor profile appeals to niche flexitarian segments and specialized nutritional applications with distinct sensory requirements.
Soy milk leads volumes today; oat milk is gaining share fastest.
Packaging Type:
Format selection tracks channel economics and storage constraints across ambient retail versus chilled distribution networks.
- Carton:Dominant ambient format with established filling line infrastructure and extended shelf stability. Supermarket banners in Seoul metropolitan area standardize carton placement for stock-up purchasing behavior.
- Pouch:Subscription platforms in Seongnam and Goyang satellite cities adopt flexible formats for last-mile efficiency and storage density in compact urban dwellings.
- Bottle:Chilled distribution requirement limits penetration to convenience store networks with temperature-controlled logistics.
- Bag:Foodservice bulk dispensing systems in restaurant chains reduce packaging waste and handling costs.
Carton holds the installed base; pouch formats are climbing the fastest.
End User:
User segments diverge sharply between at-home consumption with price anchoring and away-from-home occasions with performance premiums.
- Cafes:Specialty coffee operators demand consistent foaming performance and supply reliability for menu standardization. Barista-grade oat milk specifications now penetrate from Gangnam flagship locations to Busan neighborhood chains.
- Households:Dual-income families in satellite cities balance health positioning with subscription convenience, shifting replenishment patterns toward online platforms.
- Restaurants:Ingredient cost pressures favor soy milk in cooking applications where sensory differentiation matters less.
- Nutritional Shops:Fortification claims and allergen-free positioning command shelf space in health-focused retail with educated consumer bases.
Households anchor volume; cafes drive the steepest expansion trajectory.
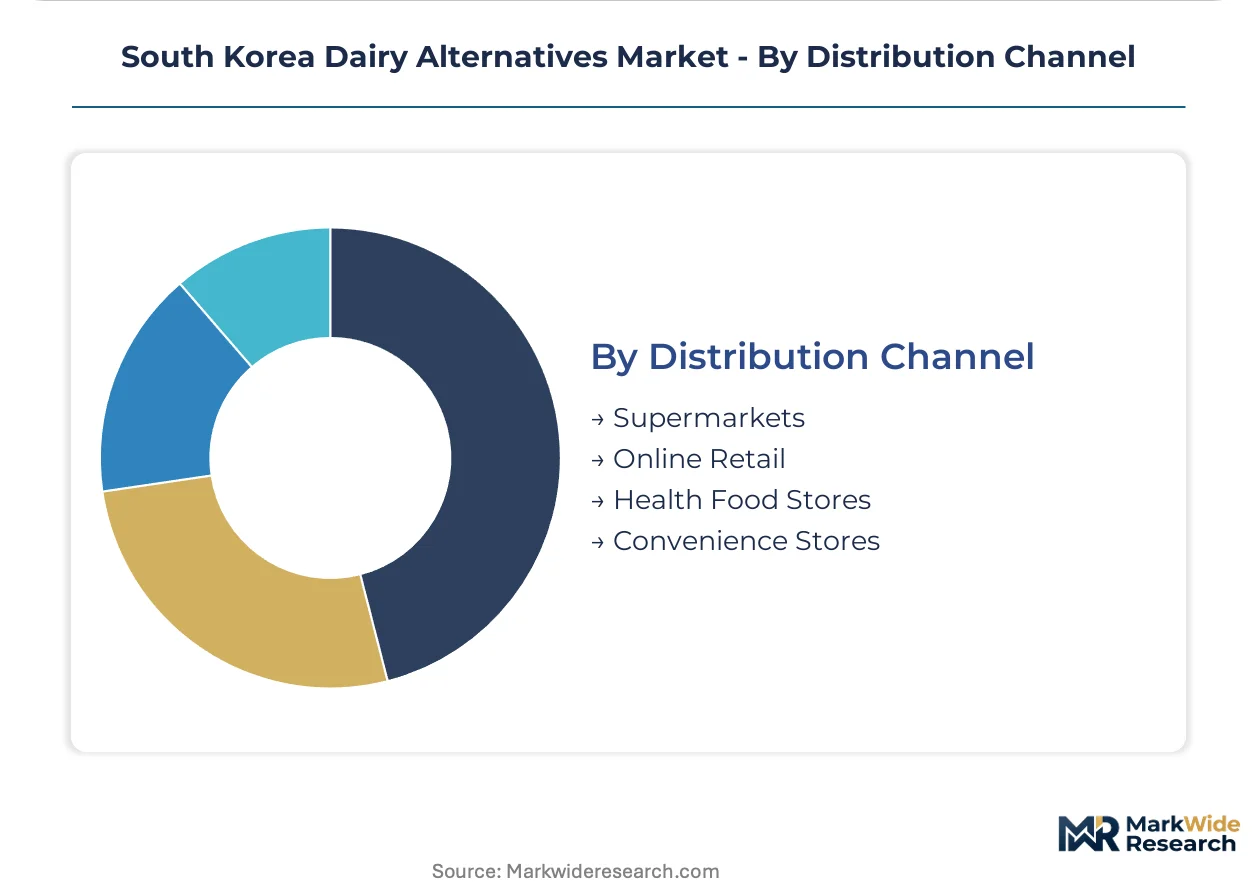
Distribution Channel:
Channel structure determines margin allocation between manufacturer investment in cold chain infrastructure versus platform fees and logistics efficiency.
- Supermarkets:Major retail banners in Seoul and Busan control shelf positioning through category management negotiations, favoring established suppliers with promotional funding capacity.
- Online Retail:Subscription mechanics capture recurring revenue with lower customer acquisition costs for pouch-format specialists targeting flexitarian households.
- Convenience Stores:Chilled distribution requirements and limited shelf space restrict assortment to high-velocity SKUs with proven turn rates.
- Health Food Stores:Premium positioning and educated staff enable higher-margin fortification variants that fail mainstream price benchmarks.
Supermarkets maintain volume leadership; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MFDS regulatory arbitrage is minimal within South Korea, yet sub-regional cost-of-compliance gaps emerge from cold chain infrastructure maturity and proximity to Seoul's regulatory filing centers. Production migrates toward Gyeonggi province where MFDS inspection protocols align with existing dairy processing facilities.
Seoul Capital Area
Seoul's Gangnam and Hongdae districts drive barista-grade oat milk adoption through specialty coffee chains standardizing plant-based defaults. MFDS headquarters proximity accelerates label approval timelines for new entrants. Convenience store networks in Jongno and Mapo gu deploy chilled distribution for single-serve formats targeting office workers.
Busan-Ulsan
Busan's Haeundae and Seomyeon commercial zones replicate Seoul cafe channel expansion with lower rent structures. Ulsan's industrial port infrastructure supports imported oat grain warehousing for domestic processors. Local distributors leverage Busan Port customs clearance efficiency to reduce Nordic supply lead times.
Gyeonggi Province
Satellite cities Seongnam and Goyang exhibit underdeveloped modern trade coverage relative to household density, creating whitespace for subscription platform penetration. MFDS manufacturing facility inspections favor Gyeonggi's converted dairy plants with existing HACCP certifications. Online retail pouch deliveries concentrate here for last-mile efficiency.
Daegu-Gyeongbuk
Daegu's traditional soy milk consumption patterns anchor volume in multi-generational households resistant to oat milk premiums. Regional health food retailers stock fortified variants meeting MFDS protein thresholds for elderly nutrition programs. Gyeongbuk's agricultural cooperatives explore domestic oat cultivation pilots to reduce import dependency.
Daejeon-Sejong
Sejong's government employee demographic drives demand for clean-label positioning aligned with public sector wellness initiatives. Daejeon's central logistics hub enables efficient distribution to secondary cities. Local universities host enzymatic research partnerships with domestic processors seeking formulation patents.
South Korea Dairy Alternatives Market Competitive Landscape
Seoul-based producers anchor the premium tier through chilled distribution infrastructure and cafe channel relationships; Gyeonggi province specialists hold volume positions via ambient carton scale and supermarket banner negotiations. Market structure consolidates around legacy dairy processors diversifying into plant-based lines alongside independent oat milk entrants. Three archetypes dominate: soy heritage conglomerates with enzymatic expertise, oat-focused greenfield specialists, and dairy cooperatives hedging category decline. Competitive moves concentrate on cold chain capex expansion into convenience networks and strategic partnerships with coffee equipment manufacturers for barista-grade co-development.
Within the soy heritage tier, Sahmyook Foods and Maeil Co. Ltd exemplify established processors leveraging decades of enzymatic formulation experience to defend shelf presence across major retail banners. Lotte Chilsung Beverage Co Ltd occupies a position bridging beverage conglomerate scale with chilled logistics capability reaching nationwide convenience store networks. These three anchors represent divergent strategic postures: religious-affiliated heritage brand equity, R&D-intensive formulation specialization, and distribution infrastructure dominance respectively.
| Leading Market Players |
|---|
| Sahmyook Foods |
| Bobsnu Co Ltd |
| Dr. Chung's Food Co. Ltd |
| Yonsei Milk |
| Lotte Chilsung Beverage Co Ltd |
| Maeil Co. Ltd |
| Otsuka Holdings Co. Ltd |
| Seoul Milk |
| Namyang Dairy Products Co. Ltd |
| Others |
Pricing and Supply Chain Analysis
Barista-grade oat milk premiums diverge sharply from ambient soy milk benchmarks, compressing distributor margins in Seoul's cafe channel while rewarding Nordic grain supply contracts with volume discounts. This tiered performance gap forces manufacturers to choose between enzymatic R&D investment for premium positioning or cost absorption in commodity segments.
Pricing Analysis
Distributor margins in convenience store networks absorb the heaviest compression as chilled logistics costs escalate. Three-tier pricing structure across premium, standard, and economy levels stratifies by protein fortification tier under MFDS thresholds, with calcium-enriched variants commanding shelf placement premiums. Pricing pressure stems from imported oat grain currency exposure. Households in Gyeonggi satellite cities exhibit highest price sensitivity, while Gangnam cafe operators prioritize foaming consistency over per-unit cost.
Supply Chain Analysis
Freight costs from Nordic and Australian grain terminals amplify working capital requirements for domestic processors without long-term offtake agreements. Supply concentrates in Sweden, Finland, and Australia for raw oat grain, while enzymatic processing equipment draws from German and Japanese specialists. Single-source vulnerability runs through Busan Port customs clearance bottlenecks. Distribution runs through chilled convenience store networks in Seoul and ambient carton supermarket channels nationwide.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's dairy alternatives market compounds steadily as cafe channel standardization of plant-based defaults locks in recurring demand across Seoul and Busan.
For Market Incumbents: Anticipate margin erosion from oat milk price anchoring by accelerating backward integration into Nordic grain supply partnerships. Sahmyook Foods and Maeil Co. Ltd should defend enzymatic formulation patents against greenfield entrants while expanding chilled distribution capex into Seongnam and Goyang convenience networks. MFDS fortification threshold adjustments represent the primary regulatory threat to premium tier eligibility. For New Entrants and Emerging Players: The premium-economy price gap in Gyeonggi province household subscriptions offers whitespace for pouch-format specialists. Target online retail replenishment models in Seongnam and Goyang where modern trade coverage lags household density. Partner with coffee equipment manufacturers for barista-grade co-development to bypass incumbent cafe channel lock-in. For Investors and Strategic Acquirers: Consolidation pressure builds where enzymatic formulation expertise concentrates among legacy soy processors with limited oat milk R&D velocity. Long-term viability favors greenfield oat specialists with validated MFDS protein fortification protocols and locked Nordic supply contracts. Watch MFDS regulatory clarity on novel legume protein sources as the inflection signal for next-generation formulation pipeline viability.| Strategic Initiative | Industry Significance |
|---|---|
| Barista-Grade Formulation Partnership | Coffee equipment co-development with Gangnam cafe chains secures default menu positioning. |
| Nordic Grain Supply Agreement | Long-term offtake contracts with Swedish and Finnish cooperatives hedge currency volatility exposure. |
| Chilled Distribution Expansion | Temperature-controlled logistics into Seongnam and Goyang convenience networks captures subscription-adjacent impulse purchases. |
| Enzymatic Processing Patent Filing | MFDS-validated protein dispersion protocols create defensible moats against commodity soy milk competitors. |
| Pouch Format Subscription Launch | Online retail replenishment models in compact Seoul metropolitan dwellings reduce last-mile cost per delivery. |
Research Methodology
Coverage spans Seoul Capital Area, Busan-Ulsan corridor, Gyeonggi province, and Daegu-Gyeongbuk region, with primary inputs from each. The analysis combines interviews with plant-based beverage R&D directors, MFDS regulatory affairs specialists, cafe chain procurement managers, and chilled logistics operators with secondary validation from MFDS labeling guidelines, Korean customs import records, and supermarket category management disclosures. Bottom-up volume triangulation against top-down market sizing ensures consistency across segmentation dimensions.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon. The modeling framework segments by product type, packaging format, end-user application, and distribution channel, with additional granularity on MFDS fortification tier compliance. CAGRs derive from historical trajectory analysis adjusted for cafe channel penetration curves and subscription platform adoption rates. Enzymatic hydrolysis technology maturation and Nordic grain supply contract renewal cycles serve as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for novel legume protein sources would alter the outlook. Forecasts reflect assumptions on MFDS regulatory clarity timelines and cafe chain standardization velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Oat Milk Market
Dairy Alternatives
North America Non-Dairy Ice Cream Market
Dairy Alternatives
Pet Milk Market
Dairy Alternatives
Hempseed Milk Market
Dairy Alternatives
Asia-Pacific Oat Milk Market
Dairy Alternatives
Canada Dairy Alternatives Market
Dairy Alternatives
Middle East and Africa Dairy Alternatives Market
Dairy Alternatives
United States Dairy Alternatives Market
Dairy Alternatives
Vegan Cheese Alternatives Market
Dairy Alternatives
Sugar-Free Soy Milk Powder Market
Dairy Alternatives
Peanut Milk Market
Dairy Alternatives
Non-Dairy Frozen Dessert Market
Dairy Alternatives
Lactose-Free Milk Market
Dairy Alternatives
Cheese Alternative Market
Dairy Alternatives
Almond Milk Market
Dairy Alternatives
Europe Non-Dairy Milk Market