
 Savory Yogurt Foods Market | 2026-2036
Savory Yogurt Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Savory Yogurt Foods Market Analytics
Clean-label fermentation technology is narrowing the gap between artisanal batch consistency and industrial scale production. Chobani LLC leverages its Greek yogurt infrastructure to extend into savory flavor platforms. Fage International S.A. anchors its positioning around Mediterranean authenticity and strained yogurt texture. Blue Hill Inc. specializes in vegetable-forward savory formulations that differentiate it from conventional sweet yogurt competitors.
Savory yogurt foods comprise cultured dairy products formulated with salt, herbs, spices, and vegetable inclusions rather than fruit or sweeteners, typically containing live active cultures and protein concentrations ranging from 10 to 20 grams per serving depending on straining intensity. These products serve as meal components, cooking ingredients, and standalone snacks across retail and food service channels. Greek Yogurt commands the largest product type position due to its structural stability and protein density, while Plant-Based Yogurt represents the fastest-expanding segment as oat and coconut bases overcome previous flavor limitations. Within flavor profiles, Herb-Infused varieties capture premium shelf space in specialty retail, whereas Spicy formulations gain traction through food service channels seeking menu differentiation.
USDA organic certification and FDA food labeling requirements shape product claims and manufacturing transparency for domestic producers, while EU regulations under EFSA and national dairy standards in France and Germany govern import access and ingredient nomenclature across European markets. FSMA preventive controls and HACCP protocols further constrain small-batch producers seeking national retail distribution. Stakeholders must monitor evolving plant-based dairy classification disputes and fermentation process validation standards as savory yogurt lines blur traditional category boundaries between fresh dairy, condiments, and functional foods.
Market Dynamics
Clean-label fermentation protocols and refrigerated cold-chain infrastructure upgrades are compressing the artisan-to-industrial gap, enabling scaled production of small-batch textured yogurts without compromising live culture viability or protein integrity.
Growth Catalysts
- FSMA Preventive Controls:The FDA's hazard analysis requirements are forcing consolidation among compliant producers, creating shelf space for validated clean-label brands that can document fermentation process controls.
- Food Service Menu Diversification:Grain bowl and Mediterranean fast-casual chains now specify savory yogurt as a base ingredient, pulling volume through commercial distribution channels.
- Mediterranean Culinary Migration:Levantine and Greek diaspora communities in the United States are normalizing strained yogurt as a savory meal component rather than a breakfast item.
Market Restraints
- Fresh Milk Input Volatility:Regional dairy commodity price swings compress margins for producers without backward integration into milk supply.
- Cold-Chain Concentration Risk:Third-party refrigerated logistics providers in North America face capacity constraints during peak summer months, limiting distribution radius for live-culture products.
- Plant-Based Substitution Threat:Oat and coconut yogurt bases are capturing shelf space in specialty retail, diverting capital from dairy savory innovation.
Strategic Opportunities
- Underpenetrated German Retail:EFSA fermentation process validation standards have kept many US producers out, creating first-mover advantage for compliant entrants.
- USDA Organic Certification Tailwind:Federal organic livestock standards are expanding certified milk supply, lowering input costs for organic savory yogurt lines.
- Direct-to-Restaurant Distribution:Bypassing traditional retail through chef-facing sales teams captures higher margins and locks in food service volume commitments.
Industry Challenges
- Fermentation Scientist Talent Gap:Industrial microbiology expertise capable of scaling artisan protocols remains concentrated in traditional dairy regions.
- Live Culture Certification Timelines:Third-party validation of CFU counts at end-of-shelf-life extends product launch cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Savory Yogurt Foods Market |
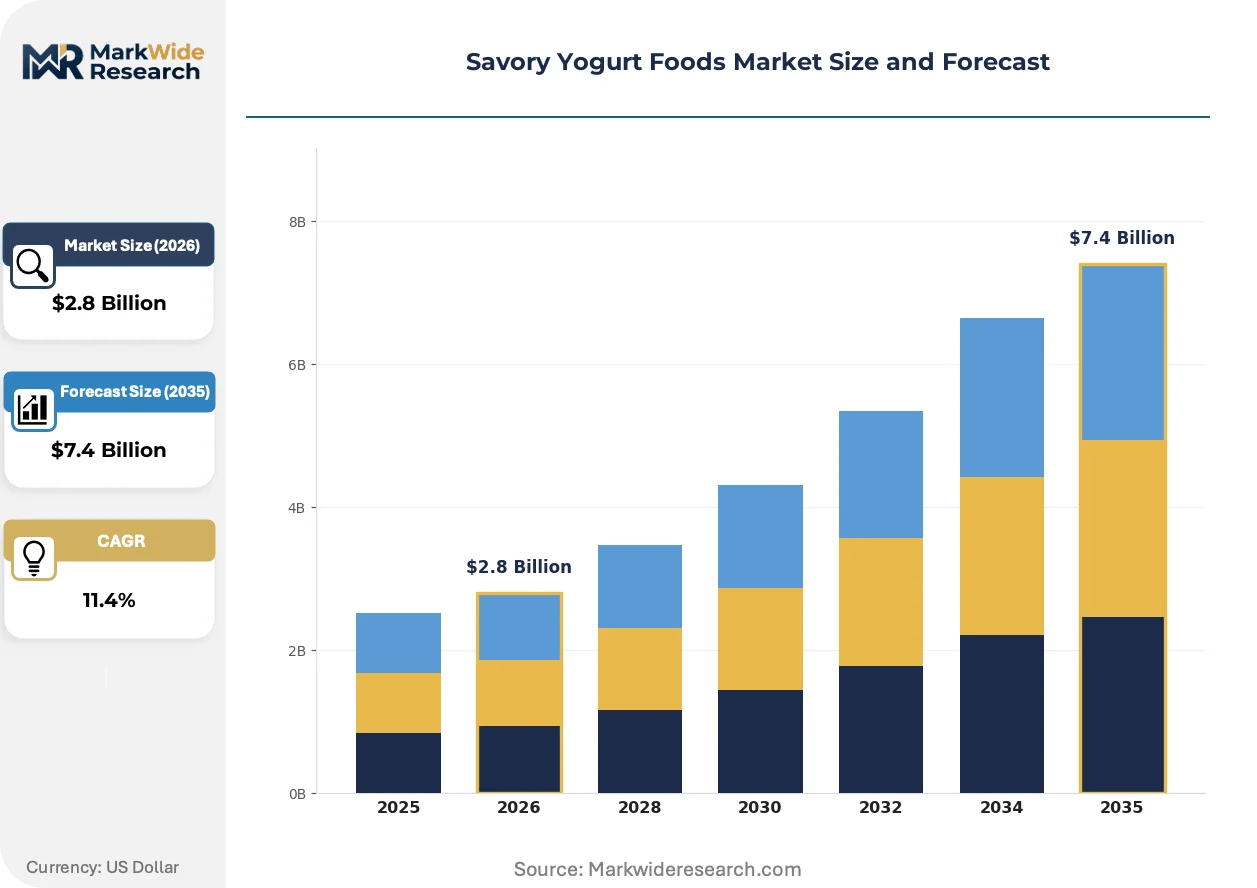
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Greek Yogurt, Low-Fat Yogurt, Organic Yogurt, Plant-Based Yogurt End User: Retail Consumers, Food Service, Health Clubs, Cafés Flavor Profile: Spicy, Herb-Infused, Savory-Sweet, Garlic Packaging Type: Plastic Cups, Glass Jars, Pouches, Bulk Packaging |
| Companies Covered | General Mills Inc., Chobani LLC, Chahani LLC, Stonyfield Farm, Inc., Sohha Savory Yogurt, Noosa Yogurt, Blue Hill Inc., La Terra Fina, Fage International S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Savory Yogurt Foods Market Evolving Landscape
Precision fermentation and strain-specific culture banking are rewriting the economics of textured yogurt production, while regulatory classification debates blur traditional boundaries between fresh dairy, condiments, and functional foods.
High-throughput culture screening platforms are rendering obsolete the guesswork of artisan batch consistency. Multi-strain starter libraries now allow industrial producers to replicate specific texture profiles previously achievable only through small-scale hand-straining. Food manufacturers in the United States are adopting these platforms fastest, compressing product development cycles from eighteen months to under six.
EFSA's evolving stance on fermentation process claims is reshaping European market access. The regulator's draft guidance on live culture quantification methods is forcing reformulation of products targeting multiple member states. French and German producers are responding by consolidating labeling around validated CFU thresholds rather than generic "contains live cultures" statements.
Chef-driven procurement is displacing traditional retail buyer gatekeeping for premium savory yogurt placement. Restaurant groups with dedicated dairy programs now specify texture, protein content, and salt levels directly with producers, bypassing distributor assortment decisions. This pattern concentrates most visibly in coastal US metropolitan markets where Mediterranean and Middle Eastern restaurant density is highest.
Savory Yogurt Foods Market Segmentation
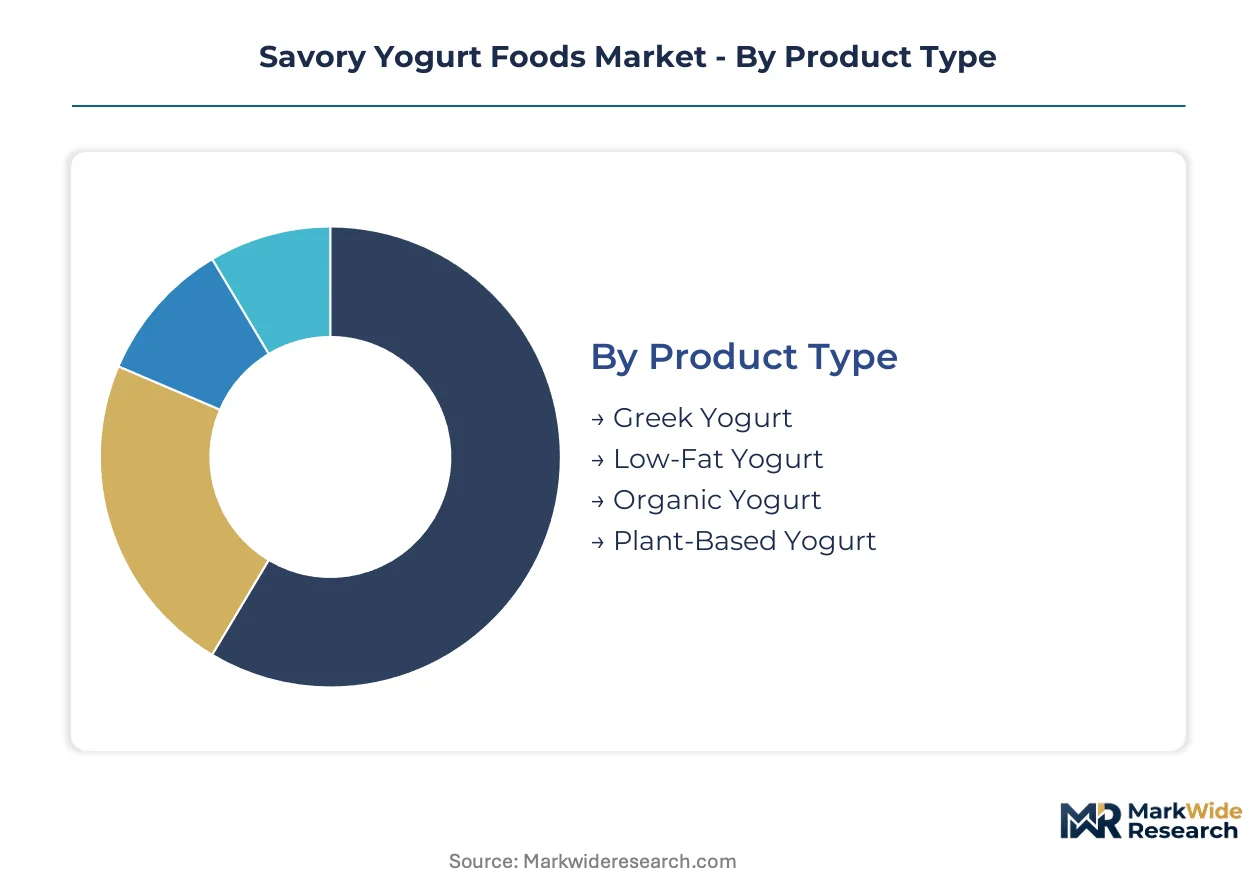
Savory yogurt manufacturers configure production lines around four distinct segmentation axes, each carrying different margin profiles and inventory velocity requirements. Product type and flavor profile decisions lock in fermentation protocols and shelf-life parameters, while end-user targeting determines cold-chain investment intensity and packaging format selection.
Product Type:
Greek Yogurt turns inventory fastest due to established consumer recognition and food service specification pull, whereas Plant-Based Yogurt cycles slowest as retailers test placement velocity before committing shelf space.
- Greek Yogurt:Strained to 10-20% protein concentration with structural stability that withstands heat application in cooking. Demand concentrates in United States food service channels where Mediterranean fast-casual chains specify it as a grain bowl base, driven by operator familiarity with Greek yogurt handling protocols.
- Plant-Based Yogurt:Fermented oat and coconut bases achieving flavor parity through precision culture selection. Specialty retail in coastal United States metropolitan markets shows strongest placement gains, constrained by EFSA fermentation validation requirements blocking European import expansion.
- Low-Fat Yogurt:Standard cultured dairy with reduced fat content, positioned for health-conscious retail consumers seeking lower-calorie meal components.
- Organic Yogurt:USDA-certified milk supply with documented livestock standards, commanding premium shelf placement in natural grocery channels.
Greek Yogurt anchors the volume base while Plant-Based Yogurt gains share at the steepest rate.
End User:
Cost tier separation runs deepest here, with Food Service procurement teams negotiating direct contracts at volume discounts while Health Clubs accept premium pricing for exclusive formulation rights.
- Food Service:Commercial kitchens and fast-casual chains purchasing bulk formats for menu integration. Grain bowl and Mediterranean restaurant density in United States coastal cities drives specification volume, constrained by FSMA preventive control documentation requirements for multi-unit operators.
- Retail Consumers:Individual households purchasing single-serve portions through grocery and specialty channels. United States supermarket dairy case placement competition intensifies as clean-label brands displace conventional sweet yogurt facings.
- Health Clubs:Fitness facilities and wellness centers offering savory yogurt as post-workout protein options.
- Cafés:Independent coffee shops and bakery-cafés incorporating savory yogurt into breakfast and lunch menus.
Food Service commands the procurement volume while Retail Consumers deliver the highest per-unit margins.
Flavor Profile:
Application context determines formulation intensity, with Spicy variants engineered for food service heat retention and Herb-Infused recipes calibrated for cold retail consumption.
- Spicy:Chili, harissa, and pepper-based formulations designed to maintain flavor impact when heated. Food service channels in United States Southwest and Southeast regions show strongest adoption, driven by operator demand for menu differentiation in competitive fast-casual markets.
- Herb-Infused:Dill, mint, za'atar, and other botanical inclusions requiring delicate culture handling to preserve volatile compounds. Specialty retail in United States Northeast and West Coast metropolitan areas captures premium placement, constrained by short shelf-life requirements for fresh herb integrity.
- Savory-Sweet:Balanced formulations bridging traditional sweet yogurt expectations with savory meal applications.
- Garlic:Allium-forward profiles positioned as condiment replacements and cooking ingredients.
Herb-Infused anchors the premium price tier while Spicy formulations expand most quickly through food service specification.
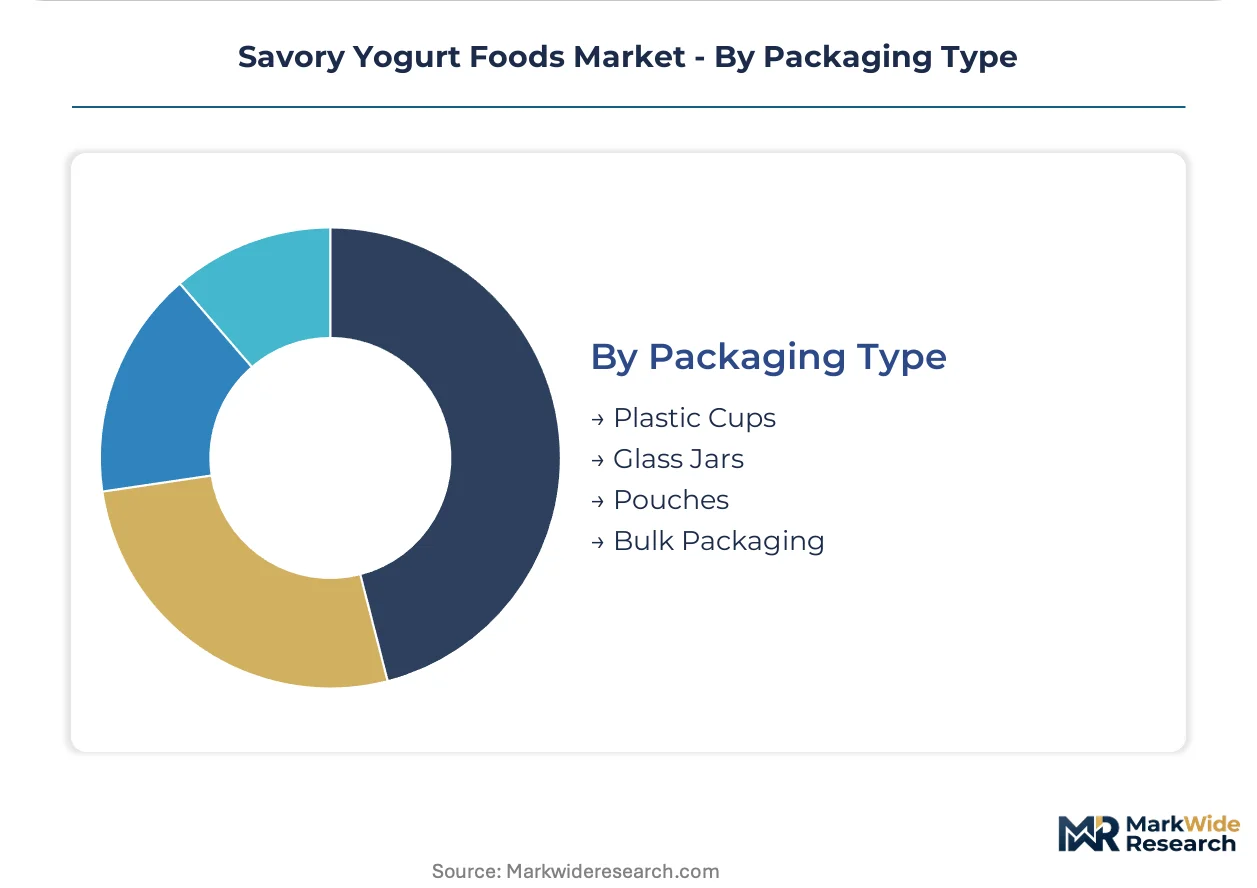
Packaging Type:
Supply concentration in cold-chain infrastructure shapes format viability, with Bulk Packaging requiring captive distribution networks while Plastic Cups leverage third-party refrigerated logistics.
- Plastic Cups:Single-serve polypropylene containers with modified atmosphere sealing. United States retail grocery distribution dominates volume, driven by consumer convenience expectations and established dairy case merchandising standards.
- Bulk Packaging:Food service pails and totes designed for commercial kitchen dispensing. Direct-to-restaurant distribution networks in United States metropolitan markets show fastest growth, constrained by FSMA preventive control requirements for repackaging operations.
- Glass Jars:Premium positioning format for specialty retail and gift channels.
- Pouches:Flexible packaging for portable consumption and outdoor recreation markets.
Plastic Cups maintain the broadest distribution footprint while Bulk Packaging climbs the fastest through food service bypass channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greek and Mediterranean culinary exports from the United States drive cross-border demand for savory yogurt formulations in Canada and Mexico, while European producers seek access to American clean-label fermentation technology.
United States
Mediterranean fast-casual chains and Levantine restaurant density in New York, Los Angeles, and Chicago generate specification pull for strained yogurt bases. FDA FSMA preventive controls and USDA organic livestock standards shape manufacturing compliance requirements. The Northeast corridor from Boston to Washington D.C. hosts the densest cluster of specialty dairy processors developing savory flavor platforms.
Germany
EFSA fermentation process validation standards and national dairy nomenclature rules constrain import access for non-EU producers. The country's central European logistics position attracts distribution investments from compliant savory yogurt brands seeking continental shelf placement. Bavaria and Baden-Württemberg concentrate artisan dairy heritage that informs clean-label production protocols.
France
Protected designation of origin frameworks and strict dairy classification systems limit how savory yogurt products position against traditional fromage blanc and faisselle. ANSM national health standards govern live culture claims on retail packaging. The Île-de-France region around Paris serves as the primary testing ground for novel savory dairy formats before national rollout.
United Kingdom
Post-Brexit regulatory divergence from EU dairy standards creates parallel compliance tracks for producers targeting both markets. London's restaurant density and Middle Eastern culinary influence drive chef-driven procurement of savory yogurt bases. The Southeast England logistics corridor handles refrigerated distribution for live-culture products entering British retail.
Canada
Health Canada dairy regulations and bilingual labeling requirements add compliance layers for American exporters. Health clubs and fast-casual chains in Toronto and Vancouver represent the strongest demand concentration for high-protein savory meal components. The Ontario-Quebec dairy belt supplies domestic milk inputs for regional savory yogurt production.
Savory Yogurt Foods Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented shelf space in retail dairy cases and food service procurement. The vendor base separates into three tiers: multinational dairy conglomerates with existing yogurt infrastructure, mid-scale clean-label specialists with fermentation expertise, and artisan batch producers with regional distribution. Consolidation pressure from FSMA compliance costs favors validated producers with documented process controls. Competitive moves concentrate on direct-to-restaurant distribution bypass and precision fermentation technology licensing.
Within the infrastructure-leveraging tier, General Mills Inc. and Chobani LLC occupy positions that exemplify scale advantages in savory platform extension. Fage International S.A. anchors the Mediterranean authenticity archetype with strained yogurt heritage. Blue Hill Inc. represents the vegetable-forward formulation specialist segment that differentiates through culinary rather than conventional dairy positioning.
| Leading Market Players |
|---|
| General Mills Inc. |
| Chobani LLC |
| Chahani LLC |
| Stonyfield Farm, Inc. |
| Sohha Savory Yogurt |
| Noosa Yogurt |
| Blue Hill Inc. |
| La Terra Fina |
| Fage International S.A. |
| Others |
Value Network & Pricing Analysis
The Northeast dairy processing corridor from Boston to Washington D.C. concentrates artisan-scale fermentation capacity that feeds pricing power to validated clean-label brands. Cold-chain infrastructure density in this cluster enables premium shelf placement that commodity yogurt producers cannot replicate. USDA organic certification tiers and FSMA preventive control documentation separate price bands across retail and food service channels.
Pricing Analysis
Clean-label fermentation technology separates current-generation savory yogurts from prior-generation commodity sweet yogurts and next-generation precision-fermented alternatives. Three-tier pricing structure across premium, standard, and economy levels anchors on certification grade and volume scale. Price differentiation centers on USDA organic livestock standards and FSMA preventive control documentation. Pricing pressure stems from oat and coconut plant-based substitutes capturing specialty retail shelf space. Food service procurement teams demonstrate lowest price sensitivity due to menu differentiation value, while retail consumers in conventional grocery channels exhibit highest elasticity.
Supply Chain Analysis
Extended payment terms from third-party refrigerated logistics providers strain working capital for small-batch producers seeking national distribution. Milk supply concentrates in the United States, Germany, and France. Raw material dependencies center on fresh milk inputs, live active culture strains, and specialty herb and spice inclusions. Single-source vulnerability runs through concentrated third-party cold-chain capacity during peak summer months. Distribution runs through direct-to-restaurant bypass networks and traditional retail dairy case placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Savory yogurt functions as a platform-economics inflection where chef-driven procurement ecosystems displace traditional retail buyer gatekeeping. Interoperability between fermentation protocols and food service kitchen systems determines competitive positioning.
For Market Incumbents: Entrench fermentation scientist talent through captive hiring in the Northeast corridor and backward integration into USDA-certified organic milk supply. Lock in multi-year direct-to-restaurant contracts before precision fermentation technology commodifies texture profiles. Threat from plant-based substitutes intensifies as oat and coconut bases achieve flavor parity. For New Entrants and Emerging Players: Build out EFSA-compliant production capacity for German retail penetration, where validation standards have excluded American competitors. Underpenetrated Bavaria and Baden-Württemberg markets offer first-mover shelf space. Chef-facing sales teams in coastal United States metropolitan markets provide the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a fermentation-platform play because precision culture banking and high-throughput strain screening will consolidate value capture among technology-enabled producers. Target acquisition archetype: mid-scale clean-label specialists with documented FSMA preventive controls and existing food service volume commitments. Signal to watch: EFSA final guidance on live culture quantification methods as European market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Technology Licensing | Chobani LLC and General Mills Inc. leverage existing Greek yogurt infrastructure to extend into savory platforms. |
| Direct-to-Restaurant Distribution Buildout | Bypassing traditional retail captures higher margins and locks in food service volume commitments from Mediterranean fast-casual chains. |
| EFSA Compliance Investment | Validation against European fermentation process standards opens continental shelf placement for compliant American producers. |
| USDA Organic Certification Expansion | Federal organic livestock standards expand certified milk supply, lowering input costs for organic savory yogurt lines. |
| Chef-Driven Procurement Partnerships | Restaurant groups with dedicated dairy programs now specify texture and protein content directly with producers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA FSMA guidance documents, USDA organic livestock standards, and EFSA fermentation process draft guidance. Primary interviews incorporated fermentation scientists at specialty dairy processors, procurement directors at Mediterranean fast-casual chains, category buyers at natural grocery retailers, and cold-chain logistics operators. Secondary validation drew from trade customs data, SEC 10-K filings of publicly traded dairy conglomerates, and refrigerated transportation capacity reports. Bottom-up segment sizing triangulated against top-down market value estimates.
Forecast inputs span product type segmentation across Greek, plant-based, low-fat, and organic yogurt; flavor profile stratification between herb-infused, spicy, savory-sweet, and garlic variants; and end-user channels covering food service, retail consumers, health clubs, and cafés. CAGRs were derived from regression analysis against historical dairy category growth patterns and protein-forward food adoption curves. Industry-specific inputs include live culture viability thresholds and refrigerated shelf-life parameters.
Stress conditions across fresh milk commodity price volatility, cold-chain capacity constraints, and plant-based substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory stability and fermentation technology diffusion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Reduced Fat Coconut Milk Market
Dairy Alternatives
Middle East and Africa Dairy Alternatives Market
Dairy Alternatives
Rice Milk Market
Dairy Alternatives
United Kingdom Dairy Alternatives Market
Dairy Alternatives
Dairy-Free Creams Market
Dairy Alternatives
Low Fat Coconut Milk Market
Dairy Alternatives
United States Oat Milk Market
Dairy Alternatives
Camel Milk Products Market
Dairy Alternatives
Europe Non-Dairy Milk Market
Dairy Alternatives
Australia Non-Dairy Milk Market
Dairy Alternatives
South America Dairy Alternatives Market
Dairy Alternatives
Global Soy Desserts Market
Dairy Alternatives
Cheese Analogue Market
Dairy Alternatives
Vegan Butter Market
Dairy Alternatives
Chickpea Milk Market
Dairy Alternatives
Yogurt Alternative Market