
 India Life and Non-Life Insurance Market | 2026-2036
India Life and Non-Life Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
India Life and Non-Life Insurance Market Foresight
Digital infrastructure is pivoting traditional paper-based policy issuance toward API-driven underwriting platforms. SBI Life Insurance leverages its bancassurance network to dominate semi-urban penetration. HDFC Life Insurance sustains margin density through proprietary term-life pricing engines. ICICI Lombard General Insurance competes on motor-claims automation, reducing loss-adjustment expenses.
India life and non-life insurance encompasses risk-pooling contracts where insurers collect premiums to indemnify policyholders against mortality, morbidity, property, or liability losses, with solvency ratios regulated at 150% minimum capital adequacy. The sector transfers catastrophic risk from individuals and enterprises to institutional balance sheets, enabling long-term capital formation through statutory investment mandates in government securities. Term Life and Health coverage command the deepest premium pools, while Unit Linked products attract equity-oriented retail capital. Bancassurance channels anchor rural distribution, though Online Sales are capturing metro-centric millennials with instant gratification.
IRDAI mandates digital sandbox compliance for insurtech entrants, while RBI oversees bancassurance capital buffers through joint-venture equity norms. SEBI regulates Unit Linked investment components under mutual-fund disclosure standards, creating overlapping jurisdictional scrutiny. Stakeholders must monitor how embedded insurance APIs in UPI payment flows reshape customer acquisition economics and regulator attention.

Market Dynamics
API-driven underwriting platforms are compressing policy-issuance cycles from weeks to minutes, forcing incumbent insurers to rebuild legacy core systems or cede metro millennials to insurtech entrants. IRDAI's digital sandbox mandates and solvency margin hikes are simultaneously accelerating compliance costs and lowering barriers for technology-native competitors.
Growth Catalysts
- Rural bancassurance expansion:SBI's branch network in semi-urban Maharashtra and Karnataka channels term-life products through Jan Dhan-linked accounts, penetrating households previously outside formal coverage.
- IRDAI digital disclosure norms:Mandatory real-time solvency reporting via API feeds increases transparency, reducing information asymmetry between underwriters and reinsurance counterparties.
- Health coverage demand concentration:Karnataka's hospital density and diagnostic infrastructure concentration attracts retail premium flows seeking cashless network access.
Market Restraints
- 150% solvency margin floor:IRDAI's capital adequacy requirement locks substantial funds in government securities, constraining product innovation budgets and equity-linked product development.
- Actuarial talent scarcity:India's specialized mortality-table modeling expertise concentrates in Mumbai and Bangalore, creating hiring bottlenecks for tier-two insurers.
- Legacy core system debt:COBOL-based policy administration platforms at established insurers resist API integration, inflating IT modernization capex requirements.
Strategic Opportunities
- UPI-embedded microinsurance:Real-time premium collection via payment rail APIs opens sub-₹500 annual policies for gig-economy workers in tier-three cities.
- SEBI-ULIP convergence:Unit-linked investment components falling under mutual-fund disclosure standards create cross-selling openings with wealth-management distributors.
- Ayushman Bharat gap coverage:Supplementary private policies targeting procedures excluded from the national health scheme capture out-of-pocket spending in Tamil Nadu and Gujarat.
Industry Challenges
- Fraud-detection model deployment:Motor-claims image-recognition systems require labeled training datasets that Indian insurers lack, forcing reliance on third-party vendors.
- Multi-regulator jurisdictional overlap:IRDAI, RBI bancassurance norms, and SEBI investment disclosure requirements create compliance mapping complexity for hybrid products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Life and Non-Life Insurance Market |
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $392.63 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Term Life, Whole Life, Endowment, Unit Linked Distribution Channel: Direct Sales, Brokers, Bancassurance, Online Sales End User: Individuals, Corporates, SMEs, Government Entities Coverage Type: Health, Motor, Property, Liability |
| Companies Covered | SBI Life Insurance, HDFC Ergo General Insurance, Life Insurance Corporation of India, Tata AIG General Insurance, ICICI Lombard General Insurance, HDFC Life Insurance, Bajaj General Insurance, New India Assurance, ICICI Prudential Life Insurance, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Life and Non-Life Insurance Market Shifts & Advancements
Telematics and wearable data streams are rewiring risk-assessment methodologies, shifting underwriting from retrospective mortality tables to real-time behavioral monitoring. This sensor-data integration is compressing pricing cycles and enabling dynamic premium adjustments.
Telematics-enabled motor insurance is converging with smartphone-based driving-behavior analytics. Fleet operators and ride-hailing platforms in Bangalore and Hyderabad are adopting usage-based coverage models. This technology convergence is enabling per-kilometer pricing that compresses traditional annual-premium structures and displaces fixed-rate motor policies.
IRDAI's digital sandbox framework mandates insurtech entrants to demonstrate API interoperability before market entry. The regulation forces established insurers to expose legacy policy-administration systems through standardized interfaces. Health and motor segments face the steepest compliance curves, with Maharashtra-based underwriters investing most aggressively in sandbox certification.
Millennial buyers are bypassing agent-mediated channels for direct-to-consumer platforms offering instant policy issuance. Metro-centric customers in Mumbai and Delhi are substituting bancassurance relationships with app-based comparison engines. This channel disintermediation is most visible among term-life purchasers under age 35, where online sales now dominate premium collection flows.
India Life and Non-Life Insurance Market Segmentation
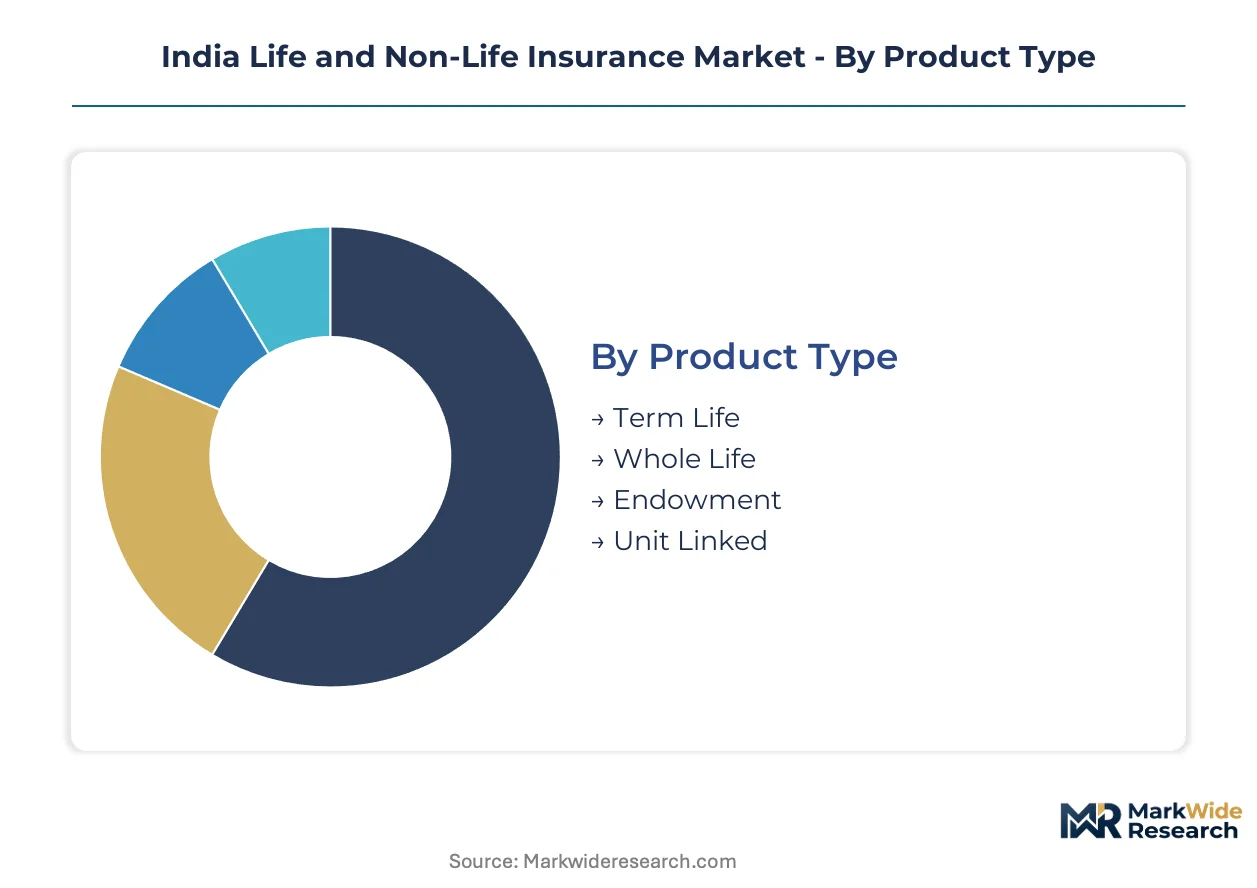
Insurance purchasing in India follows distinct decision pathways shaped by risk tolerance, liquidity constraints, and channel accessibility. Segment boundaries blur as hybrid products emerge, yet each category maintains unique margin profiles and regulatory treatment.
Product Type:
Premium outlay and investment linkage drive buyer selection across life insurance categories.
- Term Life:Pure risk coverage with no maturity benefit commands the largest premium pool among retail buyers. Maharashtra and Karnataka households favor this structure for income-protection needs amid rising nuclear-family prevalence.
- Unit Linked:Equity-linked investment components attract metro millennials seeking market participation alongside mortality coverage. SEBI disclosure mandates create compliance overlap that constrains product complexity.
- Whole Life:Lifelong coverage with guaranteed death benefits appeals to estate-planning objectives in tier-two cities.
- Endowment:Savings-cum-protection hybrids retain traction among risk-averse buyers in semi-urban markets.
Volume sits with Term Life; growth tilts toward Unit Linked.
Distribution Channel:
Geographic reach and customer demographics determine channel economics for insurers.
- Bancassurance:SBI's Jan Dhan-linked account penetration channels term-life products to previously unbanked rural households. RBI joint-venture equity norms govern capital buffers for bank-insurer partnerships.
- Online Sales:API-driven platforms capture metro-centric millennials under age 35 seeking instant policy issuance. IRDAI digital sandbox mandates accelerate insurtech entry into this channel.
- Direct Sales:Agent-mediated relationships persist among older buyers requiring advisory support for complex products.
- Brokers:Corporate risk placement and SME commercial coverage flow through independent intermediaries with specialized underwriting relationships.
Bancassurance dominates premium collection; Online Sales expand most quickly.
End User:
Risk exposure scale and purchasing sophistication separate buyer categories.
- Individuals:Retail households seeking mortality, health, and asset protection constitute the deepest premium pool. Karnataka's hospital density concentrates health coverage demand among this segment.
- Corporates:Group term-life and health policies for employee benefits leverage scale pricing. IRDAI solvency margin requirements apply differentially to group versus individual blocks.
- SMEs:Property and liability coverage for small enterprises remains underpenetrated outside major commercial centers.
- Government Entities:Public-sector undertakings and state departments procure coverage through tender processes with specialized compliance requirements.
Individuals anchor premium volume; Corporates offer margin stability.
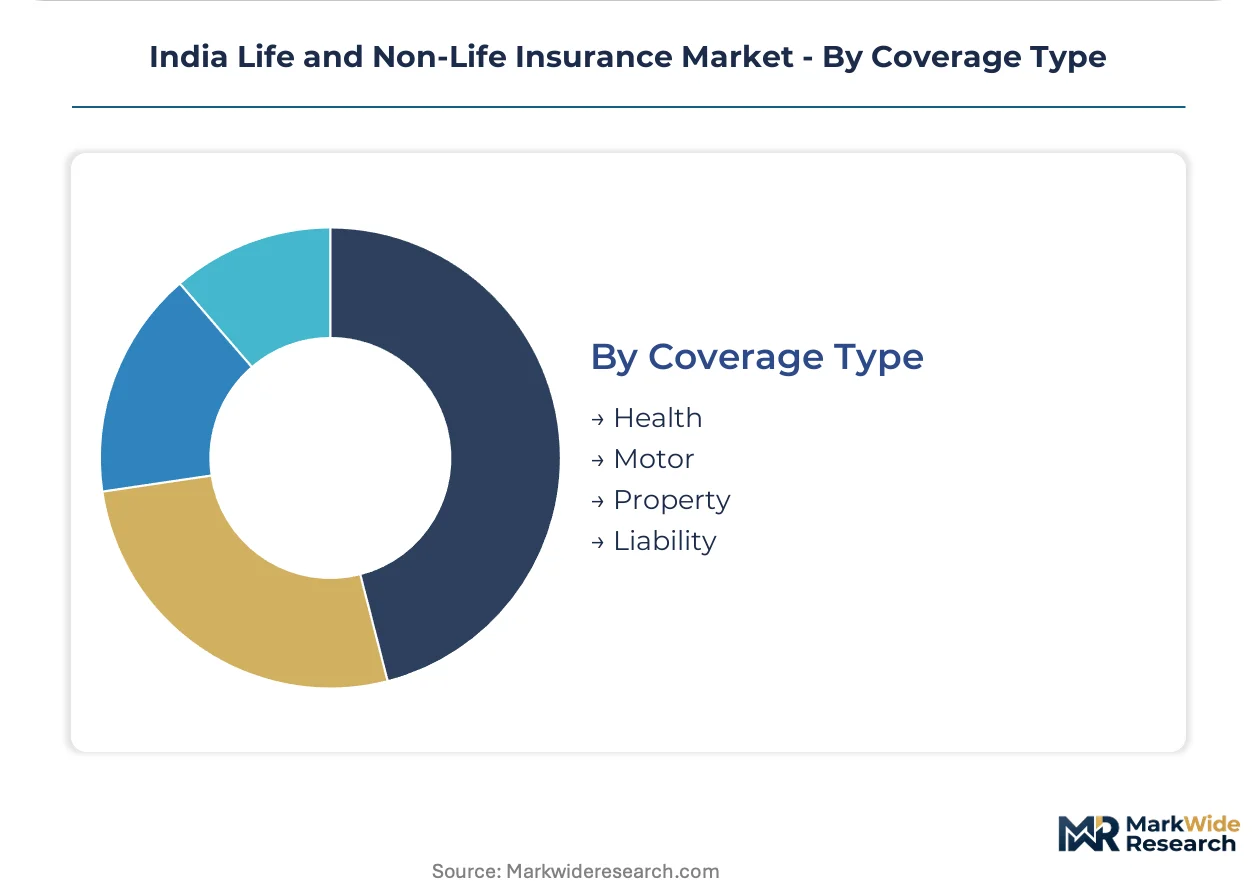
Coverage Type:
Loss event frequency and severity shape underwriting methodology and capital allocation.
- Health:Hospitalization and critical illness coverage commands expanding retail flows as out-of-pocket medical spending rises. Cashless network access drives preference for insurers with dense provider tie-ups in Tamil Nadu and Gujarat.
- Motor:Telematics-enabled usage-based models are displacing fixed-rate annual policies among fleet operators in Bangalore and Hyderabad. Image-recognition claims automation reduces loss-adjustment expenses for underwriters investing in AI infrastructure.
- Property:Fire and natural catastrophe coverage for commercial and residential assets faces pricing pressure from climate risk recalibration.
- Liability:Professional indemnity and product liability coverage grows with litigation awareness among export-oriented manufacturers.
Health coverage leads premium expansion; Motor claims automation offers cost leverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Insurance premium flows concentrate in states with dense banking networks and hospital infrastructure. Maharashtra and Karnataka anchor term-life and health coverage demand. Regulatory mandates from IRDAI and RBI shape capital deployment across sub-regional markets.
Maharashtra
Mumbai's financial sector employment drives group term-life purchasing through corporate benefit programs. IRDAI's solvency margin requirements apply stringently to insurers headquartered in this state. Pune's IT corridor attracts unit-linked product distribution targeting salaried professionals with equity exposure preferences.
Karnataka
Bangalore's hospital density and diagnostic center concentration channel retail health premium flows. The state's digital infrastructure supports API-driven underwriting platform deployment by insurtech entrants. Hyderabad's proximity extends motor insurance demand from fleet operators adopting telematics-enabled usage-based models.
Gujarat
Ahmedabad's SME manufacturing base generates property and liability coverage requirements for export-oriented enterprises. RBI bancassurance joint-venture norms govern SBI Life's penetration through Jan Dhan-linked accounts in rural Surat and Vadodara. The state's industrial insurance purchasing concentrates in chemical and textile clusters.
Tamil Nadu
Chennai's automotive supply chain anchors commercial motor fleet coverage with telematics integration. Ayushman Bharat gap coverage products target out-of-pocket medical spending excluded from the national health scheme. Coimbatore's SME engineering sector drives machinery breakdown and fire insurance demand.
Delhi-NCR
The National Capital Region's government employee concentration sustains group insurance schemes through public-sector undertakings. SEBI disclosure mandates for unit-linked investment components create compliance overlap affecting wealth-management distribution. Gurugram's startup ecosystem channels term-life purchasing among young professionals bypassing traditional agent channels.
India Life and Non-Life Insurance Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with bancassurance networks and direct digital platforms representing distinct competitive vectors. The market structure tiers between public-sector incumbents with legacy branch networks and private insurers investing in API-driven acquisition. Three archetypes dominate: bank-affiliated life insurers leveraging deposit base access, general insurers competing on claims automation infrastructure, and standalone digital entrants targeting millennial term-life purchasers. Consolidation pressure manifests through bancassurance exclusivity negotiations and insurtech partnership formations.
Among private-sector life insurers, HDFC Life Insurance and SBI Life Insurance occupy positions at opposite ends of the distribution spectrum. ICICI Lombard General Insurance anchors the general insurance tier with technology-forward claims processing. These three entities exemplify how capital backing from banking parents or standalone equity structures determine competitive flexibility under IRDAI's evolving digital sandbox mandates.
| Leading Market Players |
|---|
| SBI Life Insurance |
| HDFC Ergo General Insurance |
| Life Insurance Corporation of India |
| Tata AIG General Insurance |
| ICICI Lombard General Insurance |
| HDFC Life Insurance |
| Bajaj General Insurance |
| New India Assurance |
| ICICI Prudential Life Insurance |
| Others |
Supply & Pricing Matrix
Government securities yield movements cascade through insurer balance sheets into product pricing tiers, compressing margins on guaranteed-return endowment products while elevating unit-linked competitiveness. This interest rate transmission forces capital allocation trade-offs between solvency-compliant gilt holdings and equity-linked product development budgets.
Pricing Analysis
Volume concentrates in term-life products with thin margins, while unit-linked and health coverage sustain margin density through investment-linked fees and cashless network premiums. Price differentiation hinges on bancassurance exclusivity arrangements and proprietary underwriting engine sophistication. Pricing pressure stems from insurtech entrants offering API-driven instant issuance at 15-20% discount to traditional agent-mediated channels. Metro millennials under age 35 exhibit lowest price sensitivity due to convenience premium, while rural Jan Dhan-linked buyers prioritize absolute premium outlay over coverage depth.
Supply Chain Analysis
IRDAI sandbox certification requirements gate distribution partnerships, forcing insurtech entrants to demonstrate API interoperability before accessing insurer legacy systems. Technology development concentrates in Bangalore, Mumbai, and Hyderabad, with actuarial talent scarcity in tier-two cities creating hiring bottlenecks. Supply chain risk centers on single-source dependency for telematics data providers and third-party image-recognition vendors for motor claims automation. Distribution runs through bancassurance networks for rural penetration and direct-to-consumer platforms for metro acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API-driven underwriting platforms are displacing COBOL-based legacy policy administration systems, compressing issuance cycles from weeks to minutes and rewriting customer acquisition economics across life and non-life segments.
For Market Incumbents: Lock in bancassurance exclusivity through Jan Dhan-linked account penetration before insurtech entrants achieve IRDAI sandbox certification for UPI-embedded microinsurance. Prioritize legacy core system API exposure to defend against direct-to-consumer platform disintermediation among metro millennials. Channel modernization capex toward telematics infrastructure and wearable data integration to sustain pricing power in motor and health segments. For New Entrants and Emerging Players: Gig-economy workers in tier-three cities represent the most penetrable buyer archetype for sub-₹500 annual microinsurance policies via UPI payment rail APIs. Ayushman Bharat gap coverage in Tamil Nadu and Gujarat offers white-space targeting for supplementary private health policies excluded from national scheme reimbursement. Go-to-market execution should leverage digital sandbox compliance as competitive credential against established insurers with legacy system debt. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier general insurers with motor claims automation infrastructure in Karnataka and Maharashtra, where solvency margin pressures and legacy IT modernization burdens strain standalone capital structures. Long-term viability across the analysis window hinges on API interoperability certification and bancassurance partnership depth. Watch for IRDAI digital disclosure mandate enforcement acceleration as inflection indicator for technology-native competitor market share capture.| Strategic Initiative | Industry Significance |
|---|---|
| Legacy Core System API Exposure | Enables real-time solvency reporting to IRDAI and reinsurance counterparties through standardized data feeds. |
| Telematics Infrastructure Buildout | Supports usage-based motor pricing for Bangalore and Hyderabad fleet operators adopting per-kilometer coverage models. |
| UPI-Embedded Microinsurance Launch | Captures gig-economy premium flows in tier-three cities through payment rail API integration. |
| Jan Dhan Bancassurance Expansion | Channels term-life products through SBI's rural Maharashtra and Karnataka branch network penetration. |
| Ayushman Bharat Gap Coverage Product | Targets out-of-pocket medical spending excluded from national health scheme in Tamil Nadu and Gujarat. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with IRDAI compliance officers, chief actuaries at tier-one and tier-two insurers, bancassurance distribution heads, insurtech platform engineers, and hospital network procurement managers. IRDAI annual reports, RBI bancassurance joint-venture disclosures, SEBI unit-linked investment component filings, and hospital density statistics from state health departments provided validation benchmarks. Bottom-up policy issuance volume estimates and top-down premium pool calculations underwent cross-triangulation.
Granularity-level modeling dissected the market across product type, distribution channel, end user, coverage type, and state-level regulatory cluster dimensions. CAGRs were derived through trend extrapolation of historical premium growth rates adjusted for digital sandbox mandate implementation timelines and rural bancassurance penetration curves. Solvency margin requirement changes and telematics adoption rates in motor insurance served as industry-specific forecast inputs across the projection horizon.
Revisions become necessary when IRDAI digital disclosure mandate enforcement intensity shifts, RBI bancassurance equity norm modifications materialize, or SEBI-ULIP convergence regulatory overlap expands. Forecasts reflect assumptions regarding legacy system modernization capex availability and actuarial talent pipeline expansion. A model refresh is warranted upon material change in UPI payment rail insurance API adoption velocity or Ayushman Bharat scheme coverage expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
United States Commercial Insurance Market
Insurance
US Property and Casualty (P&C) Insurance Market
Insurance
Netherlands Property and Casualty Insurance Market
Insurance
Slovenia Property and Casualty Insurance Market
Insurance
Marine Cargo Insurance Market
Insurance
Event Insurance Market
Insurance
Norway Cyber (Liability) Insurance Market
Insurance
Bancassurance Market
Insurance
Specialty Insurance Market
Insurance
Reinsurance Carriers Market
Insurance
Europe Embedded Insurance Market
Insurance
Digital Insurance Market
Insurance
Parametric Insurance Market
Insurance
Japan Bancassurance Market
Insurance
China Parametric Insurance Market
Insurance
Peru Insurance Market