
 Saudi Arabia Condominiums and Apartments Market | 2026-2036
Saudi Arabia Condominiums and Apartments Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Condominiums and Apartments Market Analytics
Islamic financing structures and long-term lease-to-own arrangements is rewriting competitive entry requirements for developers. Dar Al Arkan leverages its land bank and construction capabilities to dominate the premium segment. ROSHN anchors large-scale master-planned communities with government-backed capital efficiency. Jabal Omar Development Company specializes in high-density towers near religious and commercial centers in Makkah.
Saudi Arabia condominiums and apartments comprise individually owned residential units within multi-unit buildings, typically constructed with reinforced concrete frames, thermal insulation systems, and smart building management interfaces serving permanent residence and rental income purposes. The luxury product type commands the deepest margin pools in Riyadh and Jeddah, while the affordable category records the fastest inventory absorption as mortgage subsidies expand. The investor end-user segment controls pre-sale velocity, whereas the expat renter base sustains yield performance in eastern province employment hubs.
The Saudi Building Code enforced by the Ministry of Municipal and Rural Affairs and Housing sets seismic and fire-safety standards that elevate construction costs but filter out undercapitalized builders. The Real Estate Development Fund and SAMA's mortgage regulations shape buyer leverage capacity and developer pre-sale eligibility. Stakeholders must monitor how central bank liquidity adjustments and municipal density zoning revisions alter project feasibility timelines.
Market Dynamics
Islamic financing structures and long-term lease-to-own arrangements are rewriting competitive entry requirements for Saudi developers, forcing capital-light models to partner with Shariah-compliant lenders or exit.
Growth Catalysts
- SAMA mortgage regulations:The central bank's expanded eligibility criteria for first-time buyers unlocks pre-sale velocity for mid-market inventory across Riyadh's western corridor.
- Red Sea coastal tourism:Jeddah's waterfront redevelopment zone draws expatriate professionals seeking leasehold units with marina access and integrated retail.
- Reinforced concrete prefabrication:Modular panel systems cut construction timelines by half, enabling developers to capture price premiums before market saturation.
Market Restraints
- Steel rebar cost volatility:Fluctuations in global iron ore pricing compress project margins during fixed-price contract periods.
- Saudi Building Code seismic compliance:Mandatory structural reinforcement adds material intensity that filters out undercapitalized builders in secondary cities.
- Skilled MEP contractor scarcity:Concentration of certified firms in Riyadh and Jeddah creates bottlenecks for projects in Dammam and Khobar.
Strategic Opportunities
- Asir mountain tourism corridor:Abha and surrounding highland zones lack branded residential inventory for domestic leisure investors.
- Real Estate Development Fund mortgage guarantees:Subsidized financing instruments expand addressable demand among public-sector employees.
- Smart building management convergence:Integration of IoT sensors with district cooling networks creates utility-cost differentiation for premium towers.
Industry Challenges
- BIM modeling talent gap:Shortage of certified technicians delays design approvals and clash-detection resolution.
- Title deed registration backlog:Municipal processing delays extend buyer financing drawdown timelines and strain developer working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Condominiums and Apartments Market |
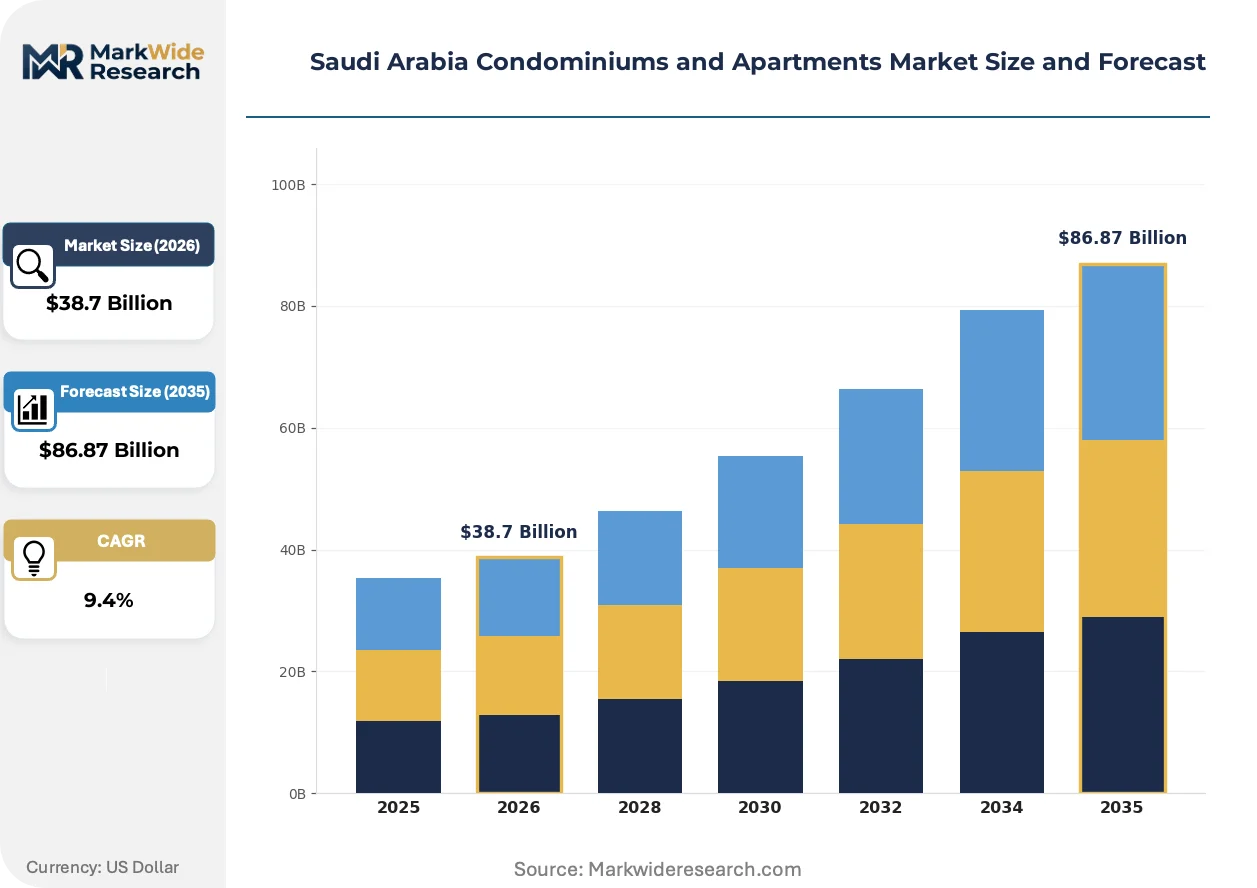
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury, Mid-Range, Affordable, Student Housing End User: Investors, Homebuyers, Renters, Expats Distribution Channel: Direct Sales, Online Listings, Real Estate Agencies, Auctions Price Tier: High-End, Competitive, Budget, Discounted |
| Companies Covered | Dar Al Arkan, ROSHN, Jabal Omar Development Company, Saudi Real Estate Company (Al Akaria), Emaar the Economic City, Retal Urban Development Company, Sumou Real Estate, Al Saedan Real Estate, Kingdom Holding Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Condominiums and Apartments Market Evolving Landscape
Construction methodologies and buyer financing preferences are converging to compress development cycles and reshape how Saudi households access ownership.
Cross-laminated timber and mass timber hybrid systems are hybridizing with conventional concrete cores in mid-rise towers. Boutique developers in Jeddah's Al Andalus district pilot these assemblies to differentiate against glass-and-steel competitors. The approach compresses superstructure timelines while satisfying Ministry of Municipal and Rural Affairs and Housing fire-safety audits through encapsulated designs.
Saudi Green Building Forum certification mandates are tightening thermal performance requirements for new approvals. Developers must now specify low-emissivity glazing and high-efficiency district cooling interfaces to secure building permits. The luxury segment absorbs these premiums most readily, while affordable projects seek volume discounts through frame supplier consolidation.
Young professional households are bypassing traditional broker channels in favor of developer-direct digital platforms with virtual unit customization. ROSHN and comparable master-planners capture preference data through these interfaces to pre-configure interior packages. Riyadh's western corridor shows the highest platform conversion rates, driven by mortgage pre-approval integration with Real Estate Development Fund portals.
Saudi Arabia Condominiums and Apartments Market Segmentation
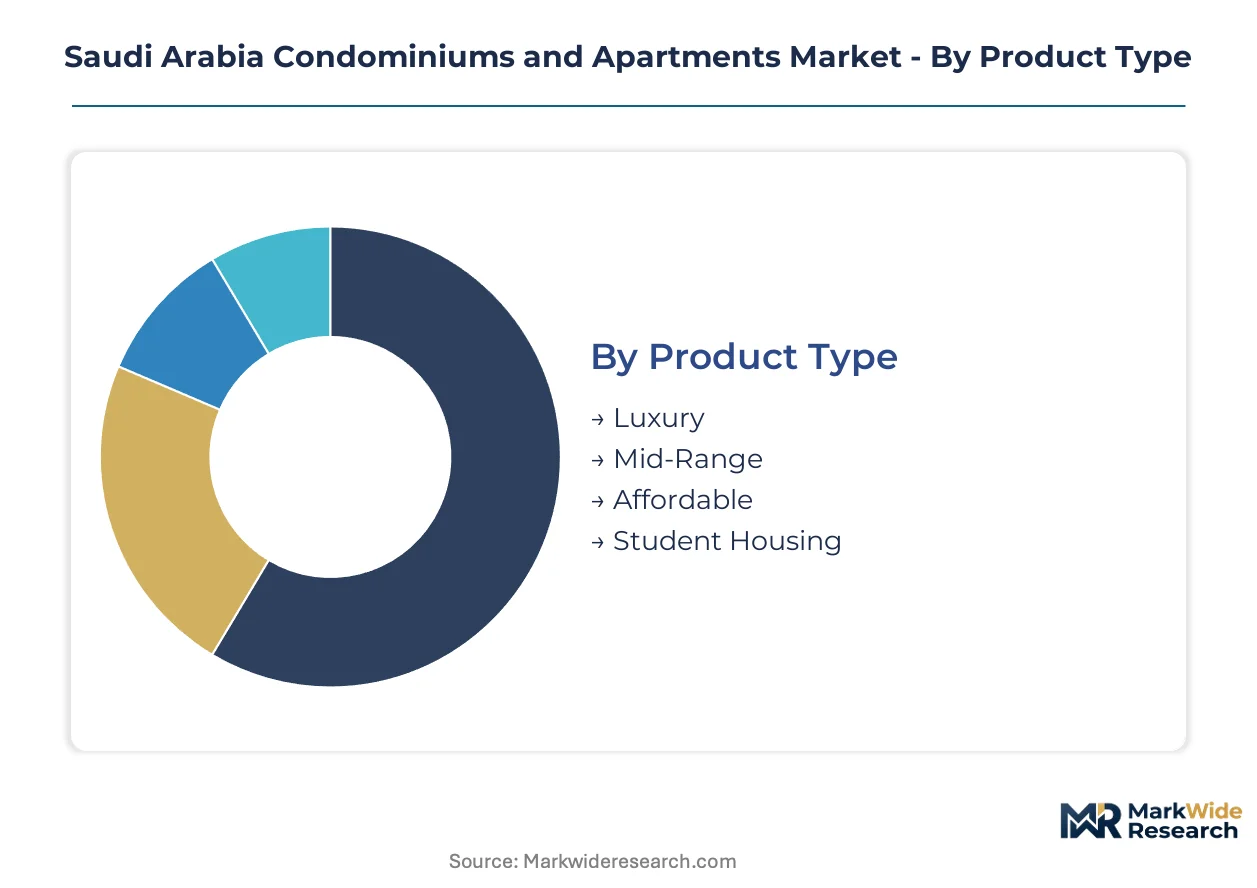
Segmentation in Saudi Arabia's condominium and apartment market reveals how financing access, construction standards, and buyer demographics create distinct commercial pockets. Developers must align product specifications with the Real Estate Development Fund's eligibility tiers and municipal zoning density to capture pre-sale velocity.
Product Type:
Mature premium inventory in Riyadh and Jeddah competes with emerging affordable stock subsidized by mortgage guarantees.
- Luxury:Reinforced concrete towers with smart building management interfaces and thermal insulation systems command the deepest margin pools in Riyadh's western corridor and Jeddah's waterfront redevelopment zone. Demand concentrates among high-net-worth investors seeking rental yield from expatriate professionals.
- Mid-Range:Standard specification units with district cooling connectivity and basic IoT infrastructure serve young professional households leveraging SAMA mortgage regulations. Inventory in Riyadh's western corridor records the highest absorption velocity as pre-approval integration streamlines purchase timelines.
- Affordable:Compact units with standardized finishes and reduced amenity loadouts target public-sector employees accessing Real Estate Development Fund guarantees. This segment expands most quickly as municipal density zoning permits higher-rise construction in secondary cities.
- Student Housing:Purpose-built clusters with shared facilities and lease-to-own structures serve domestic university populations in Abha and emerging education hubs near the Asir mountain tourism corridor.
Luxury handles the majority of throughput; affordable is the fastest mover on share.
End User:
Customer composition shifts between permanent ownership seekers and yield-focused capital deployment.
- Investors:Institutional and individual buyers prioritize pre-sale entry points and rental yield stability, concentrating activity in eastern province employment hubs where expatriate demand sustains occupancy rates.
- Homebuyers:Young professional households dominate first-time purchase flows, with preference data showing strongest conversion through developer-direct digital platforms integrated with Real Estate Development Fund portals.
- Renters:Domestic and regional tenants seeking flexibility drive leasehold absorption in master-planned communities, particularly where integrated retail and marina access differentiate offerings.
- Expats:Foreign professionals employed in oil, logistics, and tourism sectors sustain yield performance in Dammam and Khobar despite skilled MEP contractor scarcity delaying project completion in these markets.
Homebuyers anchor volume commitment; investors are expanding most quickly as pre-sale structures proliferate.
Distribution Channel:
Channel economics favor direct engagement where digital infrastructure compresses transaction friction.
- Direct Sales:Developer-operated showrooms and virtual unit customization platforms capture preference data while eliminating broker commissions. ROSHN and comparable master-planners deploy this channel most aggressively in Riyadh.
- Online Listings:Aggregator platforms with mortgage pre-approval integration serve price-sensitive buyers comparing inventory across multiple developers simultaneously.
- Real Estate Agencies:Traditional broker networks retain relevance for luxury transactions requiring personalized site visits and negotiation leverage.
- Auctions:Distressed and developer-held inventory clears through competitive bidding, particularly for units with title deed registration delays.
Direct sales carries the heaviest transaction load; online listings gain share fastest as platform infrastructure matures.
Price Tier:
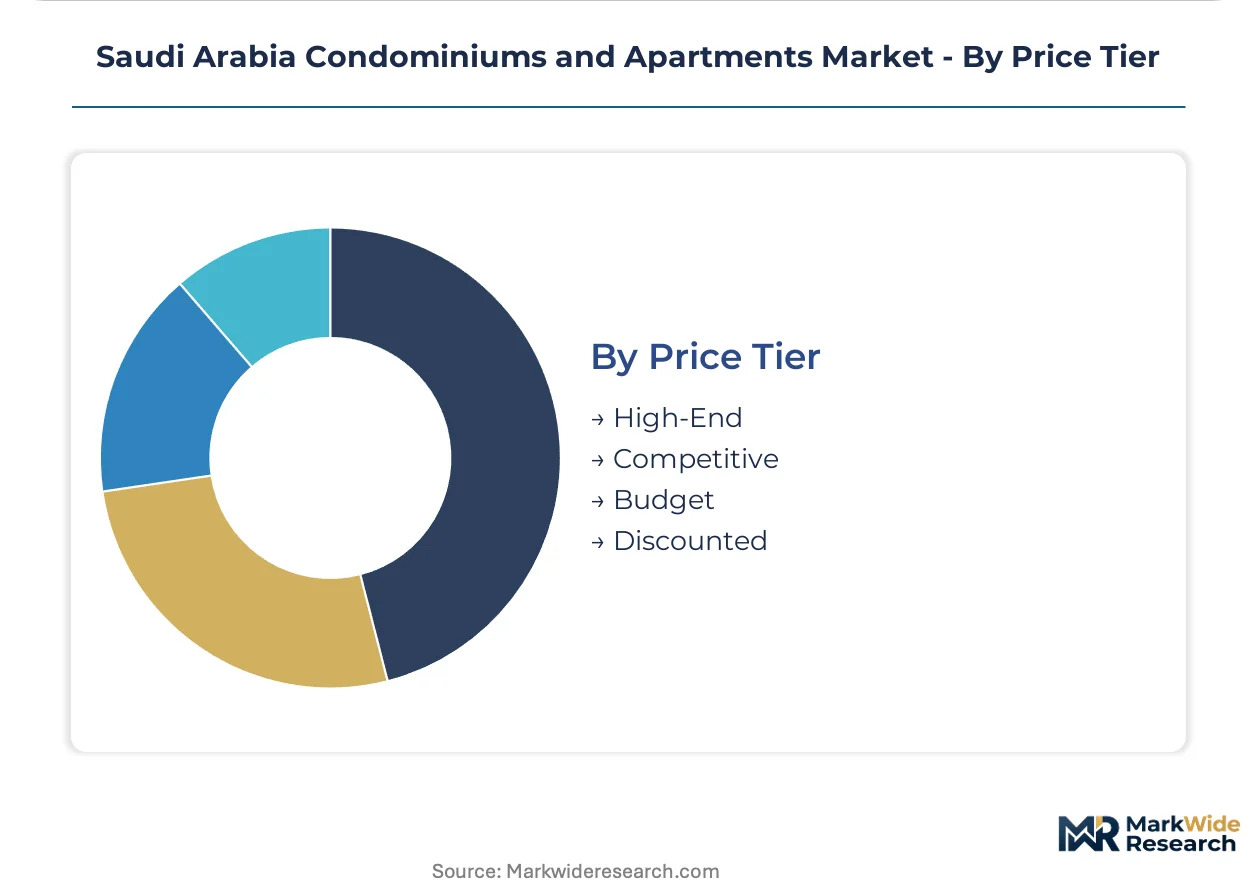
Pricing stratification reflects construction cost absorption capacity and financing eligibility boundaries.
- High-End:Units with Saudi Green Building Forum certification, low-emissivity glazing, and premium district cooling interfaces absorb material cost premiums most readily in Jeddah's Al Andalus district.
- Competitive:Mid-market positioning with selective amenity inclusion targets buyers at the upper bound of Real Estate Development Fund guarantee thresholds.
- Budget:Stripped-down specifications with frame supplier consolidation enable volume discounts while meeting Saudi Building Code seismic compliance minimums.
- Discounted:Inventory with extended completion timelines or peripheral locations clears through price reductions, often to investor buyers with holding capacity.
Competitive tier handles the majority of throughput; budget tier climbs the fastest as subsidy expansion broadens addressable demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Real Estate Development Fund's mortgage guarantee programs and SAMA's expanded eligibility criteria are redistributing construction activity across Saudi Arabia's major urban corridors. Municipal density zoning revisions in secondary cities are unlocking inventory absorption outside traditional demand centers.
Riyadh
Young professional households are concentrating purchase flows in the western corridor where developer-direct digital platforms streamline mortgage pre-approval integration. The Saudi Building Code enforced by the Ministry of Municipal and Rural Affairs and Housing elevates seismic compliance costs that filter undercapitalized builders. King Abdullah Financial District and adjacent master-planned communities anchor premium inventory deployment.
Jeddah
Expatriate professionals seeking leasehold units with marina access are sustaining yield performance in the waterfront redevelopment zone. Saudi Green Building Forum certification mandates tighten thermal performance requirements for new approvals. Al Andalus district hosts boutique developers piloting cross-laminated timber hybrid systems to differentiate against conventional glass-and-steel competitors.
Eastern Province
Oil and logistics sector employment sustains rental demand in Dammam and Khobar despite skilled MEP contractor scarcity delaying project completion. The Real Estate Development Fund's subsidized financing instruments expand addressable demand among public-sector employees. Jubail Industrial City spillover is generating secondary residential demand in northern Dammam submarkets.
Makkah
Religious tourism flows create consistent occupancy demand for high-density towers near the Grand Mosque. Jabal Omar Development Company anchors construction activity through specialized positioning in this micro-market. The Haramain High-Speed Railway connection is compressing travel times and expanding catchment for peripheral residential clusters.
Saudi Arabia Condominiums and Apartments Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure tiered by land bank scale and construction capability depth. Consolidation pressures favor entities with integrated development-to-delivery pipelines. Three archetypes dominate: government-backed master-planners with capital efficiency advantages, premium-segment specialists leveraging vertical construction expertise, and regional developers exploiting localized land positions. Competitive moves center on strategic partnerships with Shariah-compliant lenders and portfolio diversification into lease-to-own structures.
Among Riyadh-based developers with government affiliations, ROSHN exemplifies the master-planner archetype through large-scale community deployment. Dar Al Arkan occupies a position representing premium-segment concentration, while Jabal Omar Development Company anchors specialized positioning in religious tourism corridors. These three entities collectively illustrate how capital access and land positioning determine competitive viability under evolving mortgage guarantee frameworks.
| Leading Market Players |
|---|
| Dar Al Arkan |
| ROSHN |
| Jabal Omar Development Company |
| Saudi Real Estate Company (Al Akaria) |
| Emaar the Economic City |
| Retal Urban Development Company |
| Sumou Real Estate |
| Al Saedan Real Estate |
| Kingdom Holding Company |
| Others |
Value Network & Pricing Analysis
Steel rebar cost volatility determines both pricing tier spreads and supply chain shape across Saudi Arabia's condominium market, compressing margins in fixed-price contracts while forcing developers toward frame supplier consolidation and prefabrication partnerships to regain cost control.
Pricing Analysis
Saudi Green Building Forum certification level creates the primary spread between high-end and budget inventory, with low-emissivity glazing and district cooling interfaces absorbing material premiums most readily in Jeddah's Al Andalus district. Three-tier pricing structure across premium, standard, and economy levels dominates, with thermal performance grade and financing eligibility boundaries serving as key differentiation drivers. Cost compression in the affordable tier is intensifying because municipal density zoning permits higher-rise construction in secondary cities. Public-sector employees accessing Real Estate Development Fund guarantees exhibit highest price sensitivity, while high-net-worth investors in Riyadh's western corridor show least sensitivity to certification-related premiums.
Supply Chain Analysis
Reinforced concrete prefabrication capacity concentrates with modular panel system suppliers in the UAE, South Korea, and domestic Saudi fabricators serving Riyadh and Jeddah corridors. Construction inputs draw from Chinese steel rebar, regional cement clinker, and European MEP components. Single-source vulnerability runs through certified MEP contractor scarcity in Dammam and Khobar, where concentration of qualified firms creates completion bottlenecks. Distribution runs through developer-direct procurement channels for master-planned communities, with secondary reliance on traditional broker networks for distressed inventory clearance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists across Saudi Arabia's condominium market as young professional households bypass traditional channels in favor of developer-direct digital platforms, creating niches for specialized players in mortgage-integrated pre-sale structures.
For Market Incumbents: Pre-empt channel disintermediation by accelerating virtual unit customization platform deployment with Real Estate Development Fund portal integration, while securing captive supply of modular panel systems through frame supplier consolidation to defend against steel rebar cost volatility. Threat substitution from cross-laminated timber hybrid systems in Jeddah's boutique segment demands rapid certification investment to maintain premium positioning.
For New Entrants and Emerging Players: Asir mountain tourism corridor underpenetration offers white-space entry for branded residential inventory targeting domestic leisure investors in Abha and surrounding highland zones. Secondary cities with revised municipal density zoning represent the most penetrable geography, with student housing lease-to-own structures serving as the optimal go-to-market angle for public-sector employee demand capture.
For Investors and Strategic Acquirers: SAMA mortgage regulation expansion reshapes the acquisition landscape by elevating pre-sale velocity as the primary valuation driver across mid-market inventory. Long-term viability centers on developers with integrated construction capabilities and land bank depth in Riyadh's western corridor. The signal to monitor is central bank liquidity adjustments altering buyer leverage capacity and project feasibility timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Shariah-Compliant Financing Partnership | Islamic financing structures unlock capital access for mortgage guarantee-eligible buyers through REDF portal integration. |
| Modular Construction Scale-Up | Prefabricated panel systems compress superstructure timelines by half, capturing price premiums before saturation hits Riyadh. |
| Smart Building Management Convergence | IoT sensor integration with district cooling networks creates utility-cost differentiation for premium towers in Jeddah. |
| Geographic Expansion to Secondary Cities | Municipal density zoning revisions in Dammam and Khober unlock inventory absorption outside traditional demand centers. |
| Direct-to-Consumer Digital Platform Launch | Developer-direct channels with mortgage pre-approval integration eliminate broker commissions and capture preference data. |
Research Methodology
Cross-validation between primary interviews with real estate development executives, construction project managers, mortgage financing officers, and municipal planning officials and secondary sources anchors the qualitative findings in this study. Regulatory filings from the Ministry of Municipal and Rural Affairs and Housing, SAMA mortgage regulation circulars, Real Estate Development Fund guarantee program disclosures, and Saudi Building Code compliance databases provide structural validation. Bottom-up project pipeline enumeration triangulates against top-down macroeconomic absorption modeling.
Calibration against historical completion timelines and pre-sale velocity patterns across the projection horizon ensures analytical robustness. Segmentation dimensions modeled include product type tier, end-user archetype, distribution channel structure, and regional zoning cluster. CAGRs derive from unit absorption trajectories weighted by financing eligibility expansion rates and construction cost index movements.
Practitioners should monitor central bank liquidity adjustments, steel rebar import tariff movements, and municipal processing efficiency for title deed registration for early signals of forecast revision. Quarterly review of pre-sale conversion rates by corridor, MEP contractor availability indices, and REDF guarantee utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condominium and Apartments
Europe Condominiums and Apartments Market
Condominium and Apartments
Global Condominiums and Apartments Market
Condominium and Apartments
India Condominium and Apartments Market
Condominium and Apartments
Egypt Condominiums and Apartments Market
Condominium and Apartments
Italy Condominiums and Apartments Market
Condominium and Apartments
Qatar Condominium and Apartment Market
Condominium and Apartments
Germany Condominiums and Apartments Market
Condominium and Apartments
Latin America Condominiums and Apartments Market
Condominium and Apartments
Condom Market
Condominium and Apartments
Asia-Pacific Condominiums and Apartments Market
Condominium and Apartments
Canada Condominiums and Apartments Market
Condominium and Apartments
ASEAN Condominiums and Apartments Market
Condominium and Apartments
UAE Condominiums and Apartments Market
Condominium and Apartments
Spain Condominiums and Apartments Market
Condominium and Apartments
Japan Condominiums and Apartments Market