
 Egypt Condominiums and Apartments Market | 2026-2036
Egypt Condominiums and Apartments Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Condominiums and Apartments Market Foresight
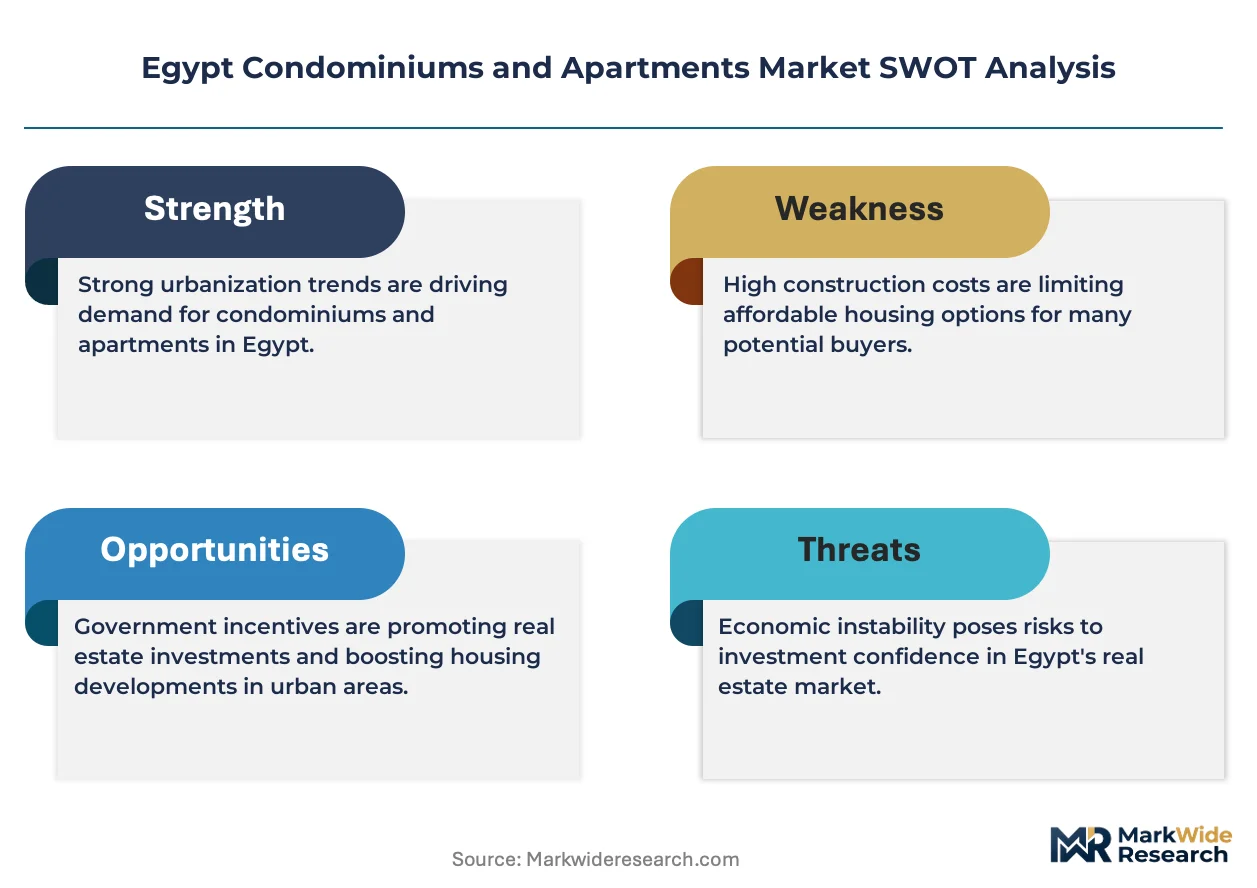
Multi-sourced land assembly is realigning how Egyptian developers secure buildable plots. SODIC leverages its West Cairo land bank to control project pipelines. Hassan Allam Properties anchors its position through infrastructure-led master planning. Orascom Development competes via integrated hospitality-residential hybrids on the Red Sea coast.
Egyptian condominiums and apartments constitute multi-unit residential structures built on single land parcels, typically employing reinforced concrete frame systems with hollow-core slab construction and facade treatments ranging from painted plaster to curtain-wall glazing for premium offerings, designed to house multiple ownership or tenancy units within vertically stacked configurations. The primary purpose centers on optimizing land utilization in dense urban corridors while providing strata-titled ownership vehicles for middle-class wealth accumulation. Luxury condominiums dominate margin pools in New Cairo and the North Coast, where expatriate and investment-driven buyers absorb premium per-square-meter pricing. Affordable units sustain the largest volume footprint, absorbing government-mandated inclusion ratios within new city developments. Joint ventures between domestic developers and Gulf capital sources represent the fastest-growing developer type, channeling sovereign wealth into long-dated Egyptian real estate yields.
The New Urban Communities Authority governs land allocation and master planning across Egypt's desert new cities, while the Central Bank of Egypt regulates mortgage finance availability through loan-to-value caps and interest rate benchmarks. The Egyptian Financial Supervisory Authority oversees real estate investment trust structures that increasingly securitize apartment rental income streams. Stakeholders must monitor liquidity conditions in the Egyptian pound and foreign currency access regimes, as these determine both construction cost trajectories and the purchasing power of the expatriate buyer segment.
Market Dynamics
Land assembly complexity in Egypt's desert new cities is reshaping developer capital deployment, as the New Urban Communities Authority's streamlined permitting for satellite urban corridors concentrates buildable inventory in the hands of established land banks. Young professionals in Greater Cairo are compressing purchase decision cycles, forcing developers to pre-sell units before steel reinforcement procurement.
Growth Catalysts
- New Urban Communities Authority permitting reforms:Accelerated approvals for desert city master plans reduce project gestation periods. Developers secure construction licenses within consolidated regulatory windows rather than sequential municipal clearances.
- Gulf sovereign wealth deployment:Joint venture structures channel long-dated capital into Egyptian residential yields. Sovereign funds from Saudi Arabia and the UAE anchor equity tranches for mega-developments in the New Administrative Capital corridor.
- Reinforced concrete frame systems:Hollow-core slab construction methods optimize vertical build speed. Local contractors achieve faster floor-cycle times compared to traditional beam-column alternatives.
Market Restraints
- Egyptian pound liquidity compression:Foreign currency access regimes restrict imported finishing material procurement. Developers face payment delays for curtain-wall glazing and elevator systems denominated in hard currency.
- Concentrated steel supply:Domestic rebar production clusters around state-linked mills in Alexandria and Suez. Price volatility in billet imports from Turkey and Ukraine transmits directly to construction cost structures.
- Mortgage finance ceilings:Central Bank of Egypt loan-to-value caps constrain middle-class purchasing power. First-time buyers face equity requirements that exclude the affordable segment's core demographic.
Strategic Opportunities
- Red Sea coast hospitality-residential hybrids:Integrated developments combining condominium inventory with resort management contracts attract yield-focused investors. Orascom Development's El Gouna model demonstrates executable precedent.
- Real estate investment trust securitization:Egyptian Financial Supervisory Authority frameworks enable rental income stream packaging. Institutional capital gains regulated exposure to apartment yield without direct development risk.
- Smart building automation convergence:Integration of energy management systems with resident-facing mobile applications differentiates premium offerings. Young professionals in New Cairo prioritize connected unit features in purchase decisions.
Industry Challenges
- Project management talent scarcity:Experienced site engineers capable of coordinating multi-tower phased delivery command premium compensation. Developer payroll costs inflate as competition intensifies for construction supervision expertise.
- Utility infrastructure synchronization:Electrification and wastewater trunk lines in new desert cities lag building completion schedules. Developers absorb holding costs on finished inventory awaiting municipal connection permits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Condominiums and Apartments Market |
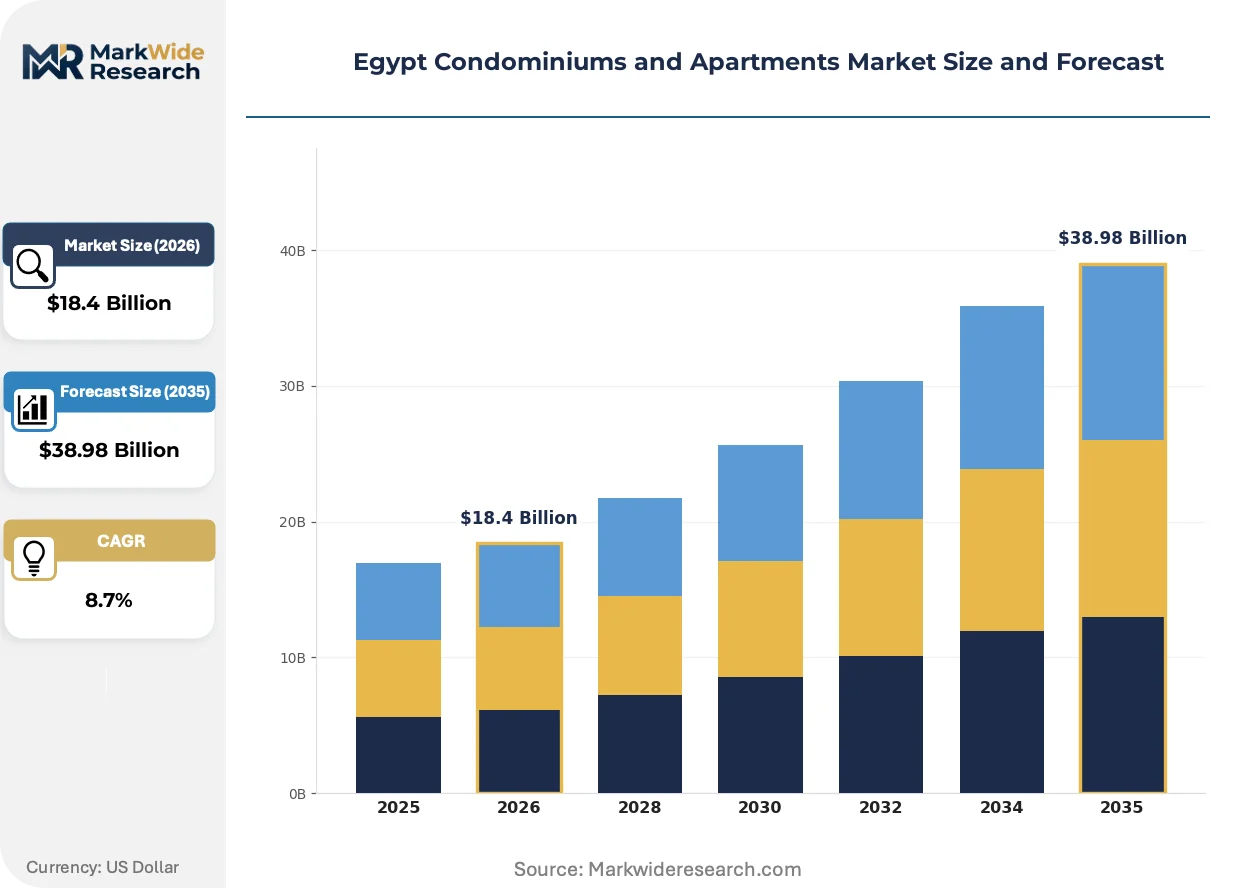
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $38.98 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Luxury Condominiums, Mid-range Apartments, Affordable Units, Studio Flats, Duplexes Developer Type: Private Developers, Government Authorities, Joint Ventures, Investment Trusts End User: Individual Homebuyers, Corporate Tenants, Expatriates, Real Estate Investors Sales Channel: Direct Sales, Real Estate Brokers, Online Portals, Property Exhibitions |
| Companies Covered | ERG Developments, ORA Developments, NEWGIZA, LA VISTA DEVELOPMENTS, SODIC, Wadi Degla Developments, Coldwell Banker Egypt, Hassan Allam Properties, Orascom Development, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Condominiums and Apartments Market Shifts & Advancements
Digital twin technology is compressing design-to-construction handoff timelines across Egyptian residential developments. Developers deploy virtual modeling to resolve structural conflicts before concrete pours, reducing rework incidence on high-rise towers.
Building information modeling platforms are unifying architectural, structural, and MEP workflows into single-source coordination environments. Hassan Allam Properties and SODIC deploy these systems on New Cairo mega-projects to compress design review cycles. The technology is unifying previously siloed consultant disciplines, enabling faster permit submission packages to the New Urban Communities Authority.
Central Bank of Egypt mortgage finance regulations are expanding eligible borrower pools through subsidized interest rate programs. The Mortgage Finance Fund's initiative reduces effective borrowing costs for middle-income applicants. Affordable segment developers in 6th of October City and Sheikh Zayed are responding with smaller unit footprints to match revised affordability ceilings.
Young professional buyers are compressing pre-sale commitment timelines through digital channel engagement. Virtual reality unit walkthroughs and blockchain-secured reservation deposits displace traditional site visit dependencies. This behavioral shift concentrates in Greater Cairo's technology sector employees, who expect seamless digital transaction experiences matching fintech service standards.
Egypt Condominiums and Apartments Market Segmentation
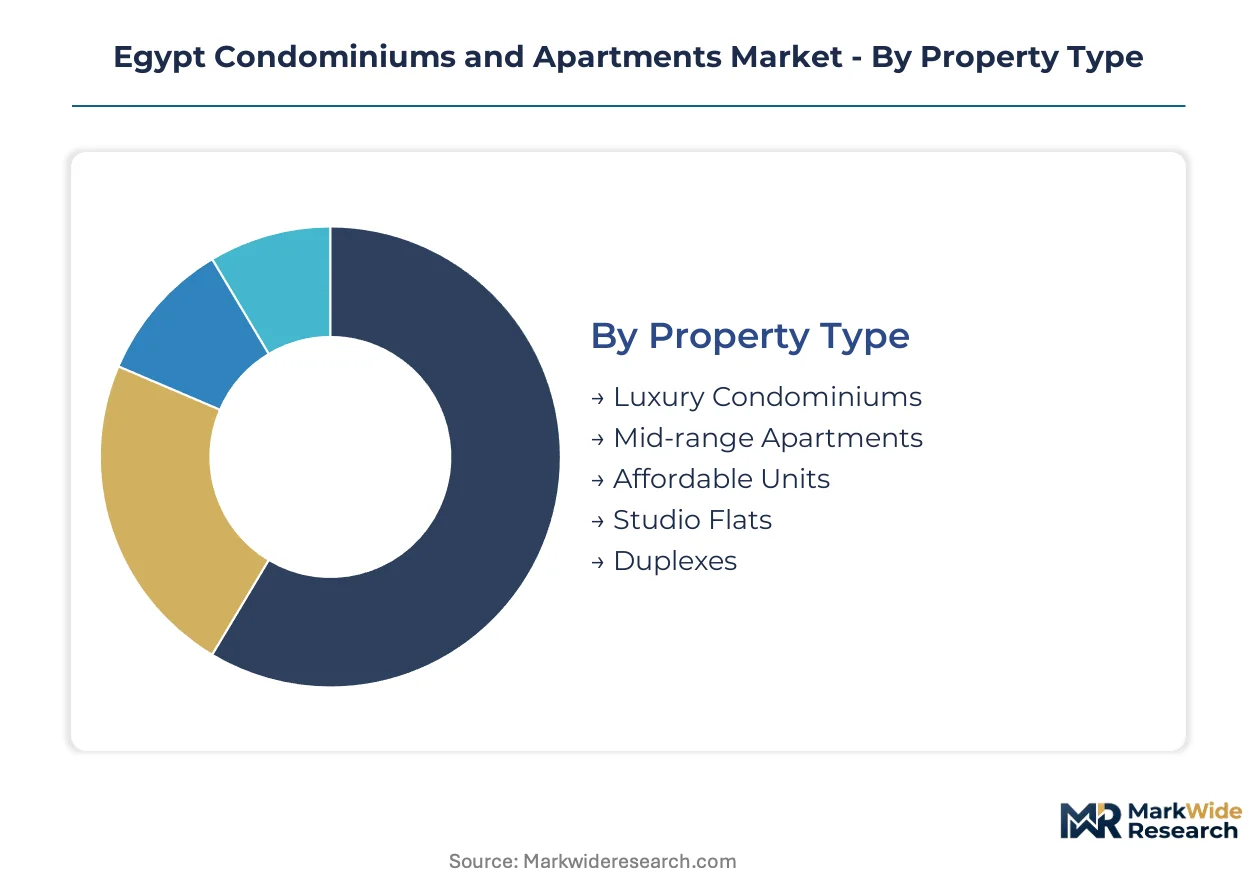
Segmentation in Egypt's condominium and apartment market reveals distinct capital deployment patterns across property tiers and buyer profiles. Developer strategies diverge sharply between luxury inventory targeting expatriate yield-seekers and affordable units absorbing government inclusion mandates. Understanding these segment boundaries enables precise positioning within the New Administrative Capital corridor and established Greater Cairo nodes.
Property Type:
Standalone ownership structures dominate premium tiers while embedded rental configurations concentrate in workforce housing segments.
- Luxury Condominiums:Reinforced concrete frame systems with curtain-wall glazing and smart building automation. Demand concentrates in New Cairo and the North Coast where Gulf sovereign wealth and expatriate buyers absorb premium per-square-meter pricing despite Egyptian pound liquidity compression.
- Mid-range Apartments:Hollow-core slab construction with painted plaster facades and standardized MEP specifications. Young professionals in Greater Cairo drive pre-sale commitments through digital channel engagement, compressing developer marketing cycles.
- Affordable Units:Government-mandated inclusion ratios within new city developments. The Mortgage Finance Fund's subsidized interest programs expand eligible borrower pools.
- Studio Flats:Compact footprints optimized for single-occupancy professionals in 6th of October City and Sheikh Zayed technology corridors.
- Duplexes:Vertically stacked two-level configurations targeting extended family occupancy in satellite urban communities.
Volume placements concentrate in Affordable Units; the faster expansion belongs to Luxury Condominiums.
Developer Type:
Capital source and regulatory access determine competitive positioning across Egypt's desert new cities.
- Private Developers:SODIC and Hassan Allam Properties leverage established land banks and infrastructure-led master planning. These firms control project pipelines through multi-sourced land assembly in West Cairo and New Cairo corridors.
- Joint Ventures:The fastest-expanding developer category channels Saudi and UAE sovereign wealth into long-dated Egyptian real estate yields. Gulf equity tranches anchor mega-developments in the New Administrative Capital.
- Government Authorities:The New Urban Communities Authority streamlines permitting and allocates buildable plots across desert satellite cities.
- Investment Trusts:Egyptian Financial Supervisory Authority frameworks enable rental income securitization without direct development exposure.
Project pipelines concentrate with Private Developers; Investment Trusts are gaining share fastest through yield-focused institutional capital.
End User:
Purchasing power segmentation aligns with foreign currency access and mortgage finance availability.
- Real Estate Investors:Yield-focused buyers prioritizing rental income streams and capital appreciation in dollar-denominated or hard-currency-linked developments. Red Sea coast hospitality-residential hybrids attract this segment through resort management contracts.
- Individual Homebuyers:Central Bank of Egypt loan-to-value caps constrain middle-class purchasing power, forcing equity requirements that exclude core affordable segment demographics.
- Expatriates:Hard-currency earners absorbing premium inventory in New Cairo and coastal developments despite Egyptian pound volatility.
- Corporate Tenants:Bulk leasing arrangements for employee housing in technology and financial services sectors.
Transaction volume concentrates with Individual Homebuyers; Real Estate Investors show the steepest expansion trajectory.
Sales Channel:
Digital migration is reshaping buyer engagement patterns across Greater Cairo's technology-savvy demographic.
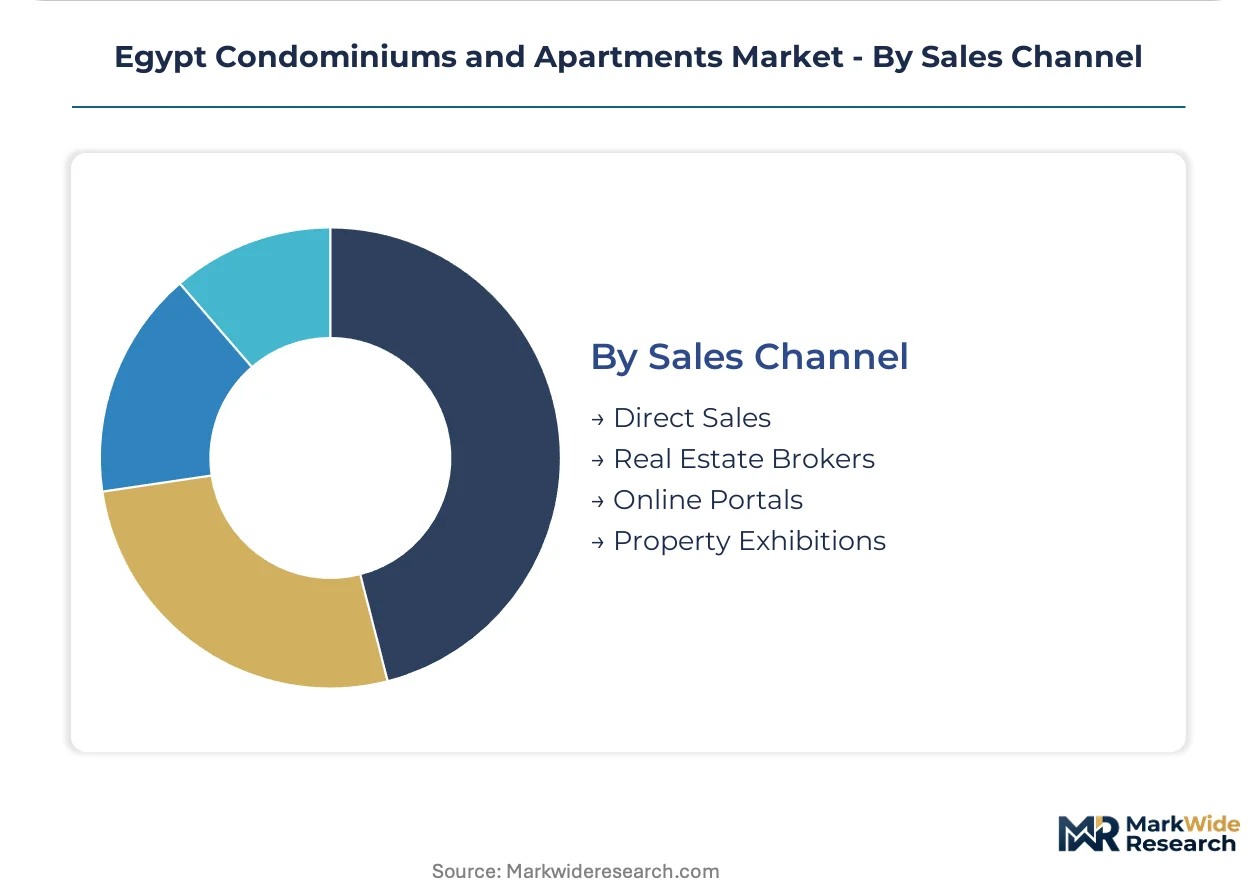
- Online Portals:Virtual reality unit walkthroughs and blockchain-secured reservation deposits displace traditional site visit dependencies. Young professionals in technology sectors expect seamless digital transaction experiences matching fintech service standards.
- Direct Sales:Developer-hosted showrooms in New Administrative Capital corridor projects enable immediate pre-sale commitment capture.
- Real Estate Brokers:Commission-based intermediaries dominate secondary market transactions and expatriate buyer navigation.
- Property Exhibitions:Periodic events in Cairo and Gulf capitals targeting offshore investment flows.
Transaction volume concentrates in Direct Sales; Online Portals are climbing the fastest among emerging channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Young professionals in Greater Cairo compress purchase decision cycles, forcing developers to pre-sell units before procurement. The New Administrative Capital corridor concentrates buildable inventory through streamlined permitting. Regional demand patterns diverge sharply between established urban nodes and emerging desert satellite cities.
Greater Cairo
Young technology sector employees drive digital channel engagement through virtual reality walkthroughs and blockchain-secured deposits. The Mortgage Finance Fund's subsidized interest programs expand eligible borrower pools for mid-range apartments. New Cairo and 6th of October City anchor luxury and affordable inventory respectively.
Alexandria and the North Coast
Expatriate buyers absorb premium per-square-meter pricing in Mediterranean coastal developments despite Egyptian pound volatility. The New Urban Communities Authority allocates buildable plots across Marina and Sahel corridors through accelerated approval windows. Orascom Development's integrated hospitality-residential hybrids demonstrate executable precedent for yield-focused investors.
Red Sea Coast
Gulf sovereign wealth channels long-dated capital into resort-adjacent condominium inventory through joint venture structures. The Egyptian Financial Supervisory Authority frameworks enable rental income securitization without direct development exposure. El Gouna and Hurghada clusters concentrate hospitality-residential hybrid construction.
Upper Egypt
Affordable unit demand sustains volume footprints through government-mandated inclusion ratios within new city developments. State-linked steel mills in Suez transmit billet import volatility directly to construction cost structures. Asyut and Sohag satellite cities absorb middle-class migration from dense Nile Valley settlements.
Sinai Peninsula
Utility infrastructure synchronization challenges delay municipal connection permits for finished inventory. The New Urban Communities Authority streamlines electrification and wastewater trunk line approvals for desert city master plans. Limited buildable inventory concentrates around El Arish and coastal development zones.
Egypt Condominiums and Apartments Market Competitive Landscape
Land bank consolidation dominates the current landscape as established developers secure multi-sourced plot assembly ahead of permitting reforms. The market structure concentrates around three tiers: private developers with legacy land positions, Gulf-backed joint ventures deploying sovereign wealth, and government authorities controlling allocation mechanisms. Strategic archetypes include infrastructure-led master planners, integrated hospitality-residential hybrid operators, and yield-focused rental income securitizers. Competitive moves center on pre-sale commitment capture through digital channels and backward integration into captive steel and finishing material procurement.
Among Cairo-based developers, SODIC and Hassan Allam Properties exemplify the infrastructure-led master planning archetype through West Cairo and New Cairo land bank control. Orascom Development occupies a position representing integrated hospitality-residential hybrid execution on coastal corridors. These three entities anchor the competitive structure through differentiated geographic and product positioning rather than direct segment overlap.
| Leading Market Players |
|---|
| ERG Developments |
| ORA Developments |
| NEWGIZA |
| LA VISTA DEVELOPMENTS |
| SODIC |
| Wadi Degla Developments |
| Coldwell Banker Egypt |
| Hassan Allam Properties |
| Orascom Development |
| Others |
Supply & Pricing Matrix
Young professionals in Greater Cairo compressing purchase decision cycles force developers to accelerate pre-sale commitments before steel reinforcement procurement, squeezing margins on mid-range apartments while Gulf-backed joint ventures absorb premium pricing power in New Administrative Capital corridor luxury inventory.
Pricing Analysis
Volume placements concentrate in affordable units absorbing government-mandated inclusion ratios; margin pools accrue to luxury condominiums in New Cairo and the North Coast where expatriate buyers tolerate premium per-square-meter pricing. Three-tier pricing structure across premium, standard, and economy levels differentiates by facade treatment quality, smart building automation integration, and mortgage finance eligibility under Central Bank of Egypt loan-to-value caps. Cost compression in mid-range segments intensifies because young professionals demand digital channel engagement infrastructure and virtual reality walkthrough capabilities. Individual homebuyers facing equity requirements demonstrate highest price sensitivity; real estate investors purchasing dollar-denominated coastal inventory show lowest.
Supply Chain Analysis
Single-source vulnerability sits with state-linked steel mills in Alexandria and Suez concentrating domestic rebar production; billet import dependence on Turkey and Ukraine transmits price volatility directly to construction cost structures. Hollow-core slab manufacturing draws from local contractor networks while curtain-wall glazing and elevator systems rest on hard-currency procurement from China, Germany, and Italy. Foreign currency access regimes restricting imported finishing materials constitute the dominant supply chain risk, forcing developers into extended payment delays. Distribution runs through developer-hosted showrooms in New Administrative Capital corridor projects and digital portals enabling blockchain-secured reservation deposits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
New Urban Communities Authority permitting reforms function as a cost-of-compliance barrier, creating regulatory moats that favor established land bank holders capable of navigating consolidated approval windows while excluding capital-constrained challengers.
For Market Incumbents: Hedge against Egyptian pound liquidity compression by securing captive supply agreements for hard-currency-denominated finishing materials before construction commencement. Deepen backward integration into steel procurement through direct billet import arrangements bypassing state-linked mill intermediaries. Defensive positioning requires accelerating digital twin technology deployment to compress design-to-construction handoff timelines and reduce rework incidence on high-rise towers. For New Entrants and Emerging Players: Technology sector employees in 6th of October City and Sheikh Zayed corridors represent an underserved buyer archetype seeking studio flats with seamless mobile application integration for energy management systems. White-space targets include smart building automation convergence for premium offerings and hospitality-residential hybrid development on underexploited Red Sea coastal plots. Go-to-market execution should prioritize virtual reality unit walkthroughs and blockchain-secured reservation deposits displacing traditional site visit dependencies. For Investors and Strategic Acquirers: The window for entry favors joint venture structures channeling Gulf sovereign wealth into long-dated Egyptian real estate yields. Long-term viability hinges on exposure to rental income securitization frameworks under Egyptian Financial Supervisory Authority regulation rather than direct development risk. Acquisition targets should display established land bank positions in West Cairo or New Cairo corridors. The signal to watch is Central Bank of Egypt mortgage finance ceiling adjustments expanding middle-class purchasing power.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Technology Deployment | Virtual modeling resolves structural conflicts before concrete pours, reducing rework on SODIC and Hassan Allam Properties mega-projects. |
| Backward Integration into Steel Procurement | Direct billet import arrangements bypass Alexandria and Suez state-linked mill concentration, insulating construction cost structures. |
| Smart Building Automation Convergence | Energy management system integration with resident-facing mobile applications differentiates premium offerings for New Cairo technology professionals. |
| Real Estate Investment Trust Securitization | Egyptian Financial Supervisory Authority frameworks enable institutional capital exposure to apartment rental yields without development risk. |
| Hospitality-Residential Hybrid Development | Integrated resort management contracts on Red Sea coast attract yield-focused investors following Orascom Development's El Gouna precedent. |
Research Methodology
Independent corroboration across Central Bank of Egypt mortgage finance regulations, New Urban Communities Authority permitting databases, and Egyptian Financial Supervisory Authority real estate investment trust filings underwrites the qualitative findings. Primary interviews with real estate development executives, construction site engineers, mortgage finance officers, and property marketing directors combined with secondary validation from customs trade data, steel import statistics, and desert new city master plan disclosures. Bottom-up unit absorption modeling and top-down macroeconomic scenario triangulation anchored volume and value estimates.
Comparable-period anchoring referenced historical construction completion cycles and pre-sale commitment timelines across the analysis window. Segmentation dimensions modeled include property type tier, developer capital source, end-user purchasing power profile, and sales channel migration pattern. CAGRs derived from compounding annual absorption rates adjusted for Egyptian pound liquidity conditions and foreign currency access regime volatility. Forecast inputs incorporated hollow-core slab construction cost trajectories and Mortgage Finance Fund subsidized interest program participation rates.
Revisions become necessary when Central Bank of Egypt loan-to-value caps tighten further, New Urban Communities Authority permitting windows contract, or hard-currency access regimes restrict imported finishing material procurement beyond current thresholds. Deviation in Gulf sovereign wealth deployment appetite would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condominium and Apartments
Canada Condominiums and Apartments Market
Condominium and Apartments
UAE Condominiums and Apartments Market
Condominium and Apartments
Italy Condominiums and Apartments Market
Condominium and Apartments
Condom Market
Condominium and Apartments
Latin America Condominiums and Apartments Market
Condominium and Apartments
Spain Condominiums and Apartments Market
Condominium and Apartments
Germany Condominiums and Apartments Market
Condominium and Apartments
Asia-Pacific Condominiums and Apartments Market
Condominium and Apartments
Saudi Arabia Condominiums and Apartments Market
Condominium and Apartments
Qatar Condominium and Apartment Market
Condominium and Apartments
ASEAN Condominiums and Apartments Market
Condominium and Apartments
Europe Condominiums and Apartments Market
Condominium and Apartments
Global Condominiums and Apartments Market
Condominium and Apartments
India Condominium and Apartments Market
Condominium and Apartments
Japan Condominiums and Apartments Market